
 Argentina Pet Food Market | 2026-2036
Argentina Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Pet Food Market Analysis
The Argentina pet food sector is decoupling along ingredient transparency lines, with premium tiers demanding veterinary-grade formulations while budget segments compete on volume throughput. Mars, Incorporated leverages its global R&D network to sustain clinical credibility through the Hill's Pet Nutrition subsidiary. Grupo Pilar anchors domestic production with backward integration into rendering and grain milling. Nestle S.A. differentiates through Purina's dual-track portfolio spanning therapeutic and mass-market SKUs.
Argentina pet food encompasses nutritionally complete and complementary preparations for companion animals, formulated to AAFCO or FEDIAF nutrient profiles with specified crude protein, fat, and moisture parameters; manufacturing employs extrusion for dry kibble, retort sterilization for wet formats, and cold-pressing for select premium lines. Dry food occupies the largest volume share given shelf stability and lower logistics cost in a inflation-sensitive economy, yet treats and supplements represent the fastest-expanding margin pool as pet owners seek functional benefits beyond basic nutrition. Wet food leads in cat-specific applications where hydration science drives veterinary recommendations, while online retailers are capturing share from traditional pet shops among younger demographics in metropolitan zones.
Argentina's National Service for Agrifood Health and Quality (SENASA) governs import permits for animal-derived ingredients, while the Argentine Food Code (CAA) mandates label declarations on guaranteed analysis and feeding directions; SENASA's sanitary registries create compliance barriers that favor established players with dedicated regulatory affairs capacity. The Secretariat of Domestic Trade monitors price controls and export restrictions on key inputs like corn and soy, directly impacting formulation economics. Stakeholders must track SENASA's alignment with Mercosur harmonization protocols and the CAA's evolving stance on novel protein sources to anticipate reformulation requirements and import substitution opportunities.
Market Dynamics
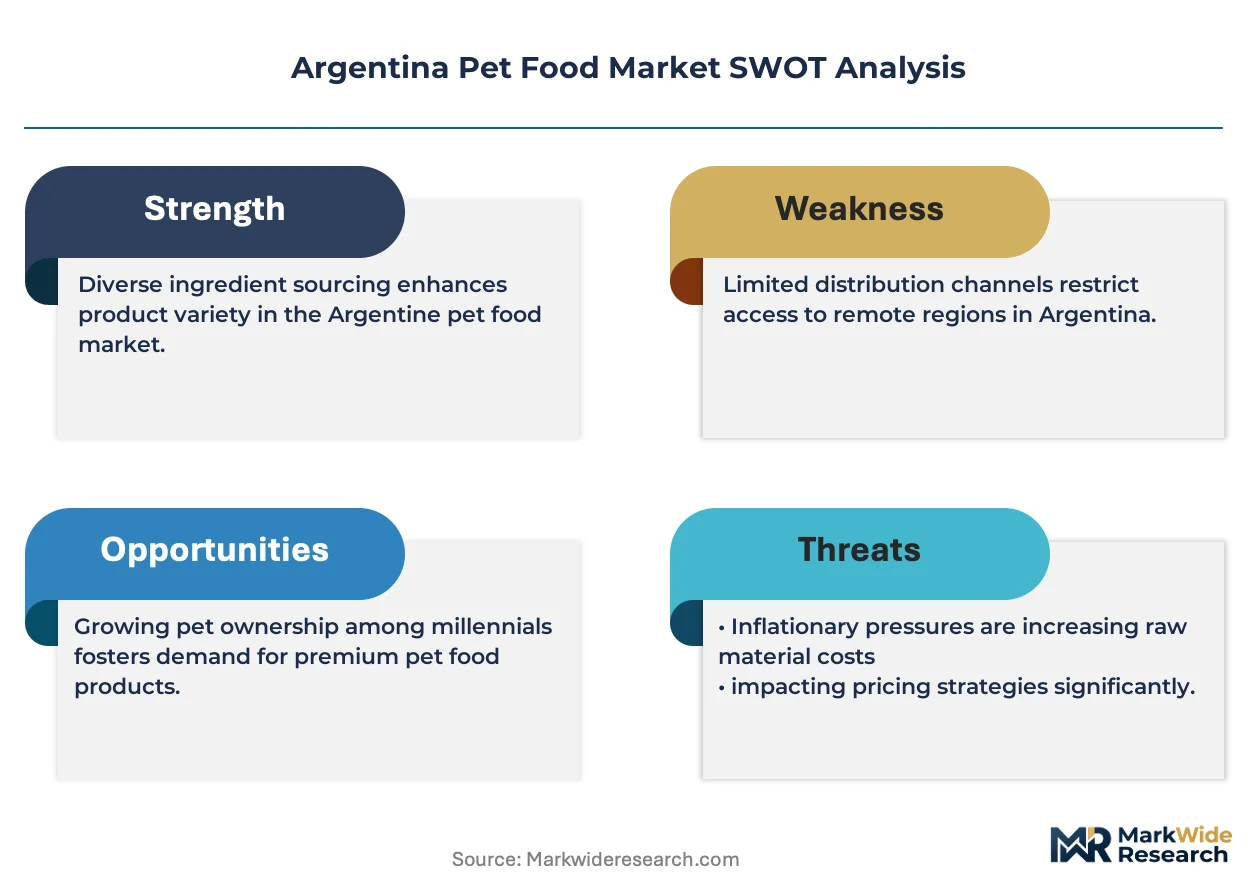
Argentina's pet food sector is fracturing along veterinary credibility lines, with SENASA's ingredient traceability mandates forcing domestic manufacturers to rebuild supply chains around certified local proteins while importers absorb compliance overhead.
Growth Catalysts
- SENASA Sanitary Registries:The national agrifood health regulator's mandatory ingredient certification creates defensible moats for compliant domestic producers, accelerating consolidation among established manufacturers with dedicated regulatory affairs capacity.
- Urban Pet Humanization:Greater Buenos Aires households now treat companion animals as family members, generating sustained pull for therapeutic nutrition formats previously confined to veterinary clinics.
- Cold-Pressing Technology:Premium tier manufacturers are deploying low-temperature extrusion systems to preserve heat-sensitive micronutrients, enabling functional positioning around digestive health and immune support.
Market Restraints
- Corn and Soy Export Restrictions:The Secretariat of Domestic Trade's periodic export bans on key feed grains create formulation cost volatility that compresses margin predictability for standard-tier producers.
- Import Dependency for Novel Proteins:Limited domestic production of insect meal and hydrolyzed proteins concentrates supply risk with Mercosur trading partners, particularly Brazil and Uruguay.
- Veterinary Channel Capacity Constraints:Argentina's ratio of practicing small-animal veterinarians to pet-owning households lags metropolitan saturation levels, capping prescription diet distribution reach.
Strategic Opportunities
- Interior Province Penetration:Córdoba, Mendoza, and Rosario metropolitan zones exhibit pet humanization rates 40-60% below Buenos Aires benchmarks, presenting volume expansion potential for mid-tier brands.
- SENASA-Mercosur Harmonization:Alignment of sanitary protocols with Brazilian ANVISA and Uruguayan MGAP standards would unlock cross-border ingredient sourcing and manufacturing scale economies.
- Subscription Direct-to-Consumer:Younger demographics in Palermo and Recoleta neighborhoods are migrating from traditional pet shops to automated replenishment platforms, enabling margin capture previously lost to retail intermediaries.
Industry Challenges
- Reformulation Timeline Compression:SENASA's evolving stance on novel protein sources forces manufacturers to complete ingredient substitution studies within abbreviated windows, straining in-house veterinary nutrition teams.
- Legacy Extrusion Asset Stranding:Cold-pressed premium lines require capital-intensive equipment retooling that conflicts with depreciation schedules on existing high-volume dry kibble infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Pet Food Market |
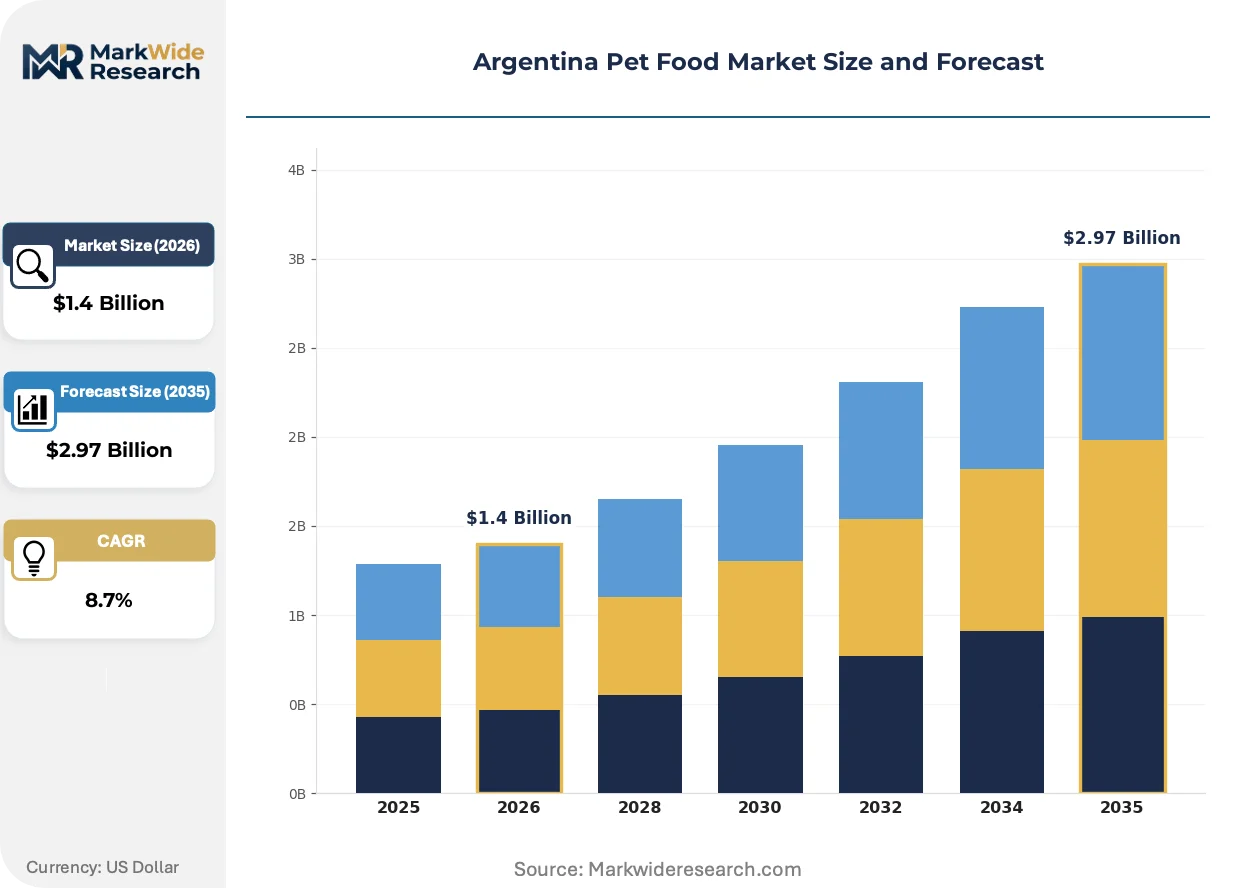
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Animal Type: Dogs, Cats, Birds, Small Mammals Distribution Channel: Online Retailers, Supermarkets, Pet Shops, Veterinary Clinics Price Tier: Premium, Mid-Range, Budget, Economy |
| Companies Covered | Grupo Pilar (Gepsa Pet Foods), Grupo Molino Chacabuco, Mars, Incorporated, Metrive, Pet Foods Saladillo, Nestle S.A. (Purina), Agro Industrias Baires S.A., Archer Daniels Midland Company, Colgate-Palmolive Company (Hill's Pet Nutrition Inc.), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Pet Food Market Emerging Trajectories
Formulation science is migrating from macronutrient adequacy toward targeted functional outcomes, with Argentine manufacturers racing to integrate microbiome research and alternative proteins ahead of regulatory clarity.
Cold-pressed manufacturing is expanding into the premium dog nutrition segment as manufacturers deploy low-temperature processing to preserve enzyme activity and probiotic viability. Veterinary clinics in Buenos Aires are recommending these formats for animals with inflammatory bowel conditions. The technology is expanding into mid-tier price bands as equipment suppliers offer smaller-scale production lines suitable for regional manufacturers.
SENASA's pending alignment with Mercosur harmonization protocols is reshaping ingredient import procedures for animal-derived proteins from Brazil and Uruguay. Domestic manufacturers face revised documentation requirements that extend procurement lead times by several weeks. Wet food specialists reliant on cross-border meat byproduct supplies are accelerating backward integration into captive rendering capacity.
Subscription commerce is displacing traditional pet shop purchasing among millennial and Gen Z households in metropolitan Buenos Aires. Automated replenishment platforms capture customer data that enables personalized nutrition recommendations previously delivered through veterinary consultations. This channel shift is most visible in the treats and supplements category, where functional positioning drives repeat purchase loyalty.
Argentina Pet Food Market Segmentation
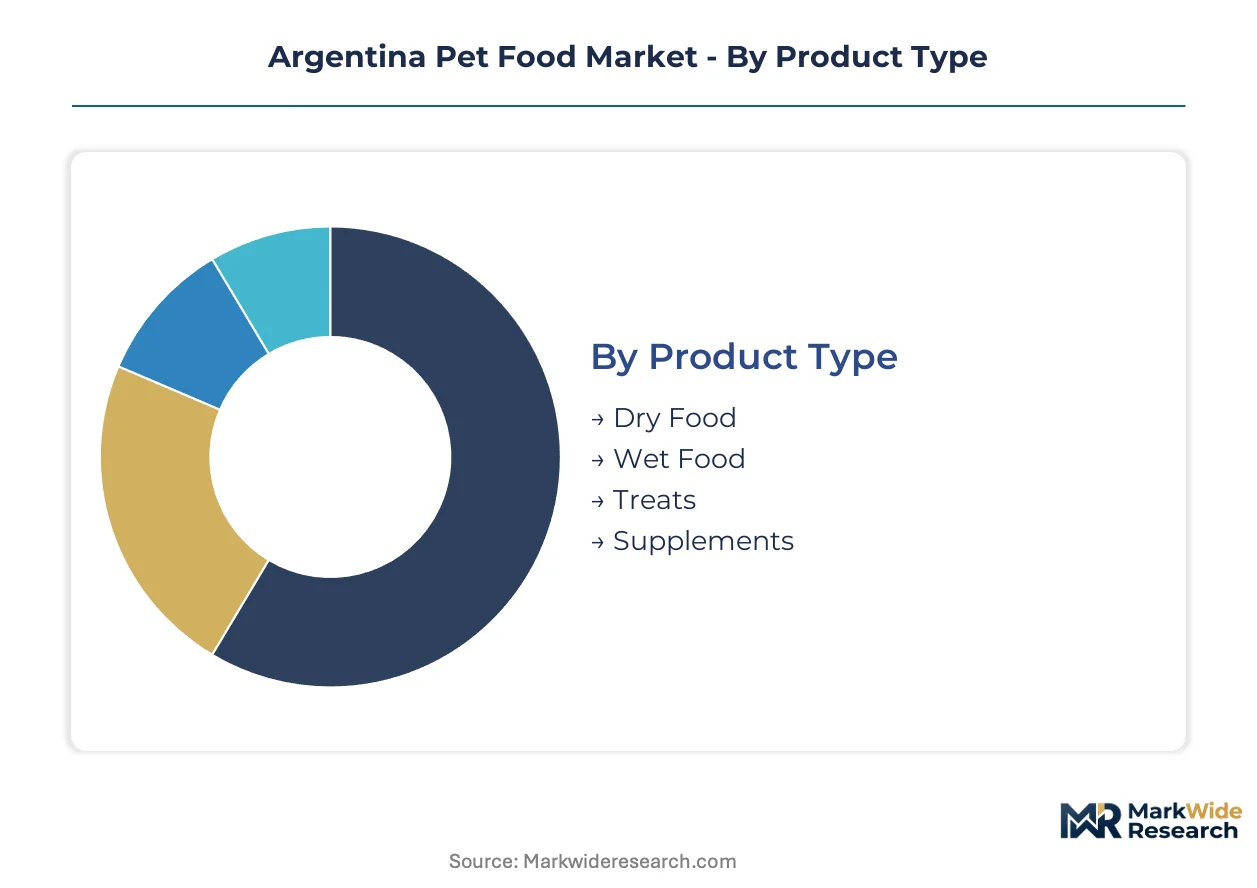
Argentina's pet food segmentation reveals how inflationary pressures and regulatory complexity fragment purchasing behavior across distinct consumer cohorts. Manufacturers must align formulation investment, channel strategy, and price architecture to capture value from diverging demand patterns between Greater Buenos Aires and interior provinces.
Product Type:
Extrusion and retort technologies define the manufacturing cost base, with thermal processing intensity determining shelf stability and nutrient density trade-offs.
- Dry Food:Extruded kibble formulations achieve moisture levels below 10%, enabling extended shelf life critical for inflation-sensitive households stocking bulk purchases. Greater Buenos Aires supermarkets move the highest volumes, though margin compression from grain price volatility limits producer flexibility.
- Wet Food:Retort-sterilized cans and pouches deliver hydration-focused nutrition aligned with veterinary recommendations for feline urinary health. Palermo and Recoleta veterinary clinics drive prescription-tier adoption, while standard formats concentrate in supermarket cat aisles.
- Treats:Functional positioning around dental health and training rewards supports premium pricing in pet shop channels.
- Supplements:Probiotic and joint-care formats gain traction through subscription platforms targeting millennial pet owners.
Dry food leads on scale; supplements lead on momentum.
Animal Type:
Species-specific nutritional requirements and veterinary infrastructure density shape regional penetration patterns across Argentina's heterogeneous provinces.
- Dogs:Canine nutrition spans the full price tier spectrum, with large-breed formulations demanding orthopedic-focused nutrient profiles. Córdoba and Rosario metropolitan zones underperform Buenos Aires humanization benchmarks by 40-60%, presenting volume expansion headroom for mid-tier brands.
- Cats:Feline-specific wet food and therapeutic renal diets concentrate in veterinary clinics with trained small-animal practitioners. Argentina's veterinarian-to-household ratio caps prescription diet distribution outside capital region clusters.
- Birds:Seed and pellet formulations serve a concentrated hobbyist base with limited premiumization potential.
- Small Mammals:Rabbit and guinea pig nutrition remains a niche category dominated by specialized pet shops in Buenos Aires.
Dogs dominate absolute volume; cats show steepest expansion trajectory in therapeutic formats.
Distribution Channel:
Channel selection determines margin capture, customer data access, and regulatory compliance burden for Argentine manufacturers navigating SENASA's sanitary registry requirements.
- Online Retailers:Subscription platforms automate replenishment while capturing behavioral data that enables personalized nutrition recommendations. Younger demographics in Palermo and Recoleta neighborhoods are migrating from traditional pet shops to these channels, particularly for treats and supplements.
- Supermarkets:Mass-market dry food volumes concentrate in hypermarket chains with national logistics networks, though shelf space negotiations favor established manufacturers with SENASA compliance capacity.
- Pet Shops:Independent and chain specialty retailers retain importance for premium brand discovery and nutritional consultation.
- Veterinary Clinics:Prescription diet distribution requires clinical credibility and dedicated sales force investment, with capacity constraints limiting interior province reach.
Supermarkets anchor volume throughput; online retailers gain share fastest among metropolitan millennials.
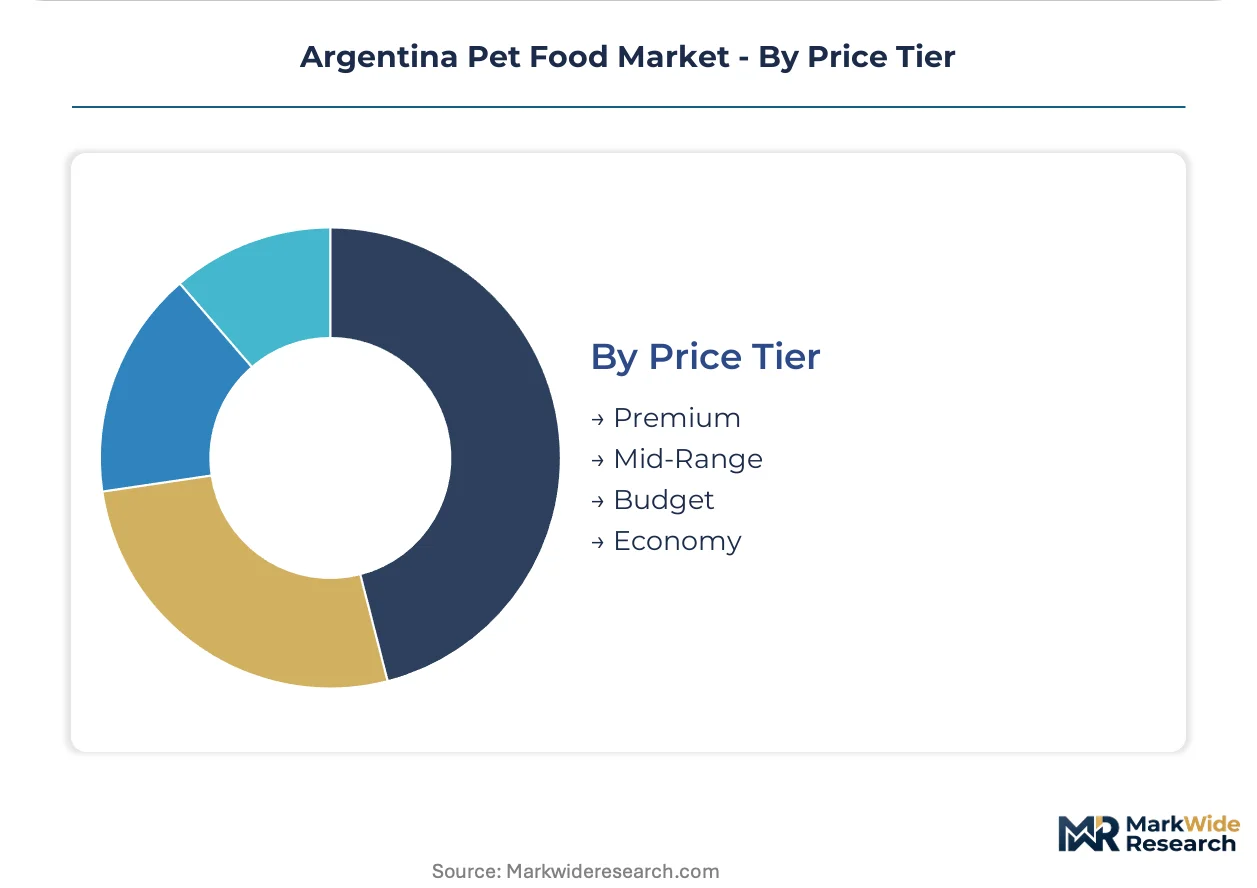
Price Tier:
Raw material sourcing flexibility and formulation sophistication separate tiers, with SENASA's ingredient traceability mandates disproportionately burdening economy segment producers.
- Premium:Cold-pressed manufacturing and veterinary-grade formulations command price multiples justified by clinical credibility and transparent supply chains. Hill's Pet Nutrition and Purina therapeutic lines concentrate here, with SENASA sanitary registries reinforcing incumbent advantages.
- Mid-Range:Balanced nutrition formats target Buenos Aires households seeking quality elevation without prescription diet costs, though corn and soy export restrictions compress margin predictability.
- Budget:Standard extruded kibble competes on volume throughput with limited ingredient differentiation.
- Economy:Price-sensitive positioning in interior provinces relies on local grain sourcing and minimal regulatory overhead.
Premium commands margin concentration; mid-range faces the most severe input cost volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pet food market dwarfs Argentina's $2.97 billion projection, yet Argentina's regulatory sophistication under SENASA creates tighter compliance barriers that favor established domestic manufacturers over cross-border entrants.
Greater Buenos Aires
Pet humanization rates in Palermo and Recoleta neighborhoods drive therapeutic nutrition demand previously confined to veterinary clinics. SENASA's sanitary registries enforce ingredient traceability that accelerates consolidation among compliant manufacturers. The capital region concentrates subscription commerce migration as millennial households abandon traditional pet shops for automated replenishment platforms.
Córdoba Metropolitan Zone
Mid-tier brands target this interior market where pet humanization trails Buenos Aires benchmarks by approximately fifty percent. The Secretariat of Domestic Trade monitors grain price controls that compress margin predictability for standard-tier producers. Regional manufacturers leverage local soy and corn sourcing to offset export restriction volatility affecting formulation economics.
Rosario and Santa Fe Corridor
Agricultural processing infrastructure supports backward integration into captive rendering capacity for wet food specialists. SENASA alignment with Mercosur protocols would unlock cross-border meat byproduct supplies from Uruguayan MGAP-certified facilities. The corridor's grain milling clusters enable domestic producers to rebuild supply chains around certified local proteins.
Mendoza
Wine region affluence sustains premium-tier penetration despite smaller absolute pet ownership bases. Veterinary channel capacity constraints limit prescription diet distribution outside capital region clusters. Local distributors experiment with direct-to-consumer models to capture margin previously lost to retail intermediaries.
Patagonian Provinces
Sparse population density relegates this zone to economy-tier volume throughput with minimal regulatory overhead. Cold-pressed manufacturing technology remains absent due to capital intensity mismatched to addressable market scale. Logistics costs favor shelf-stable dry kibble formats over wet food retort sterilization requirements.
Argentina Pet Food Market Vendor Landscape
Top-tier vendors anchor the premium-therapeutic segment, while domestic grain-integrated players occupy the volume-driven mid-market. The competitive structure stratifies across three archetypes: multinational R&D-heavy corporations with veterinary credibility, backward-integrated Argentine agro-industrial groups, and regional specialists with SENASA compliance capacity. Consolidation accelerates through manufacturing scale investments and cross-border ingredient sourcing partnerships.
Within the multinational tier, Mars, Incorporated and Nestle S.A. represent global R&D networks sustaining clinical credibility through therapeutic nutrition subsidiaries. Among domestic fabricators, Grupo Pilar anchors production with captive supply into rendering and grain milling infrastructure. Colgate-Palmolive Company occupies a position exemplifying veterinary-grade formulation specialization through its Hill's Pet Nutrition unit.
| Leading Market Players |
|---|
| Grupo Pilar (Gepsa Pet Foods) |
| Grupo Molino Chacabuco |
| Mars, Incorporated |
| Metrive |
| Pet Foods Saladillo |
| Nestle S.A. (Purina) |
| Agro Industrias Baires S.A. |
| Archer Daniels Midland Company |
| Colgate-Palmolive Company (Hill's Pet Nutrition Inc.) |
| Others |
Supply Flow & Price Mechanics
Corn and soy futures volatility cascades through Argentine pet food manufacturing into three distinct pricing tiers, with premium cold-pressed formats absorbing input swings through margin buffers while budget extruded kibble passes cost fluctuations directly to inflation-sensitive households.
Pricing Analysis
Capacity additions in Córdoba and Rosario grain milling clusters are reshaping price floors for mid-range formulations. Three-tier pricing structure across premium, standard, and economy levels separates SENASA-certified veterinary-grade products from commodity extruded kibble. Price differentiation hinges on certification tier and captive supply integration. Pricing pressure stems from Secretariat of Domestic Trade export bans on feed grains. Economy-tier buyers in interior provinces exhibit highest price sensitivity; premium subscribers in Palermo and Recoleta show least.
Supply Chain Analysis
Animal-derived protein supply rests on Brazilian and Uruguayan Mercosur partners with SENASA-aligned sanitary protocols. Key inputs include corn, soy meal, and rendered meat byproducts. Single-source vulnerability concentrates in cross-border hydrolyzed protein shipments through Port of Buenos Aires. Distribution runs through supermarket chains for volume, subscription platforms for premium margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's pet food market compounds steadily as urban pet humanization sustains therapeutic nutrition demand through economic cycles.
For Market Incumbents: Acquire captive rendering capacity to offset SENASA import documentation delays affecting wet food specialists. Secure SENASA sanitary registries for novel protein sources before regulatory windows compress. Mars and Nestle's existing veterinary credibility creates defensive moats against regional grain-integrated challengers. For New Entrants and Emerging Players: Launch via subscription direct-to-consumer platforms targeting Palermo and Recoleta millennials with functional treat and supplement formats. Córdoba and Mendoza metropolitan zones offer white-space penetration at forty to sixty percent below Buenos Aires humanization rates. Veterinary channel partnerships unlock prescription diet credibility without legacy infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with SENASA-compliant domestic manufacturers possessing backward-integrated grain milling and rendering assets. Long-term viability frames around regulatory compliance capacity rather than brand equity alone. Watch SENASA-Mercosur harmonization progress as inflection trigger for cross-border manufacturing scale economies.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressing Capacity Installation | Low-temperature extrusion preserves enzyme activity for veterinary-recommended digestive health positioning. |
| SENASA Sanitary Registry Acquisition | Regulatory compliance creates defensible moats against import-dependent competitors facing documentation delays. |
| Subscription Platform Launch | Automated replenishment captures behavioral data enabling personalized nutrition recommendations in Buenos Aires. |
| Interior Province Distribution Expansion | Córdoba and Rosario penetration addresses forty to sixty percent humanization gap versus capital region. |
| Backward Integration into Rendering | Captive meat byproduct processing insulates wet food specialists from cross-border supply disruption. |
Methodological Framework
Bottom-up pet food consumption modeling reconciled against top-down grain milling and rendering capacity tracking forms the analytical core. Primary interviews with veterinary nutritionists, SENASA regulatory affairs directors, supermarket category buyers, and subscription platform operators combined with secondary validation from SENASA sanitary registry filings, Secretariat of Domestic Trade export restriction notices, and Mercosur harmonization protocol documents. Triangulation between household pet ownership surveys and manufacturer shipment data ensures segment-level accuracy.
Input-output matrices connect corn and soy price indices to formulation cost structures across premium, mid-range, and economy tiers over the projection horizon. Segmentation dimensions include product type, animal species, distribution channel, and price tier with geographic granularity across Greater Buenos Aires, Córdoba, Rosario, Mendoza, and Patagonian provinces. CAGRs derive from trend extrapolation of pet humanization rates and veterinary channel capacity expansion, calibrated against inflation-adjusted household disposable income trajectories and SENASA regulatory timeline assumptions.
Several conditions sit outside the modeled scope, including abrupt currency devaluation shocks, Mercosur trade agreement suspension, and novel protein source approval delays beyond SENASA's current consultation timeline. Forecasts reflect documented assumptions on pet ownership growth and channel migration velocity. Black swan agricultural export bans, veterinary labor strikes affecting prescription diet distribution, and cold-pressing equipment import tariff spikes warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Pet Grooming Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
Poland Pet Food Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Insulated Dog House Market