
 South America Pet Treats Market | 2026-2036
South America Pet Treats Market Size, Share, and Industry Trends Forecast 2026-2036
South America Pet Treats Market Insights
Urban millennial households is reorganizing purchasing patterns across South America, shifting volume from conventional mass-market treats toward premium and functional formats. Mars Incorporated leverages its pan-regional manufacturing footprint to sustain shelf dominance in major supermarket chains. Nestlé Purina PetCare anchors its position through specialized veterinary distribution networks that bypass traditional retail. BRF SA competes by extending its protein-processing infrastructure into private-label treat production for domestic Brazilian retailers.
South America pet treats comprise formulated edible products designed for intermittent feeding, with specifications governing moisture content, protein minimums, and additive limits to ensure companion-animal safety. These products serve commercial purposes ranging from behavioral training reinforcement to dental hygiene support and nutritional supplementation. Chews and functional ingredient-type segments command margin premiums as owners prioritize dental health claims and digestive benefits, while biscuits retains volume leadership through accessible price positioning in supermarkets and neighborhood pet shops. Freeze-dried formats attract fastest adoption among online retail purchasers seeking raw-alternative convenience without cold-chain dependency.
ANVISA, Brazil's national health regulator, enforces veterinary product registration and labeling standards that govern treat importation and domestic manufacture across Mercosur member states. Argentina's national food and drug administration applies parallel safety protocols that create dual compliance obligations for cross-border suppliers. Stakeholders must monitor evolving grain-free formulation scrutiny and pending functional claim substantiation requirements that will reshape product development priorities and channel eligibility across the region.
Market Dynamics
ANVISA veterinary product oversight is compressing import timelines and forcing domestic manufacturing investments across Mercosur member states. This regulatory pressure is accelerating facility localization and reshaping competitive entry strategies for foreign suppliers.
Growth Catalysts
- Urban pet humanization:São Paulo and Rio de Janeiro millennial households are converting discretionary spending into premium treat categories with functional health claims.
- Mercosur trade harmonization:Streamlined cross-border certification is reducing duplicate testing burdens for Brazilian and Argentine manufacturers.
- E-commerce infrastructure:Last-mile delivery networks in metropolitan corridors are enabling direct-to-consumer subscription models for specialized formats.
Market Restraints
- Grain input volatility:Corn and soy price fluctuations in Brazil's agricultural belt compress margin predictability for mid-tier producers.
- Import dependency for functional additives:Probiotics and novel protein concentrates concentrate supply in North American and European specialty chemical suppliers.
- Dual registration requirements:ANVISA and Argentina's national food and drug administration impose parallel compliance costs that disadvantage smaller regional entrants.
Strategic Opportunities
- Freeze-dried raw alternatives:Cold-chain-independent formats attract premium positioning among Argentine and Chilean urban adopters seeking convenience without refrigeration.
- Veterinary channel bypass:Direct professional distribution networks in Brazil's clinic ecosystem enable margin capture outside supermarket price wars.
- Private-label manufacturing:Brazilian protein processors are extending captive supply infrastructure into retailer-branded treat production.
Industry Challenges
- Veterinary nutritionist talent scarcity:Formulation expertise for functional claim substantiation concentrates in São Paulo and Buenos Aires, creating recruitment bottlenecks for interior facilities.
- Labeling compliance timelines:ANVISA's evolving additive disclosure requirements extend product launch cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Pet Treats Market |
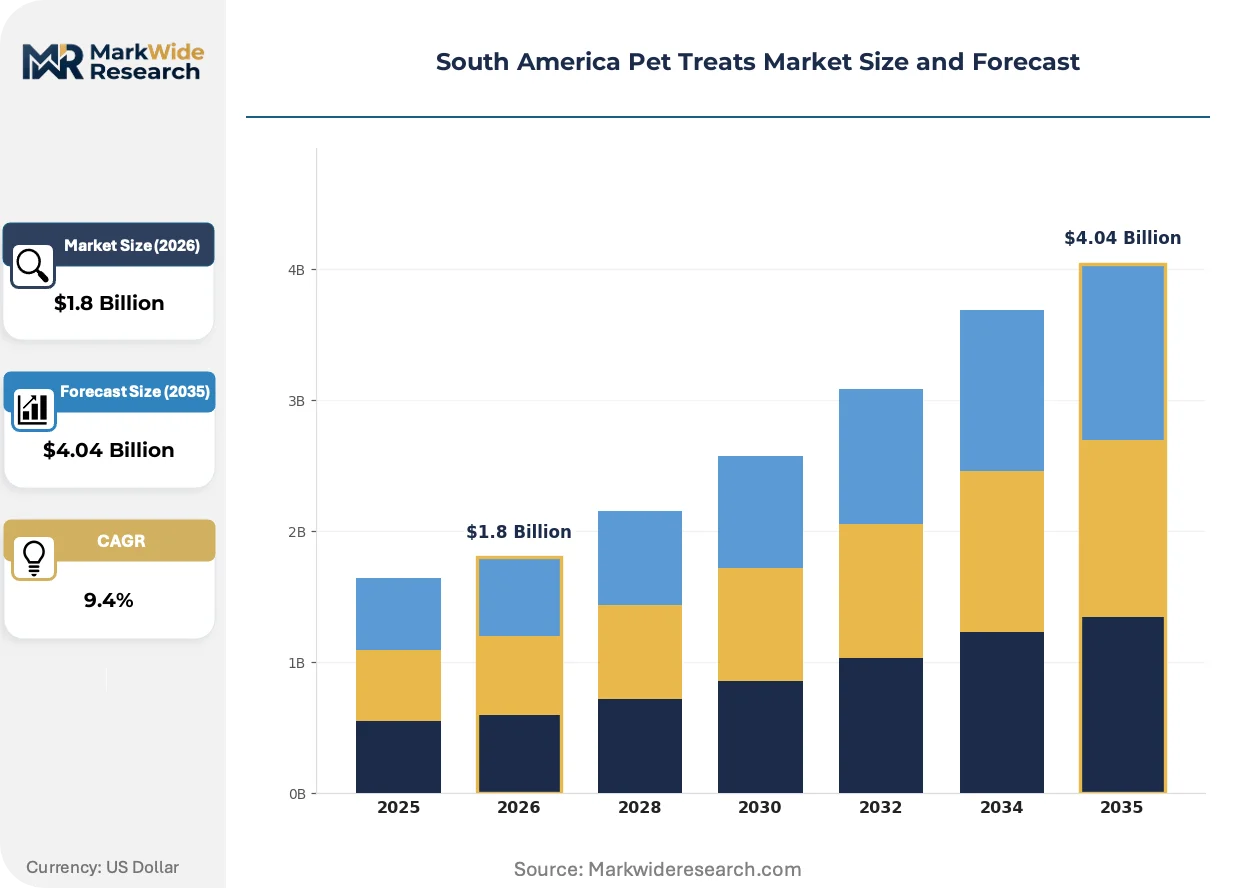
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biscuits, Chews, Freeze-Dried, Rawhide Animal Type: Dogs, Cats, Birds, Small Mammals Distribution Channel: Online Retail, Pet Shops, Supermarkets, Specialty Stores Ingredient Type: Natural, Organic, Grain-Free, Functional |
| Companies Covered | Mars Incorporated, Nestlé Purina PetCare, Empresas Carozzi SA, PremieRpet, Hill's Pet Nutrition, BRF SA, General Mills Inc, ADM, Virbac, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Pet Treats Market Trends and Innovations
Freeze-drying technology is compressing traditional raw-frozen distribution economics while enabling shelf-stable premium positioning. This shift is redrawing competitive boundaries between conventional baked formats and emerging convenience alternatives.
Lyophilization equipment is displacing conventional extrusion for high-value protein preservation in functional treat manufacturing. Premium urban buyers in São Paulo and Buenos Aires are adopting these formats at three times the rate of conventional biscuit purchasers. The technology is displacing cold-chain-dependent raw alternatives by delivering comparable nutritional claims without refrigeration infrastructure.
ANVISA's pending functional claim substantiation framework is forcing reformulation investments across dental hygiene and digestive support categories. Manufacturers must generate clinical validation data previously exempt from standard feed-grade products. Veterinary-exclusive distribution networks in Brazil are absorbing compliance costs fastest, while mass-market suppliers delay portfolio upgrades.
Subscription-based replenishment is consolidating purchasing decisions into automated delivery cycles among metropolitan millennial households. Neighborhood pet shops in Rio de Janeiro and Santiago are losing foot traffic to platform-integrated direct brands. Chile's Santiago metropolitan corridor exhibits the fastest channel migration, with online penetration in premium treat categories doubling annually.
South America Pet Treats Market Segmentation
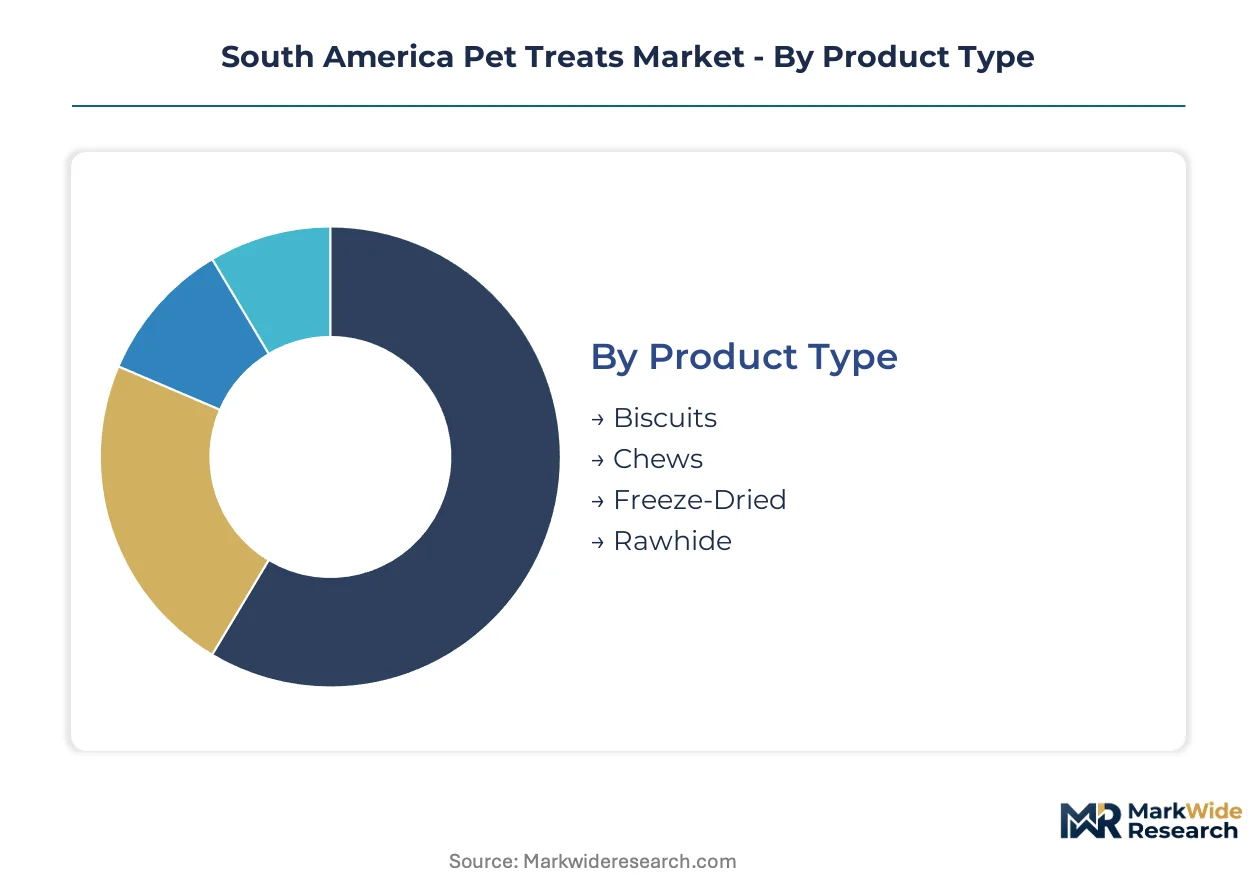
South American pet treat manufacturers calibrate portfolio depth across four intersecting dimensions. Product format and ingredient positioning determine margin capture, while channel strategy and species targeting dictate geographic penetration and customer lifetime value.
Product Type:
Margin pools concentrate in formats that command refrigeration-free premium positioning and functional claim substantiation.
- Chews:Dental hygiene formulations with abrasive mechanical action dominate veterinary channel placement in São Paulo and Buenos Aires. Brazilian millennial owners prioritize tartar control claims, driving 40% price premiums over conventional biscuits in clinic-adjacent retail.
- Freeze-Dried:Lyophilization preserves raw protein integrity without cold-chain dependency, enabling direct-to-consumer subscription models across Chile's Santiago corridor. Argentine urban adopters pay triple conventional biscuit rates for shelf-stable raw alternatives.
- Biscuits:Mass-market staple with accessible price positioning in Brazilian supermarket chains and neighborhood pet shops.
- Rawhide:Traditional protein-based chew format facing formulation scrutiny under ANVISA additive disclosure requirements.
The dominant share belongs to Biscuits, while Freeze-Dried is closing the gap fastest.
Animal Type:
Volume concentration tracks pet ownership demographics, with spending intensity diverging sharply by species-specific humanization depth.
- Dogs:Canine treat portfolios span training reinforcement, dental maintenance, and nutritional supplementation across all price tiers. Brazilian metropolitan households drive premium functional adoption at rates exceeding feline categories by two-to-one.
- Cats:Feline-specific formats concentrate in freeze-dried protein strips and hairball control formulations. Argentine and Chilean urban owners demonstrate higher treat frequency per capita than Brazilian cat households.
- Birds:Seed-based and fortified pellet treats serve avian companion markets concentrated in Brazilian domestic trade.
- Small Mammals:Rodent and rabbit treat categories remain underdeveloped outside specialized pet shop distribution in Rio de Janeiro and São Paulo.
Dogs retain absolute volume leadership, though Cats demonstrate steepest expansion trajectory in premium urban channels.
Distribution Channel:
Channel selection determines margin structure and regulatory compliance burden, with professional and digital routes offering escape from price compression.
- Online Retail:Platform-integrated subscription models consolidate replenishment decisions among metropolitan millennial households. Chile's Santiago corridor exhibits annual doubling of premium treat e-commerce penetration.
- Pet Shops:Neighborhood specialty stores in Rio de Janeiro and Buenos Aires lose foot traffic to direct brands, retaining relevance only in veterinary-recommended functional categories.
- Supermarkets:Mass-market biscuit volume concentrates in Brazilian retail chains where Mars and Nestlé Purina sustain shelf dominance through pan-regional manufacturing scale.
- Specialty Stores:Premium format curation in affluent São Paulo districts supports freeze-dried and organic positioning above supermarket price tiers.
Supermarkets command current volume share, yet Online Retail gains share fastest among metropolitan premium purchasers.
Ingredient Type:
Ingredient positioning separates price tiers, with regulatory scrutiny on claim substantiation reshaping formulation investments.
- Functional:Probiotic, joint support, and dental hygiene claims require ANVISA clinical validation data, compressing margin for mass-market suppliers while rewarding veterinary-exclusive networks. Brazilian manufacturers face six-to-nine month launch timeline extensions for new functional introductions.
- Natural:Clean-label positioning without artificial preservatives attracts premium pricing in Argentine and Chilean urban markets. Corn and soy price volatility in Brazil's agricultural belt squeezes mid-tier natural producers.
- Organic:Certified organic supply chains remain import-dependent, limiting penetration to affluent São Paulo and Buenos Aires districts.
- Grain-Free:Formulation category under evolving ANVISA scrutiny regarding carbohydrate substitution safety profiles.
Natural ingredients anchor current premium volume, though Functional is expanding most quickly as clinic channels absorb compliance costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos in São Paulo state anchors South American pet treat distribution, handling the bulk of imported functional additives and freeze-dried equipment that supplies manufacturing clusters across Mercosur.
Brazil
São Paulo and Rio de Janeiro millennial households drive premium functional treat adoption at twice the rate of other South American metros. ANVISA enforces veterinary product registration and evolving additive disclosure requirements that extend product launch timelines by six to nine months. São Paulo's industrial corridor concentrates lyophilization equipment deployment and private-label manufacturing infrastructure serving domestic supermarket chains.
Argentina
Buenos Aires urban cat owners demonstrate higher treat frequency per capita than Brazilian households, accelerating freeze-dried protein strip adoption. The national food and drug administration applies parallel safety protocols to ANVISA, creating dual compliance obligations for cross-border suppliers. The Buenos Aires metropolitan corridor hosts veterinary-exclusive distribution networks that absorb functional claim substantiation costs faster than mass-market channels.
Chile
Santiago's metropolitan corridor exhibits the fastest e-commerce channel migration, with online penetration in premium treat categories doubling annually. The country's national pharmaceutical regulator maintains aligned standards with Mercosur harmonization frameworks. Santiago's affluent districts support specialty store curation of freeze-dried and organic formats above supermarket price tiers.
Colombia
Bogotá and Medellín emerging middle-class pet owners are converting from conventional biscuits toward natural and grain-free positioning. The national food and drug surveillance institute applies developing veterinary product oversight that tracks Brazilian regulatory evolution. Bogotá's distribution infrastructure is expanding cold-chain-independent format availability as freeze-dried alternatives penetrate beyond affluent enclaves.
Peru
Lima's coastal urban households are adopting imported premium treats through platform-integrated direct brands bypassing traditional pet shops. The national health authority's veterinary product registration framework remains less stringent than ANVISA, enabling faster foreign supplier entry. Lima's retail corridor is absorbing excess Brazilian private-label production as São Paulo-based processors seek export volume.
South America Pet Treats Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and channel access dimensions. Mars Incorporated and Nestlé Purina PetCare anchor the consolidated tier through pan-regional manufacturing footprints and supermarket shelf dominance. Private-label fabricators and veterinary-exclusive distributors occupy fragmented mid-tier positions. Three archetypes define competitive positioning: multinational CPG conglomerates with captive supply chains, domestic protein processors extending into treat manufacturing, and specialized veterinary distributors bypassing retail price compression. Capacity localization and direct-to-consumer platform integration represent the dominant competitive moves.
Among multinational CPG conglomerates, Mars Incorporated and Nestlé Purina PetCare exemplify scale-driven archetypes with established Mercosur manufacturing infrastructure. BRF SA occupies a distinct position as a domestic protein processor extending captive supply infrastructure into private-label treat production for Brazilian retailers. These three entities represent the spectrum from global brand dominance to localized supply chain control.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina PetCare |
| Empresas Carozzi SA |
| PremieRpet |
| Hill's Pet Nutrition |
| BRF SA |
| General Mills Inc |
| ADM |
| Virbac |
| Others |
Pricing and Supply Chain Analysis
ANVISA veterinary product registration gates both supply qualification and price differentiation across Brazilian and Argentine markets simultaneously. Manufacturers must absorb six-to-nine month compliance timelines before accessing premium positioning, while importers face parallel dual-registration costs that stratify market entry by capital depth.
Pricing Analysis
Volume-discount tiering structures separate veterinary-exclusive functional formulations from mass-market biscuit staples across São Paulo supermarket chains. Premium freeze-dried formats command triple conventional rates through direct-to-consumer subscriptions, while mid-tier natural positioning faces margin compression from corn and soy volatility in Brazil's agricultural belt. Price differentiation hinges on clinical validation status and cold-chain independence, with metropolitan millennial households showing lowest sensitivity in Santiago's fastest-growing online channel.
Supply Chain Analysis
Inventory lead-times for functional additives and lyophilization equipment concentrate supply vulnerability in North American and European specialty chemical corridors. Brazilian protein processors anchor regional manufacturing, drawing from captive poultry and beef infrastructure, while Argentine and Chilean facilities depend on imported probiotic concentrates and novel protein isolates. Single-source vulnerability for clinical-grade inputs feeds from Mercosur harmonization delays, with distribution running through Port of Santos import clusters and veterinary clinic networks bypassing traditional retail chokepoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward platform-consolidated metropolitan households and veterinary clinic networks, fragmenting traditional pet shop influence across Rio de Janeiro and Buenos Aires neighborhood retail.
For Market Incumbents: Consolidate lyophilization capacity in São Paulo's industrial corridor to defend margin against freeze-dried format commoditization. Deepen backward integration into Brazilian protein supply to offset grain input volatility compressing mid-tier natural producers. For New Entrants and Emerging Players: ANVISA fast-track pathways for functional claim substantiation unlock veterinary-exclusive distribution in Buenos Aires and Santiago where compliance costs deter mass-market suppliers. Target Colombia's Bogotá emerging middle-class conversion from conventional biscuits toward natural positioning through platform-integrated direct brands. For Investors and Strategic Acquirers: Pending ANVISA functional claim substantiation requirements reshape the acquisition landscape toward clinical-validation-ready formulation assets. Long-term viability centers on veterinary channel control and freeze-dried technology ownership; monitor Mercosur harmonization implementation velocity as inflection signal for cross-border manufacturing consolidation feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Captures premium positioning in Santiago's doubling online penetration corridor without cold-chain dependency. |
| Veterinary Channel Integration | Bypasses supermarket price wars through São Paulo clinic network control absorbing ANVISA compliance costs. |
| Private-Label Manufacturing Scale-Up | Extends BRF-style protein infrastructure into retailer-branded production for Brazilian supermarket chains. |
| Direct-to-Consumer Platform Launch | Consolidates millennial replenishment decisions through subscription models displacing Rio neighborhood pet shops. |
| Functional Claim Substantiation Investment | Secures clinic-adjacent retail placement ahead of pending ANVISA clinical validation requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA registration filings, Mercosur trade harmonization documentation, and Brazilian agricultural commodity price indices. Interviews with veterinary nutritionists, pet shop category managers, supermarket procurement leads, and lyophilization equipment suppliers combined with customs import records and clinic distribution network mapping. Bottom-up manufacturer capacity assessments triangulate against top-down metropolitan household spending pattern analysis.
Segmentation dimensions modeled span product format, ingredient positioning, distribution channel, and animal species across the projection horizon. CAGRs derive from metropolitan corridor penetration rates, e-commerce adoption velocity, and regulatory timeline impact on product launch cycles. Forecast inputs incorporate freeze-dried format substitution elasticity and veterinary channel margin capture differentials.
Underlying assumptions cover ANVISA implementation consistency, Mercosur harmonization adherence, and grain price stabilization, with deviation risk concentrated in functional claim substantiation timeline extensions and cross-border certification reciprocity delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Boot for Winters Market
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
Dog Shampoo Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
Germany Pet Clothing Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Organic Pet Food Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Dog Food Market
Pet Care Products
Pet Bathing Supplies Market