
 Medicated Shampoo Market | 2026-2036
Medicated Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Medicated Shampoo Market Outlook
The capital-intensity divergence between mass-market manufacturers and clinical-grade formulators is unwinding competitive stability in medicated hair care. Procter & Gamble leverages its global distribution infrastructure to maintain shelf presence across pharmacy and mass retail channels. Himalaya Wellness Company specializes in botanical-active hybrids that occupy a distinct price-position between pharmaceutical and natural positioning. Johnson & Johnson sustains dermatologist endorsement through controlled-release zinc pyrithione technologies developed for sensitive scalp protocols.
Medicated shampoo denotes a therapeutic cleansing formulation containing pharmacologically active concentrations of antifungal, keratolytic, or cytostatic agents—typically ketoconazole at one to two percent or coal tar extracts at 0.5 to five percent—manufactured under drug or cosmetic-drug hybrid regulatory frameworks for the treatment of seborrheic dermatitis, psoriasis, or tinea capitis. Gel formulations dominate hospital and clinic dispensing due to precise dosing control and extended scalp contact time, while foam delivery systems represent the fastest-expanding segment in home-use channels driven by ease of application and reduced residue concerns. Anti-dandruff remains the largest product category by volume, though anti-fungal applications command premium pricing through prescription-tier reimbursement pathways.
FDA monograph compliance requirements for over-the-counter anti-dandruff actives and EPA registration standards for coal tar derivatives impose substantial formulation and labeling constraints on market participants. The EU's REACH framework and MDR cosmetic-drug boundary classifications create additional complexity for cross-border product registration and ingredient disclosure protocols. Stakeholders must monitor evolving regulatory thresholds for selenium sulfide and salicylic acid concentrations while evaluating captive manufacturing investments that reduce third-party formulation dependency.
Market Dynamics
FDA monograph revisions for coal tar concentration limits are forcing North American manufacturers to reformulate active ingredient sourcing strategies while dermatology clinics accelerate pharmaceutical-grade cleansing protocols into scalp treatment regimens.
Growth Catalysts
- Telehealth Integration:Direct-to-consumer subscription models partnered with telehealth platforms in the United States are expanding prescription-strength shampoo accessibility beyond traditional pharmacy channels.
- REACH Compliance:The EU's evolving cosmetic-drug boundary classifications under ECHA frameworks are creating competitive separation for manufacturers with captive regulatory affairs capabilities.
- Ketoconazole Demand:Rising clinical protocols for tinea capitis treatment in hospital dispensing channels are elevating antifungal formulation volumes above standard anti-dandruff baselines.
Market Restraints
- Coal Tar Sourcing:EPA registration requirements for coal tar derivatives impose multi-year approval timelines that constrain formulation flexibility for OTC manufacturers.
- Active Ingredient Concentration:FDA upper limits on selenium sulfide percentages cap therapeutic efficacy claims in mass-market positioning.
- Botanical Extract Volatility:Supply concentration for Ayurvedic actives in South Asian sourcing corridors creates input cost unpredictability for natural-hybrid formulators.
Strategic Opportunities
- Foam Delivery Systems:Home-use channels in Germany and France are adopting residue-reducing foam technologies faster than gel formats, opening premium positioning above standard shampoo price tiers.
- Trichology Center Partnerships:Clinical-grade private label manufacturing for independent trichology chains represents uncontracted volume in the United Kingdom and Netherlands.
- IRA Manufacturing Credits:United States domestic production incentives for pharmaceutical-grade personal care are reducing cost disadvantages against Asian contract manufacturers.
Industry Challenges
- Formulation Chemist Scarcity:Shortage of specialists capable of navigating FDA cosmetic-drug hybrid classifications is extending product development cycles by 8-14 months.
- Cross-Border Registration Complexity:Divergent MDR and FDA monograph requirements force redundant stability testing and label redesign for multi-territory launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicated Shampoo Market |
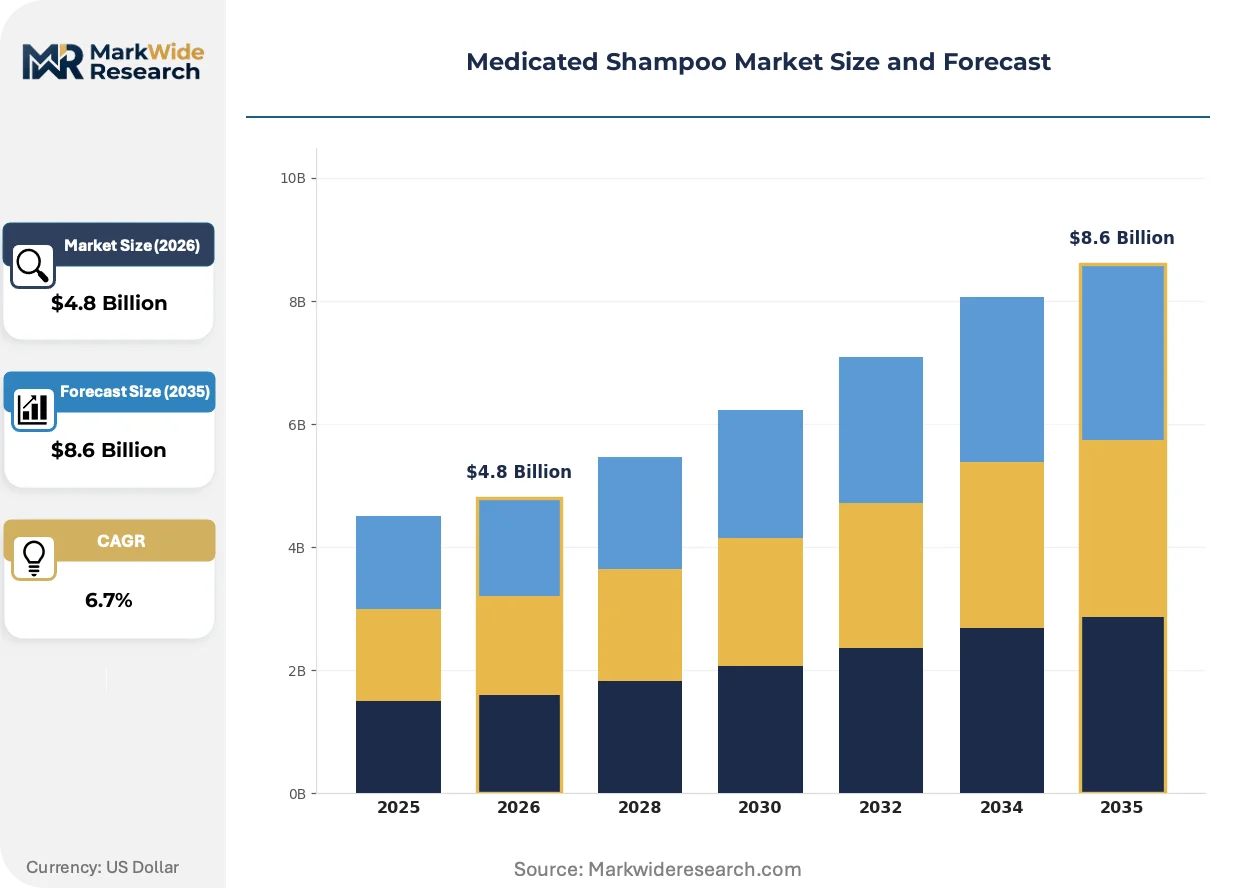
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Dandruff, Anti-Acne, Anti-Fungal, Moisturizing Active Ingredient: Zinc Pyrithione, Ketoconazole, Salicylic Acid, Coal Tar Formulation: Gel, Foam, Liquid, Bar End User: Adults, Children, Sensitive Scalps, Professional Use |
| Companies Covered | Henkel AG & Co. KGaA, Himalaya Wellness Company, Procter & Gamble, Hain Celestial Group, Shiseido Company, Unilever, Kao Corporation, Summers Laboratories, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicated Shampoo Market Strategic Shifts
Controlled-release delivery technologies and regulatory boundary reclassifications are compressing traditional competitive advantages between mass-market and clinical-grade manufacturers.
Encapsulated zinc pyrithione microsphere technology is displacing conventional suspension formulations in sensitive scalp protocols. Trichology centers in Japan and South Korea are adopting these systems at twice the pace of Western markets. The shift is displacing commodity-grade active suppliers from premium treatment regimens.
MDR Article 117 clinical evaluation requirements for borderline cosmetic-drug products are extending conformity assessment timelines by 12-18 months. Manufacturers with existing notified body relationships are capturing shelf space from smaller competitors unable to absorb compliance costs. Hospital procurement departments in Italy and Spain are prioritizing MDR-certified suppliers in tender specifications.
Subscription-based replenishment models bundled with scalp health monitoring apps are capturing recurring revenue from traditional pharmacy walk-in purchases. Direct-to-consumer channels in the United States and United Kingdom are replacing retail pharmacy as the primary acquisition path for chronic condition users. This behavioral pivot concentrates customer lifetime value data with platform operators rather than brand manufacturers.
Medicated Shampoo Market Segmentation
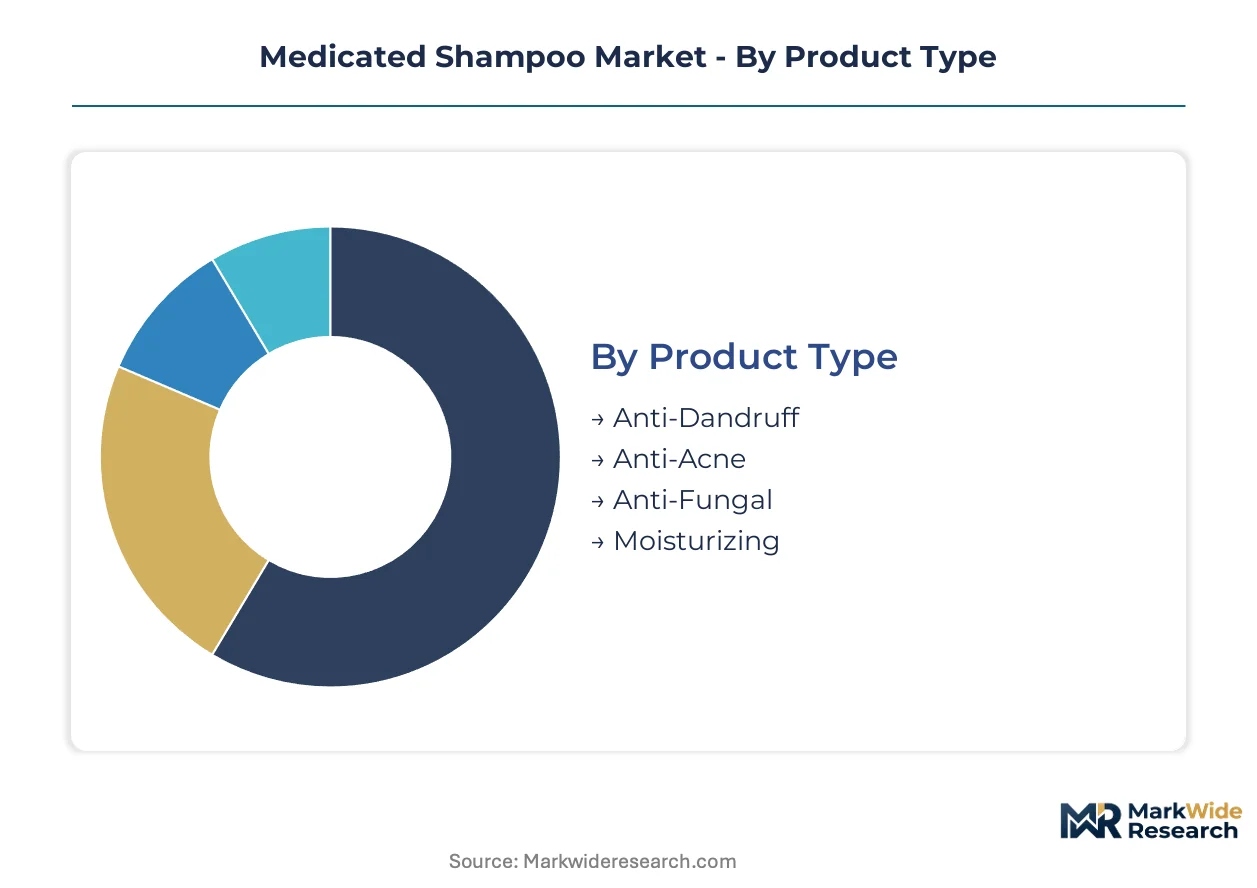
Medicated shampoo manufacturers must align formulation architecture with distinct dispensing channels. Channel-specific packaging, concentration limits, and application protocols fragment production runs and inventory requirements across segments.
Product Type:
Anti-dandruff formulations flow through mass retail and pharmacy channels, while antifungal variants concentrate in hospital dispensing and trichology clinics.
- Anti-Dandruff:Zinc pyrithione and selenium sulfide suspensions at 0.5-2% concentration dominate shelf-stable retail formats. United States mass pharmacy chains capture the highest throughput volumes for chronic maintenance regimens.
- Anti-Fungal:Ketoconazole-based protocols at prescription-tier concentrations serve tinea capitis treatment pathways. Hospital procurement departments in Germany and France prioritize these formulations for dermatology wards.
- Anti-Acne:Salicylic acid hybrids address folliculitis overlap conditions in teen and young adult demographics.
- Moisturizing:Ceramide-enriched medicated bases support post-treatment scalp barrier repair in sensitive scalp protocols.
By volume, Anti-Dandruff leads. By growth pace, Anti-Fungal is expanding most quickly through prescription-tier reimbursement expansion.
Active Ingredient:
Ingredient sourcing strategies diverge sharply between botanical-extract suppliers and synthetic active manufacturers, with cost tiers clustering around regulatory compliance burdens.
- Zinc Pyrithione:Controlled-release microsphere technologies developed for sensitive scalp protocols command premium positioning above commodity suspensions. Johnson & Johnson's dermatologist endorsement programs concentrate demand in United States clinical channels.
- Ketoconazole:Azole antifungal actives at 1-2% concentration require FDA drug registration and prescription-tier labeling. Rising tinea capitis protocols in Japanese hospital dispensing are elevating volumes.
- Salicylic Acid:Keratolytic actives face concentration caps in OTC monographs that limit therapeutic claim breadth.
- Coal Tar:EPA-registered derivatives at 0.5-5% concentration serve psoriasis protocols with multi-year approval timelines constraining formulation flexibility.
Zinc Pyrithione maintains the broadest channel penetration. Ketoconazole gains share fastest through telehealth-integrated prescription pathways.
Formulation:
Application mechanics determine contact time, residue profiles, and patient compliance rates across home-use versus clinical environments.
- Gel:Viscous aqueous bases enable precise dosing control and extended scalp contact in hospital and clinic dispensing. Italian and Spanish hospital procurement departments specify gel formats for inpatient dermatology protocols.
- Foam:Aerosolized delivery systems reduce residue concerns and application time for home-use channels. German and French consumers are adopting foam technologies faster than gel alternatives.
- Liquid:Traditional rinse-off formats dominate mass-market price positioning with established manufacturing infrastructure.
- Bar:Solid shampoo formats address sustainability preferences and travel-size regulatory compliance in European markets.
Liquid formulations retain volume leadership. Foam delivery systems are climbing the fastest through premium home-use positioning.
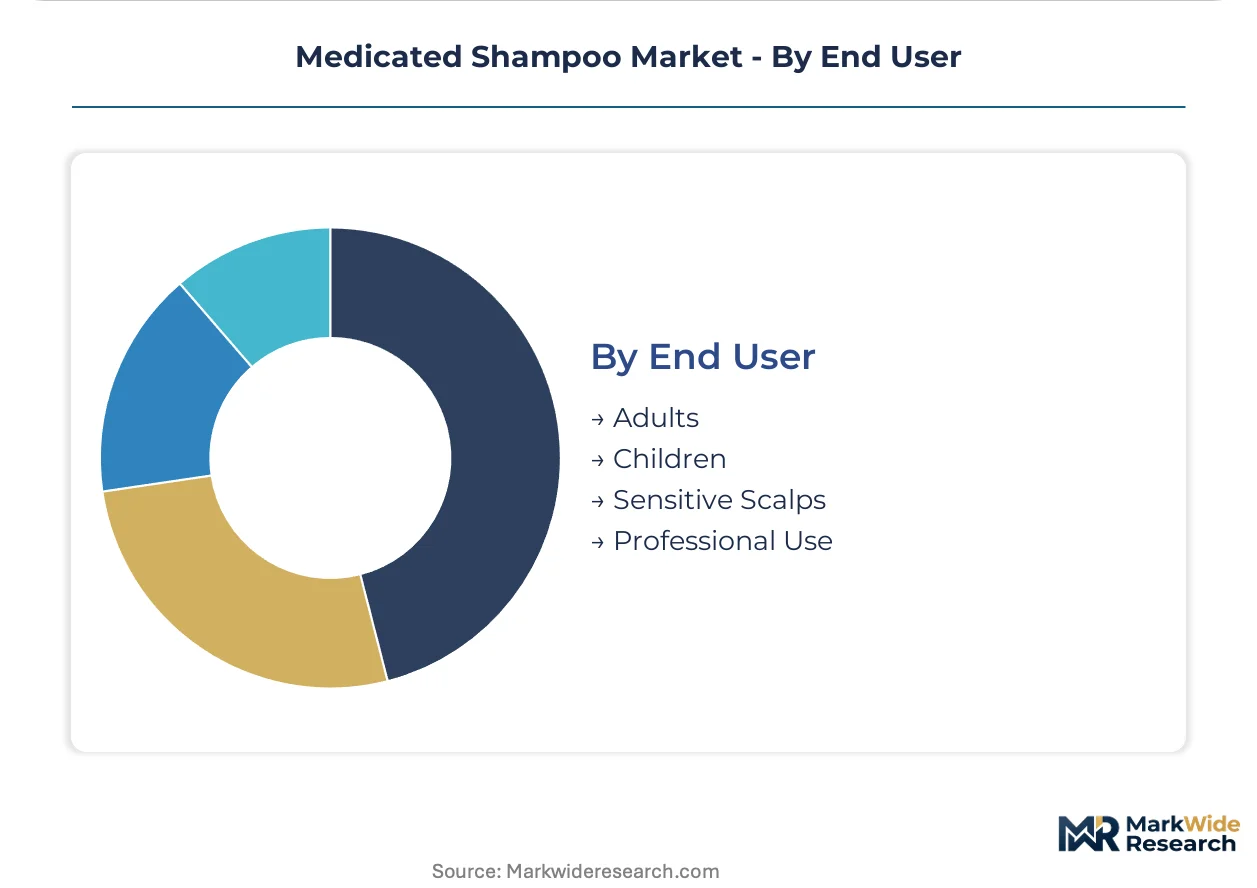
End User:
User-specific safety profiles and application assistance requirements split manufacturing between self-administered and professionally supervised protocols.
- Adults:Self-directed chronic condition management drives subscription replenishment models in United States direct-to-consumer channels bundled with scalp health monitoring apps.
- Children:Pediatric formulations require gentler active concentrations and tear-free base modifications with stricter label warnings.
- Sensitive Scalps:Fragrance-free, pH-balanced protocols with encapsulated actives serve post-chemotherapy and eczema patient populations in United Kingdom trichology centers.
- Professional Use:Concentrated actives for salon and clinic application require licensing restrictions and bulk dispensing formats.
Adult self-use captures the highest absolute volume. Professional Use is gaining share fastest through trichology center network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Germany absorb premium clinical-grade pricing with minimal volume elasticity, while Indian and Brazilian consumers gravitate toward botanical-hybrid formats at mid-tier price points. Mass-market channels in Mexico and Southeast Asia exhibit acute price sensitivity, compressing manufacturer margins.
United States
Direct-to-consumer subscription models partnered with telehealth platforms are displacing traditional pharmacy walk-in purchases for chronic scalp conditions. The FDA's ongoing scrutiny of coal tar concentration limits in OTC formulations is forcing active ingredient sourcing revisions among domestic manufacturers. New Jersey and Pennsylvania host concentrated pharmaceutical-grade personal care production clusters where IRA manufacturing credits are reducing cost disadvantages against Asian contract manufacturers.
Germany
Hospital procurement departments in Berlin and Munich prioritize MDR-certified suppliers for inpatient dermatology protocols, elevating compliance-capable manufacturers. ECHA frameworks under REACH continue tightening cosmetic-drug boundary classifications, extending conformity assessment timelines for borderline products. The Rhine-Ruhr industrial corridor concentrates gel formulation manufacturing for clinical dispensing channels across German-speaking Europe.
Japan
Trichology centers in Tokyo and Osaka are adopting encapsulated zinc pyrithione microsphere technologies at twice the pace of Western markets, displacing commodity-grade active suppliers. METI oversight of quasi-drug classifications creates regulatory predictability for manufacturers navigating cosmetic-drug hybrids. The Kanto region anchors premium sensitive-scalp protocol development for post-chemotherapy patient populations.
India
Ayurvedic botanical-active hybrids occupy distinct price-positioning between pharmaceutical and natural segments, capturing value-conscious consumers in Mumbai and Delhi. CDSCO oversight of drug-cosmetic classifications imposes formulation constraints on coal tar and ketoconazole concentrations. Maharashtra and Gujarat host concentrated South Asian sourcing corridors for Ayurvedic actives where supply volatility creates input cost unpredictability.
United Kingdom
Independent trichology chains in London and Manchester represent uncontracted volume for clinical-grade private label manufacturing. The Medicines and Healthcare products Regulatory Agency enforces strict label redesign requirements for products crossing the cosmetic-drug boundary. The Southeast England cluster concentrates subscription-platform operations bundling scalp health monitoring apps with replenishment models.
Medicated Shampoo Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with mass-market multinationals leveraging global distribution infrastructure against clinical-grade formulators dependent on dermatologist endorsement programs. Three archetypes dominate: pharmaceutical-cosmetic hybrids with captive regulatory affairs capabilities, botanical-natural specialists occupying mid-tier price positioning, and mass-market incumbents with pharmacy channel saturation. Competitive moves concentrate on M&A for regulatory expertise and strategic partnerships with telehealth platforms.
Among the integrated multinational tier, Procter & Gamble and Unilever exemplify mass-market incumbents with pharmacy and mass retail channel saturation across North America and Europe. Johnson & Johnson occupies a position within the pharmaceutical-cosmetic hybrid archetype, anchored by dermatologist endorsement programs in United States clinical channels. Himalaya Wellness Company represents the botanical-natural specialist tier, positioned between pharmaceutical and natural segments with concentrated presence in South Asian and Middle Eastern markets.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Himalaya Wellness Company |
| Procter & Gamble |
| Hain Celestial Group |
| Shiseido Company |
| Unilever |
| Kao Corporation |
| Summers Laboratories |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Ninety-day active ingredient inventory buffers at North American formulators compress pricing power for coal tar and ketoconazole suppliers while amplifying margin pressure on botanical-extract dependent manufacturers facing South Asian supply volatility. This inventory posture concentrates negotiating leverage with synthetic active producers holding EPA and FDA drug registrations, leaving natural-hybrid competitors exposed to Ayurvedic input cost swings.
Pricing Analysis
Subscription replenishment revenue bundled with scalp health monitoring apps drives lifetime value capture beyond initial unit sales. Three-tier pricing structure across premium encapsulated actives, standard suspension formulations, and economy liquid bases separates clinical-grade from mass-market positioning. Cost compression in botanical-hybrid tiers intensifies as Maharashtra and Gujarat sourcing corridors face monsoon-driven supply disruptions. Mass-market pharmacy chains in the United States exhibit acute price sensitivity, while German hospital procurement departments absorb premium clinical-grade pricing with minimal volume elasticity.
Supply Chain Analysis
Strategic stockpiling of selenium sulfide and zinc pyrithione precursors dominates manufacturer preferences over just-in-time sourcing given FDA monograph compliance timelines and multi-year stability testing requirements. Active ingredient production concentrates in the United States, Germany, and India, with synthetic actives anchored in domestic pharmaceutical corridors and botanical extracts drawing from South Asian agricultural networks. Single-source vulnerability pervades Ayurvedic active supply chains where crop concentration in Maharashtra and Gujarat creates input unpredictability. Distribution runs through pharmacy retail, hospital procurement, and direct-to-consumer subscription platforms in divergent fulfillment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution pressure from telehealth-integrated prescription platforms that disintermediate traditional pharmacy channels and capture customer lifetime value data. Botanical-natural specialists and mass-market multinationals must navigate this platform-mediated threat to maintain brand equity and pricing power.
For Market Incumbents: Shield dermatologist endorsement relationships through controlled-release technology investments that differentiate clinical-grade protocols from commodity suspensions. Deepen backward integration into captive regulatory affairs capabilities to compress MDR Article 117 conformity timelines that currently extend product launches. Prioritize telehealth platform partnerships before subscription-based competitors lock in chronic condition user bases and displace pharmacy walk-in purchases.
For New Entrants and Emerging Players: FDA cosmetic-drug hybrid fast-track pathways offer expedited market entry for formulations leveraging existing monograph actives at compliant concentrations. White-space concentrates in clinical-grade private label manufacturing for independent trichology chains in the United Kingdom and Netherlands where uncontracted volume persists. Target foam delivery system adoption in German and French home-use channels where residue-reducing technologies climb faster than established gel formats.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capability consolidation play because MDR certification and FDA monograph navigation expertise concentrate competitive advantage among a narrowing set of compliant manufacturers. Acquisition candidates with existing notified body relationships and captive formulation chemists command premium positioning as development cycle extensions squeeze smaller competitors. Watch trichology center network expansion rates as the inflection signal for clinical-grade volume migration from mass retail channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Partnership | Direct-to-consumer subscription models displace pharmacy walk-in purchases for chronic scalp conditions. |
| Encapsulated Active Technology Investment | Microsphere delivery systems capture premium positioning in Japanese and South Korean trichology protocols. |
| MDR Certification Fast-Track | Notified body relationships accelerate conformity assessment timelines for borderline cosmetic-drug products. |
| Trichology Center Private Label Manufacturing | Uncontracted clinical-grade volume in United Kingdom and Netherlands offers white-space expansion. |
| Botanical Supply Chain Diversification | Multi-source Ayurvedic active procurement reduces Maharashtra and Gujarat concentration risk. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with dermatology clinic procurement managers, trichology center operators, pharmaceutical formulation chemists, and regulatory affairs specialists at OTC and prescription-tier manufacturers. Secondary validation drew from FDA monograph filings, EMA borderline product classifications, CDSCO drug-cosmetic determinations, and REACH compliance disclosures. Customs records for coal tar derivatives and zinc pyrithione precursors, alongside hospital procurement tender databases in Germany, Italy, and Spain, supported volume estimation. Bottom-up channel throughput analysis and top-down regulatory framework sizing were triangulated to reconcile segment-level estimates.
Across the analysis window, projections reflect modeled trajectories for anti-dandruff, antifungal, anti-acne, and moisturizing product types segmented by gel, foam, liquid, and solid formulations. Active ingredient dynamics incorporated zinc pyrithione, ketoconazole, salicylic acid, and coal tar concentration tier shifts. End-user segmentation spanned adult self-use, pediatric, sensitive scalp, and professional application protocols. CAGRs were derived from regression analysis of historical dispensing channel growth, telehealth platform partnership expansion, and trichology center network development. Forecast inputs included FDA monograph revision timelines, MDR Article 117 implementation pacing, and IRA manufacturing credit uptake rates.
The analysis sits within stated boundaries; outcomes outside sustained telehealth platform growth, stable FDA coal tar concentration thresholds, or uninterrupted South Asian botanical supply would require recalibration. Forecasts reflect assumptions regarding regulatory compliance cost absorption and channel migration velocity. Revision becomes warranted when MDR certification delays or botanical input volatility crosses thresholds that materially alter manufacturer competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Epigenetic Cosmetic Products Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Liquid Lipstick Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Eyeliner Pen Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Thailand Skin Care Products Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Japan Organic Cosmetics Market
Cosmetics & Skincare
GCC Halal Cosmetics Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market