
 Pet Hair Care Market | 2026-2036
Pet Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Hair Care Market Outlook
Veterinary clinics are consolidating as a high-value end-use vertical for pet hair care, shifting volume away from traditional retail channels. Nestlé Purina Petcare leverages its nutrition-to-grooming brand continuity to anchor shelf positioning in mass retail. Wahl Clipper Corporation sustains manufacturing scale across professional-grade grooming tools, while Furminator specializes in de-shedding technology that commands premium placement in specialty pet stores.
Pet hair care encompasses topical formulations and mechanical instruments designed to maintain coat hygiene, manage shedding, and prevent dermatological conditions in companion animals; active ingredients typically include oatmeal extracts, chlorhexidine, and silicone-based detangling agents that address pH-sensitive skin barriers. Grooming tools and de-shedding applications occupy the strongest margin pools as pet owners trade up to ergonomic, breed-specific designs. Natural products within the solution dimension are expanding fastest as clean-label expectations migrate from human personal care into pet categories. Shampoos remain the volume anchor across retail and professional channels, though conditioners are gaining traction in salon-format distribution.
The US FDA Center for Veterinary Medicine and the EPA jointly govern topical pet product safety, while the EU REACH regulation restricts certain surfactants and preservatives in formulations sold across Europe. These frameworks elevate compliance costs for chemical formulations but simultaneously accelerate innovation in hypoallergenic and plant-derived alternatives. Stakeholders must monitor how state-level veterinary practice acts in the US reshape permissible service boundaries between clinics and independent groomers.
Market Dynamics
Veterinary clinics are consolidating as a high-value end-use vertical for pet hair care, shifting volume away from traditional retail channels as preventive coat health protocols expand and clinic service boundaries broaden.
Growth Catalysts
- REACH Chemical Safety Framework:The EU REACH regulation is accelerating innovation in hypoallergenic and plant-derived formulations across European markets, creating new product categories that command premium positioning.
- Salon-Format Distribution:Premium grooming salon chains in the United States are driving category development through professional-grade service bundling that elevates consumer expectations for at-home maintenance products.
- De-Shedding Technology:Ergonomic, breed-specific grooming tool designs are capturing margin pools as pet owners trade up from generic instruments to specialized mechanical solutions.
Market Restraints
- Surfactant Input Volatility:REACH-restricted surfactants and preservatives in European formulations elevate compliance costs and compress margins for chemical-based product lines.
- Veterinary Practice Act Fragmentation:State-level veterinary practice acts in the US create regulatory friction that limits permissible service boundaries between clinics and independent groomers, constraining channel expansion.
- Natural Ingredient Sourcing Concentration:Clean-label oatmeal extracts and chlorhexidine alternatives face supply concentration risks in specific agricultural regions, creating input cost instability.
Strategic Opportunities
- Direct-to-Consumer Channels:Digital-native subscription models for breed-specific grooming kits represent underpenetrated white space in the United States market, bypassing traditional retail markup structures.
- Conditioner Category Expansion:Conditioners are gaining traction in salon-format distribution as a complementary revenue stream to established shampoo volume anchors.
- Silicone-Based Detangling Convergence:Cross-application of human personal care silicone chemistry into pH-sensitive pet formulations is opening premium positioning opportunities in specialty pet stores.
Industry Challenges
- Dermatological Certification Timelines:FDA Center for Veterinary Medicine safety validation for topical formulations extends product development cycles, delaying market entry for novel active ingredients.
- Ergonomic Design Talent Scarcity:Breed-specific mechanical tool development requires specialized industrial design capabilities that concentrate among a limited pool of grooming equipment specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Hair Care Market |
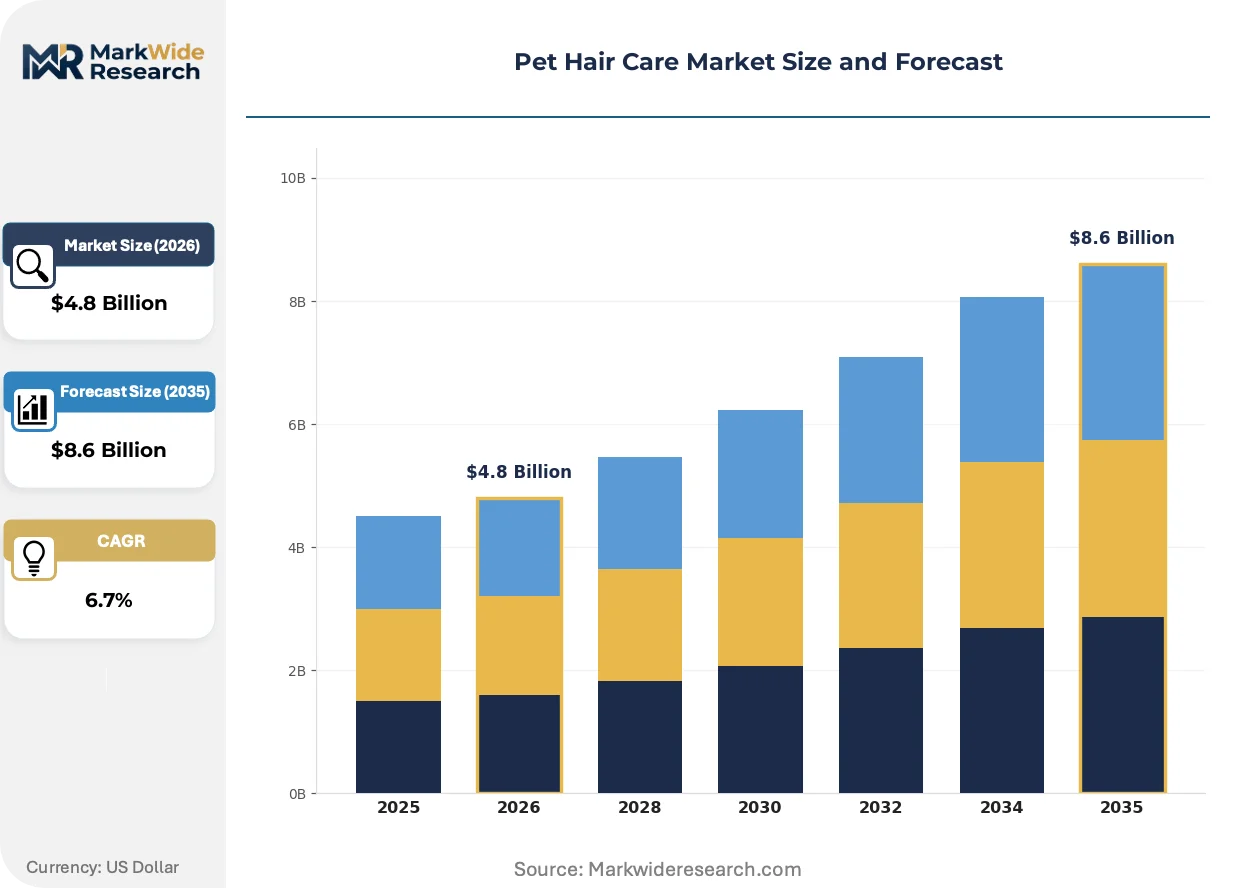
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Grooming Tools, Detanglers End User: Pet Owners, Veterinary Clinics, Pet Grooming Salons, Animal Shelters Solution: Natural Products, Chemical Formulations, Hypoallergenic Products, Styptic Powders Application: Bathing, Brushing, De-shedding, Dematting |
| Companies Covered | Nestlé Purina Petcare, Groomer's Choice, SynergyLabs, Wahl Clipper Corporation, Petco Animal Supplies, Inc., Furminator, PetSafe, Burt's Bees, Hartz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Hair Care Market Strategic Shifts
Formulation chemistry and distribution architecture are undergoing parallel transformation as clean-label migration from human personal care reshapes ingredient sourcing priorities and channel control shifts toward professional service integration.
Smart grooming devices with embedded sensors are automating coat condition monitoring during home grooming sessions. High-frequency purchasers in the premium segment are adopting these instruments at accelerating rates. This convergence of diagnostic hardware and maintenance tools is automating the traditional separation between professional assessment and consumer execution.
EPA-FDA joint governance of topical pet product safety is tightening pre-market notification requirements for new chemical entities. Manufacturers are reformulating around restricted surfactant classes ahead of anticipated state-level adoption of federal standards. Professional salon channels in California and New York are most affected, with distributors accelerating inventory turnover to clear non-compliant stock.
Breed-specific subscription boxes are consolidating purchasing decisions into curated quarterly cycles that displace episodic retail browsing. Specialty pet stores and veterinary clinic dispensaries are the channels being disrupted by this model, replaced by algorithmic replenishment tied to coat growth cycles. This behavioral shift is most visible in metropolitan United States markets with high purebred dog ownership density.
Pet Hair Care Market Segmentation
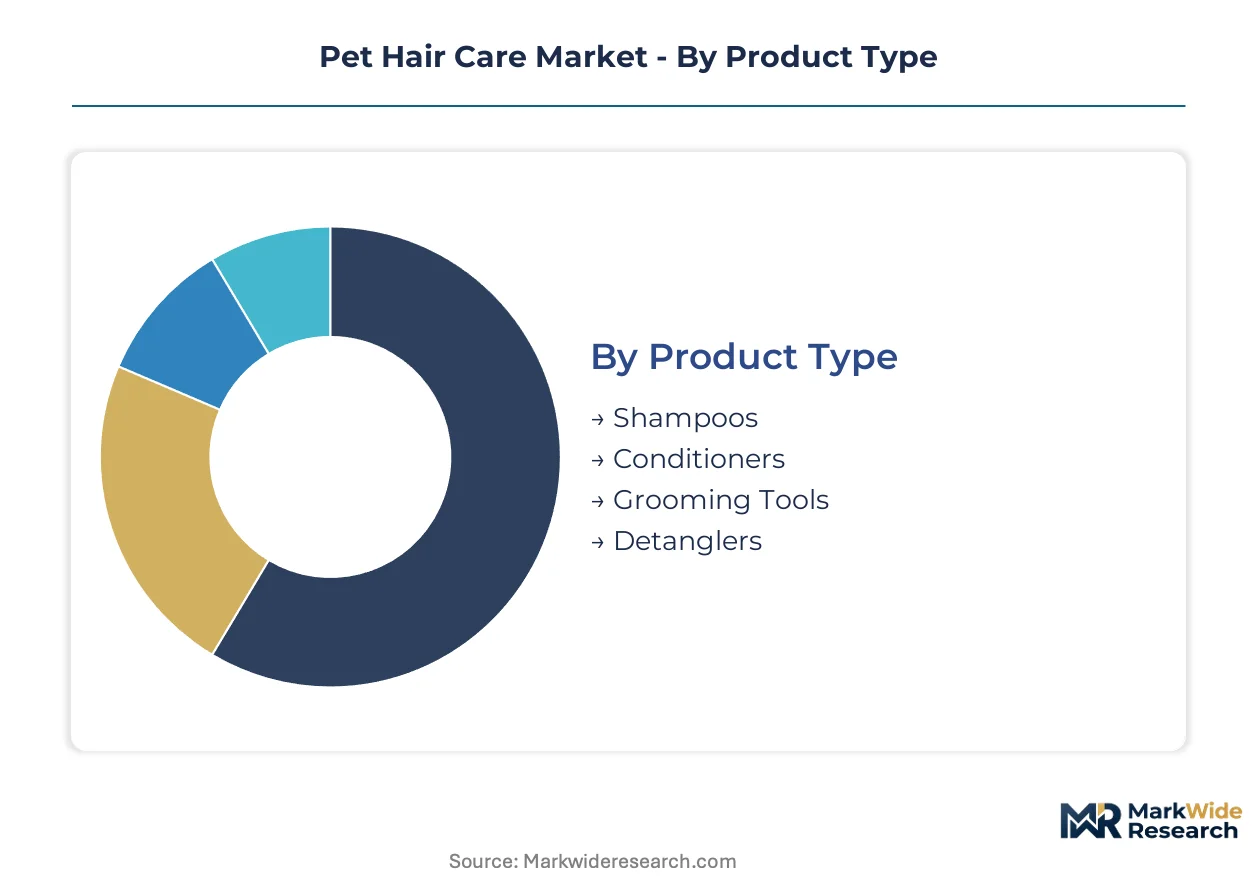
Segmentation in pet hair care reveals distinct margin architectures across formulation chemistry, professional service integration, and mechanical tool design. Understanding these divides exposes where pricing power concentrates and where channel control is shifting.
Product Type:
Supply concentration in manufacturing equipment and raw material sourcing determines which product lines capture scale economies versus premium positioning.
- Shampoos:Volume anchors across mass retail and veterinary dispensaries, with pH-balanced oatmeal and chlorhexidine bases dominating formulation. United States mass retail chains consolidate procurement, driving standardization around 16-20 oz bottle formats.
- Grooming Tools:Ergonomic, breed-specific designs command the strongest margin pools as pet owners trade up from generic instruments. De-shedding variants with stainless steel edges and rubberized grips concentrate manufacturing among specialized metalworking facilities.
- Conditioners:Gaining traction in salon-format distribution as complementary revenue streams to shampoo anchors.
- Detanglers:Silicone-based formulations targeting long-coated breeds, with spray and leave-in formats displacing traditional rinse-out products in specialty channels.
Shampoos absorb the bulk of installed capacity; grooming tools are expanding most quickly.
End User:
Cost tier stratification separates episodic low-engagement purchasers from high-frequency professional service relationships.
- Pet Owners:Direct-to-consumer subscription models and mass retail dominate, with breed-specific curation algorithms displacing episodic browsing in metropolitan United States markets.
- Veterinary Clinics:Consolidating as high-value verticals through preventive coat health protocols that bundle topical products with dermatological assessments. FDA Center for Veterinary Medicine compliance requirements elevate entry barriers for clinic-dispensed formulations.
- Pet Grooming Salons:Professional-grade service bundling elevates consumer expectations for at-home maintenance, creating pull-through demand for retail SKUs.
- Animal Shelters:Volume purchasers prioritizing cost efficiency and broad-spectrum efficacy over specialized formulations, with procurement concentrated through nonprofit distributors.
Pet owners represent the deepest volume base; veterinary clinics are climbing the fastest as service boundaries broaden.
Solution:
Application maturity separates established chemical formulations from emerging clean-label alternatives facing sourcing and certification hurdles.
- Chemical Formulations:Chlorhexidine-based antimicrobials and surfactant systems remain the clinical standard, though EU REACH restrictions on specific preservative classes are forcing reformulation cycles.
- Natural Products:Oatmeal extracts, aloe vera, and plant-derived surfactants are gaining fastest as clean-label expectations migrate from human personal care. Agricultural sourcing concentration in specific regions creates input cost volatility.
- Hypoallergenic Products:Fragrance-free, pH-optimized formulations targeting sensitive skin barriers, with certification timelines extending development cycles under FDA Center for Veterinary Medicine oversight.
- Styptic Powders:Niche solutions for grooming-induced micro-injuries, with ferric subsulfate and aluminum chloride bases concentrated in professional tool kits.
Chemical formulations retain the bulk of installed capacity; natural products are gaining share fastest.
Application:
Customer type and engagement frequency determine whether applications support recurring revenue models or remain transactional.
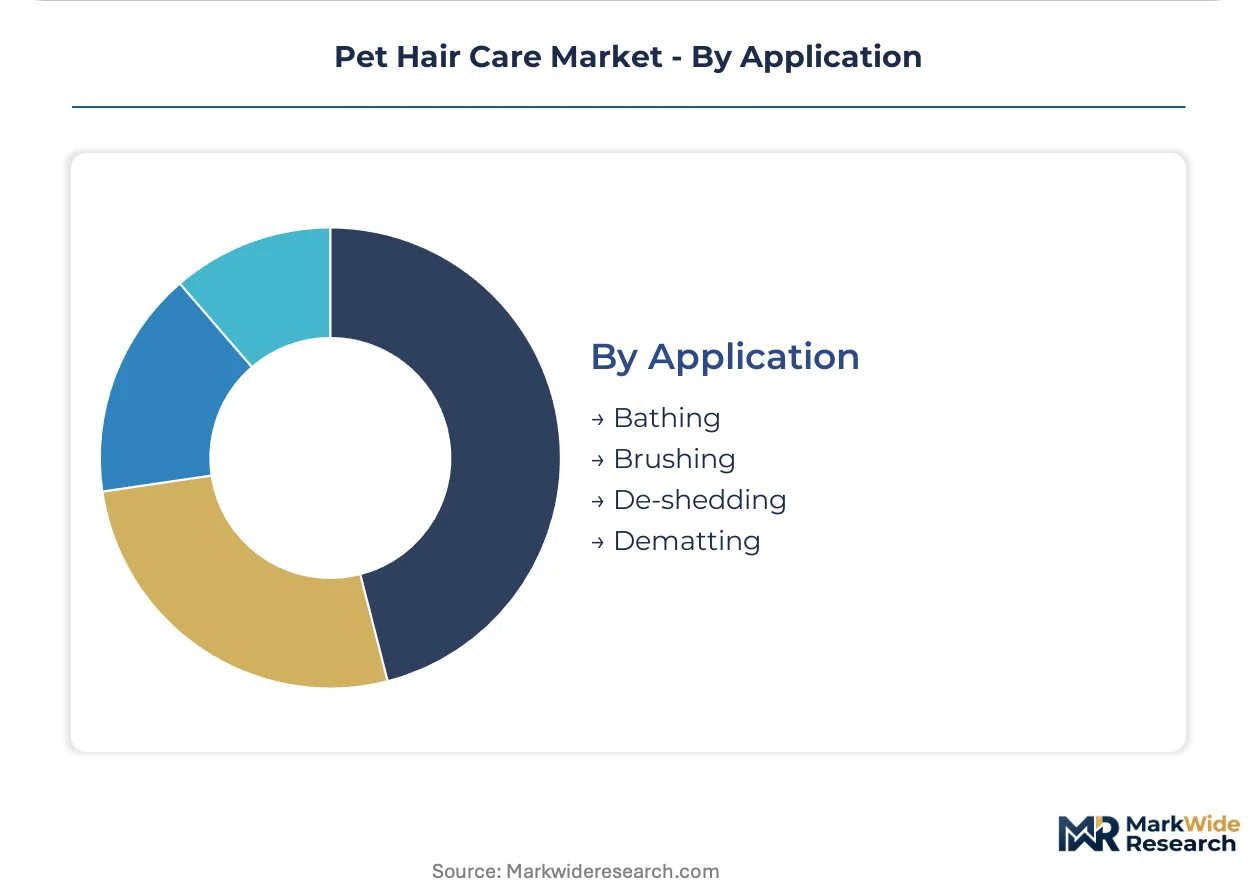
- Bathing:Shampoo and conditioner consumption anchors routine maintenance schedules, with frequency varying by breed coat type and owner hygiene preferences.
- De-shedding:Seasonal demand spikes drive tool replacement cycles, with smart devices embedding coat condition sensors to automate scheduling recommendations.
- Brushing:Daily engagement applications supporting the broadest tool variety, from slicker brushes to pin brushes tailored to coat length and texture.
- Dematting:Problem-resolution applications concentrated among long-coated breed owners and professional groomers, with specialized rake and comb designs commanding premium pricing.
Bathing absorbs the bulk of installed capacity; de-shedding is expanding most quickly through technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of pet grooming tools concentrates in metalworking clusters across China and Germany, while formulation chemistry and premium brand development dominate in the United States and Western Europe. Consumption patterns diverge sharply between mature markets with veterinary-integrated service models and emerging economies where retail channels still govern purchasing behavior.
United States
Premium grooming salon chains and direct-to-consumer subscription services are consolidating purchasing decisions in metropolitan markets with high purebred dog ownership density. The FDA Center for Veterinary Medicine and EPA jointly govern topical product safety, extending development timelines for novel formulations. California and New York professional salon channels face accelerated inventory turnover requirements as distributors clear non-compliant stock ahead of anticipated state-level adoption of federal standards.
Germany
Ergonomic tool design capabilities concentrate among specialized industrial manufacturers serving both professional groomers and export markets. The EU REACH framework restricts specific surfactants and preservatives, forcing reformulation cycles that elevate compliance costs for chemical-based product lines. The North Rhine-Westphalia metalworking cluster anchors stainless steel grooming instrument production for European distribution.
China
Manufacturing scale for mechanical grooming tools and silicone-based detangling formulations supports global supply chains through Yangtze River Delta production facilities. The country's national chemical safety regulator maintains evolving standards for pet product ingredients that increasingly align with EU REACH restrictions. Zhejiang and Jiangsu provinces host concentrated capacity for grooming tool metal fabrication and plastic molding.
United Kingdom
Specialty pet retail channels and veterinary clinic dispensaries remain significant volume outlets despite digital disruption from subscription models. The Veterinary Medicines Directorate oversees topical product classifications that reshape permissible service boundaries between clinics and independent groomers. Greater London's premium pet service economy drives demand for breed-specific grooming protocols and associated maintenance products.
France
Natural and hypoallergenic formulation development accelerates as clean-label expectations migrate from human personal care into pet categories. ANSM oversight of cosmetic and veterinary product safety creates parallel compliance pathways for topical formulations. The Île-de-France region concentrates R&D activity for plant-derived surfactants and pH-optimized coat treatments.
Pet Hair Care Market Competitive Environment
Top-tier vendors anchor mass retail and veterinary channels through nutrition-to-grooming brand continuity, while mid-tier specialists capture margin pools in ergonomic tool design and de-shedding technology. The competitive structure stratifies across three archetypes: diversified consumer goods conglomerates with pet care divisions, specialized grooming equipment fabricators, and natural formulation specialists migrating from human personal care. Dominant competitive moves include portfolio diversification into adjacent pet wellness categories and strategic partnerships between formulation houses and professional salon chains.
Within the diversified consumer goods tier, Nestlé Purina Petcare leverages brand continuity across nutrition and grooming segments to secure shelf positioning in mass retail channels. Wahl Clipper Corporation and Furminator exemplify the specialized equipment archetype, with the former sustaining manufacturing scale across professional-grade grooming tools and the latter commanding premium placement through de-shedding technology specialization. These three companies occupy distinct competitive positions that reflect broader market segmentation between formulation chemistry and mechanical instrument design.
| Leading Market Players |
|---|
| Nestlé Purina Petcare |
| Groomer's Choice |
| SynergyLabs |
| Wahl Clipper Corporation |
| Petco Animal Supplies, Inc. |
| Furminator |
| PetSafe |
| Burt's Bees |
| Hartz |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA Center for Veterinary Medicine-compliant clinic dispensary formulations and mass retail commodity shampoos manifests in both pricing premiums and supply chain sourcing configurations. REACH-restricted surfactant substitution in European formulations elevates input costs while compressing margins for chemical-based lines.
Pricing Analysis
Short lead-time premiums attach to salon-format professional-grade bundles that bypass traditional retail markup structures, while spot inventory in mass channels trades at discounted rates. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-dispensed hypoallergenic formulations from specialty store natural products and mass retail commodity shampoos. Price differentiation hinges on certification tier and volume scale, with pricing pressure intensifying as REACH compliance costs feed through European chemical formulations. Animal shelters and nonprofit procurement channels exhibit highest price sensitivity, while premium grooming salons demonstrate lowest sensitivity due to service bundling economics.
Supply Chain Analysis
Returns and refurbishment flows for stainless steel grooming tools concentrate in Yangtze River Delta metalworking facilities, where remanufacturing extends product lifecycles. Geographic supply concentration centers on China for mechanical tool fabrication, Germany for precision metalworking, and the United States for formulation chemistry. Raw material dependencies include agricultural sourcing of oatmeal extracts from specific regions, chlorhexidine precursor chemicals, and silicone-based detangling agents. Single-source vulnerability in natural ingredient agricultural concentration creates supply chain risk. Distribution runs through veterinary clinic dispensaries, specialty pet retail, and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in specialized ergonomic design talent prop pricing power for breed-specific grooming tools. Capacity bottlenecks in FDA Center for Veterinary Medicine certification timelines limit clinic-dispensed formulation entrants.
For Market Incumbents: Extend certification coverage into hypoallergenic and plant-derived categories ahead of anticipated state-level adoption of federal standards. Deepen channel control through exclusive professional salon partnerships that lock in service bundling relationships. Vertical integration into agricultural sourcing of oatmeal extracts mitigates input cost volatility from geographic concentration. For New Entrants and Emerging Players: Direct-to-consumer veterinary clinic partnerships represent the most penetrable white space, bypassing traditional retail markup structures entirely. Algorithmic subscription models tied to coat growth cycles in metropolitan United States markets offer immediate addressable demand. Go-to-market execution should prioritize breed-specific curation algorithms that displace episodic retail browsing. For Investors and Strategic Acquirers: Re-rating potential sits with specialized ergonomic tool fabricators given de-shedding technology convergence and smart device sensor integration. Long-term viability over the five-to-ten year window favors manufacturers with captive metalworking capabilities and REACH-compliant formulation pipelines. Acquisition target archetypes include natural formulation specialists migrating from human personal care and de-shedding technology patent holders. The signal to watch is FDA Center for Veterinary Medicine pre-market notification clearance timelines for novel active ingredients.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses retail markup structures while capturing breed-specific algorithmic replenishment demand in metropolitan United States markets. |
| REACH-Compliant Formulation Reformulation | Accelerates plant-derived surfactant adoption ahead of anticipated state-level adoption of federal standards in California and New York. |
| Smart Grooming Device Integration | Embeds coat condition sensors that automate scheduling recommendations and displace traditional professional assessment boundaries. |
| Veterinary Clinic Channel Partnership | Locks in preventive coat health protocol bundling that shifts volume from traditional retail channels to high-margin dispensary formats. |
| Ergonomic Design Talent Acquisition | Concentrates specialized industrial design capabilities for breed-specific mechanical tool development among limited specialist pools. |
Study Parameters
Document review covered regulatory filings with the FDA Center for Veterinary Medicine and EPA, EU REACH substance restriction updates, and veterinary practice act compilations, complemented by interviews with veterinary dermatology specialists, professional groomer association representatives, and specialty pet retail category buyers. Secondary validation drew from customs trade data on grooming tool imports, Nielsen retail audit data on pet care SKU movement, and SEC 10-K disclosures from diversified consumer goods conglomerates with pet care divisions. Bottom-up triangulation across product-level volume estimates and top-down cross-reference against macroeconomic pet ownership trends anchored forecast integrity.
Cross-reference between historical volume trajectories and expert panel input on regulatory timeline expectations shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type chemistry, end-user channel control, solution formulation certification tier, and application engagement frequency. CAGRs were derived through regression analysis of historical growth patterns adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated coat growth cycle seasonality and breed-specific ownership density in metropolitan statistical areas.
Caveats apply where FDA Center for Veterinary Medicine safety validation delays, EU REACH substance restriction expansions, or state-level veterinary practice act revisions could materially shift the outlook. Forecasts reflect assumptions on regulatory timeline adherence and clean-label migration velocity from human personal care. Practitioners should monitor pre-market notification clearance queues and REACH candidate list updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Pad Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Raw Meat Pet Food Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Pet Dental Health Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Pet Care E-Commerce Market
Pet Care Products
Elevated Dog Bowls Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
Dog Food Market
Pet Care Products
Europe Pet Smart Tracker Market