
 Spain Pet Food Market | 2026-2036
Spain Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Pet Food Market Analytics
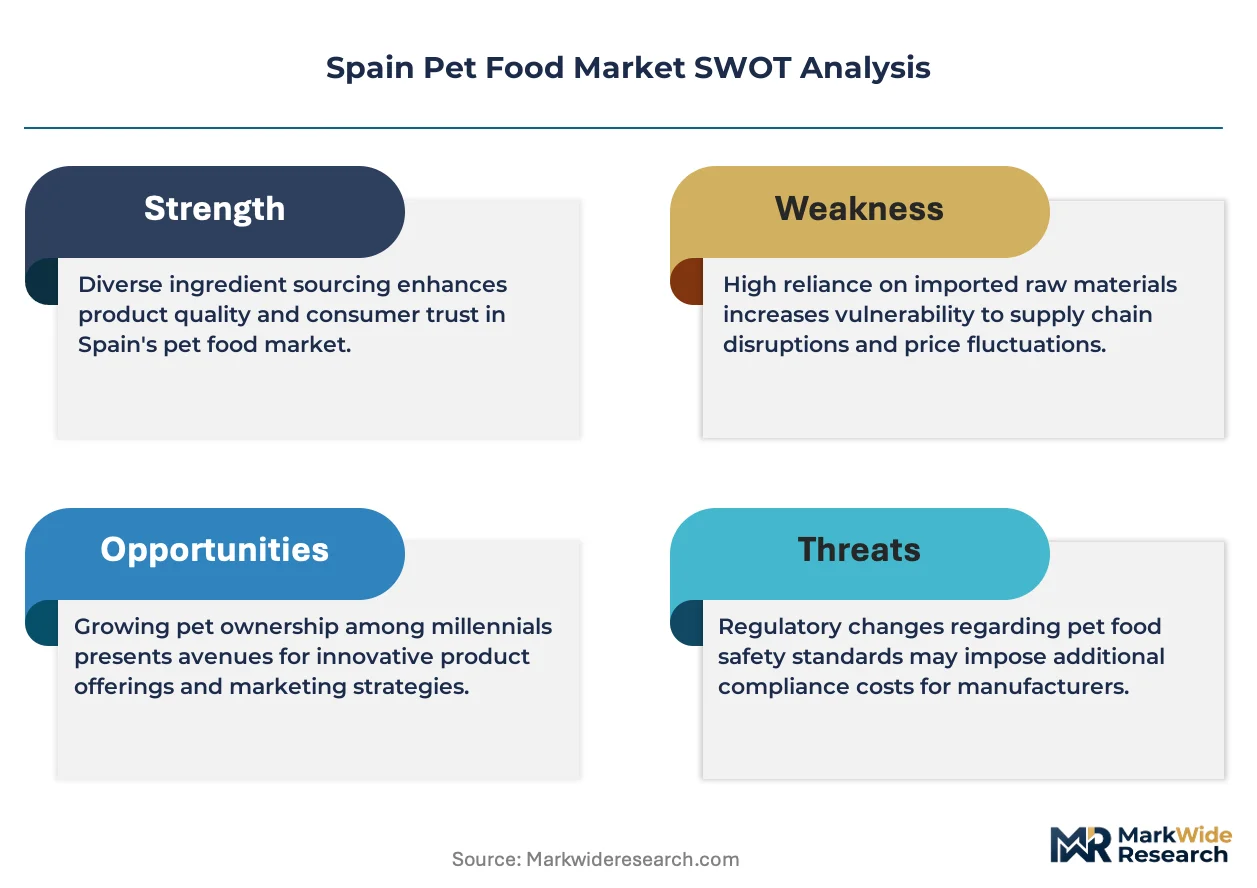
Multi-source ingredient procurement is recalibrating how Spanish manufacturers balance cost stability against supply resilience. Mars Incorporated leverages its European manufacturing footprint to secure protein supply chains across Iberia. Nestle Purina anchors its position through veterinary-exclusive formulations that bypass retail price competition. Affinity Petcare SA specializes in Mediterranean-sourced formulations that resonate with region-specific palatability preferences.
Spain pet food encompasses nutritionally complete and complementary feeds formulated for domesticated companion animals, typically containing protein meals, cereals, fats, vitamins, and minerals processed through extrusion, canning, or cold-pressing techniques to meet species-specific metabolic requirements. Dry food dominates volume throughput in supermarket and online channels due to shelf stability and lower logistics costs, while wet food commands margin concentration in premium and specialty tiers where moisture content and palatability drive unit economics. Treats represent the fastest-expanding segment as functional ingredients such as dental care additives and joint-support compounds justify price premiums in veterinary and pet-store channels.
Spain's Ministry of Agriculture enforces EU Regulation 767/2009 on feed labeling and safety, while the Spanish Agency for Food Safety and Nutrition monitors contaminant thresholds and nutritional claims. The EU Green Deal and Farm-to-Fork Strategy tighten sustainability reporting for pet food ingredient sourcing, pressuring manufacturers to document carbon intensity and deforestation-free supply chains. Stakeholders must monitor how forthcoming EU packaging waste rules and extended producer responsibility schemes reshape material costs and brand positioning across the value chain.
Market Dynamics
EU Green Deal compliance mandates are forcing Spanish pet food manufacturers to reconfigure ingredient sourcing and packaging specifications ahead of binding 2025 sustainability reporting deadlines.
Growth Catalysts
- EU Farm-to-Fork Strategy:Deforestation-free supply chain documentation requirements accelerate premium positioning for Iberian producers with traceable Mediterranean protein sources.
- Veterinary-channel premiumization:Madrid and Barcelona urban households redirect spending toward prescription-grade formulations sold through clinic networks.
- Cold-pressing technology:Nutrient retention advantages in artisanal dry food production attract functional-ingredient buyers seeking digestibility claims.
Market Restraints
- Animal protein cost volatility:Iberian pork and poultry meal prices fluctuate with agricultural commodity cycles, compressing mid-tier manufacturer margins.
- Import dependency for specialty additives:Joint-support compounds and dental-care enzymes concentrate sourcing from German and Dutch suppliers.
- Wet food logistics constraints:Higher moisture content elevates cold-chain costs and limits distribution radius for regional brands.
Strategic Opportunities
- Andalusian coastal corridor:Underpenetrated pet-store density in Málaga and Cádiz provinces offers first-mover expansion for premium treat specialists.
- Extended producer responsibility schemes:Forthcoming EU packaging waste rules reward early adopters of recyclable mono-material pouches with retailer preferential placement.
- Telemedicine-veterinary convergence:Subscription-based pet health platforms create direct-to-consumer channels bypassing traditional retail markups.
Industry Challenges
- Regulatory documentation talent scarcity:Shortage of professionals fluent in EU 767/2009 feed labeling compliance slows new product registration timelines.
- Legacy ERP integration with traceability systems:Batch-level ingredient tracking requirements clash with outdated manufacturing execution software at mid-sized facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Pet Food Market |
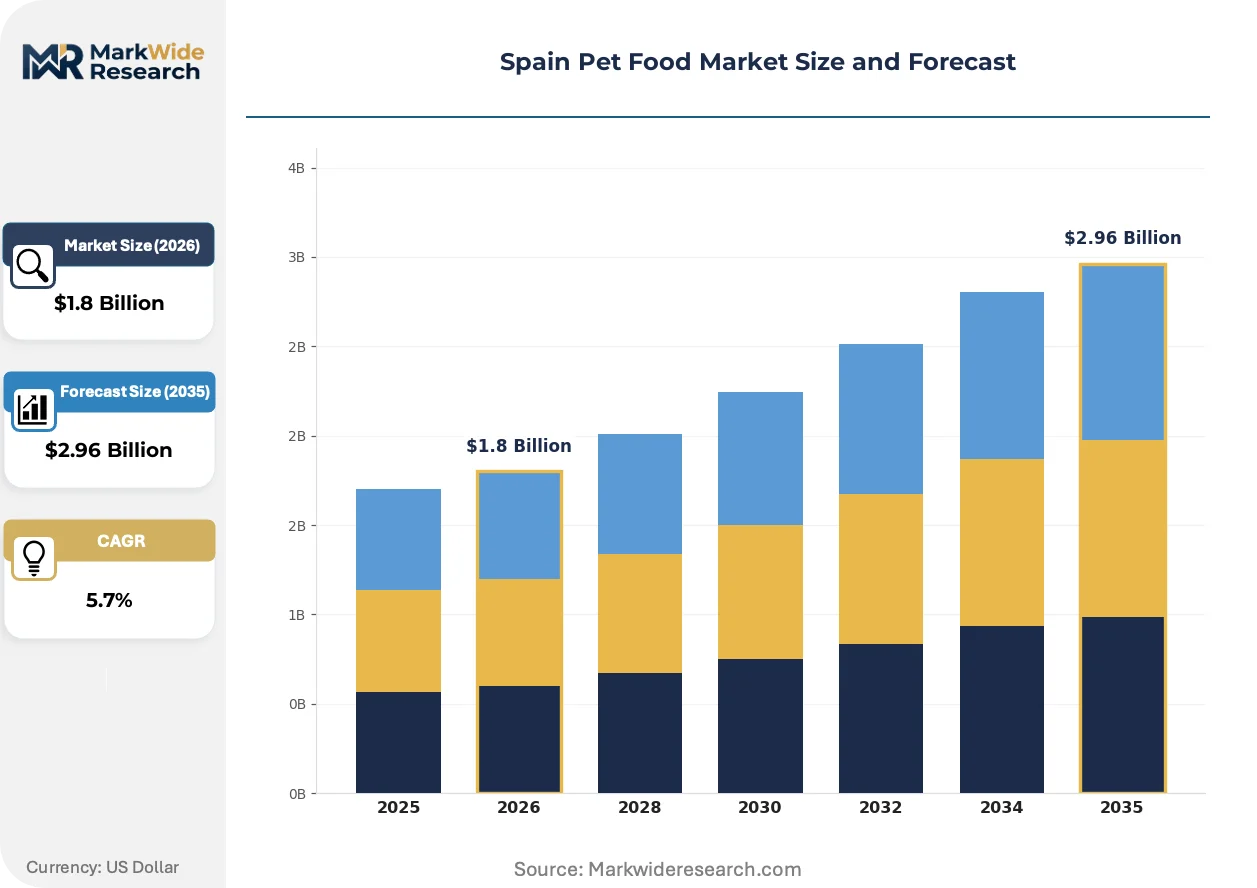
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Customer Type: Cat Owners, Dog Owners, Small Animal Owners, Exotic Pet Owners Brand Positioning: Premium, Mid-Range, Budget, Specialty Distribution Channel: Online Retail, Supermarkets, Pet Stores, Veterinary Clinics |
| Companies Covered | Colgate-Palmolive Company, General Mills Inc, Mars Incorporated, Alltech, Dechra Pharmaceuticals PLC, Nestle Purina, ADM, Schell & Kampeter Inc, Affinity Petcare SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Pet Food Market Evolving Landscape
Spanish pet food manufacturing is absorbing sustainability-driven material substitutions and digital traceability investments that redefine competitive differentiation beyond conventional nutrition claims.
Cold-pressed extrusion is absorbing capital allocation from conventional high-temperature processing lines. Premium dry food specialists in Catalonia deploy this technology to preserve heat-sensitive probiotics and omega fatty acids. The shift is absorbing margin pressure from energy-intensive thermal methods while enabling shelf-stable raw-adjacent positioning.
EU CSRD sustainability disclosure rules now extend to mid-cap pet food producers with balance sheets above defined thresholds. Mandatory Scope 3 emissions reporting forces documentation of upstream agricultural impacts from cereal and protein suppliers. Spanish manufacturers with integrated Iberian farming partnerships gain audit trail advantages over importers dependent on South American soy complexes.
Subscription-based replenishment models displace supermarket bulk purchasing among Madrid's dual-income households. Automated delivery scheduling for prescription diets locks in twelve-month customer lifetime value multiples exceeding retail impulse buys. Veterinary clinics in Barcelona pilot integrated telehealth-food bundling that captures recurring revenue streams from chronic condition management.
Spain Pet Food Market Segmentation
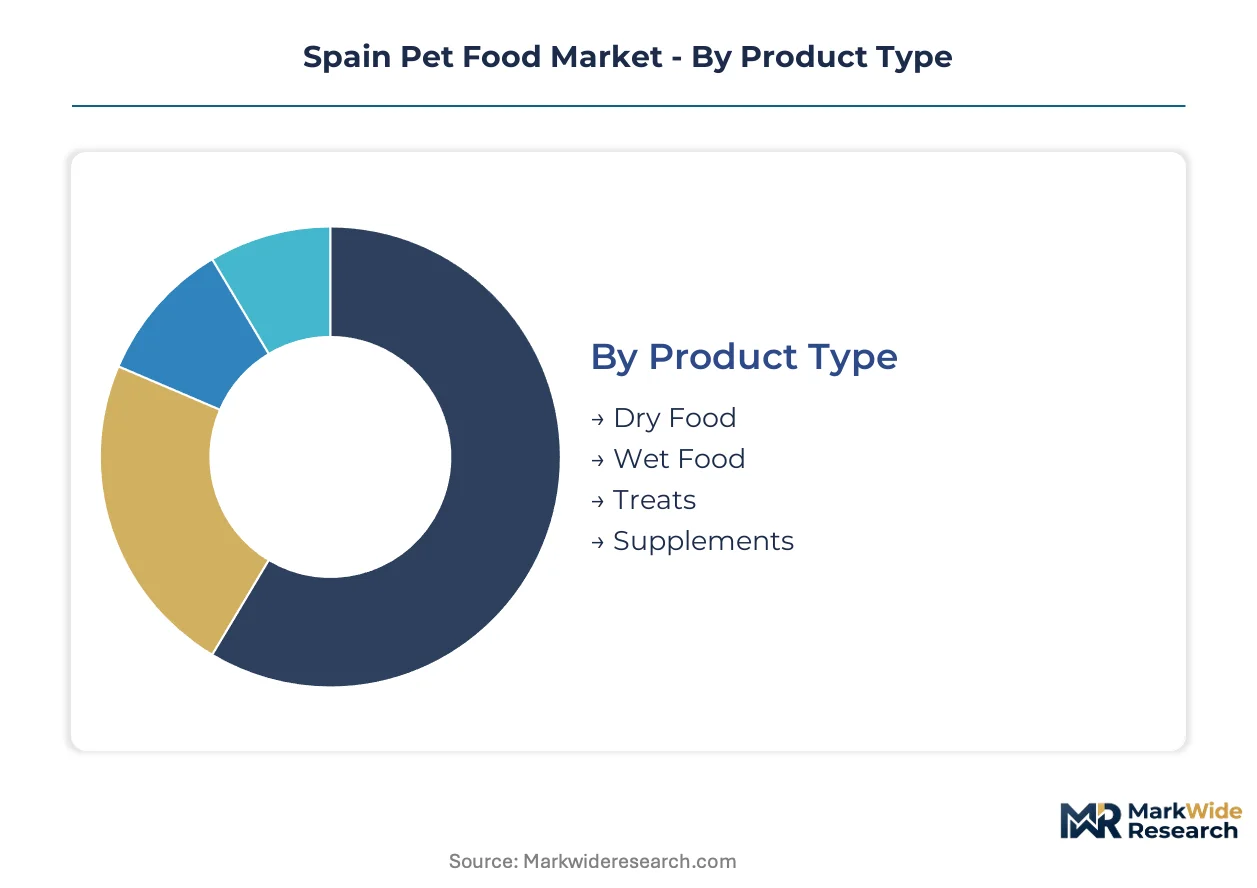
Segmentation in Spain's pet food market reveals how purchasing power, species-specific nutrition science, and channel access stratify demand across the Iberian Peninsula. Manufacturers configure formulation, packaging, and pricing architectures to match distinct owner profiles from Madrid apartment dwellers to coastal small-animal enthusiasts.
Product Type:
Customization intensity spans from commodity dry extrusions to functionally engineered wet formulations, with processing complexity and moisture content defining the standardization spectrum.
- Dry Food:Extruded kibble formulations deliver shelf-stable complete nutrition through thermal processing of cereal-protein matrices. Supermarket and e-commerce channels in Madrid and Barcelona concentrate volume throughput, with logistics efficiency and bulk purchasing habits sustaining dominance among multi-pet households.
- Wet Food:Canned or pouch-packaged high-moisture formulations preserve protein integrity through retort or cold-fill processing. Veterinary clinics and premium pet stores in Barcelona's Eixample district drive margin concentration, where palatability claims and prescription-grade positioning justify unit price premiums.
- Treats:Complementary functional snacks incorporate dental abrasives, joint-support compounds, or calming botanicals.
- Supplements:Targeted nutritional additives address specific metabolic deficiencies or life-stage requirements.
Leading the category by volume: Dry Food. Expanding most quickly: Treats.
Customer Type:
Species-specific metabolic requirements and owner spending propensity create distinct demand profiles across companion animal categories.
- Dog Owners:Canine formulations dominate absolute spend through larger portion sizes and veterinary-channel prescription penetration. Urban households in Madrid's Salamanca district concentrate premium wet food and functional treat demand, with humanization trends elevating per-animal expenditure above regional averages.
- Cat Owners:Feline nutrition emphasizes high-protein, low-carbohydrate formulations aligned with obligate carnivore metabolism. Barcelona's dense apartment housing sustains elevated cat ownership rates, with specialized retail and subscription channels capturing recurring dry and wet food purchases.
- Small Animal Owners:Rodent, rabbit, and bird formulations occupy niche volume positions.
- Exotic Pet Owners:Reptile, amphibian, and avian specialty feeds require species-precise nutritional engineering.
Commanding highest per-capita spend: Dog Owners. Gaining share fastest: Cat Owners.
Brand Positioning:
Price architecture separates mass-market penetration from margin capture through ingredient provenance and functional claim differentiation.
- Premium:Human-grade ingredient specifications, cold-pressed processing, and Mediterranean protein traceability define positioning. Catalonian manufacturers with integrated Iberian farming partnerships leverage EU Green Deal compliance for shelf placement advantages in specialty channels.
- Specialty:Veterinary-exclusive or prescription formulations bypass retail price competition through clinic network distribution. Chronic condition management protocols and telemedicine bundling in Madrid generate recurring revenue streams with elevated customer lifetime value.
- Mid-Range:Balanced nutrition at accessible price points targets mainstream supermarket channels.
- Budget:Commodity formulations prioritize cost minimization through conventional extrusion and bulk packaging.
Generating strongest margin pools: Premium. Climbing fastest: Specialty.
Distribution Channel:
Channel selection determines margin retention, customer data access, and regulatory compliance burden for Spanish manufacturers.
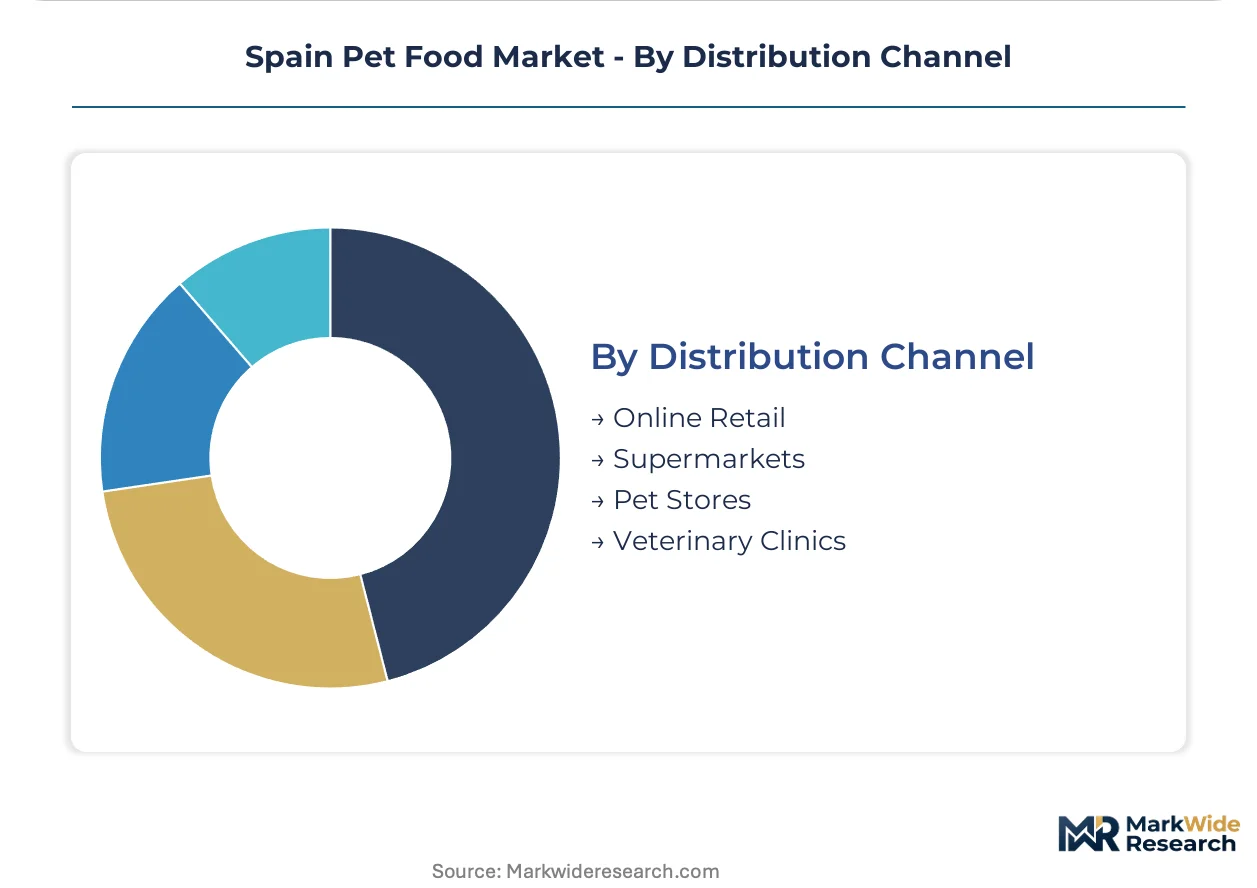
- Veterinary Clinics:Prescription-grade and therapeutic formulations distributed through credentialed professional networks. Barcelona and Madrid clinic consolidation creates concentrated gatekeeper power, with exclusive supplier agreements locking out retail competitors from chronic condition nutrition segments.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators displace supermarket bulk purchasing among time-constrained urban professionals. Subscription automation and telemedicine convergence in Madrid capture twelve-month purchase commitments with superior lifetime value metrics.
- Supermarkets:Mass-market dry food volume concentrates in Carrefour, Mercadona, and El Corte Inglés hypermarket networks.
- Pet Stores:Specialty retailers in Málaga and Cádiz provinces offer underpenetrated expansion terrain for premium treat and supplement specialists.
Retaining highest margins: Veterinary Clinics. Steepest expansion trajectory: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andalusian olive oil byproducts and Extremaduran pork processing residues anchor Spain's ingredient sourcing geography for pet food manufacturing. Regional consumption patterns diverge sharply between northern industrial corridors and southern coastal zones.
Madrid
Urban dog ownership concentrates in the Salamanca and Chamberí districts, where dual-income households drive prescription diet demand through veterinary clinic networks. The Spanish Agency for Food Safety and Nutrition maintains enforcement offices in the capital, streamlining EU 767/2009 compliance documentation for manufacturers. Madrid's logistics hub status enables cold-chain distribution of premium wet formulations to Castile-La Mancha satellite markets.
Catalonia
Barcelona's dense apartment housing sustains elevated cat ownership rates and specialized retail channel penetration. EFSA-aligned nutritional research clusters around the Universitat Autònoma de Barcelona, accelerating functional ingredient development. Cold-pressed dry food specialists in Girona province leverage proximity to French border crossings for German additive imports.
Andalusia
Málaga and Cádiz provinces present underpenetrated pet-store density for premium treat expansion. The Junta de Andalucía administers EU Common Agricultural Policy subsidies that stabilize local poultry meal supply costs. Coastal tourism corridors in Marbella generate seasonal demand spikes for convenience-oriented pet nutrition formats.
Basque Country
Industrial automation expertise in Bilbao supports packaging machinery upgrades for mono-material pouch transitions. Basque environmental regulations anticipate EU extended producer responsibility schemes with mandatory recycling quotas. Vitoria-Gasteiz hosts logistics platforms serving northern Spanish supermarket distribution networks.
Valencia
Rice cultivation residues from Albufera wetlands supply carbohydrate inputs for mid-tier dry food formulations. The Port of Valencia handles bulk soybean imports from South American suppliers subject to EU deforestation-free documentation requirements. Turia basin manufacturing plants serve Levantine coastal markets with lower cold-chain cost structures.
Spain Pet Food Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers reconfigure around EU Green Deal compliance deadlines. The market structure concentrates among multinational consumer goods conglomerates with Iberian manufacturing footprints and mid-sized Mediterranean specialists with regional ingredient integration. Three archetypes define competitive positioning: veterinary-channel exclusivity players, supermarket-volume scale operators, and artisanal cold-press specialists. M&A activity and sustainability certification investments constitute the primary competitive moves reshaping market share allocation.
Among multinational conglomerates, Mars Incorporated and Nestle Purina anchor the scale-driven tier with integrated European supply chains. Affinity Petcare SA occupies a distinct position as a Barcelona-based specialist emphasizing Mediterranean-sourced formulations. These three entities exemplify divergent strategic archetypes: Mars represents cross-border manufacturing leverage, Nestle Purina embodies veterinary-channel premiumization, and Affinity Petcare illustrates regional ingredient provenance positioning.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| General Mills Inc |
| Mars Incorporated |
| Alltech |
| Dechra Pharmaceuticals PLC |
| Nestle Purina |
| ADM |
| Schell & Kampeter Inc |
| Affinity Petcare SA |
| Others |
Value Network & Pricing Analysis
Veterinary-channel prescription bundling in Madrid and Barcelona forces manufacturers to absorb cold-chain logistics costs while maintaining margin discipline across supermarket and online tiers. This demand-side pressure reshapes how Spanish producers configure ingredient sourcing and packaging specifications to preserve profitability.
Pricing Analysis
Subscription-based veterinary bundling includes telemedicine consultations and automated replenishment, while unbundled supermarket transactions expose buyers to spot-price volatility. Three-tier pricing structure across premium, standard, and economy levels separates cold-pressed formulations with Mediterranean traceability from commodity extrusions. Cost compression in mid-tier dry food intensifies because Iberian pork meal prices fluctuate with agricultural cycles. Supermarket bulk purchasers exhibit highest price sensitivity; veterinary-exclusive subscribers demonstrate lowest sensitivity due to health-outcome framing.
Supply Chain Analysis
Single-source vulnerability sits with German and Dutch suppliers of joint-support compounds and dental-care enzymes. Geographic concentration centers on Spain for Iberian pork and poultry processing residues, France for cold-pressed equipment technology, and Brazil for deforestation-risk soy complexes. Raw material dependencies include Mediterranean fish meal, Andalusian olive oil byproducts, and imported specialty additives. Tariff exposure looms for South American soy imports under EU deforestation-free documentation mandates. Distribution runs through Madrid logistics hubs serving Castile-La Mancha, Barcelona cold-chain networks reaching Catalonia, and Valencia port facilities for Levantine coastal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Regulation 767/2009 feed labeling compliance erects a barrier-to-entry moat that rewards early documentation investment and penalizes late adopters with extended product registration delays.
For Market Incumbents: Anticipate margin compression from cold-pressing technology adoption costs by securing Iberian farming partnerships that satisfy EU Green Deal traceability requirements. Consolidate veterinary-channel relationships through exclusive chronic-condition formulation agreements before subscription-platform competitors scale. Prioritize ERP upgrades that integrate batch-level ingredient tracking to preempt regulatory documentation talent scarcity. For New Entrants and Emerging Players: Capture underpenetrated pet-store density in Málaga and Cádiz provinces where premium treat specialists face limited incumbent presence. Target Andalusian coastal corridors with mono-material pouch positioning that aligns with forthcoming EU extended producer responsibility schemes. Deploy direct-to-consumer telemedicine bundling to bypass consolidated Barcelona and Madrid clinic gatekeepers. For Investors and Strategic Acquirers: The window for entry favors mid-sized Mediterranean specialists with integrated Iberian protein sourcing and existing EU Green Deal audit trails. Long-term viability hinges on defensible documentation capabilities rather than scale economies alone. Monitor EU packaging waste rule implementation timelines as inflection indicator for recyclable material cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressing Technology Adoption | Preserves heat-sensitive probiotics for premium positioning against conventional extrusion competitors. |
| Veterinary-Exclusive Formulation Development | Locks recurring revenue through Madrid and Barcelona clinic network prescription protocols. |
| Mono-Material Pouch Transition | Secures retailer preferential placement under EU extended producer responsibility schemes. |
| Iberian Farming Partnership Integration | Generates Scope 3 emissions audit advantages over South American soy-dependent importers. |
| Telemedicine-Platform Convergence | Captures twelve-month customer lifetime value multiples exceeding traditional retail impulse purchases. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Spain pet food market analysis. Primary interviews with veterinary clinic procurement managers, pet-store category buyers, manufacturing plant directors, and Spanish Agency for Food Safety and Nutrition compliance officers combined with secondary validation from EU feed legislation databases and Iberian agricultural statistics. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Granularity-level modeling deployed product-type splits across dry, wet, treats, and supplements; customer-type differentiation between dog, cat, small animal, and exotic pet owners; brand-positioning tiers spanning premium, specialty, mid-range, and budget; and distribution-channel disaggregation across veterinary clinics, online retail, supermarkets, and pet stores. CAGRs derived from trend-line extrapolation adjusted for regulatory compliance cost absorption and sustainability-driven material substitution timelines. Forecast inputs incorporated EU Green Deal reporting deadline proximity and cold-pressing technology adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU packaging waste rule enforcement intensity and deforestation-free supply chain documentation requirements. Forecasts reflect assumptions about veterinary-channel consolidation continuity and Iberian protein cost stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Pillow Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
North America Pet Food Market
Pet Care Products
Dog Box Market
Pet Care Products
Therapeutic Diet for Pet Market
Pet Care Products
Pet Feeder Market
Pet Care Products
Dog Clippers Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Cat Harness Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Dog Food Market
Pet Care Products
PET Market
Pet Care Products
High Fiber Dog Food Market