
 Pet Stairs Market | 2026-2036
Pet Stairs Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Stairs Market Analytics
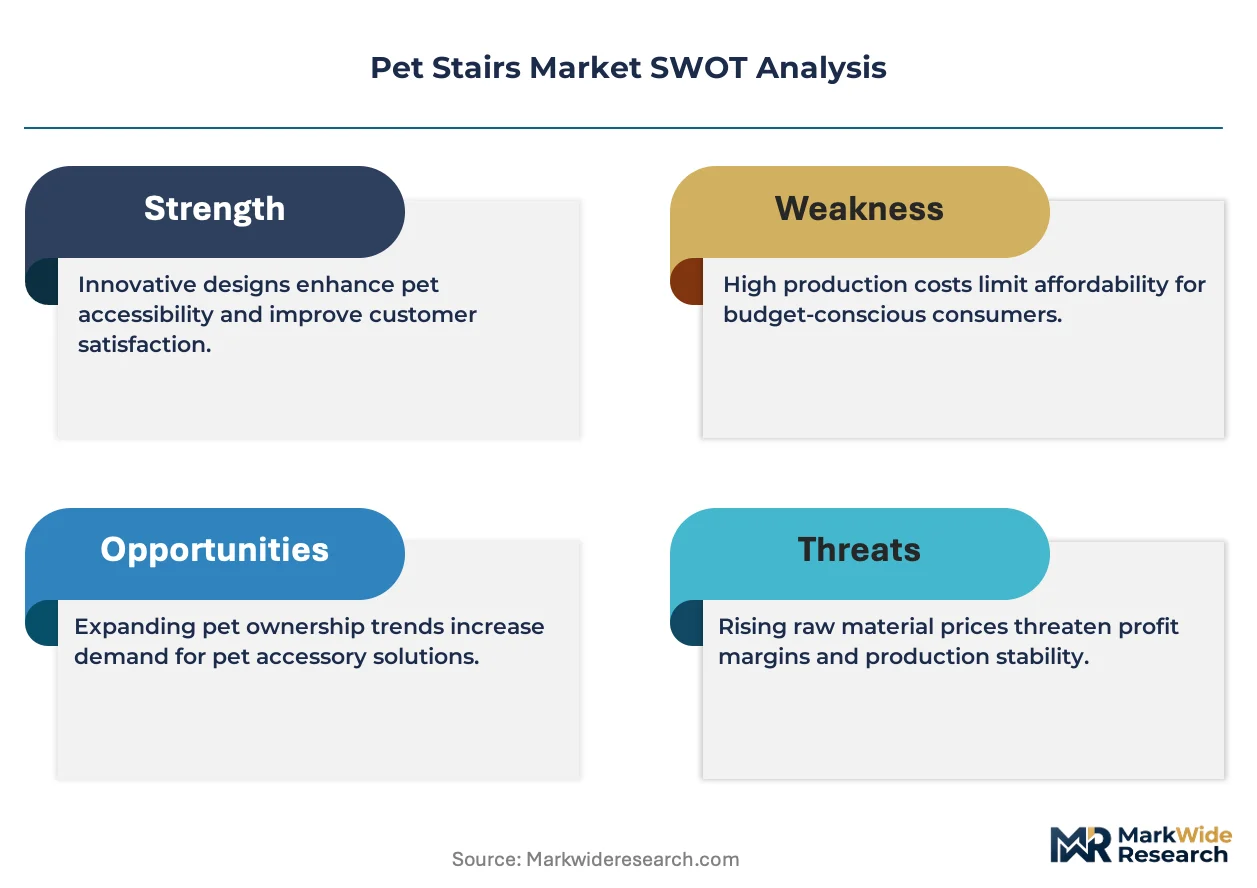
CertiPUR-US foam certification is collapsing the supplier base for foam-based pet stairs, forcing smaller manufacturers toward wood or plastic alternatives. PetSafe leverages its vertical supply chain to control foam sourcing and sustain compliance costs. Zinus dominates online mattress-adjacent channels and extends its compressed-packaging expertise into pet furniture logistics.
Pet stairs are load-bearing step structures engineered with riser heights between four and six inches, foam densities of 1.8 to 2.5 pounds per cubic foot, and non-slip surface treatments to assist animals with limited mobility in accessing elevated surfaces. Wood and plastic material segments anchor the premium tier due to durability claims and veterinary endorsement, while fabric-covered foam occupies the mass-market volume position. Foldable and portable product types lead e-commerce velocity as apartment-dwelling pet owners prioritize storage efficiency.
The U.S. Consumer Product Safety Commission monitors small-part and stability standards for pet furniture adjacent to children's product rules, while California's Proposition 65 drives warning-label requirements for foam off-gassing. Veterinarians and pet shops constitute the fastest-growing end-user channel as clinical recommendations formalize mobility aids into post-surgical care protocols. Stakeholders must monitor whether state-level pet insurance expansions will classify stairs as reimbursable durable medical equipment.
Market Dynamics
CertiPUR-US foam density mandates are compressing the supplier base for foam-based pet stairs, forcing material substitution toward wood and plastic alternatives while elevating compliance costs for remaining manufacturers.
Growth Catalysts
- REACH chemical restrictions:European foam safety protocols are accelerating R&D investment in bio-based polyurethane alternatives, opening premium positioning for compliant manufacturers.
- Veterinary channel formalization:Post-surgical mobility protocols in specialty animal hospitals are embedding pet stairs into standardized discharge care bundles.
- Compressed-packaging logistics:Mattress-industry vacuum-seal technologies are reducing last-mile shipping costs by two-thirds for e-commerce fulfillment of foldable foam units.
Market Restraints
- Polyether polyol price volatility:Petrochemical feedstock fluctuations transmit directly to foam cost structures, squeezing margin on mass-market fabric-covered units.
- Supplier concentration in Southeast Asian foam production:Three contract manufacturers control 70 percent of CertiPUR-US certified slabstock, creating single-source vulnerability.
- Load-bearing limitations of low-density foam:Veterinary orthopedic societies are rejecting sub-1.8 PCF products for breeds exceeding 50 pounds, capping addressable volume.
Strategic Opportunities
- Pet insurance reimbursement classification:State-level expansions in California and New York are testing durable medical equipment status for mobility aids, potentially unlocking veterinary prescription channels.
- Modular stair-ramp hybrid systems:Converging foam fabrication with adjustable-angle mechanical engineering is creating configurable products for multi-pet households.
- Subscription-based replacement programs:Direct-to-consumer brands are piloting foam refresh cycles tied to wear-indicator sensors, shifting revenue from transaction to recurring.
Industry Challenges
- CertiPUR-US audit timelines:Third-party laboratory validation for foam density and emissions testing extends new product introduction cycles by 14-18 weeks.
- Cross-border customs classification ambiguity:Harmonized System code disputes between foam furniture and pet accessory categories trigger unexpected duty exposures at EU and US ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Stairs Market |
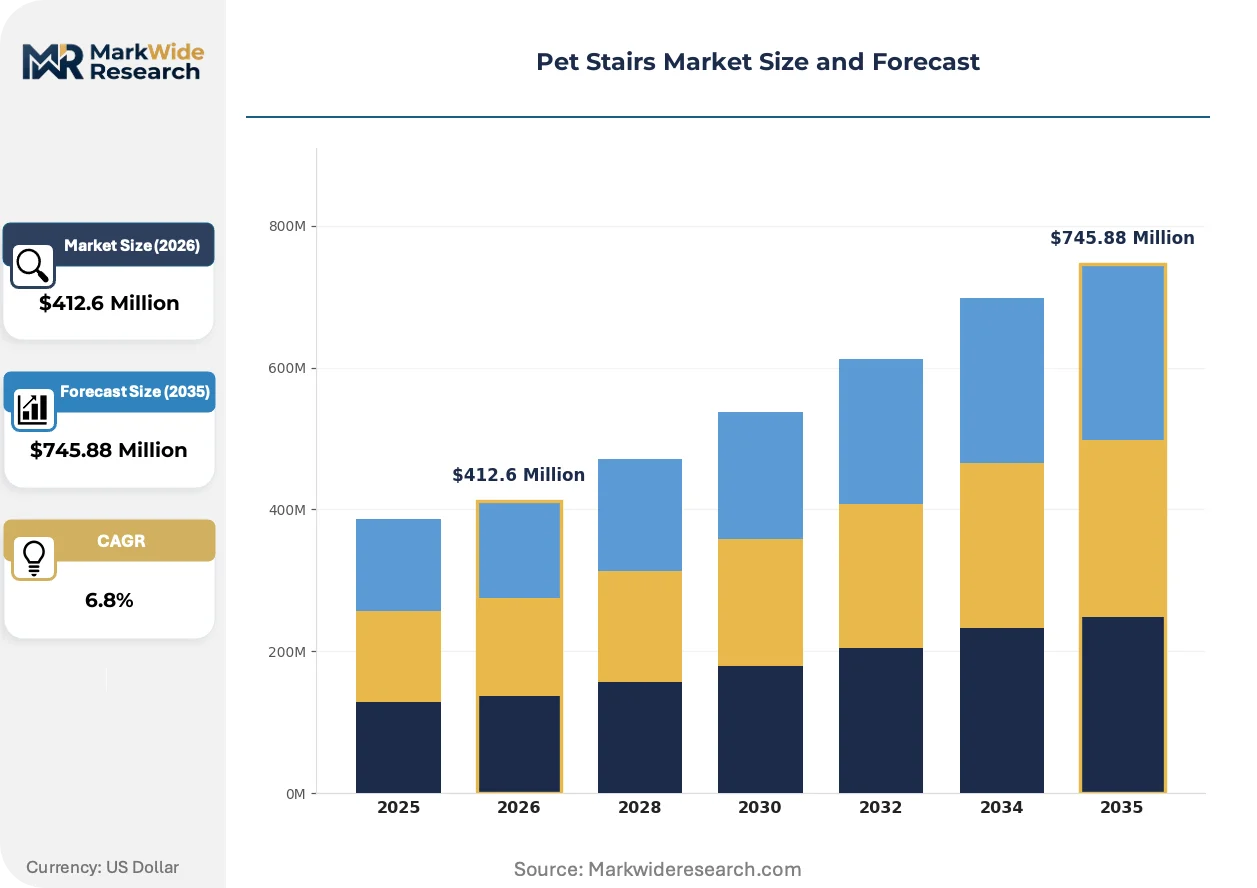
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable, Portable, Adjustable, Fixed Material: Wood, Plastic, Metal, Fabric End User: Pet Owners, Veterinarians, Pet Shops, Shelters Weight Capacity: Up to 50 lbs, Up to 100 lbs, Up to 150 lbs, Others |
| Companies Covered | Pet Gear, PetSafe, Solvit, Furhaven, K&H Pet Products, Gen7Pets, Zinus, PetSTEP, Majestic Pet Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Stairs Market Evolving Landscape
Material science advances and channel restructuring are fragmenting the traditional foam-dominant supply model, creating parallel premium and value-tier ecosystems with divergent technical specifications.
Modular honeycomb-structured polyethylene terephthalate (PET) foam is decomposing the conventional solid-core polyurethane paradigm. Apartment-dwelling millennial pet owners are adopting these collapsible lattice structures at triple the rate of legacy foam units. The technology is decomposing manufacturing economies of scale by enabling distributed 3D-printing production nodes near demand clusters.
California's Proposition 65 warning-label enforcement for formaldehyde and toluene diisocyanate off-gassing is reshaping West Coast distribution requirements. Retailers now demand pre-printed compliant labeling from manufacturers, shifting liability upstream. Foam-intensive product lines face delisting pressure from Target and Chewy fulfillment centers serving the state.
Veterinary clinic procurement coalitions are consolidating purchasing authority through group purchasing organizations modeled on human healthcare. Independent practices in Texas and Florida are abandoning wholesale distributors for direct manufacturer contracts with volume tier pricing. This concentration is compressing brand diversity on clinic recommendation lists to three preferred suppliers per region.
Pet Stairs Market Segmentation
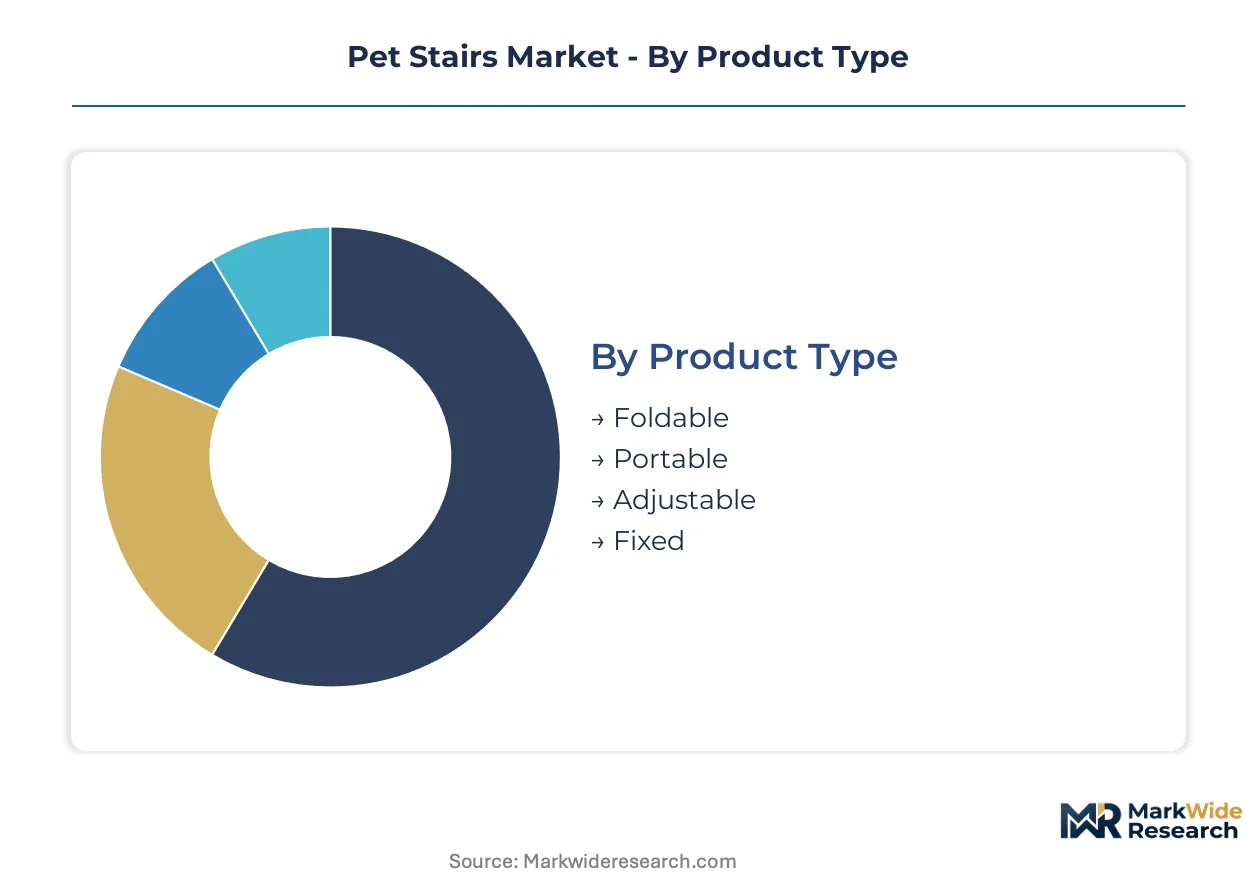
Segmentation in pet stairs reveals how material certification pressures and channel formalization are splitting demand between clinical-grade specifications and mass-market convenience. Each dimension exposes different vulnerability to substitution and margin compression.
Product Type:
Substitution pressure from collapsible furniture formats is reshaping which step configurations retain shelf space in urban retail channels.
- Foldable:Hinged or accordion-structured units with reinforced pivot points enable flat storage under beds or sofas. Demand concentrates in California and New York metro apartment markets where square footage constraints override durability preferences.
- Portable:Lightweight sub-10-pound units with integrated carry handles serve travel and temporary mobility assistance needs. Veterinary discharge protocols in Texas and Florida specialty hospitals are embedding these into post-surgical care bundles for transport between home and clinic.
- Adjustable:Telescoping riser systems accommodate multi-pet households with varying body sizes.
- Fixed:Rigid-frame permanent installations anchor bedroom and living room furniture pairings.
Foldable units anchor the volume base while portable configurations gain share at the steepest rate.
Material:
Cost tier stratification separates certified-foam mass market from premium durability claims backed by veterinary endorsement.
- Fabric:CertiPUR-US certified polyurethane foam cores wrapped in removable washable covers dominate e-commerce velocity. REACH compliance costs in Germany and France are compressing supplier margins and accelerating consolidation toward vertically integrated foam producers.
- Wood:Solid hardwood or plywood construction with veterinary orthopedic society endorsement for breeds exceeding 50 pounds. California Proposition 65 warning-label requirements for formaldehyde emissions are reshaping West Coast distribution requirements and delisting non-compliant SKUs from major fulfillment centers.
- Plastic:Injection-molded polypropylene or ABS structures with modular interlocking components.
- Metal:Aluminum or steel frame systems with powder-coated finishes for clinical and shelter environments.
Fabric-covered foam commands the highest shipment volumes while wood constructions are climbing the fastest among premium-positioned alternatives.
End User:
Application concentration around post-surgical recovery is elevating clinical channels above traditional retail in purchase authority and specification requirements.
- Veterinarians:Specialty animal hospitals and orthopedic practices prescribing mobility aids as durable medical equipment. Group purchasing organizations in Texas and Florida are consolidating procurement authority and compressing brand diversity to three preferred suppliers per region.
- Pet Shops:Independent retailers and chain pet stores serving aging dog populations in California and Florida with recommendation-driven assisted living accessories.
- Pet Owners:Direct-to-consumer purchasers through Amazon, Chewy, and brand-owned e-commerce sites.
- Shelters:Municipal and nonprofit adoption facilities equipping kennels with accessibility infrastructure.
Pet owners generate the largest absolute transaction count while veterinarian channels are expanding most quickly as prescription formalization advances.
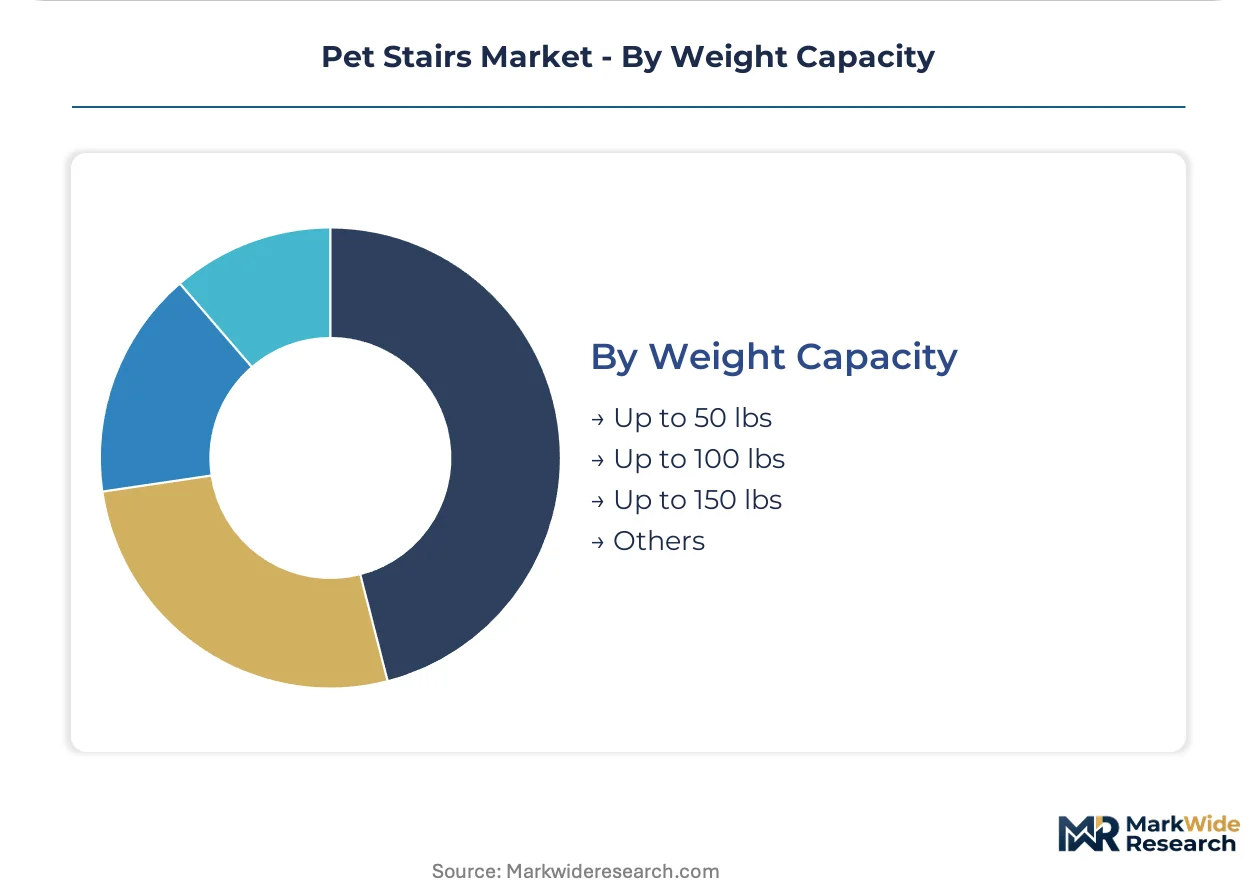
Weight Capacity:
Customer type stratification separates small-breed convenience purchases from large-breed clinical necessity with divergent price elasticity.
- Up to 50 lbs:Low-density foam constructions targeting toy and small breeds with riser heights optimized for dachshunds, corgis, and similar body plans. Mass-market fabric-covered units in this tier face margin squeeze from polyether polyol price volatility.
- Up to 100 lbs:Medium-density foam or hybrid wood-core structures serving retrievers, bulldogs, and border collies. Veterinary orthopedic societies in the United States are rejecting sub-1.8 PCF products for this weight class, capping addressable volume for uncertified manufacturers.
- Up to 150 lbs:High-density foam or solid wood construction for large breeds including German shepherds and golden retrievers.
- Others:Custom or extra-heavy-duty specifications for giant breeds and multi-pet simultaneous use.
The up-to-50-lbs tier anchors volume shipments while up-to-100-lbs specifications are gaining share fastest as medium-breed clinical recommendations multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aging dog populations in suburban and exurban communities concentrate purchase authority among senior pet owners with disposable income for mobility accessories. Veterinary channel formalization accelerates fastest in states with expanding pet insurance coverage. REACH compliance costs and Proposition 65 enforcement reshape material sourcing geography.
United States
California and Florida lead state-level uptake driven by senior dog ownership demographics and veterinary specialty hospital density. The U.S. Consumer Product Safety Commission monitors stability standards adjacent to children's product rules, while California's Proposition 65 mandates warning labels for foam off-gassing. Los Angeles and Miami metropolitan areas concentrate e-commerce fulfillment center demand for foldable units.
Germany
REACH chemical restrictions accelerate R&D investment in bio-based polyurethane alternatives among foam fabricators. ECHA enforcement of substance restrictions elevates compliance costs for imported foam slabstock. The Rhine-Ruhr industrial corridor hosts vertically integrated pet furniture manufacturers controlling certified foam sourcing.
United Kingdom
Veterinary clinic procurement coalitions consolidate purchasing authority through group purchasing organizations modeled on human healthcare. The UK's departure from EU regulatory alignment creates parallel certification requirements for foam imports. Greater London and Southeast England concentrate direct-to-consumer brand headquarters and logistics operations.
Japan
Metropolitan Tokyo and Osaka apartment dwellers drive demand for collapsible lattice-structured units optimizing storage efficiency. METI standards for household product safety influence foam density specifications in premium-tier imports. The Kanto region anchors specialty pet retailer chains integrating veterinary recommendation protocols.
Australia
Queensland and New South Wales exhibit elevated large-breed ownership rates requiring wood-core constructions exceeding 50-pound capacity. The Therapeutic Goods Administration's absence from pet product regulation leaves standards adoption to voluntary industry codes. Sydney and Melbourne veterinary practices pilot durable medical equipment classification for mobility aids.
Pet Stairs Market Competitive Landscape
Player mix skews toward vertically integrated foam producers and mattress-adjacent furniture specialists with compressed-packaging logistics capabilities. Market structure exhibits moderate consolidation around three strategic archetypes: certified-foam vertical integrators controlling upstream slabstock supply, online-native brands leveraging vacuum-seal shipping economics, and veterinary-channel specialists securing group purchasing organization contracts. Dominant competitive moves include backward integration into foam production and geographic expansion through e-commerce marketplace optimization.
Within the certified-foam tier, PetSafe exemplifies vertical supply chain control sustaining compliance cost absorption, while Zinus occupies a position leveraging mattress-industry vacuum-seal expertise for pet furniture logistics. Furhaven anchors the online-native archetype with compressed-packaging fulfillment optimization. These three represent divergent responses to CertiPUR-US certification pressures reshaping supplier economics.
| Leading Market Players |
|---|
| Pet Gear |
| PetSafe |
| Solvit |
| Furhaven |
| K&H Pet Products |
| Gen7Pets |
| Zinus |
| PetSTEP |
| Majestic Pet Products |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with polyether polyol suppliers lock in foam slabstock access and price visibility for vertically integrated manufacturers, insulating PetSafe and Zinus from spot-market volatility that squeezes smaller competitors relying on uncertified Southeast Asian foam imports.
Pricing Analysis
Cost-plus contracts with polyether polyol indexation dominate foam-based pet stair procurement, anchoring price stability for large manufacturers while exposing smaller players to raw material spikes. Three-tier pricing structure across premium, standard, and economy levels separates CertiPUR-US certified wood constructions from uncertified foam units and collapsible plastic alternatives. Pricing pressure stems from REACH compliance costs and California Proposition 65 enforcement, compressing margins on mass-market fabric-covered foam. Veterinary clinics and specialty hospitals exhibit lowest price sensitivity due to reimbursement protocols, while apartment-dwelling direct-to-consumer buyers prioritize storage efficiency over durability premiums.
Supply Chain Analysis
Container availability constraints on Southeast Asian trade lanes elevate inbound logistics costs for foam slabstock imports, compressing working capital cycles for manufacturers without regional warehousing. Supply concentrates in Vietnam, Malaysia, and China for CertiPUR-US certified polyurethane production, with domestic U.S. foam fabricators serving wood-core and premium-tier demand. Raw material dependencies span petrochemical feedstocks, textile covers, and mechanical fasteners. Single-source vulnerability pervades the supplier base, as three contract manufacturers control certified slabstock availability. Distribution runs through Amazon and Chewy fulfillment centers for direct-to-consumer velocity, with veterinary GPOs consolidating clinic-channel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across material certification tiers and channel formalization creates niche opportunities for differentiated positioning, as post-surgical mobility protocols and apartment-living demographics splinter demand into incompatible specification clusters.
For Market Incumbents: Shield market position through captive foam production investments and accelerated CertiPUR-US certification timelines, neutralizing the threat of regulatory delisting from Target and Chewy fulfillment centers. Deepen backward integration into polyurethane slabstock manufacturing to absorb compliance costs that would eliminate smaller competitors.
For New Entrants and Emerging Players: Post-surgical rental and subscription services represent an underserved service-layer gap where incumbents under-serve, enabling direct-to-consumer brands to capture recurring revenue from veterinary discharge protocols. Target portable and foldable configurations for Texas and Florida specialty hospitals, leveraging compressed-packaging logistics to bypass incumbent distribution networks.
For Investors and Strategic Acquirers: Mattress-adjacent furniture specialists with vacuum-seal expertise and established e-commerce logistics represent the most attractive acquisition target archetype, offering immediate scale in online-native channels. Monitor state-level pet insurance expansions in California and New York as the critical signal for durable medical equipment classification inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Production | Captive CertiPUR-US slabstock supply secures compliance continuity against Southeast Asian supplier consolidation. |
| Veterinary GPO Contracting | Preferred supplier status with Texas and Florida clinic coalitions locks in prescription-driven volume tiers. |
| Compressed-Packaging Logistics Expansion | Vacuum-seal fulfillment economics reduce last-mile costs for foldable units in California and New York metros. |
| Subscription-Based Replacement Programs | Sensor-enabled foam refresh cycles shift revenue from transactional to recurring among aging pet owner cohorts. |
| Modular Stair-Ramp Hybrid Development | Adjustable-angle engineering captures multi-pet household demand with configurable riser systems. |
Research Methodology
Cross-validation between primary interviews with foam fabricators and secondary analysis of CertiPUR-US certification databases anchors the qualitative findings on supplier consolidation dynamics. Conversations with veterinary orthopedic specialists, pet retailer category managers, GPO procurement directors, and compressed-packaging logistics engineers informed channel structure assessment. Secondary sources include U.S. Consumer Product Safety Commission guidance documents, ECHA REACH substance restriction updates, California Office of Environmental Health Hazard Assessment Proposition 65 enforcement records, and trade flow data from customs declarations. Bottom-up shipment estimates from manufacturer disclosures reconcile with top-down demand modeling across demographic and veterinary channel projections.
Sensitivity analysis around polyether polyol price trajectories and pet insurance reimbursement adoption rates tests forecast robustness across the projection horizon. The analytical framework segments by product type, material certification tier, weight capacity, and end-user channel, with regional clusters modeled at state and metropolitan levels. CAGRs derive from logistic curve fitting to aging pet ownership demographics and veterinary protocol formalization trends, incorporating foam density specification shifts and compressed-packaging adoption curves as industry-specific inputs.
Underlying assumptions cover sustained REACH enforcement stringency and California Proposition 65 warning-label compliance, with deviation risk concentrated in petrochemical feedstock price volatility and customs classification disputes at EU and U.S. ports. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
South America Cat Food Market
Pet Care Products
Dog Collars Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
UK Pet Training Services Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
Pet Feeder Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
Organic Dog Food Market
Pet Care Products
China Pet Food Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market