
 Cat Food Toppers Market | 2026-2036
Cat Food Toppers Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Food Toppers Market Outlook
Premium human-grade specification is bifurcating the Cat Food Toppers landscape into mass-market and super-premium tiers. Mars Incorporated leverages its global supply chain infrastructure to sustain cost advantages across wet and dry topper lines. Nestlé Purina Petcare anchors North American distribution through veterinary and mass retail channels. Stella & Chewy's differentiates via freeze-dried raw formulations that command shelf-space premiums in independent pet specialty.
Cat food toppers comprise supplemental meal enhancers—wet, dry, sauce, or gravy formats—formulated with protein contents typically exceeding 50 percent on a dry-matter basis for meat-based variants, designed to improve palatability, moisture intake, or nutritional completeness of base diets. Wet toppers and gravy formats occupy the fastest-expanding margin pools as hydration-conscious owners shift from standalone kibble feeding. Grain-free ingredient positioning competes with functional vegetable inclusions for shelf-space in pouches and tubs, though meat-first formulations sustain the dominant revenue share across all packaging configurations.
The FDA's Food Safety Modernization Act preventive controls for animal food and the Association of American Feed Control Officials nutrient profiles govern product formulation, labeling, and facility compliance across domestic manufacturing. State-level feed control officials in California, Texas, and New York enforce additional registration and inspection protocols that shape regional market access requirements. Stakeholders must monitor evolving clean-label enforcement thresholds and state-level raw-food handling restrictions that will determine which ingredient and processing investments align with tomorrow's compliance landscape.
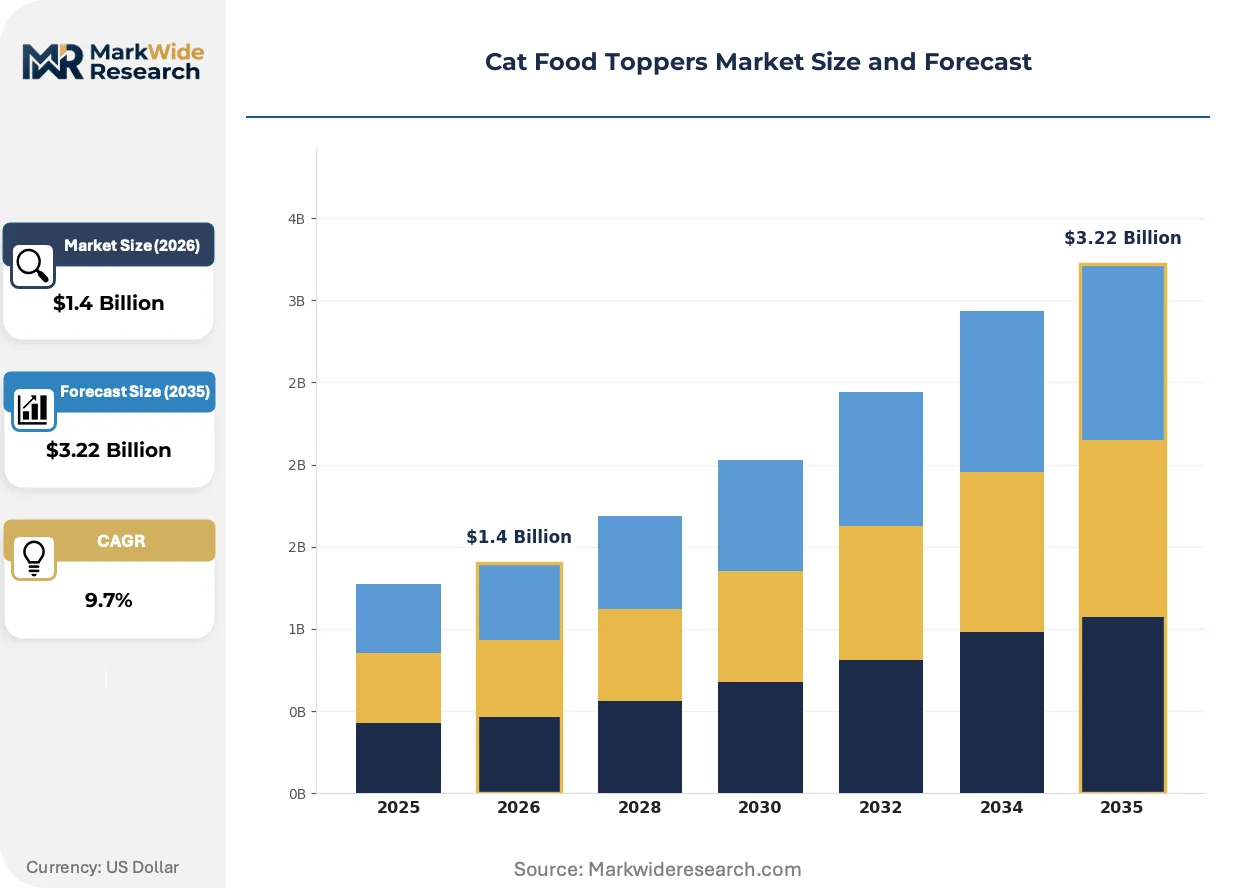
Market Dynamics
The humanization of pet diets is fragmenting the Cat Food Toppers landscape into functional, indulgence, and therapeutic tiers, with millennial urban households driving premiumization through ingredient transparency demands and subscription purchasing patterns.
Growth Catalysts
- FSMA Preventive Controls:The FDA's Food Safety Modernization Act mandates hazard analysis and risk-based preventive controls for animal food facilities, elevating manufacturing standards that premium brands leverage as competitive differentiation.
- Freeze-Drying Technology:Low-temperature dehydration preserves raw nutritional integrity while extending shelf stability, enabling raw-format toppers to penetrate mass retail channels previously closed to refrigerated products.
- Urban Pet Density:Metropolitan household concentration in cities like New York, Los Angeles, and Chicago concentrates demand for compact-format, high-moisture toppers that address hydration concerns in indoor-only cat populations.
Market Restraints
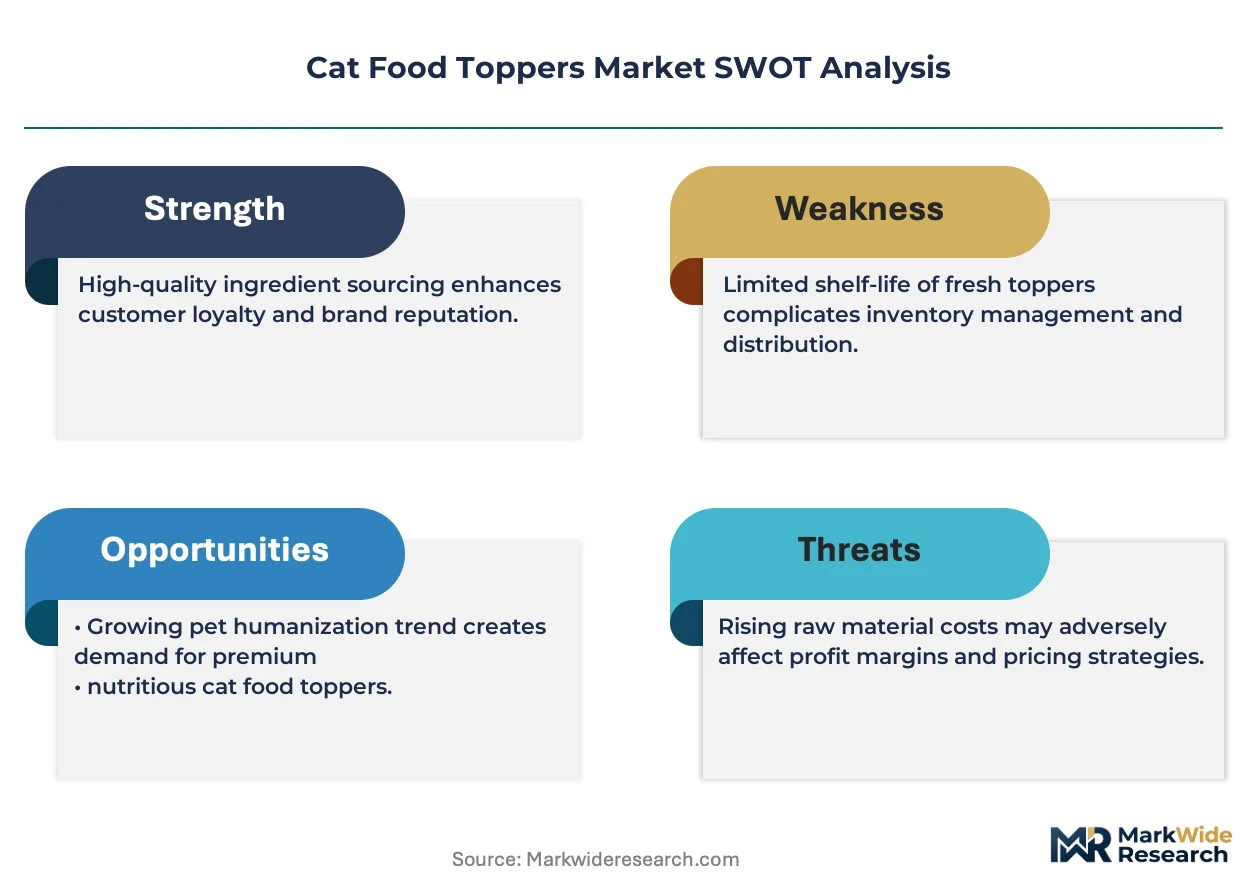
- Animal Protein Input Volatility:Wild-caught fish and free-range poultry supply fluctuations create margin compression for human-grade formulations dependent on consistent premium sourcing.
- State-Level Raw Food Restrictions:California, Texas, and New York enforce divergent pathogen handling and labeling protocols that fragment distribution economics for raw and freeze-dried product lines.
- Homemade Substitute Prevalence:Owner-prepared cooked chicken, fish, and broth alternatives capture price-sensitive demand, particularly among multi-cat households in suburban markets.
Strategic Opportunities
- Veterinary Channel Expansion:Therapeutic toppers addressing renal support, weight management, and digestive health can penetrate clinic-exclusive distribution networks with prescription-adjacent positioning.
- AAFCO Nutrient Profile Convergence:The Association of American Feed Control Officials' evolving complete-and-balanced definitions create openings for toppers formulated as meal replacements rather than supplements.
- Direct-to-Consumer Subscriptions:Auto-replenishment models bypass slotting fee barriers in brick-and-retail while capturing lifetime value through personalized feeding algorithm recommendations.
Industry Challenges
- Clean-Label Enforcement Thresholds:Absence of standardized definitions for "human-grade," "natural," and "holistic" claims exposes manufacturers to class-action litigation risk and state attorney general scrutiny.
- Cold Chain Integration Complexity:Fresh and refrigerated topper formats require temperature-controlled logistics investments that conflict with existing dry pet food distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Food Toppers Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Toppers, Dry Toppers, Sauces, Gravy Ingredient Type: Meat, Fish, Vegetables, Grain Free Packaging Type: Pouches, Cans, Bottles, Tubs Target Animal: Cats, Kittens, Senior Cats, Indoor Cats |
| Companies Covered | Mars Incorporated, Nestlé Purina Petcare, Blue Buffalo Co., Ltd., Hill's Pet Nutrition, Stella & Chewy's, The Honest Kitchen, Merrick Pet Care, Inc., Nature’s Variety, WellPet LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Food Toppers Market Strategic Shifts
Formulation science and channel architecture are converging to redefine how supplemental nutrition reaches feline consumers, with processing methods and purchasing interfaces undergoing simultaneous transformation.
High-pressure processing (HPP) is decomposing the traditional trade-off between raw nutritional bioavailability and pathogen elimination. Premium manufacturers adopt HPP for refrigerated topper lines targeting urban households with veterinary-guided feeding protocols. This non-thermal pasteurization method compresses the cost gap between conventional cooked formats and untreated raw alternatives.
The FDA's evolving enforcement of Food Safety Modernization Act preventive controls is tightening facility registration and supply chain documentation requirements. Small-batch manufacturers face capital barriers for hazard analysis verification and supplier approval systems. Independent pet specialty retailers respond by consolidating vendor bases toward FSMA-compliant suppliers with documented preventive control implementation.
Subscription-based replenishment is displacing episodic retail purchasing among millennial cat owners. E-commerce platforms capture recurring revenue through algorithm-driven portion recommendations and flavor rotation protocols. This behavioral shift concentrates most visibly in coastal metropolitan markets where delivery density optimizes logistics economics and veterinary telehealth services reinforce feeding guidance continuity.
Cat Food Toppers Market Segmentation
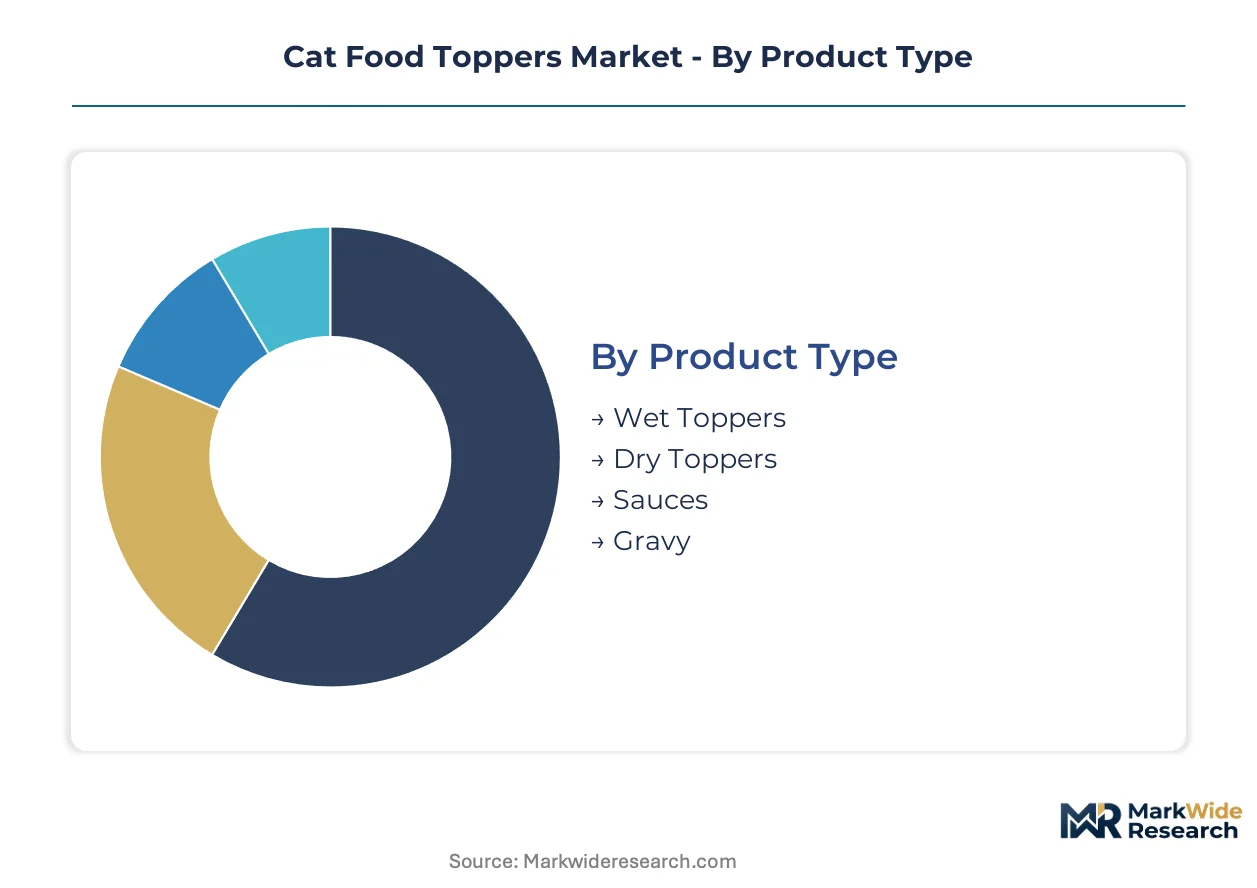
Segmentation in cat food toppers reveals how hydration priorities, ingredient sourcing constraints, and life-stage nutritional requirements fragment purchasing behavior across distinct product configurations. Manufacturers align R&D investments and packaging formats against these divides to capture margin concentration in premium urban households.
Product Type:
Wet toppers and gravy formats command the deepest margin pools as moisture-conscious owners abandon standalone dry feeding, while dry toppers retain volume leadership through shelf stability and lower unit economics.
- Wet Toppers:High-moisture pouches and tubs typically deliver protein exceeding 50 percent on a dry-matter basis. Demand concentrates in metropolitan United States households with indoor-only cats where veterinary guidance emphasizes hydration support.
- Gravy:Pourable sauce formulations enhance palatability of base kibble without textural replacement. Urban subscription purchasers in New York and Los Angeles drive fastest adoption through e-commerce auto-replenishment models.
- Dry Toppers:Freeze-dried and dehydrated formats extend shelf stability without refrigeration. Mars Incorporated and Nestlé Purina Petcare dominate mass retail distribution through veterinary and grocery channels.
- Sauces:Concentrated flavor enhancers in squeeze bottles target portion-controlled feeding. Functional positioning around digestive health and renal support expands clinic-adjacent placement.
The dominant share belongs to Wet Toppers, while Gravy is closing the gap fastest.
Ingredient Type:
Cost tier stratification separates commodity protein inputs from certified human-grade sourcing, with meat-first formulations anchoring premium positioning and grain-free claims competing against functional vegetable inclusions for shelf space.
- Meat:Chicken, turkey, and beef formulations sustain the largest revenue footprint across all packaging configurations. Free-range and human-grade specifications command 40-60 percent price premiums in independent pet specialty.
- Fish:Wild-caught salmon, tuna, and whitefish variants target omega-3 positioning for coat and cognitive health. Supply volatility in North Atlantic and Pacific fisheries creates margin compression for consistent premium sourcing.
- Grain Free:Absence of wheat, corn, and soy appeals to allergy-sensitive households. AAFCO nutrient profile compliance challenges require careful amino acid supplementation.
- Vegetables:Pumpkin, sweet potato, and carrot inclusions address fiber and digestive positioning. Functional claims around hairball control and weight management expand veterinary channel penetration.
Meat retains volume leadership, though Fish is expanding most quickly in coastal metropolitan markets.
Packaging Type:
Format selection reflects trade-offs between portion control convenience, sustainability signaling, and cold chain infrastructure requirements, with flexible pouches displacing rigid containers in subscription-heavy channels.
- Pouches:Lightweight flexible film reduces shipping costs and storage footprint. Millennial urban subscribers in Chicago and Seattle favor single-serve portions for freshness and waste reduction.
- Tubs:Reclosable plastic containers support multi-cat households and larger portion requirements. Independent pet specialty retailers allocate prime shelf space to premium tub formats.
- Cans:Aluminum packaging retains recycling credibility and thermal processing compatibility. Mass retail and veterinary channels maintain strong can format presence for wet toppers.
- Bottles:Squeeze and pump dispensers dominate sauce and gravy applications. Portion precision appeals to weight-management and therapeutic feeding protocols.
Pouches hold the dominant position, while Tubs are gaining share fastest in multi-cat suburban households.
Target Animal:
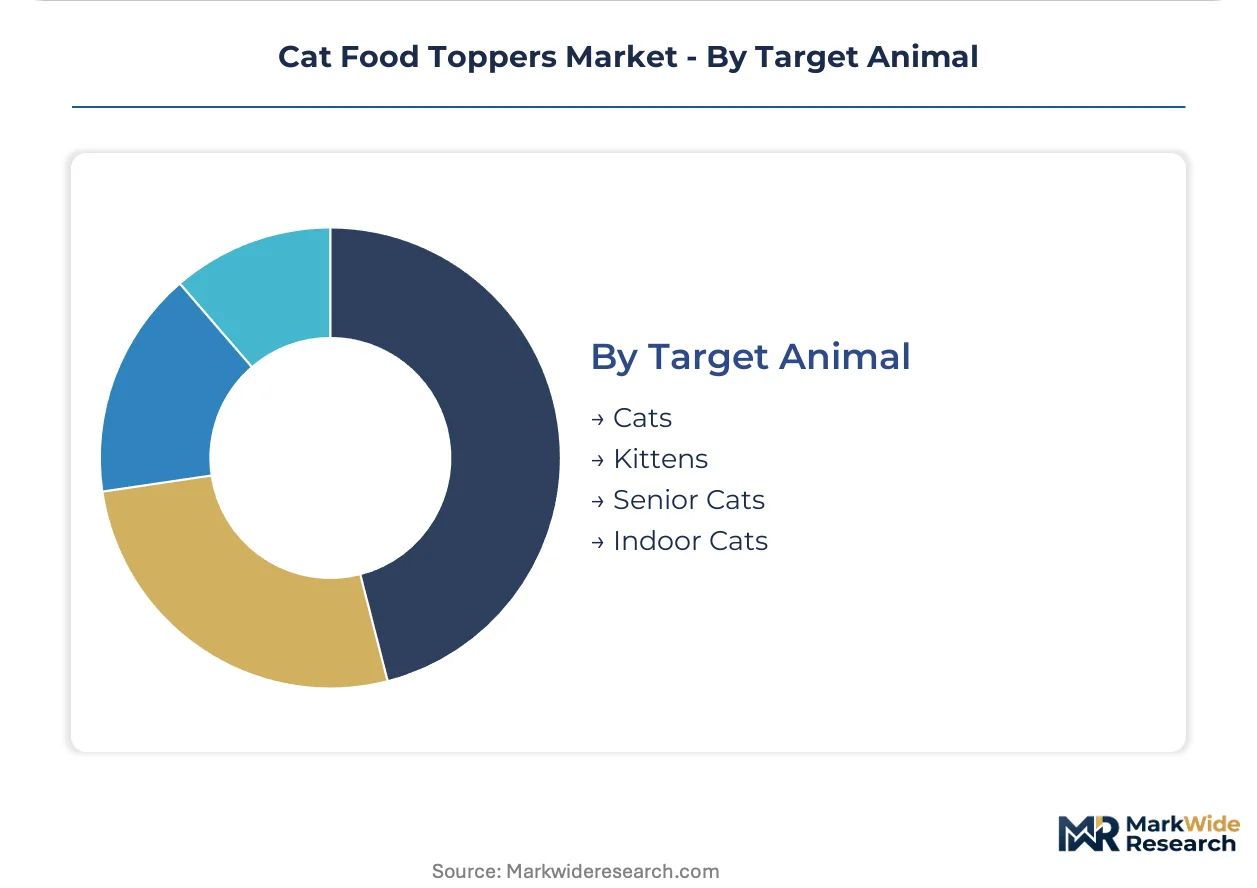
Life-stage and lifestyle segmentation directs formulation specificity around caloric density, texture adaptability, and therapeutic nutrient profiles, with senior and indoor cat targeting driving premiumization.
- Cats:General adult formulations balance palatability enhancement with complete nutrition compatibility. Mass market volumes concentrate in grocery and mass retail channels.
- Indoor Cats:Reduced calorie density and hairball control positioning address sedentary metabolism. Metropolitan United States households with exclusively indoor populations drive premium pricing tolerance.
- Senior Cats:Renal support, joint health, and enhanced digestibility formulations target veterinary-guided feeding. Prescription-adjacent positioning opens clinic-exclusive distribution networks.
- Kittens:Higher protein and fat content supports growth-phase nutritional requirements. Smaller portion formats and texture gradation appeal to first-time millennial adopters.
The dominant share belongs to general Cat formulations, though Senior Cats is climbing the fastest as veterinary channel expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cat food topper manufacturing concentrates in the United States, where FDA-regulated facilities cluster around Midwestern protein processing corridors and coastal distribution hubs serve subscription-heavy urban markets. Facility investments in freeze-drying and high-pressure processing equipment concentrate near Chicago, Omaha, and Kansas City to leverage beef and poultry supply chains.
United States
Metropolitan households in New York, Los Angeles, and Chicago drive demand for high-moisture toppers addressing indoor cat hydration. The FDA's FSMA preventive controls mandate hazard analysis for animal food facilities, elevating compliance costs that favor scaled manufacturers. Omaha, Nebraska anchors wet topper production with direct rail access to Midwestern rendering and meat processing plants.
Germany
Pet humanization trends in Berlin, Munich, and Hamburg sustain premium-tier demand for grain-free and functional vegetable formulations. EFSA pet food safety guidelines and national feed regulations under the German Feed Act shape ingredient sourcing and labeling requirements. The Bavarian industrial corridor hosts specialized drying equipment manufacturers supplying European freeze-dried topper producers.
Japan
Tokyo and Osaka metropolitan areas concentrate ownership of indoor-only cats with veterinary-guided feeding protocols emphasizing moisture supplementation. METI standards for pet food quality and the Ministry of Agriculture's import quarantine requirements structure market access for foreign brands. The Kanto region's cold chain infrastructure supports refrigerated fresh topper distribution previously limited to conventional retail.
United Kingdom
London and Southeast England households exhibit strongest subscription purchasing penetration for premium gravy and sauce formats. FSA pet food hygiene regulations and post-Brexit import certification requirements reshape continental European supplier relationships. The Midlands manufacturing belt retains wet pet food canning capacity serving both domestic and export markets.
Australia
Sydney and Melbourne urban pet owners drive demand for wild-caught fish-based toppers targeting coat and cognitive health positioning. The Department of Agriculture's biosecurity import restrictions and state-level pet food standards limit raw ingredient sourcing flexibility. Queensland's aquaculture processing clusters supply domestic tuna and salmon inputs for premium formulation lines.
Cat Food Toppers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Cat Food Toppers landscape, with freeze-drying and high-pressure processing specialists commanding premium positioning while mass-market manufacturers leverage scale economies in conventional wet and dry formats. The market structure tiers into three strategic archetypes: multinational CPG conglomerates with veterinary channel dominance, independent specialty brands anchored in pet retail, and emerging direct-to-consumer subscription operators. Consolidation activity concentrates on freeze-dried raw specialists acquiring regional distribution rights, while capacity expansion focuses on refrigerated fresh formats requiring cold chain integration.
Within the multinational tier, Mars Incorporated and Nestlé Purina Petcare occupy positions defined by global supply chain infrastructure and mass retail shelf-space dominance. Stella & Chewy's represents the independent specialty archetype, with freeze-dried raw positioning that commands premium placement in pet specialty channels. These three companies exemplify the competitive spectrum from scale-driven cost efficiency to formulation-driven premium segmentation that defines strategic positioning across the category.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina Petcare |
| Blue Buffalo Co., Ltd. |
| Hill's Pet Nutrition |
| Stella & Chewy's |
| The Honest Kitchen |
| Merrick Pet Care, Inc. |
| Nature's Variety |
| WellPet LLC |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for human-grade poultry and wild-caught fish lock in supply access and price visibility for premium cat food topper manufacturers, insulating scaled producers from spot market volatility in protein inputs while smaller competitors absorb margin compression from volatile commodity sourcing.
Pricing Analysis
The FDA's Food Safety Modernization Act dictates the pricing tier structure across the cat food toppers landscape, with FSMA-compliant facilities commanding 25-40 percent premiums over non-certified alternatives. Three-tier pricing structure across premium, standard, and economy levels separates human-grade freeze-dried formulations from conventional wet toppers and mass-market gravy formats. Cost compression in the premium tier is intensifying because wild-caught salmon and free-range poultry supply constraints tighten input costs. Multi-cat suburban households exhibit highest price sensitivity, while millennial urban subscribers in coastal metros demonstrate lowest elasticity.
Supply Chain Analysis
The United States anchors wet topper production with Midwestern protein processing corridors around Omaha and Kansas City feeding FDA-regulated facilities, while Germany and Japan host specialized freeze-drying equipment and cold chain distribution hubs. Raw material dependencies center on North Atlantic fisheries for omega-3 positioning, Midwestern rendering plants for poultry and beef inputs, and Bavarian drying technology suppliers. Single-source vulnerability in wild-caught fish procurement creates disruption exposure for premium lines. Distribution runs through veterinary channel gatekeepers, e-commerce subscription platforms, and mass retail slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from owner-prepared cooked chicken and broth alternatives that capture price-sensitive demand in multi-cat suburban markets, requiring defensive positioning around convenience and nutritional completeness claims.
For Market Incumbents: Consolidate backward integration into Midwestern poultry rendering and North Atlantic fisheries to secure human-grade input streams against supply volatility. Lock in veterinary channel exclusivity through prescription-adjacent therapeutic formulations that homemade substitutes cannot replicate. FSMA compliance investments create regulatory moats that smaller competitors cannot bridge without capital barriers. For New Entrants and Emerging Players: Differentiate on functional vegetable inclusions targeting digestive health and hairball control positioning where meat-first incumbents remain underdeveloped. Target senior cat therapeutic segments in veterinary-adjacent distribution where prescription positioning commands pricing power. Direct-to-consumer subscription models bypass slotting fee barriers while capturing lifetime value through algorithm-driven replenishment. For Investors and Strategic Acquirers: Freeze-drying technology specialists with established cold chain partnerships represent the highest-conviction acquisition archetype for premium portfolio expansion. Long-term viability hinges on regulatory compliance scalability and subscription retention economics rather than brand awareness alone. Watch for AAFCO complete-and-balanced definition shifts that would recalibrate meal-replacement versus supplement positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Integration Investment | Temperature-controlled logistics unlock refrigerated fresh topper distribution in metropolitan markets. |
| Veterinary Channel Partnership | Clinic-exclusive placement secures prescription-adjacent positioning for therapeutic formulations. |
| Freeze-Drying Capacity Expansion | Low-temperature dehydration preserves raw nutrition while extending shelf stability for mass retail. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment models capture recurring revenue through algorithm-driven portion recommendations. |
| FSMA Compliance Certification | Preventive control documentation satisfies FDA hazard analysis requirements for facility registration. |
Study Parameters
A spread of perspectives from brand managers at multinational CPG conglomerates, category buyers at specialty pet retail chains, veterinary nutrition specialists, and supply planners at protein rendering facilities converged on the working assumptions driving this analysis. Secondary validation drew from FDA facility registration databases, AAFCO nutrient profile publications, Nielsen retail audit data, and customs records of pet food ingredient imports. Bottom-up demand modeling triangulated against top-down manufacturer capacity assessments.
Product type, ingredient sourcing tier, packaging format, and target life-stage segmentation dimensions structured the analytical framework across the analysis window. CAGRs were derived from trajectory fitting against historical volume elasticities and projected urban pet density trends. Forecast inputs incorporated veterinary telehealth adoption curves and e-commerce subscription penetration rates in coastal metropolitan markets.
The analysis sits within stated boundaries; outcomes outside sustained millennial pet ownership growth or stable FDA enforcement posture would require recalibration. Forecasts reflect assumptions around protein input supply continuity and state-level raw food handling regulation stability. Recalibration cycles align with material shifts in AAFCO nutrient profile definitions and FSMA preventive control enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
Japan Pet Food Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
Pet Calming Products Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Pet Lodging Market