
 Pet Lodging Market | 2026-2036
Pet Lodging Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Lodging Market Analytics
Affluent millennial pet owners is collapsing the traditional price-sensitive boarding segment into premium experience-driven lodging. PetSmart leverages its national retail footprint to anchor veterinary-integrated boarding concepts across suburban markets. Dogtopia differentiates through franchise scalability and specialized daycare programming. K9 Resorts competes on luxury facility design and breed-specific care protocols.
Pet lodging encompasses temporary housing and care services for companion animals, typically involving climate-controlled enclosures with defined square footage per animal, supervised exercise protocols, and documented health monitoring. The primary commercial purpose centers on enabling pet owners to travel or work while ensuring animal welfare through professional oversight. Boarding and daycare services dominate revenue generation within service type segmentation, with luxury hotels capturing disproportionate margin pools among facility types. Dogs represent the anchor animal type by volume, though cat-specific lodging is expanding fastest as feline ownership rises among urban apartment dwellers.
The US FDA oversees animal pharmaceutical and biologic standards affecting on-site medical care capabilities, while state agriculture departments enforce kennel sanitation and staffing ratios through licensing regimes. Local zoning boards further restrict facility placement near residential zones, shaping geographic expansion feasibility. Stakeholders must monitor evolving municipal animal welfare ordinances and certification standards from the Pet Care Services Association to anticipate compliance costs and service differentiation requirements.
Market Dynamics
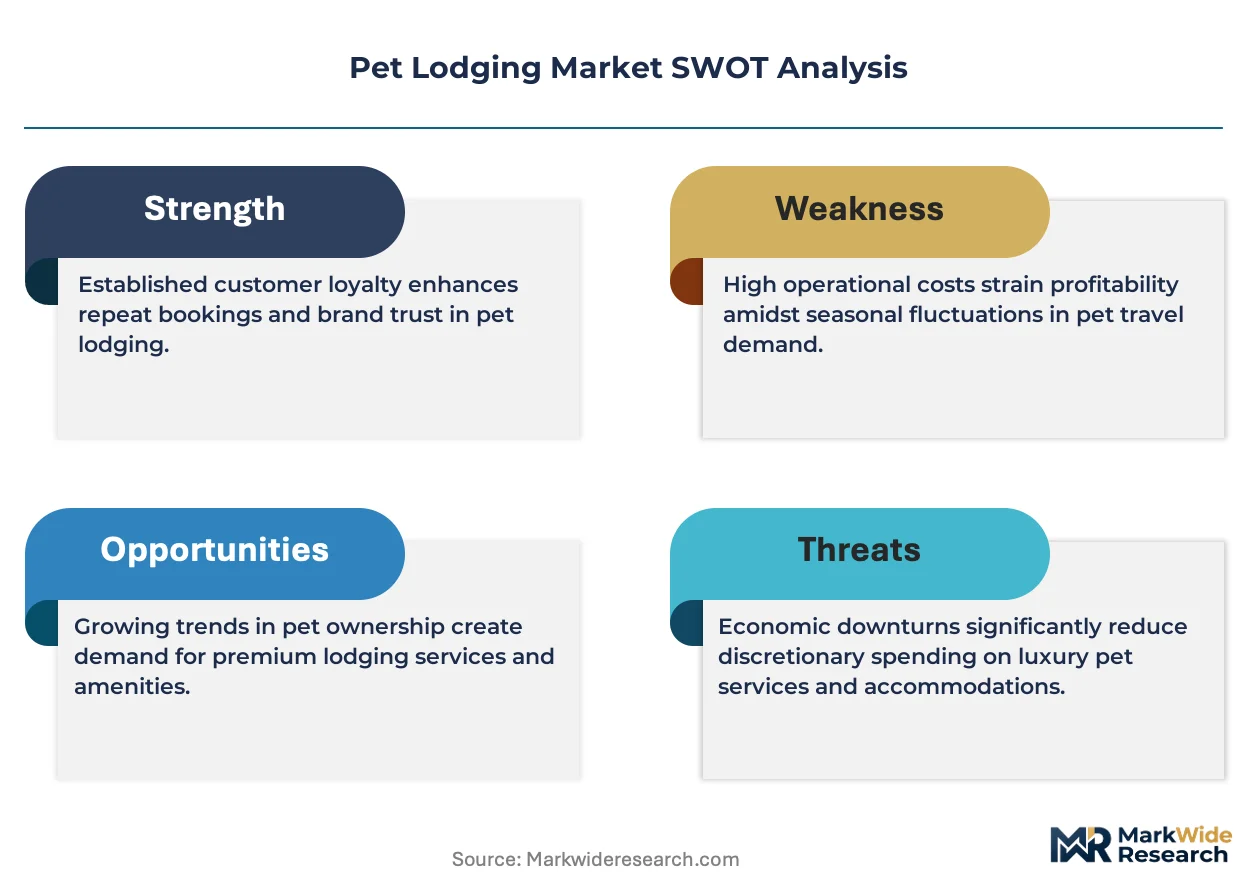
Affluent millennial and Gen Z pet owners are collapsing the traditional price-sensitive boarding segment into premium experience-driven lodging, forcing facility operators to reconfigure capital deployment toward amenity-rich environments and specialized care protocols.
Growth Catalysts
- US FDA Animal Health Oversight:Tighter pharmaceutical and biologic standards for on-site medical care are compelling facilities to invest in veterinary-integrated service models, elevating professional credibility and justifying premium rate structures.
- Urban Corridor Demand Concentration:Dense pet ownership in New York, Los Angeles, and Chicago generates sufficient volume to support specialized daycare programming and luxury facility economics unavailable in dispersed markets.
- Climate-Controlled Enclosure Technology:Advanced HVAC and monitoring systems enable operators to guarantee defined square footage per animal with documented environmental parameters, reducing liability exposure and supporting certification premiums.
Market Restraints
- State Kennel Licensing Requirements:Agriculture departments enforce staffing ratios and sanitation protocols that vary significantly across jurisdictions, creating compliance fragmentation that slows multi-state expansion.
- Local Zoning Board Restrictions:Municipal ordinances frequently prohibit facility placement near residential zones, constraining site availability and inflating real estate acquisition costs in target markets.
- Labor-Intensive Service Model:Supervised exercise protocols and documented health monitoring require high staff-to-animal ratios that resist automation, compressing operating margins relative to capital-light alternatives.
Strategic Opportunities
- Cat-Specific Lodging Expansion:Rising feline ownership among urban apartment dwellers represents underpenetrated white space, as existing facilities predominantly optimize for canine volume and behavior patterns.
- Pet Care Services Association Certification:Industry-wide standardization creates differentiation pathways for early adopters to command rate premiums through documented quality assurance.
- Suburban Veterinary-Retail Integration:Co-location with pet retail footprints reduces customer acquisition costs and enables cross-selling of medical, grooming, and boarding services through shared foot traffic.
Industry Challenges
- Veterinary Technician Talent Scarcity:Facilities integrating on-site medical care face competition from clinical practices for credentialed staff, extending recruitment timelines and inflating compensation benchmarks.
- Capex-Heavy Facility Standards:Climate-controlled enclosures with defined square footage requirements demand substantial upfront investment in specialized construction and environmental systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Lodging Market |
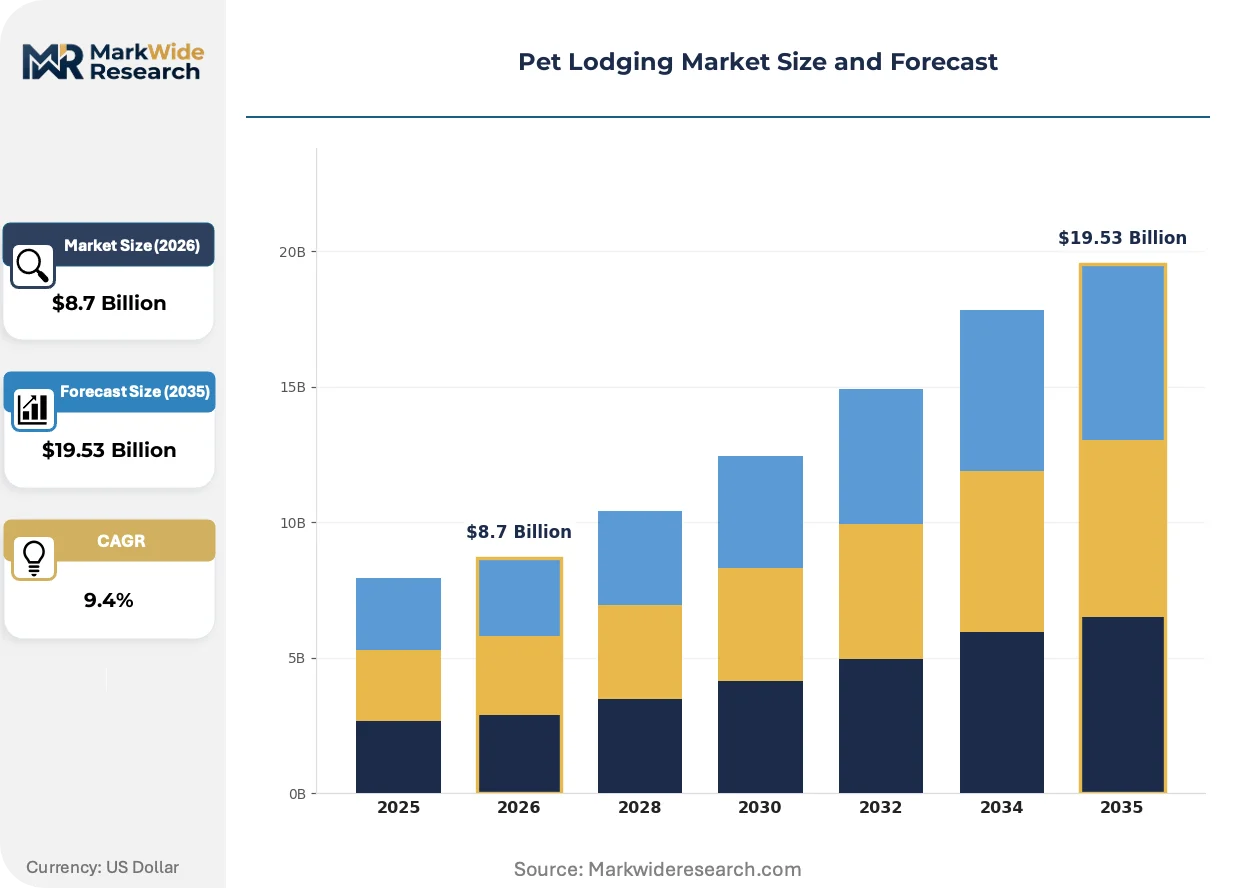
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Boarding, Daycare, Pet Sitting, Grooming Animal Type: Dogs, Cats, Birds, Small Mammals Facility Type: Luxury Hotels, Standard Lodges, Home-based Care, Kennels Customer Segment: Pet Owners, Corporate Clients, Breeders, Rescue Organizations |
| Companies Covered | PetSmart, Camp Bow Wow, Rover, Dogtopia, Best Friends Pet Care, Petco, Wag Hotels, K9 Resorts, VCA Animal Hospitals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Lodging Market Evolving Landscape
Digital monitoring systems and breed-specific care protocols are actively reshaping competitive positioning, separating technology-enabled operators from traditional kennel models while regulatory pressure accelerates professionalization standards.
Smart enclosure monitoring is bifurcating facility tiers by embedding real-time environmental sensors and video streaming capabilities that transmit animal status to owner devices. Premium urban operators are deploying these systems as baseline amenities, while budget providers face margin compression from consumer expectation shifts. The technology is bifurcating market structure into documented, transparent operations versus opaque traditional boarding.
State agriculture departments are intensifying kennel sanitation enforcement through unannounced inspections and documented staffing ratio verification. Facilities must now maintain auditable records of exercise protocols and health monitoring to retain operating licenses. Mid-tier operators in California and Texas are responding by consolidating into larger professionally managed groups capable of absorbing compliance overhead.
Subscription-based daycare memberships are displacing transactional boarding purchases among urban professional segments. Younger pet owners in Chicago and Seattle prefer unlimited monthly access models that guarantee reservation availability and bundle grooming services. This pattern concentrates revenue predictability with scaled operators while fragmenting demand across smaller facilities unable to offer comparable commitment structures.
Pet Lodging Market Segmentation
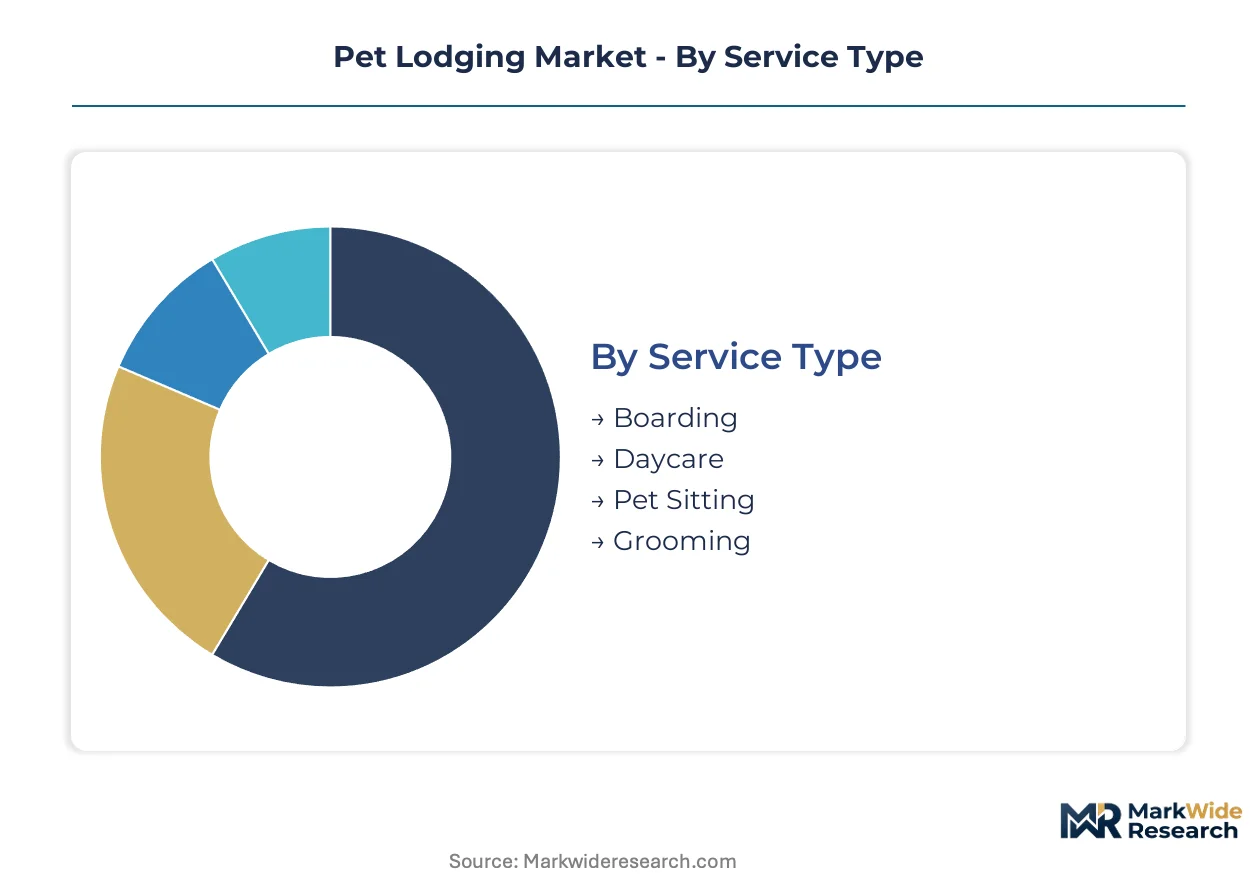
Pet lodging segmentation reveals how service intensity, animal behavior patterns, and facility capital requirements create distinct competitive arenas. Operators must align capability investments with segment-specific substitution threats rather than pursuing uniform scale.
Service Type:
Boarding faces the strongest substitution pressure from informal neighbor networks and gig-economy pet sitting apps, forcing established facilities to differentiate through veterinary integration and documented care protocols.
- Boarding:Overnight housing in climate-controlled enclosures with defined square footage per animal and supervised exercise rotations. Demand concentrates among leisure travelers in urban corridors like New York and Los Angeles, where the US FDA's animal health oversight compels facilities to maintain pharmaceutical handling capabilities. Extended stay packages and medical monitoring justify rate premiums above informal alternatives.
- Daycare:Supervised daytime activity programming with socialization protocols and behavioral assessment. Subscription membership models in Chicago and Seattle displace transactional purchases among remote-hybrid professionals seeking guaranteed reservation availability. Breed-specific grouping and enrichment activities separate premium operators from basic supervision services.
- Pet Sitting:In-home visits or overnight stays at the owner's residence, minimizing animal transport stress. Mobile apps and independent contractors dominate this segment through price undercutting of facility-based alternatives.
- Grooming:Hygiene maintenance services including bathing, coat trimming, and nail care. Co-location with boarding and daycare generates cross-selling opportunities and shared customer acquisition costs.
Boarding retains volume leadership; Daycare holds the steepest expansion curve.
Animal Type:
Cost tier stratification separates capital-intensive canine facilities from lower-infrastructure feline operations, with species-specific behavior dictating staffing ratios and enclosure design specifications.
- Dogs:Social pack animals requiring exercise yards, group play supervision, and noise mitigation systems. Volume concentrates in suburban markets with PetSmart-anchored veterinary-retail integration capturing foot traffic economies.
- Cats:Solitary territorial animals demanding vertical climbing structures, separate air handling, and reduced sensory stimulation. Rising ownership among urban apartment dwellers in dense corridors drives fastest facility expansion, as existing operators predominantly optimize for canine patterns.
- Birds:Avian species with specialized temperature, humidity, and lighting requirements. Niche demand from exotic pet owners limits addressable market scale.
- Small Mammals:Rabbits, guinea pigs, and rodents with compact housing needs and minimal exercise protocols. Home-based care and pet sitting services capture most demand due to low service intensity.
Dogs anchor revenue volume; Cats are climbing the fastest as urban ownership patterns shift.
Facility Type:
Application context determines facility selection, with travel duration, animal medical needs, and owner price sensitivity driving choice between institutional and residential care models.
- Luxury Hotels:Amenity-rich environments featuring private suites, webcam monitoring, and spa services. Premium urban operators in Los Angeles and New York deploy these as baseline competitive requirements, while budget providers face margin compression from elevated consumer expectations.
- Standard Lodges:Functional boarding with basic climate control and scheduled exercise. State agriculture department staffing ratio enforcement and sanitation audits favor consolidated professional groups over independent operators.
- Home-based Care:Residential operators with limited animal capacity and informal oversight. Local zoning board restrictions near residential zones constrain geographic expansion and legal compliance.
- Kennels:Traditional high-density housing with outdoor run access. Legacy facilities face obsolescence pressure from climate-controlled enclosure standards and documented health monitoring requirements.
Standard Lodges retain volume leadership; Luxury Hotels gain share fastest through amenity escalation.
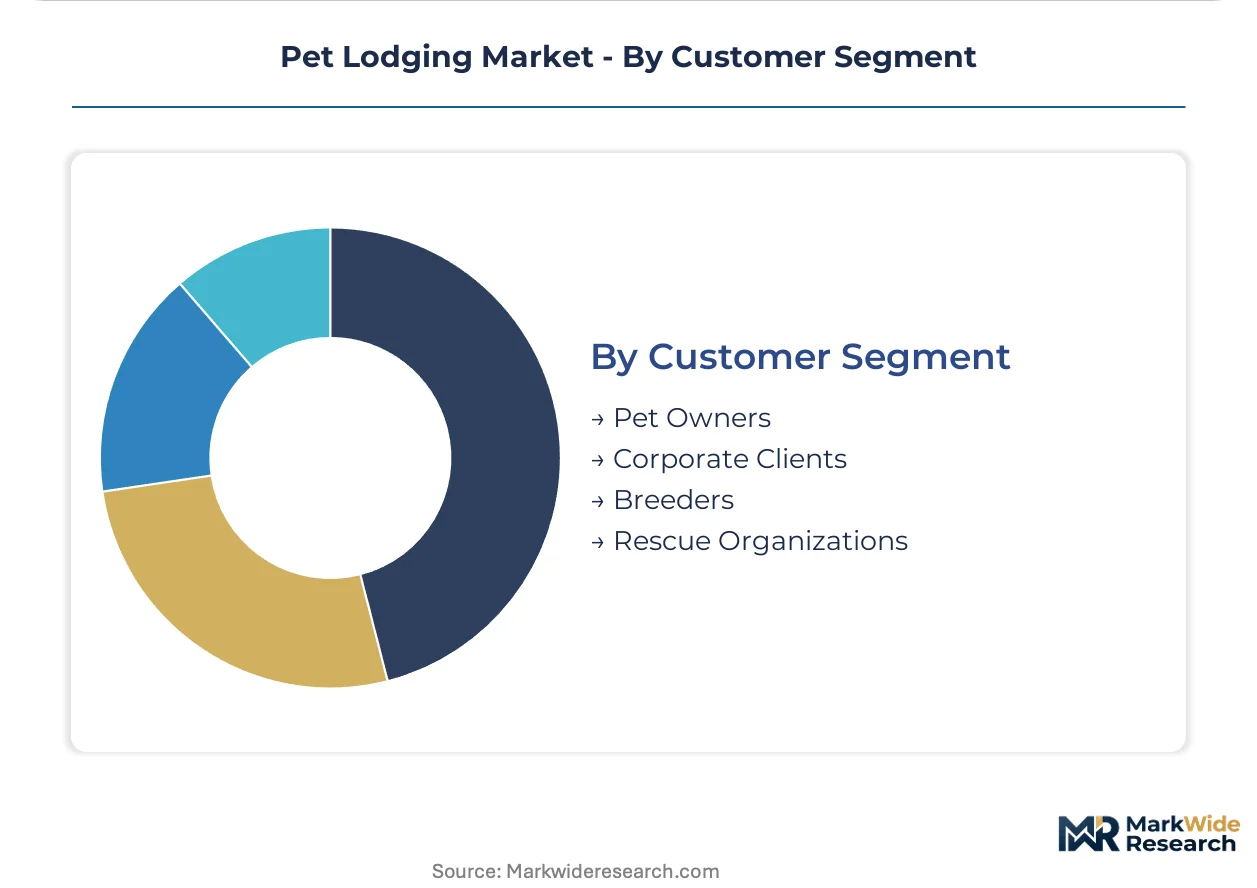
Customer Segment:
Customer maturity and procurement scale separate individual pet owners from institutional buyers, with contract terms and volume guarantees shaping operator revenue predictability.
- Pet Owners:Individual consumers purchasing discretionary care services. Millennial and Gen Z demographics in urban corridors drive premium experience expectations and subscription preference over transactional models.
- Corporate Clients:Employers offering pet care as employee benefit or relocation service. Tech sector adoption in Seattle and Austin creates concentrated demand for vetted facility networks and consolidated billing.
- Breeders:Commercial breeding operations requiring temporary housing for dams, litters, and show animals. Seasonal demand patterns and specialized neonatal care protocols limit facility interchangeability.
- Rescue Organizations:Non-profit shelters and transport networks needing quarantine and rehabilitation housing. Municipal contracts and grant funding create price-sensitive procurement with stringent documentation requirements.
Pet Owners retain volume leadership; Corporate Clients hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pet lodging operators export premium service protocols to Canadian and Mexican franchise networks, establishing North America as the dominant trade corridor for veterinary-integrated boarding concepts.
United States
Urban corridor demand concentrates in New York, Los Angeles, and Chicago, where millennial pet owners drive premium experience expectations. The US FDA enforces tighter pharmaceutical and biologic standards for on-site medical care, compelling facilities to invest in veterinary-integrated models. Greater Los Angeles anchors luxury facility expansion, with amenity-rich environments featuring private suites and webcam monitoring becoming baseline competitive requirements.
Canada
Pet ownership rates in Toronto and Vancouver mirror US urban patterns, creating demand for climate-controlled enclosures with documented health monitoring. Health Canada and PMRA oversee animal pharmaceutical standards affecting cross-border service protocol adoption. The Greater Toronto Area attracts US franchise expansion, where PetSmart-anchored veterinary-retail integration captures suburban foot traffic economies.
Germany
Affluent pet ownership in Berlin and Munich supports premium boarding economics, though cultural preferences favor smaller facility formats than US counterparts. The country's national veterinary regulator enforces strict kennel sanitation and staffing ratio requirements through licensing regimes. Bavaria hosts specialized daycare programming expansion, with subscription membership models displacing transactional purchases among remote-hybrid professionals.
United Kingdom
London's dense pet ownership generates sufficient volume for luxury facility economics unavailable in regional markets. DEFRA and local authority environmental health teams enforce animal welfare licensing with documented exercise protocol verification. The Southeast England corridor sees consolidation into professionally managed groups capable of absorbing compliance overhead from intensified inspection regimes.
Australia
Sydney and Melbourne urban apartment dwellers drive fastest growth in cat-specific lodging, as existing facilities predominantly optimize for canine patterns. The national veterinary medicines regulator and state agriculture departments enforce varying kennel standards across jurisdictions. New South Wales concentrates technology-enabled operator expansion, with smart enclosure monitoring and real-time environmental sensors separating premium tiers from traditional kennel models.
Pet Lodging Market Competitive Landscape
Player mix skews toward franchise-scalable networks and veterinary-integrated retail chains, with independent operators consolidating under professional management to absorb compliance overhead. Market structure bifurcates between capital-heavy premium facility developers and asset-light digital platforms connecting pet owners with independent caregivers. Three archetypes dominate: retail-anchored veterinary chains, specialized daycare franchise systems, and technology-enabled marketplace platforms. Competitive moves center on multi-state expansion through franchise development and co-location strategies with pet retail footprints.
Among retail-anchored veterinary chains, PetSmart and Petco exemplify suburban veterinary-retail integration, leveraging national footprints to cross-sell medical, grooming, and boarding services. Within the premium facility tier, K9 Resorts occupies a position emphasizing luxury design and breed-specific care protocols, while Dogtopia represents franchise scalability with specialized daycare programming. These three companies anchor distinct strategic vectors in a market where documented quality assurance and certification premiums increasingly separate scalable operators from fragmented independents.
| Leading Market Players |
|---|
| PetSmart |
| Camp Bow Wow |
| Rover |
| Dogtopia |
| Best Friends Pet Care |
| Petco |
| Wag Hotels |
| K9 Resorts |
| VCA Animal Hospitals |
| Others |
Value Network & Pricing Analysis
Subscription membership models displacing transactional boarding purchases simultaneously reshape supply geography toward urban corridor concentration and compress pricing power in dispersed markets unable to support comparable commitment structures. This substitution dynamic elevates facility utilization predictability in dense metropolitan zones while fragmenting revenue streams across smaller operators lacking scale economics.
Pricing Analysis
Next-generation smart enclosure monitoring systems command rate premiums of 25-40% above prior-generation climate-controlled facilities, while legacy kennel operators face margin compression from elevated consumer transparency expectations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and veterinary integration depth, with Pet Care Services Association accreditation separating rate tiers. Pricing pressure stems from gig-economy pet sitting apps undercutting facility-based alternatives in the boarding segment. Corporate clients exhibit lowest price sensitivity due to consolidated billing and employee benefit positioning, while individual leisure travelers demonstrate highest elasticity to informal substitutes.
Supply Chain Analysis
Port congestion at Los Angeles and Long Beach inflates inbound logistics costs for specialized HVAC equipment and environmental monitoring systems sourced from China, Taiwan, and South Korea. Climate-controlled enclosure manufacturing draws from steel fabrication in Mexico, electronics assembly in Vietnam, and insulation materials from Canada. Single-source vulnerability concentrates in smart sensor chipsets from Taiwanese foundries. Distribution runs through veterinary-integrated retail chains and franchise development networks, with regional hub-and-spoke models serving metropolitan daycare demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet lodging operates as a high-growth disruption where US FDA animal health oversight and state kennel licensing intensification are forcing capital reallocation toward veterinary-integrated service models. This regulatory inflection compresses returns for non-compliant independents while rewarding scaled operators with certification premiums.
For Market Incumbents: Fortify market position through backward integration into veterinary technician training pipelines and captive development of proprietary daycare programming IP. State agriculture department staffing ratio enforcement threatens independent operators with compliance overhead; absorption capacity through professional management consolidation represents the priority defensive lever. Climate-controlled enclosure standardization requires sustained capex deployment that fragments smaller competitors.
For New Entrants and Emerging Players: Differentiate on cat-specific lodging protocols targeting urban apartment dwellers in dense corridors where existing facilities optimize for canine volume. This white space offers lowest competitive density and fastest ownership growth curves. Suburban veterinary-retail co-location with PetSmart-anchored foot traffic reduces customer acquisition costs versus greenfield development.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed franchise networks consolidating mid-tier operators under professional management platforms. Long-term viability across the 5-10 year window favors operators with documented quality assurance and multi-state licensing compliance infrastructure. The signal to watch is municipal zoning board relaxation near residential zones enabling geographic expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary-Integrated Facility Development | US FDA pharmaceutical handling requirements elevate professional credibility and justify premium rate structures. |
| Franchise Network Expansion | Dogtopia and K9 Resorts demonstrate scalable protocols for multi-state compliance absorption. |
| Smart Enclosure Technology Deployment | Real-time environmental sensors separate premium tiers from opaque traditional boarding models. |
| Cat-Specific Lodging Buildout | Rising feline ownership among urban apartment dwellers creates underpenetrated white space. |
| Subscription Membership Migration | Unlimited monthly access models concentrate revenue predictability with scaled urban operators. |
Research Methodology
Cross-validation between facility operator interviews and municipal licensing database analysis anchors the qualitative findings on regulatory enforcement intensity. Primary interviews with veterinary-integrated boarding executives, state agriculture department inspectors, franchise development directors, and urban real estate brokers combine with secondary validation through FDA guidance documents, state kennel licensing statutes, Pet Care Services Association certification standards, and municipal zoning ordinances. Bottom-up facility count triangulation against top-down market sizing ensures dimensional consistency.
Sensitivity analysis across pricing tier elasticity and urban corridor penetration rates shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include service type, animal species, facility tier, and customer procurement scale, with regional regulatory cluster variations capturing compliance cost differentials. CAGRs derive from cohort-based expansion rates applied to baseline facility counts. Industry-specific forecast inputs incorporate veterinary technician wage inflation and climate-controlled construction cost indices.
Material uncertainties — municipal zoning board composition shifts, state kennel staffing ratio amendments, and gig-economy platform regulatory classification — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and consumer substitution patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Pet Noise Anxiety Market
Pet Care Products
Pet Calming Products Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Pet Supplement Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Spain Pet Food Market