
 Leisure Battery Market | 2026-2036
Leisure Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Leisure Battery Market Insights
Chinese lithium cell production is decoupling from European pack assembly, reshaping how leisure battery supply chains configure. Fogstar Batteries leverages its UK-based pack engineering to serve caravan and narrowboat operators with application-specific form factors. Renogy anchors the North American RV solar-battery ecosystem through integrated charge controller and lithium storage bundles. LiTime competes aggressively on cylindrical cell sourcing, sustaining margin pressure on incumbent lead-acid suppliers across marine and camping channels.
A leisure battery is a deep-cycle rechargeable storage unit engineered for partial-state-of-charge operation, typically delivering between 50 and 300 ampere-hours at 12V or 24V, with lithium-ion variants achieving 3,000 to 5,000 cycles at 80 percent depth of discharge versus 500 to 800 cycles for flooded lead-acid equivalents. Its primary purpose is to power auxiliary loads in mobile and off-grid environments where engine-starting batteries would fail under sustained discharge. The lithium-ion product category captures the fastest expansion as weight-sensitive marine and RV applications abandon lead-acid, while gel batteries retain share in fire-safety-critical installations aboard commercial vessels. Camping applications now drive portable installation growth, though fixed integration dominates in factory-fit RV builds where OEMs specify battery management systems at the chassis design stage.
REACH restricts cadmium and lead content in European-sold batteries, pushing manufacturers toward lithium iron phosphate and absorbent glass mat alternatives that satisfy ECHA substance thresholds. The EU Green Deal's embedded carbon requirements for imported cells are forcing Asian suppliers to disclose factory energy sources or risk exclusion from premium distribution channels. Stakeholders must monitor how emerging battery passport regulations reshape aftermarket replacement economics and whether marine classification societies extend fire-safety rules from commercial shipping into leisure craft.
Market Dynamics
The EU F-Gas Regulation and REACH compliance requirements are forcing battery manufacturers to abandon lead-acid chemistries in favor of sealed gel and lithium-ion alternatives, restructuring procurement patterns across European caravan manufacturing and Mediterranean marine service networks.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbons in mobile refrigeration systems is driving RV OEMs to specify lithium battery packs with integrated thermal management, eliminating lead-acid from factory-fit chassis designs.
- Marine electrification:Coastal operators in Florida and the Mediterranean are retrofitting diesel auxiliary systems with electric propulsion banks, creating sustained demand for deep-cycle lithium storage with marine-grade battery management systems.
- Camping segment expansion:Portable power station adoption among off-grid campers is accelerating cylindrical cell consumption, with weekend users prioritizing weight reduction over cycle-life specifications.
Market Restraints
- Lithium carbonate volatility:Raw material price swings from South American brine operations compress pack assembler margins, particularly for UK-based engineering firms serving narrowboat operators with low-volume custom form factors.
- Cell supply concentration:Chinese cylindrical production dominates upstream supply, creating dependency risks for European pack integrators facing EU Green Deal embedded carbon disclosure requirements.
- Fire-safety certification delays:Marine classification societies have yet to harmonize leisure craft battery standards with commercial shipping rules, slowing lithium adoption in fire-critical installations.
Strategic Opportunities
- German caravan corridor:Factory-fit OEM relationships in Baden-Württemberg and Bavaria offer captive channels for battery management system integration at the chassis design stage.
- Solar-battery convergence:Integrated charge controller and storage bundles are capturing RV retrofit demand, with rooftop panel installations driving 12V system upgrades across North American dealer networks.
- Battery passport readiness:Early compliance with emerging EU traceability mandates positions aftermarket suppliers for premium replacement economics as circularity rules tighten.
Industry Challenges
- Battery management system firmware integration:Pack assemblers must coordinate with RV chassis OEMs on CAN bus protocols, extending development timelines and requiring specialized embedded engineering talent.
- Cross-chemistry inventory complexity:Distributors serving mixed marine and camping channels face working capital strain from stocking lead-acid, gel, and lithium variants with incompatible charge profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leisure Battery Market |
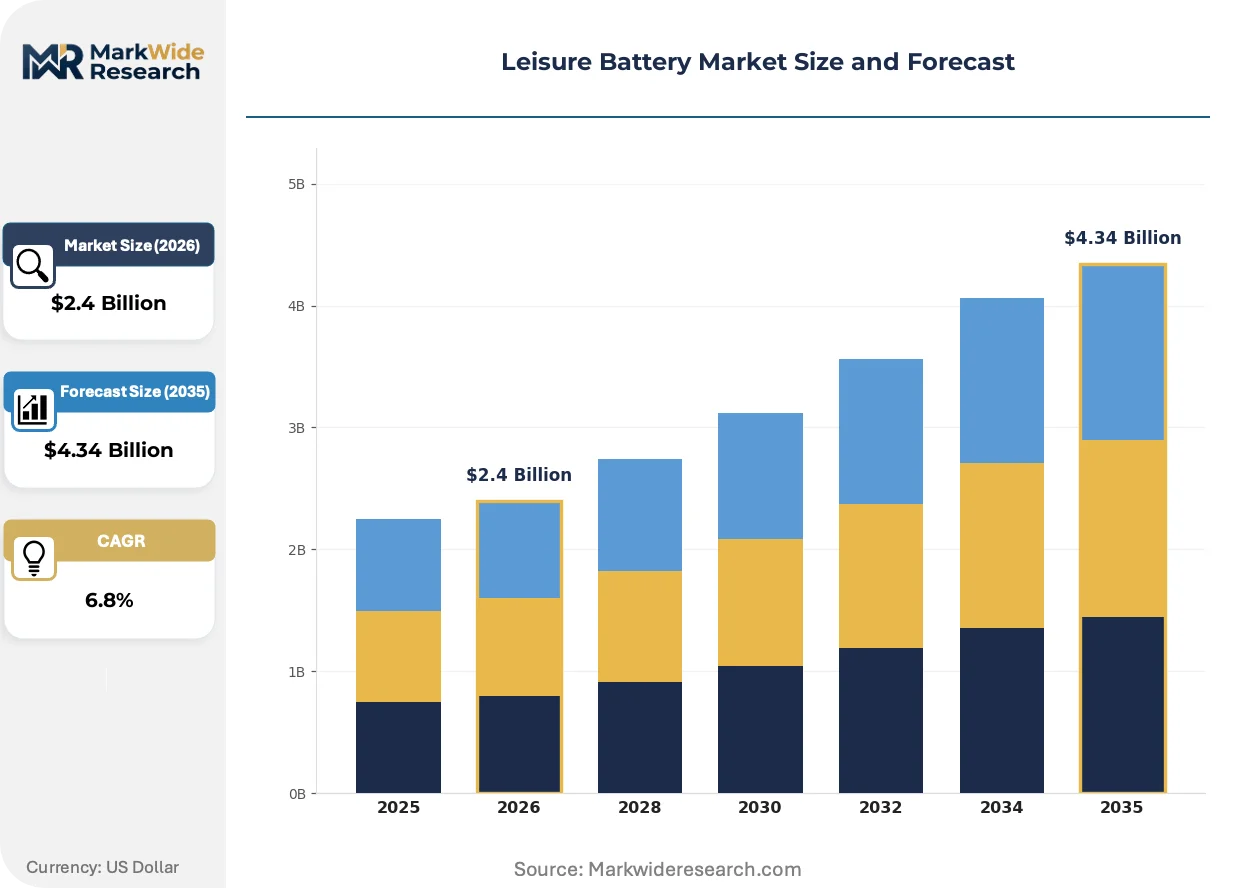
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Gel Application: Camping, Marine, RVs, Power Tools End User: Outdoor Enthusiasts, Commercial Users, Emergency Services, Residential Users Installation Type: Portable, Fixed, Integrated, Standalone |
| Companies Covered | Fogstar Batteries, Eco Worthy, Roamer, LithiumPro Energy, EcoTree Lithium, Renogy, LiTime, GOLDENMATE, SkyEnergi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leisure Battery Market Trends and Innovations
Lithium iron phosphate cell chemistry is rewriting competitive boundaries in this market. Pack assemblers are racing to secure automotive-grade cell supply as tier-one suppliers redirect capacity toward electric vehicle contracts.
Lithium iron phosphate delivers 3,000 to 5,000 cycles at 80 percent depth of discharge, enabling weekend RV users to size systems smaller without sacrificing service life. Marine operators are adopting these cells for weight-sensitive sailing craft, abandoning flooded lead-acid despite higher upfront cost. This chemistry is rewriting how distributors configure stock-keeping units, compressing lead-acid shelf space in coastal marine supply stores.
REACH substance restrictions on cadmium and lead content are forcing Asian cell manufacturers to disclose factory energy sources or risk exclusion from premium European distribution channels. The regulation's ECHA enforcement arm is tightening documentation requirements for imported packs, raising compliance costs for non-EU assemblers. German caravan OEMs are responding by qualifying domestic pack engineering partners who can verify supply chain carbon intensity.
Buyer preferences are fragmenting between factory-fit OEM specification and aftermarket portable installation. Camping enthusiasts are purchasing standalone power stations through direct-to-consumer channels, bypassing traditional marine and RV dealers. This channel disintermediation is most visible in North American national park adjacent retail, where solar-battery bundles now compete with generator rentals for weekend power solutions.
Leisure Battery Market Segmentation
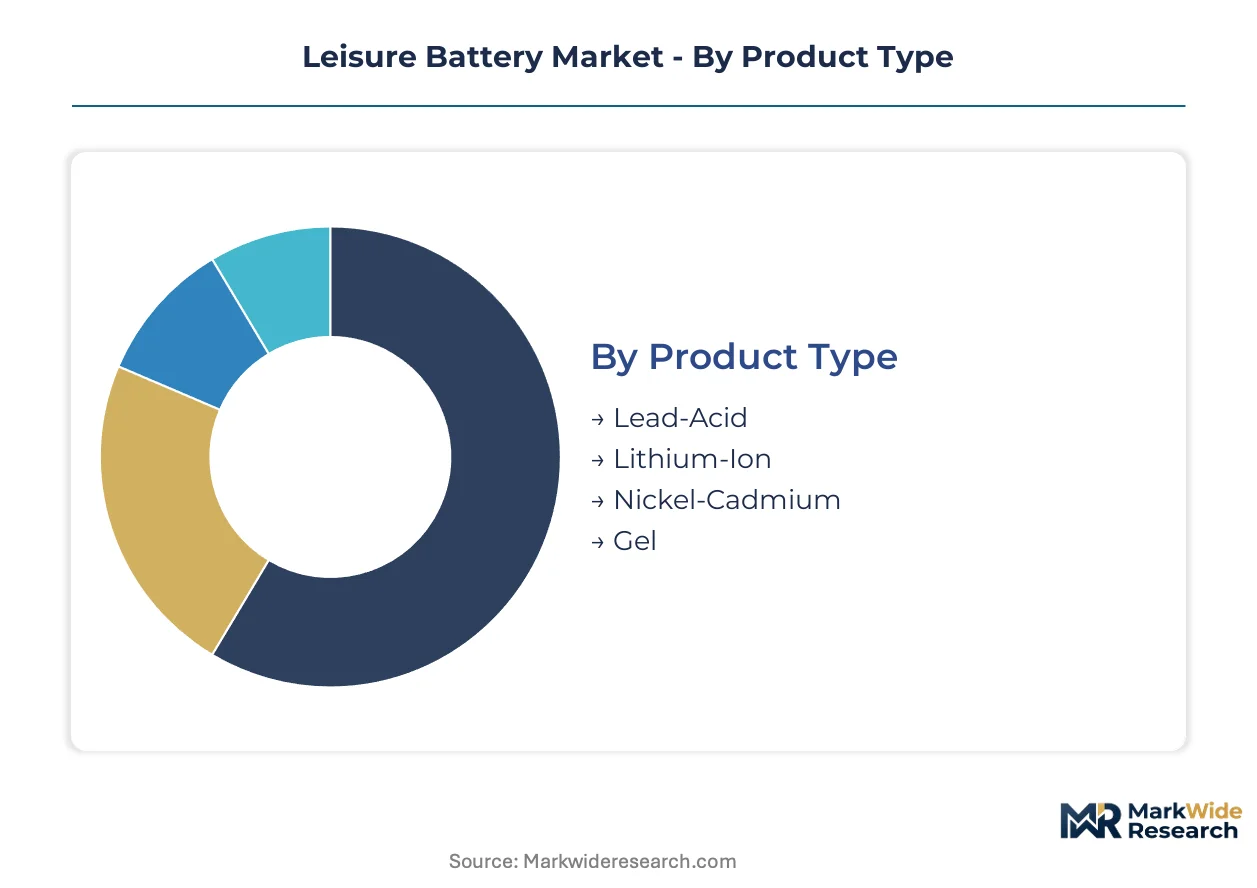
Leisure battery procurement splits sharply between standardized OEM chassis integration and customized aftermarket configurations. Understanding these fault lines reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Standardized cell formats dominate high-volume channels while custom pack engineering serves narrowboat and specialty marine operators with non-standard form factors.
- Lead-Acid:Flooded and absorbent glass mat variants deliver 500-800 cycles at 50% depth of discharge. Demand concentrates in price-sensitive Mediterranean marine service networks where retrofit economics resist lithium premiums.
- Lithium-Ion:Lithium iron phosphate chemistry achieves 3,000-5,000 cycles at 80% depth of discharge with one-third the weight of lead-acid equivalents. Florida coastal operators and German caravan OEMs specify these packs for weight-critical installations where cycle life offsets upfront cost.
- Nickel-Cadmium:REACH substance restrictions and ECHA enforcement on cadmium content have relegated this chemistry to legacy commercial vessel applications with grandfathered certifications.
- Gel:Sealed electrolyte construction satisfies fire-safety-critical installations aboard commercial vessels where thermal runaway risks trigger classification society scrutiny.
Leading the category by volume: Lead-Acid. Expanding most quickly: Lithium-Ion.
Application:
Volume scales inversely with customization requirements across these use cases, with factory-fit RV builds generating predictable demand curves.
- Camping:Portable power station adoption accelerates cylindrical cell consumption through direct-to-consumer channels. Weekend users prioritize weight reduction over cycle-life specifications, bypassing traditional dealer networks.
- Marine:Coastal operators in Florida and the Mediterranean retrofit diesel auxiliary systems with electric propulsion banks. Marine-grade battery management systems with IP67 sealing command specification premiums.
- RVs:Factory-fit OEM relationships in Baden-Württemberg and Bavaria integrate battery management systems at chassis design stage. Rooftop solar installations drive 12V system upgrades across North American dealer networks.
- Power Tools:Cordless equipment OEMs source cylindrical cells in high volumes, though this segment sits at the margin of core leisure battery definitions.
RVs generate the steadiest OEM demand. Camping shows the steepest channel disintermediation.
End User:
Procurement authority separates specification-driven commercial buyers from discretionary retail purchasers with divergent technical literacy.
- Outdoor Enthusiasts:Camping and overlanding participants purchase through Amazon and specialty retailers, prioritizing portability and solar compatibility over deep-cycle specifications.
- Commercial Users:Charter fleet operators and rental companies standardize on lithium iron phosphate for total cost of ownership advantages across multi-season deployment cycles.
- Emergency Services:Search-and-rescue and disaster response units require UN38.3-certified transportable power with rapid redeployment capability.
- Residential Users:Off-grid cabin owners size stationary installations for seasonal occupancy patterns with minimal maintenance requirements.
Commercial Users anchor replacement demand. Outdoor Enthusiasts drive portable segment innovation.
Installation Type:
Integration depth determines whether battery management system firmware coordinates with vehicle CAN bus protocols or operates independently.
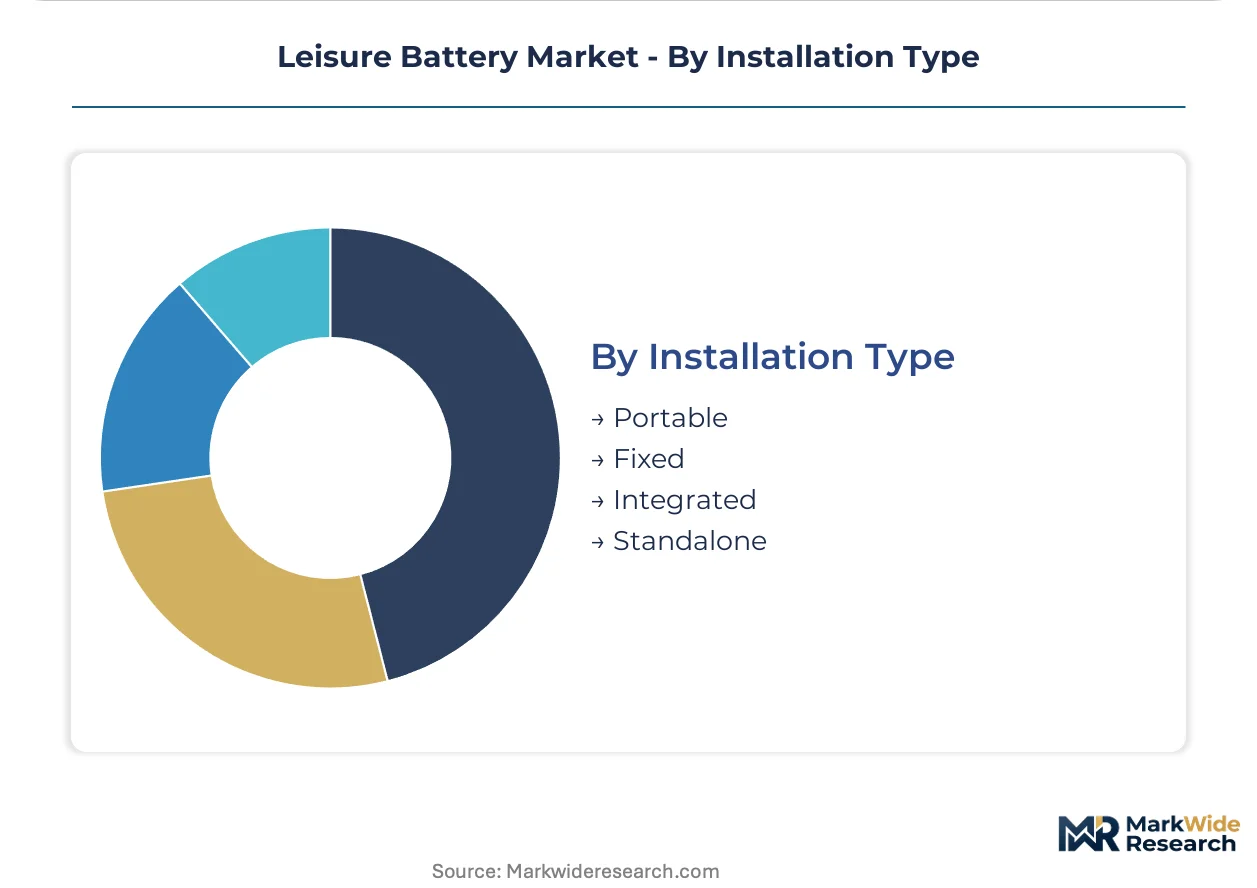
- Portable:Standalone power stations with integrated inverters serve camping and emergency applications where grid independence matters more than capacity optimization.
- Fixed:Bulkhead-mounted banks in sailing craft and narrowboats require ventilation engineering and secure tie-down to withstand pitch and roll forces.
- Integrated:Factory-fit OEM installations embed battery management systems at chassis design stage with proprietary CAN bus communication protocols.
- Standalone:Off-grid residential and commercial backup systems operate independently of vehicle electrical architecture with external charge controllers.
Fixed installations dominate marine replacement economics. Integrated configurations capture the highest per-unit value in OEM channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean lithium brine operations supply the cathode material feeding pack assembly across three continents. This raw-material anchor shapes where cell production concentrates and which geographies capture downstream value.
Germany
Baden-Württemberg and Bavaria host Europe's densest caravan manufacturing corridor, with OEMs integrating battery management systems at chassis design stage. The EU F-Gas Regulation phases down hydrofluorocarbons in mobile refrigeration, eliminating lead-acid from factory-fit specifications. Stuttgart-based engineering firms verify supply chain carbon intensity to satisfy EU Green Deal embedded carbon requirements.
United States
Florida's coastal marine service networks retrofit diesel auxiliary systems with electric propulsion banks, generating sustained demand for deep-cycle lithium storage. The Inflation Reduction Act's domestic content incentives favor North American pack assembly over imported cells. Tampa and Miami marine distributors compress lead-acid shelf space as lithium iron phosphate captures retrofit economics.
United Kingdom
Narrowboat operators on England's canal network drive demand for custom form factors from low-volume pack engineering specialists. REACH substance restrictions on cadmium and lead content push distributors toward sealed gel and lithium alternatives. Midlands-based assemblers source cylindrical cells independently of European pack integration to manage margin pressure.
China
Zhejiang and Guangdong provinces dominate cylindrical cell production for portable power stations serving camping applications. The country's dual carbon goals force factory energy source disclosure for export eligibility under EU Green Deal rules. Shenzhen pack assemblers decouple from European integration to serve direct-to-consumer channels.
Australia
Queensland and Western Australia off-grid cabin installations prioritize stationary lithium systems with minimal maintenance requirements. The national Clean Energy Council sets installation standards for solar-battery convergence in remote residential applications. Perth-based distributors stock integrated charge controller bundles for rooftop panel retrofits.
Leisure Battery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channels and specialty form factors. The vendor base splits between high-volume cylindrical cell distributors and low-volume custom pack engineers serving narrow marine applications. Three archetypes dominate: automotive cell redirectors capturing RV OEM relationships, camping specialists optimizing weight-to-capacity ratios, and marine-grade integrators satisfying IP67 sealing requirements. Capacity expansion and strategic partnerships with charge controller manufacturers constitute the dominant competitive moves.
Among UK-based pack engineering specialists, Fogstar Batteries occupies a position serving caravan and narrowboat operators with application-specific configurations. Renogy anchors the North American RV solar-battery ecosystem through its geographic concentration in the United States. LiTime exemplifies the cylindrical cell sourcing archetype, competing on cost structures that sustain margin pressure across marine and camping channels.
| Leading Market Players |
|---|
| Fogstar Batteries |
| Eco Worthy |
| Roamer |
| LithiumPro Energy |
| EcoTree Lithium |
| Renogy |
| LiTime |
| GOLDENMATE |
| SkyEnergi |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up pack assemblers in the UK and Germany enforce pricing discipline through captive battery management system engineering, while Chinese cylindrical cell producers operate on thin margins that compress European distributor working capital. This ownership split between financialized Western integrators and production-heavy Asian suppliers creates divergent pricing power across factory-fit OEM and aftermarket portable channels.
Pricing Analysis
Warranty and service bundling separates premium lithium iron phosphate packs from unbundled lead-acid alternatives in marine and RV channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—UN38.3 and IP67 marine-rated units command substantial premiums over camping-grade portable stations. Cost compression in cylindrical cell sourcing is intensifying because Chinese producers redirect automotive-grade capacity toward EV contracts. Weekend campers in the portable segment exhibit highest price sensitivity, while German caravan OEMs prioritize cycle-life specifications over upfront cost.
Supply Chain Analysis
Certification and qualification gating restricts European pack integrators to ECHA-verified cell suppliers capable of documenting factory carbon intensity under EU Green Deal rules. Upstream concentration centers on China, South Korea, and Japan for cylindrical cell production, while Chilean brine operations anchor lithium carbonate feedstock. Pack assembly draws from automotive-grade cell supply, marine-grade battery management systems, and aluminum enclosure fabrication. Single-source vulnerability in Chinese cylindrical output creates exposure for UK narrowboat specialists sourcing custom form factors. Distribution runs through marine service networks in Florida and Mediterranean coastal hubs, caravan OEM direct procurement in Baden-Württemberg, and direct-to-consumer camping channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive cell suppliers redirecting capacity toward electric vehicle contracts have created a supply-constrained environment that props pricing for qualified leisure battery pack assemblers. This capacity bottleneck favors incumbents with secured cell offtake and certified battery management system integration capabilities.
For Market Incumbents: Lock in multi-year cell supply agreements with tier-one cylindrical producers before automotive contracts absorb remaining capacity. Secure IP67 marine certification pathways ahead of classification society rule harmonization to defend against emerging camping specialists entering fire-safety-critical installations. Prioritize backward integration into battery management system firmware development to reduce dependency on chassis OEM CAN bus protocol coordination. For New Entrants and Emerging Players: Marine dealers in Mediterranean coastal networks represent the most penetrable channel partner type for aftermarket lithium retrofit kits, given fragmented incumbent presence outside Florida and German caravan corridors. Target narrowboat operators in England's canal network with application-specific form factors that bypass standardized RV chassis integration. Deploy direct-to-consumer solar-battery bundles through national park adjacent retail to capture weekend camping demand without dealer network investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor UK-based pack engineering specialists with ECHA-compliant supply chains and established narrowboat operator relationships during periods of lithium carbonate volatility. Long-term viability across the analysis window rests on battery passport readiness and circularity infrastructure investment. Watch for EU embedded carbon disclosure enforcement tightening as the inflection signal triggering premium channel exclusion for non-compliant Asian suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Cell Supply Agreement | Secures lithium iron phosphate capacity ahead of EV contract absorption. |
| Battery Management System Certification | Qualifies packs for IP67 marine installations under evolving classification society rules. |
| Battery Passport Compliance Program | Positions aftermarket suppliers for premium replacement economics under EU circularity mandates. |
| Solar-Battery Bundle Integration | Captures RV retrofit demand through Renogy-style charge controller convergence. |
| Custom Form Factor Engineering | Serves narrowboat operators with non-standard dimensions outside standardized OEM channels. |
Research Methodology
Independent corroboration across pack assembler engineering directors, marine classification society technical officers, and caravan OEM procurement leads underwrites the qualitative findings in this study. Primary fieldwork with cylindrical cell sourcing managers at UK and German distributors, combined with secondary validation through EU ECHA substance restriction filings, SEC disclosures from listed battery component suppliers, and customs trade data on lithium carbonate imports, establishes demand-side and supply-side triangulation. Bottom-up capacity estimates from Zhejiang and Guangdong production facilities reconcile with top-down spending patterns across Florida marine service networks and Baden-Württemberg caravan manufacturing corridors.
Rate-of-change decomposition separates volume drivers from value migration across the projection horizon. The analytical framework models segmentation dimensions spanning chemistry type, installation configuration, application vertical, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, OEM chassis specification trends, and aftermarket retrofit penetration curves. Forecast inputs incorporate lithium carbonate price volatility bands and EU Green Deal embedded carbon disclosure implementation timelines.
Caveats apply where lithium carbonate supply disruptions or classification society rule harmonization delays could materially shift the outlook for marine adoption curves. Forecasts reflect assumptions about cell supply redirection, regulatory enforcement intensity, and channel disintermediation velocity in camping applications. A model refresh is warranted upon material change in automotive cell contract allocation or EU battery passport implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Medical Batteries Market
Batteries
Europe Industrial Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Denmark Rechargeable Battery Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Military Battery Market
Batteries
Global Solar Battery Charger Market
Batteries
Forklift Battery Rental Market
Batteries
Mobile Battery Market
Batteries
Vietnam Battery Market
Batteries
Europe Battery Cell Market
Batteries
Nickel-Based Battery Charger Market
Batteries
United States Household Battery Market