
 Disposable Hygiene Footwear Market | 2026-2036
Disposable Hygiene Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Hygiene Footwear Market Outlook
Modular packaging configurations in bulk dispensers and color-coded sizing systems is expanding buyer flexibility across healthcare and food processing channels. Kimberly-Clark leverages its institutional supply contracts to sustain volume leadership in North American hospital systems. DuPont anchors its position through advanced spunbond material science that differentiates its protective footwear from commodity polyethylene alternatives. Cardinal Health competes on distribution density, controlling direct-to-facility logistics that reduce inventory carrying costs for large clinical networks.
Disposable hygiene footwear encompasses single-use protective coverings manufactured from polyethylene films, spunbond polypropylene nonwovens, or laminated barrier fabrics, designed to prevent particulate and microbial transfer in controlled environments. These products typically feature elasticized ankle closures, skid-resistant sole treatments, and fluid-resistant seam constructions to meet ISO 22609 splash penetration standards. Shoe covers and booties dominate current revenue flows due to universal adoption across healthcare and cleanroom settings, while spunbond and nonwoven fabric grades command margin premiums over basic polyethylene variants. The food industry end-use segment is gaining structural importance as HACCP compliance mandates expand beyond processing floors into packaging and distribution zones.
FDA quality system regulations and OSHA bloodborne pathogen standards shape product design and validation protocols for US-manufactured and imported disposable footwear. The EU Medical Device Regulation and REACH chemical compliance frameworks govern market access for European distribution, while Germany's DIN standards and France's ANSM facility inspections create additional certification layers for premium suppliers. Stakeholders must monitor evolving cleanroom classification harmonization between ISO 14644 and US FED-STD-209E successor protocols, as divergence in particulate testing methods could fragment qualification requirements and reshape supplier competitive rankings.
Market Dynamics
Cleanroom classification harmonization between ISO 14644 and successor protocols is fragmenting supplier qualification requirements, forcing manufacturers to maintain parallel certification tracks for pharmaceutical and semiconductor buyers.
Growth Catalysts
- OSHA Bloodborne Pathogen Standards:US healthcare facilities face mandatory single-use protective apparel mandates in surgical and isolation environments, accelerating polyethylene and spunbond polypropylene consumption.
- Semiconductor Cleanroom Expansion:Taiwan, South Korea, and Germany are adding fabrication capacity requiring ISO Class 3-5 footwear protocols, creating premium-grade demand that commands material science investments.
- HACCP Compliance Extension:Food processing regulations now mandate protective coverings in packaging and cold-chain distribution zones, widening addressable market beyond traditional processing floors.
Market Restraints
- Petrochemical Input Volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil benchmarks, compressing margins for converters lacking long-term supply contracts.
- Asian Supply Concentration:Over 60% of spunbond nonwoven capacity sits in China and Southeast Asia, creating geographic risk exposure for buyers requiring just-in-time delivery.
- Biodegradation Performance Gap:Current compostable alternatives fail ISO 22609 splash penetration standards, limiting substitution in fluid-exposure applications.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO facility certification expansion and PLI scheme incentives are driving cleanroom infrastructure investment in Hyderabad and Ahmedabad clusters.
- Antimicrobial Additive Integration:Silver-ion and copper-nanoparticle surface treatments are converging with spunbond substrates to create differentiated infection-control products.
- E-commerce Direct Procurement:Hospital systems and food processors are bypassing traditional distribution layers through Amazon Business and specialized medical supply platforms.
Industry Challenges
- ISO 14644-1:2015 Transition Complexity:Facilities must recalibrate particulate monitoring equipment and retrain quality personnel during the 2015 revision adoption window.
- Cross-Contamination Validation Documentation:FDA quality system regulations require material traceability systems that many mid-tier converters lack the IT infrastructure to support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Hygiene Footwear Market |
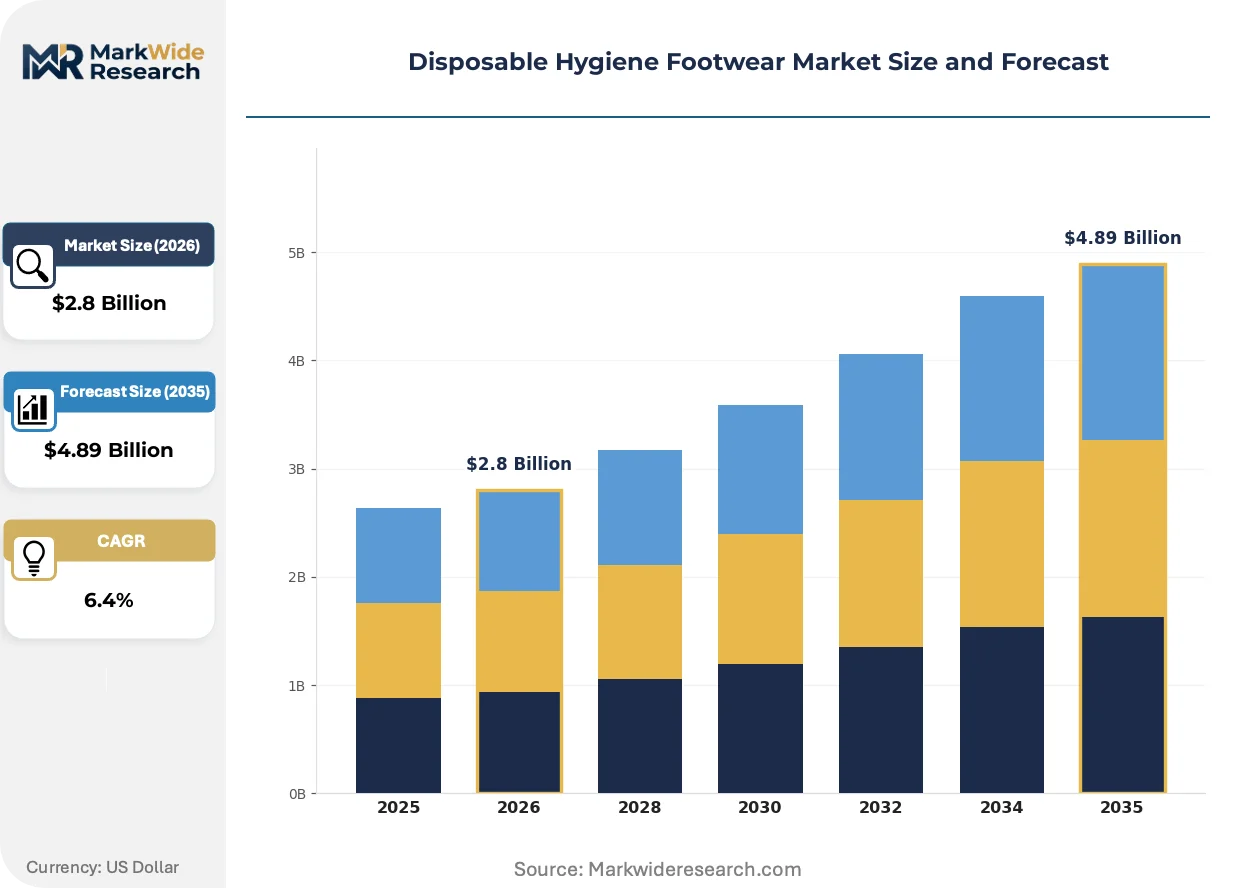
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoe Covers, Slippers, Overboots, Booties Material: Polyethylene, Spunbond, Nonwoven Fabric, Plastic End User: Healthcare, Food Industry, Cleanrooms, Hospitality Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Distributors |
| Companies Covered | 3M, DuPont, Honeywell International, Kimberly-Clark, Alpha Pro Tech, Ansell, Cardinal Health, Franz Mensch, Royal Shoe Covers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Hygiene Footwear Market Strategic Shifts
Material science advancement and procurement digitization are compressing product lifecycles while elevating performance thresholds across healthcare, food safety, and controlled manufacturing environments.
Spunbond-meltblown-spunbond (SMS) laminates are overtaking basic polyethylene films in surgical applications where fluid resistance and breathability must coexist. German and US hospital systems now specify SMS construction for operating theater footwear, compressing commodity polyethylene margins while rewarding barrier-fabric specialists with volume commitments and multi-year supply agreements.
REACH chemical compliance frameworks are tightening phthalate and heavy-metal restrictions in disposable protective apparel, forcing reformulation of elastic compounds and sole treatments. EU Medical Device Regulation technical documentation requirements are extending certification timelines, with French ANSM facility inspections now scrutinizing footwear as Class I medical devices in sterile processing departments.
Hospital system consolidation is compressing vendor lists and extending contract durations, with integrated delivery networks centralizing procurement decisions at regional headquarters. This concentration is displacing local distributors in favor of national contracts with direct logistics capabilities, most visible in US Midwest and Southeast health system alliances where three-year agreements now predominate over spot purchasing.
Disposable Hygiene Footwear Market Segmentation
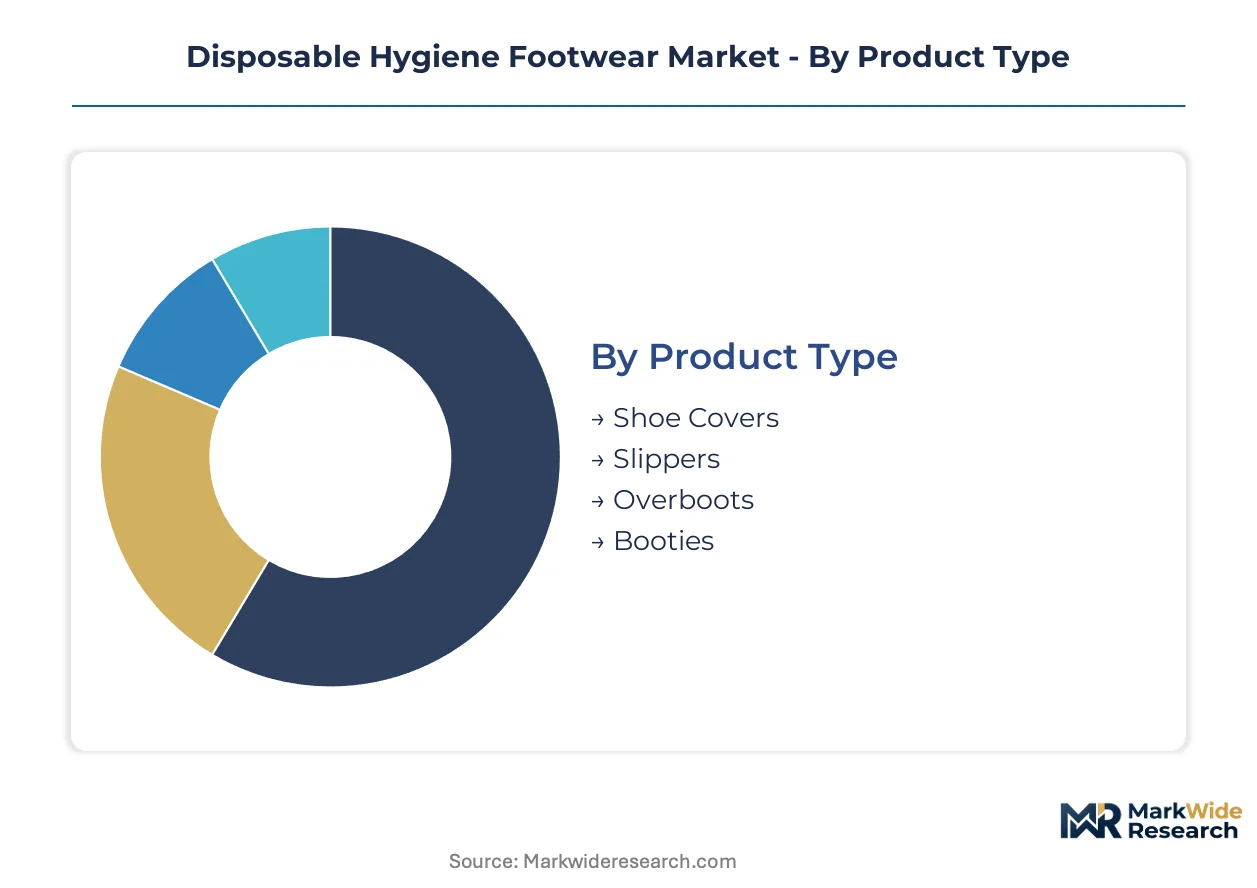
Segmentation in disposable hygiene footwear reveals divergent margin structures across material grades and end-use compliance thresholds. Product managers allocate R&D budgets toward spunbond laminates in surgical applications while defending polyethylene volumes in food processing and general healthcare.
Product Type:
Volume leadership sits with universal-fit coverings, while premium margins concentrate in specialized surgical and cleanroom designs.
- Shoe Covers:Elasticized ankle closures and skid-resistant sole treatments define this polyethylene-dominant category. US hospital systems and German pharmaceutical facilities drive procurement of ISO 22609-compliant variants for operating theater use.
- Booties:SMS laminate construction commands price premiums in semiconductor cleanrooms requiring ISO Class 3-5 particulate control. Taiwan and South Korea fabrication capacity expansion is accelerating specification upgrades beyond basic polyethylene.
- Slippers:Closed-toe designs with enhanced sole grip serve extended-wear applications in hospitality and outpatient clinics.
- Overboots:Extended calf coverage targets chemical processing and agricultural biosecurity zones with fluid-resistant seam sealing.
Today's leader: Shoe Covers. Tomorrow's challenger: Booties.
Material:
Cost tiers separate commodity resins from engineered barrier fabrics with validated traceability documentation.
- Spunbond:Meltblown interlayers create breathable fluid barriers that satisfy FDA quality system regulations for surgical environments. German DIN EN ISO 14644 cleanroom standards and US hospital procurement specifications are converging on SMS construction.
- Polyethylene:Blown-film extrusion delivers lowest unit cost for high-volume food processing and general healthcare applications. OSHA bloodborne pathogen compliance mandates sustain baseline demand despite margin compression.
- Nonwoven Fabric:Carded thermal-bonded structures serve cost-sensitive institutional buyers with moderate fluid exposure risk.
- Plastic:Rigid injection-molded clogs and sandals address reusable-equipment substitution in wet-processing environments.
Spunbond claims the steepest expansion trajectory as certification requirements tighten.
End User:
Application-specific compliance mandates fragment procurement specifications across regulated industries.
- Healthcare:Surgical centers and isolation wards require FDA-validated single-use apparel with material traceability systems. US integrated delivery networks are consolidating vendor lists toward direct-contract suppliers.
- Cleanrooms:Pharmaceutical and semiconductor manufacturing impose ISO 14644-1:2015 particulate limits that exclude commodity polyethylene. Germany and France lead European specification stringency through ANSM facility inspections.
- Food Industry:HACCP extension into packaging and distribution zones widens addressable market beyond traditional processing floors.
- Hospitality:Spa and wellness applications prioritize guest-perceived hygiene over regulatory compliance, enabling cost-optimized procurement.
Healthcare generates current volume concentration. Cleanrooms deliver margin expansion.
Distribution Channel:
Channel selection determines working capital requirements and customer relationship depth.
- Distributors:Cardinal Health and regional medical supply networks control direct-to-facility logistics that reduce inventory carrying costs for large clinical systems.
- Online Retail:Amazon Business and specialized medical platforms enable hospital systems to bypass traditional distribution layers for standardized products.
- Specialty Stores:Cleanroom outfitters provide application engineering support for semiconductor and pharmaceutical buyers requiring protocol consultation.
- Wholesalers:Bulk packaging configurations serve food processors and hospitality chains with predictable consumption patterns.
Distributors retain contract complexity. Online Retail captures standard product migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Disposable hygiene footwear manufacturing first achieved industrial scale in the United States during the 1960s hospital infection-control movement, with subsequent process innovation spreading to German cleanroom engineering clusters and East Asian semiconductor fabrication corridors.
United States
OSHA bloodborne pathogen standards and FDA quality system regulations sustain procurement volumes across integrated delivery networks. Hospital system consolidation in the Midwest and Southeast has compressed vendor lists toward direct-contract suppliers with logistics capabilities. The Greater Boston and Research Triangle Park pharmaceutical clusters drive premium-grade spunbond specifications for sterile processing environments.
Germany
DIN EN ISO 14644 cleanroom standards and ANSM-aligned facility inspections create the world's most stringent footwear certification requirements. Bavaria and Baden-Württemberg pharmaceutical manufacturing corridors absorb disproportionate volumes of SMS laminate booties. The Eindhoven-Frankfurt semiconductor axis extends demand into neighboring jurisdictions.
China
NMPA medical device registration requirements and GB standard harmonization efforts are upgrading domestic production quality. Yangtze River Delta electronics manufacturing clusters in Suzhou and Wuxi now specify ISO Class 5 footwear for advanced packaging facilities. Zhejiang and Jiangsu provinces concentrate spunbond nonwoven conversion capacity serving both export and domestic hospital procurement.
India
CDSCO facility certification expansion and PLI scheme incentives are accelerating cleanroom infrastructure investment. Hyderabad and Ahmedabad pharmaceutical clusters now require disposable footwear meeting EU MDR-equivalent standards for export-oriented production. Karnataka and Maharashtra states lead contract manufacturing organization facility construction.
South Korea
MFDS medical device quality regulations and national semiconductor self-sufficiency initiatives are tightening procurement specifications. Busan-Ulsan and Daejeon-Sejong fabrication corridors require ISO Class 3-4 footwear protocols for advanced node production. Government-funded cleanroom construction is outpacing regional supplier qualification capacity.
Disposable Hygiene Footwear Market Competitive Environment
Premium-margin players sit above commodity-margin players across material science and certification documentation capabilities. The vendor base separates into three tiers: multinational diversified healthcare suppliers with institutional contract infrastructure, specialized cleanroom outfitters with application engineering depth, and regional converters competing on polyethylene unit economics. Strategic moves concentrate on backward integration into spunbond nonwoven production and direct-to-facility logistics investments that displace traditional distribution layers.
Within the diversified healthcare supplier tier, 3M, DuPont, and Kimberly-Clark exemplify distinct competitive positioning. 3M occupies a position anchored in adhesive and filtration material science that extends into footwear barrier applications. DuPont represents the advanced polymer archetype with spunbond manufacturing capabilities that differentiate from commodity alternatives. Kimberly-Clark sits within the institutional supply infrastructure tier, leveraging distribution density and hospital system contract relationships. These three entities collectively demonstrate how material science investment and procurement channel control define sustainable competitive position in regulated end-use segments.
| Leading Market Players |
|---|
| 3M |
| DuPont |
| Honeywell International |
| Kimberly-Clark |
| Alpha Pro Tech |
| Ansell |
| Cardinal Health |
| Franz Mensch |
| Royal Shoe Covers |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap converters across Zhejiang and Jiangsu provinces anchor polyethylene film production, their consolidated ownership patterns enabling rapid capacity adjustments that buffer spot-price volatility while constraining premium-grade spunbond investment. This supply-side fragmentation compresses margins at the commodity tier even as ISO-certified specialists capture pricing power through material traceability documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SMS laminate booties from spunbond shoe covers and basic polyethylene films. Price differentiation hinges on ISO 14644-1:2015 certification grade and FDA-validated material traceability systems. Cost compression in the polyethylene tier is intensifying because Chinese resin oversupply and Indian import substitution are eroding regional premium capture. Food processors exhibit highest price sensitivity, while semiconductor cleanroom buyers absorb premium markups for particulate-control validation.
Supply Chain Analysis
Direct-to-facility channels handle hyperscale hospital system demand, displacing traditional distributor layers through Cardinal Health and Amazon Business procurement platforms. Raw material supply draws from Chinese polyethylene resin capacity, German spunbond nonwoven engineering, and Taiwanese meltblown interlayer production. Tariff exposure on Chinese-manufactured spunbond imports creates margin vulnerability for US converters lacking alternative sourcing. Distribution runs through integrated delivery networks in the US Midwest and Southeast, regional medical supply wholesalers in Europe, and specialized cleanroom outfitters serving semiconductor corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Semiconductor fabrication expansion in Taiwan and South Korea is shifting procurement specifications toward ISO Class 3-5 bootie grades that command material science premiums.
For Market Incumbents: Anticipate margin compression in polyethylene shoe covers as Indian pharmaceutical manufacturing scales domestic conversion capacity. Defend position by deepening backward integration into spunbond nonwoven production and securing multi-year direct contracts with US integrated delivery networks. Prioritize certification investment for EU MDR-equivalent documentation to access Indian export-oriented facilities. For New Entrants and Emerging Players: Capture whitespace in antimicrobial additive integration, where silver-ion surface treatments on spunbond substrates remain underdeveloped relative to surgical glove and drape applications. Target Indian pharmaceutical clusters in Hyderabad and Ahmedabad, where CDSCO facility certification expansion outpaces qualified domestic footwear suppliers. Lead with e-commerce direct procurement partnerships that bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Diversified healthcare suppliers with institutional contract infrastructure are the most active acquirer in this space, seeking spunbond manufacturing capabilities and direct-to-facility logistics assets. Long-term viability centers on consolidation plays that combine material science depth with procurement channel control. Watch for divergence between ISO 14644 and successor cleanroom protocols as the signal for qualification fragmentation that reshapes supplier competitive rankings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spunbond Production | Captive SMS laminate supply secures margin capture from semiconductor cleanroom demand in Taiwan and Germany. |
| Antimicrobial Additive Integration | Silver-ion surface treatments differentiate infection-control products for US surgical center procurement. |
| E-Commerce Direct Procurement Partnership | Amazon Business and specialized medical platforms displace traditional distribution layers for standardized products. |
| EU MDR-Equivalent Certification Investment | CDSCO-aligned documentation unlocks Indian pharmaceutical export manufacturing in Hyderabad clusters. |
| Cleanroom Protocol Harmonization Monitoring | Early positioning for ISO 14644 successor standards prevents qualification fragmentation in semiconductor supply. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and cleanroom facility engineers with secondary validation against FDA 510(k) filings, EU MDR technical documentation, customs trade data, and hospital procurement databases. Bottom-up facility-level demand modeling and top-down resin consumption analysis provided cross-verification.
Segment-weighting across material grade, end-use compliance threshold, and distribution channel density structured the analytical framework over the projection horizon. CAGRs derived from facility expansion pipelines, regulatory mandate adoption curves, and substitution elasticity between polyethylene and spunbond specifications. Modeled inputs included OSHA bloodborne pathogen enforcement intensity, semiconductor fabrication capacity announcements, and HACCP compliance extension timelines.
Petrochemical input volatility, cleanroom protocol divergence, and hospital system consolidation velocity are the dominant revision risks to modeled outputs across the analysis window. Forecasts reflect documented assumptions regarding regulatory harmonization trajectories and substitution technology maturation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
China Pollution Mask Market
Protective Gear
Flavored Condoms Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Work Shoes Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Earplug Distributor Market
Protective Gear
Hand Gloves Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Boxed Glove for Food Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Cooking Gloves Market
Protective Gear
Tactical Boots Market
Protective Gear
Dust Covers Market
Protective Gear
Earplugs Market
Protective Gear
Europe Protective Footwear Market