
 Tissue and Hygiene Market | 2026-2036
Tissue and Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue and Hygiene Market Outlook
Aftermarket service revenue from dispenser maintenance and hygiene compliance auditing is reshaping margin pools away from pure product sales in the commercial tissue sector. Procter & Gamble leverages its North American manufacturing scale to dominate institutional contracts. Essity Aktiebolag anchors European sustainability premiums through certified fiber sourcing. Kimberly-Clark Corporation competes in Asia-Pacific through localized product formats tailored to smaller bathroom footprints.
Tissue and hygiene encompasses absorbent paper products and non-woven disposables engineered from virgin pulp, recycled fibers, or bamboo derivatives with basis weights typically ranging from 15 to 40 grams per square meter, manufactured through wet-laid creping or air-laid bonding processes for moisture absorption and single-use sanitation. Facial tissue commands premium shelf positioning in supermarkets due to lotion-infused and hypoallergenic variants, while bamboo-based toilet paper captures fastest-growing material share as consumers reject plastic packaging. Online retail channels now challenge wholesale dominance in household replenishment, though hotels and restaurants remain locked into long-term distributor contracts for paper towels and napkins.
The EPA's Safer Choice program and EU Ecolabel certification constrain bleach chemistry and post-consumer recycled content claims in the United States and European markets, compelling reformulation investments. China's SAMR enforces GB standards for microbial limits in tissue contacting skin or food surfaces. Stakeholders must monitor how fragmented national packaging laws alter export compliance costs versus the consolidation savings of regional hub production.
Market Dynamics
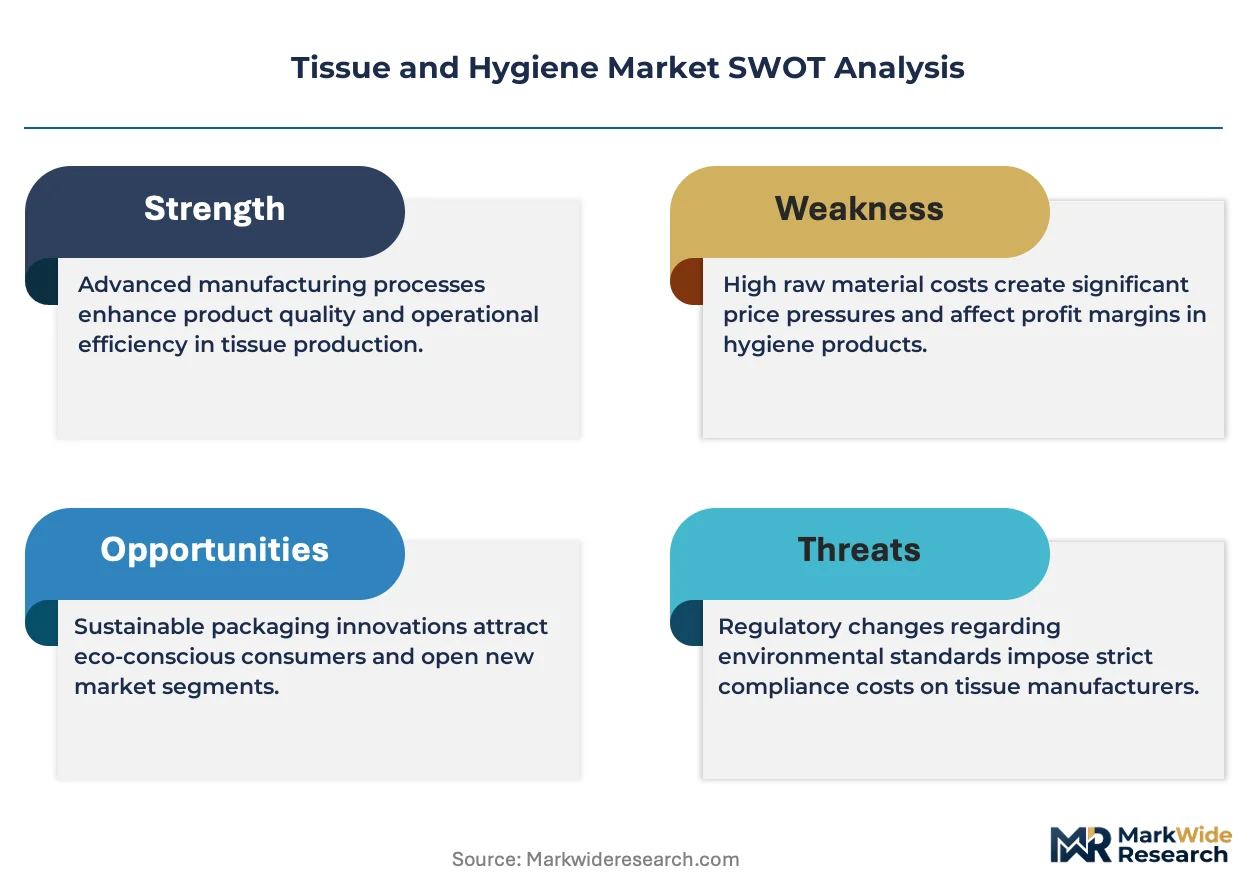
The EU Green Deal's single-use plastic restrictions are redirecting capital toward biodegradable pulp alternatives, compressing legacy polymer-based product lines while opening margin pools for fiber innovators.
Growth Catalysts
- EU Ecolabel certification:Hotels and restaurants across Germany, France, and Italy now mandate certified fiber sourcing for procurement contracts, pulling premium-grade tissue volumes upward.
- Bamboo derivative materials:Southeast Asian urban centers are upgrading from unbranded to packaged tissue products, with bamboo-based toilet paper capturing fastest-growing material share as consumers reject plastic packaging.
- Aftermarket service revenue:Dispenser maintenance and hygiene compliance auditing is reshaping margin pools away from pure product sales in the commercial tissue sector.
Market Restraints
- Virgin pulp price volatility:Input cost swings in Brazilian and Indonesian pulp markets compress margins for manufacturers locked into long-term distributor contracts.
- China's SAMR microbial limits:GB standards enforcement creates export friction for tissue contacting skin or food surfaces, extending compliance timelines by 8-14 months.
- Recycled fiber quality ceiling:Post-consumer recycled content claims face EPA Safer Choice program constraints, limiting product performance in premium facial tissue segments.
Strategic Opportunities
- India's PLI scheme for manufacturing:Incentives for domestic absorbent paper production create white space for regional hub consolidation serving South Asian demand.
- Online retail channel expansion:E-commerce platforms are challenging wholesale dominance in household replenishment, enabling direct-to-consumer subscription models.
- Wet-laid creping process automation:Convergence of sensor-based quality control with predictive maintenance is digitizing yield optimization in basis weight production.
Industry Challenges
- Specialized fiber sourcing expertise:Certified sustainable supply chain management requires talent scarce outside Nordic and North American pulp regions.
- Legacy dispenser infrastructure integration:Smart hygiene monitoring systems face retrofit complexity with existing commercial building plumbing specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue and Hygiene Market |
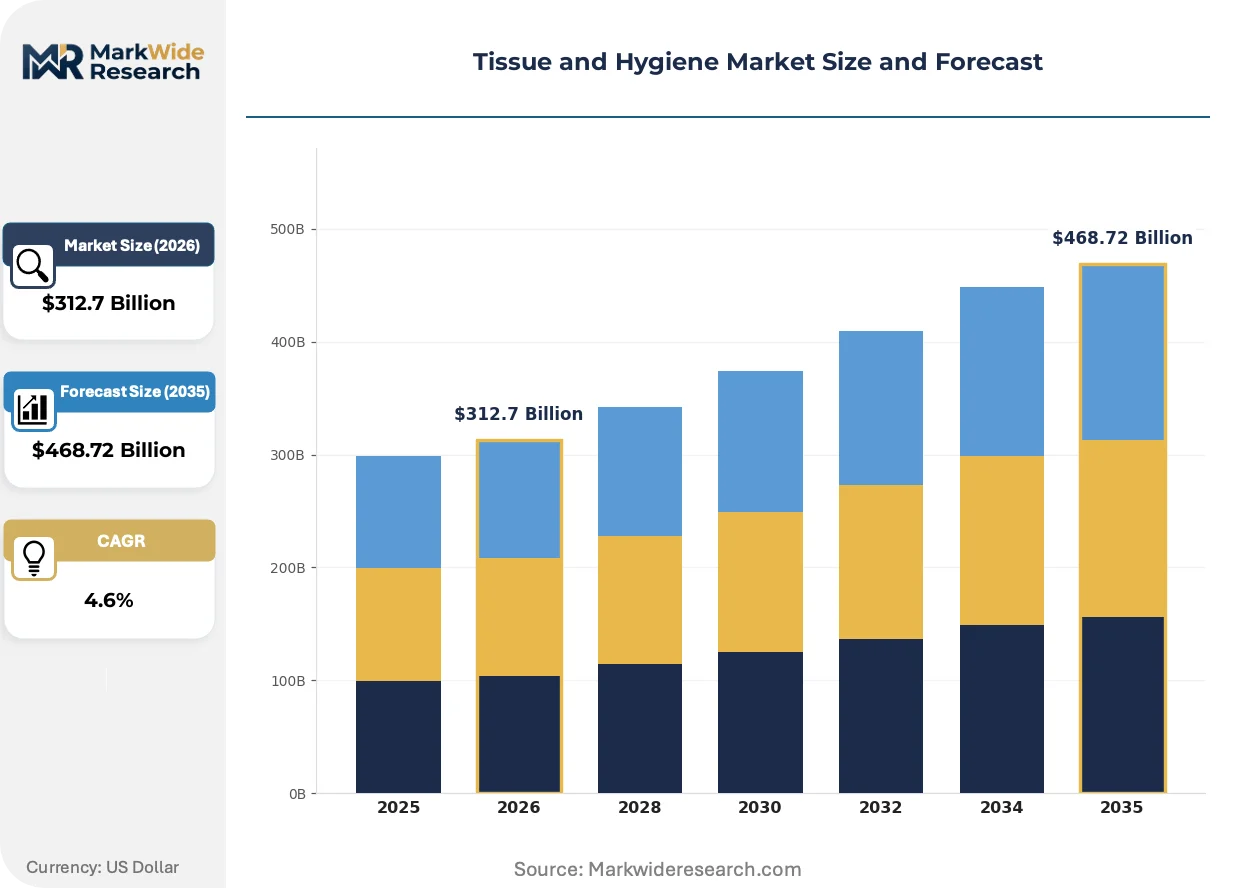
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $468.72 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Tissue, Toilet Paper, Paper Towels, Napkins End User: Households, Hotels, Restaurants, Schools Material: Pulp, Recycled Paper, Non-Woven Fabrics, Bamboo Sales Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Essity Aktiebolag, Georgia-Pacific, Sofidel, Hengan International Group Company Ltd., Unicharm Corporation, WEPA Hygieneprodukte GmbH, Kruger Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue and Hygiene Market Strategic Shifts
Sensor-enabled dispensers and blockchain-tracked fiber provenance are compressing traditional supply chain opacity, while regulatory chemistry constraints force reformulation investments.
Smart dispensing systems equipped with fill-level sensors and usage analytics are digitizing restocking logistics for facility management providers. Marriott and Hilton properties in Singapore and Dubai now pilot these systems, reducing linen service labor allocation by predictive consumption modeling. The technology is digitizing aftermarket revenue capture, converting capital equipment into recurring software-subscription relationships.
REACH restrictions on bleach chemistry are compelling European manufacturers to shift toward elemental chlorine-free and totally chlorine-free processing lines. Industrial consequence includes 15-25% capacity retrofit requirements at mills serving EU Ecolabel contracts. Premium facial tissue segments in Germany and the Netherlands respond fastest, with lotion-infused variants reformulating around peroxide-based whitening.
Subscription-based replenishment models displace periodic wholesale purchasing among urban households in Tokyo, Seoul, and Sydney. Direct-to-consumer platforms capture share from supermarket shelf replenishment, particularly for hypoallergenic and bamboo-based product variants. This channel rotation is most visible in apartment-dense districts where delivery logistics cost structures favor consolidated drop scheduling over individual store trips.
Tissue and Hygiene Market Segmentation
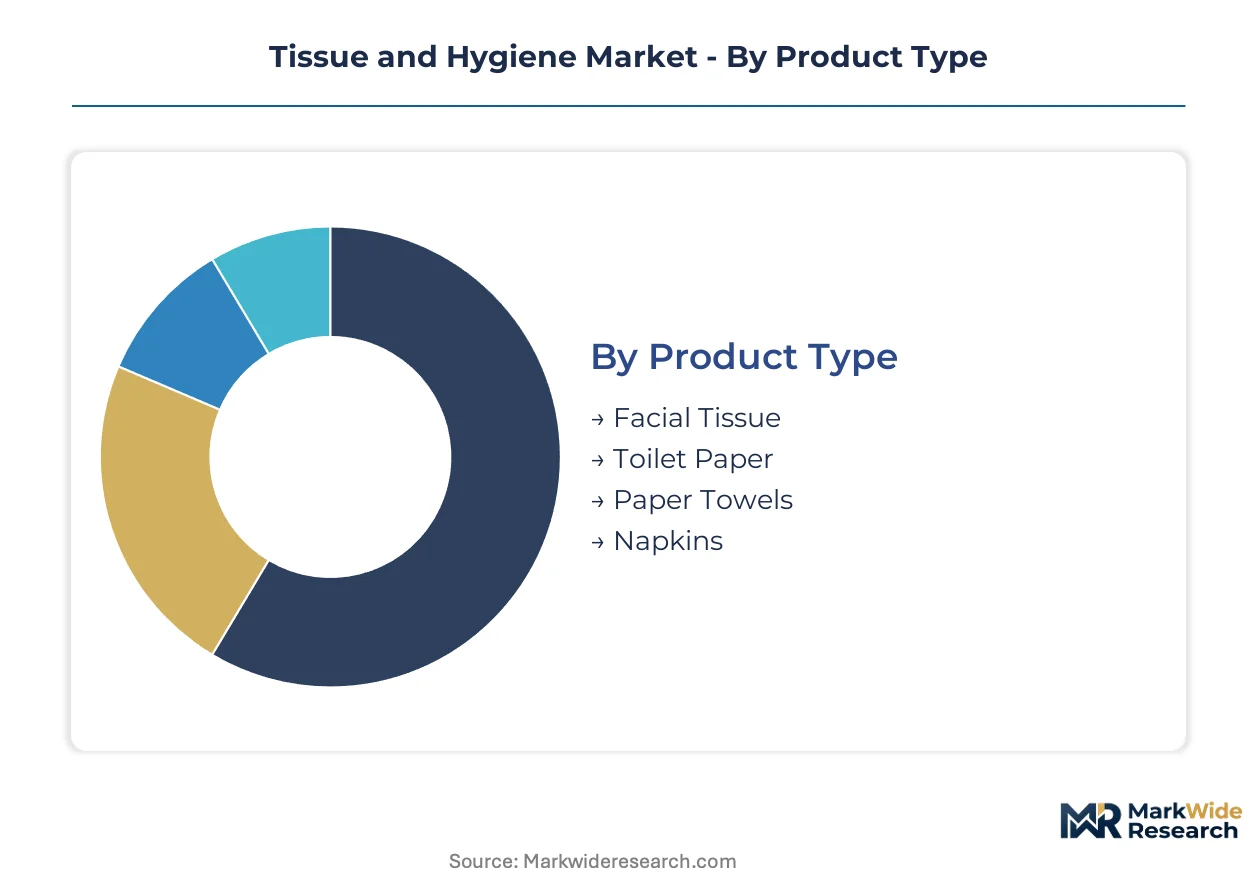
Segmentation in tissue and hygiene reveals how procurement logic splits between cost-sensitive institutional buyers and premium-seeking household consumers. Material sourcing certifications and channel economics determine margin capture across each divide.
Product Type:
Cost tier differentiation separates commodity basics from performance-engineered formats commanding shelf positioning premiums.
- Toilet Paper:Virgin pulp and bamboo derivatives dominate roll construction with basis weights of 15-25 gsm. Hotels and restaurants across Germany, France, and Italy now mandate EU Ecolabel-certified fiber sourcing, pulling premium-grade volumes upward as procurement contracts tighten compliance requirements.
- Facial Tissue:Lotion-infused and hypoallergenic variants utilize air-laid bonding for enhanced softness. Southeast Asian urban centers are upgrading from unbranded to packaged tissue products, with facial tissue capturing fastest-growing premium positioning as middle-class consumers reject plastic packaging.
- Paper Towels:Wet-laid creping processes deliver absorbency for food service and facility maintenance. EPA Safer Choice program constraints on bleach chemistry compel reformulation investments at mills serving institutional contracts.
- Napkins:Lower basis weight construction targets single-use food service applications. Long-term distributor contracts lock hotels and restaurants into volume commitments that resist channel switching.
Toilet paper holds installed capacity. Facial tissue is rotating up the share rankings.
End User:
Application context dictates performance specifications, compliance burdens, and aftermarket service attachment rates.
- Hotels:Smart dispensing systems with fill-level sensors and usage analytics digitize restocking logistics. Marriott and Hilton properties in Singapore and Dubai pilot these systems, reducing linen service labor allocation through predictive consumption modeling.
- Households:Subscription-based replenishment models displace periodic wholesale purchasing in Tokyo, Seoul, and Sydney. Direct-to-consumer platforms capture share from supermarket shelf replenishment, particularly for hypoallergenic and bamboo-based variants.
- Restaurants:EU Green Deal single-use plastic restrictions redirect procurement toward biodegradable pulp alternatives. Certified fiber sourcing mandates compress legacy polymer-based napkin and paper towel lines.
- Schools:Budget-constrained institutional purchasing prioritizes volume scale over premium features. China's SAMR microbial limits create export friction for tissue contacting skin, extending compliance timelines.
Hotels anchor aftermarket service revenue. Households are climbing the fastest as e-commerce penetration deepens.
Material:
Supply concentration and sustainability certification premiums stratify input cost structures across manufacturing bases.
- Pulp:Virgin softwood and hardwood fibers from Brazilian and Indonesian markets supply wet-laid creping operations. Price volatility in these sourcing regions compresses margins for manufacturers locked into long-term distributor contracts.
- Bamboo:Fastest-expanding material category leverages Southeast Asian plantation expansion. Consumers rejecting plastic packaging drive demand concentration in urban centers upgrading from unbranded to packaged tissue products.
- Recycled Paper:Post-consumer fiber claims face EPA Safer Choice program and EU Ecolabel constraints on bleach chemistry. Quality ceilings limit performance in premium facial tissue segments requiring hypoallergenic specifications.
- Non-Woven Fabrics:Air-laid bonding processes serve industrial and medical hygiene applications outside core tissue markets. REACH restrictions on chemical processing compel European manufacturers toward elemental chlorine-free lines.
Pulp retains dominant input share. Bamboo is gaining share fastest as sustainability premiums harden.
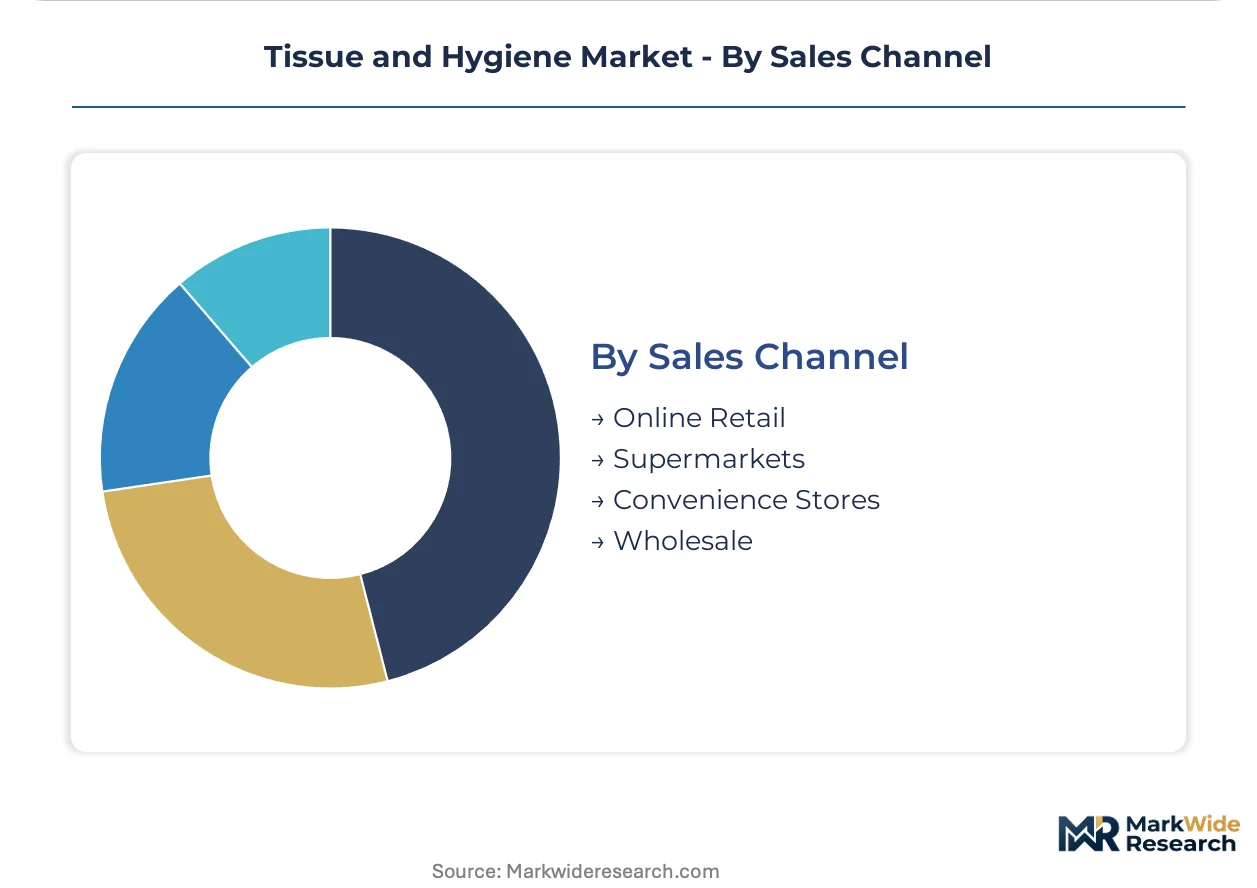
Sales Channel:
Customer type and purchase frequency determine logistics economics and margin capture mechanisms.
- Online Retail:Subscription models consolidate replenishment cycles for urban apartment households. Delivery logistics cost structures in dense districts favor consolidated drop scheduling over individual store trips.
- Wholesale:Long-term distributor contracts lock hotels and restaurants into volume commitments for paper towels and napkins. Aftermarket service revenue from dispenser maintenance reshapes margin pools away from pure product sales.
- Supermarkets:Facial tissue commands premium shelf positioning due to lotion-infused variant differentiation. Retail channel rotation is most visible where e-commerce platforms challenge wholesale dominance in household replenishment.
- Convenience Stores:Emergency and travel-size tissue purchases capture impulse demand with minimal brand loyalty. Limited SKU depth restricts premium product penetration.
Wholesale maintains institutional lock-in. Online retail is expanding most quickly as subscription mechanics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hotel procurement mandates EU Ecolabel-certified fiber sourcing, while Indonesian pulp mills supply wet-laid creping operations with volatile pricing. Chinese GB standards enforcement extends compliance timelines for skin-contact exports.
United States
EPA Safer Choice program constraints on bleach chemistry compel reformulation investments at mills serving institutional contracts. Marriott and Hilton properties pilot smart dispensing systems with fill-level sensors in Florida and Texas. Subscription-based replenishment models displace wholesale purchasing among urban households in New York and California.
Germany
REACH restrictions on chemical processing drive European manufacturers toward elemental chlorine-free processing lines. EU Ecolabel certification mandates pull premium-grade tissue volumes upward across procurement contracts. Industrial clusters in North Rhine-Westphalia and Bavaria retrofit 15-25% of capacity to serve certified fiber sourcing requirements.
China
SAMR microbial limits for tissue contacting skin or food surfaces create export friction extending compliance timelines. Middle-class consumers in Shanghai and Beijing upgrade from unbranded to packaged tissue products. Yangtze River Delta manufacturing bases face quality ceiling constraints on post-consumer recycled content claims.
Indonesia
Virgin pulp price volatility in Brazilian and Indonesian markets compresses margins for manufacturers locked into long-term distributor contracts. Plantation expansion in Sumatra and Kalimantan feeds fastest-growing bamboo derivative material share. Jakarta and Surabaya urban centers drive demand concentration as consumers reject plastic packaging.
India
PLI scheme incentives for domestic absorbent paper production create white space for regional hub consolidation. BIS standards enforcement shapes microbial limit compliance for tissue products. Maharashtra and Gujarat industrial corridors attract manufacturing investment serving South Asian demand.
Tissue and Hygiene Market Competitive Environment
Capability concentration sits with fiber innovators and certified sourcing specialists; scale advantage sits with North American manufacturing bases and European sustainability premiums. The vendor base organizes around three strategic archetypes: integrated pulp-to-product multinationals, regional hygiene specialists with localized formats, and bamboo-based sustainability challengers. Dominant competitive moves include capacity retrofit investments for elemental chlorine-free processing lines and strategic partnerships for smart dispenser infrastructure integration.
Among integrated pulp-to-product multinationals, Procter & Gamble and Kimberly-Clark Corporation represent scale-driven positioning anchored in North American manufacturing bases. Essity Aktiebolag occupies a position exemplifying European sustainability premium capture through certified fiber sourcing. These three entities sit within the tier where aftermarket service revenue from dispenser maintenance reshapes margin pools away from pure product sales.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Essity Aktiebolag |
| Georgia-Pacific |
| Sofidel |
| Hengan International Group Company Ltd. |
| Unicharm Corporation |
| WEPA Hygieneprodukte GmbH |
| Kruger Inc. |
| Others |
Value Chain & Pricing Dynamics
Brazilian and Indonesian pulp concentration anchors margin capture downstream, with wet-laid creping mills in these regions supplying basis-weight production that feeds contract-locked institutional buyers and subscription-channel household replenishment.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement for hotels and restaurants, while spot purchasing governs emergency replenishment through convenience retail. Three-tier pricing structure across premium, standard, and economy levels separates EU Ecolabel-certified fiber from elemental chlorine-free grades and unbranded commodity rolls. Cost compression in virgin pulp tiers is intensifying because Brazilian and Indonesian supply volatility feeds directly into manufacturer margin pressure. Budget-constrained schools and municipal institutions exhibit highest price sensitivity; premium facial tissue segments in Germany and the Netherlands show lowest elasticity due to lotion-infused reformulation loyalty.
Supply Chain Analysis
Extended payment terms from Indonesian pulp mills to European converters compress working capital cycles across the value chain. Supply concentrates in Brazil, Indonesia, and Nordic regions for virgin softwood fiber, with bamboo plantation expansion accelerating in Sumatra and Kalimantan. Wet-laid creping operations draw from hardwood and softwood pulp grades, while air-laid bonding feeds facial tissue softness specifications. Single-source vulnerability concentrates in Indonesian pulp corridors exposed to plantation climate risk. Distribution runs through long-term distributor contracts for institutional buyers and direct-to-consumer platforms for household subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as Southeast Asian middle-class consumers upgrade from unbranded to packaged tissue products, with smart dispenser digitization creating recurring revenue attachment in commercial channels.
For Market Incumbents: Pre-empt bamboo-based sustainability challengers by securing certified fiber sourcing contracts ahead of EU Green Deal procurement mandates tightening across German, French, and Italian hospitality. Accelerate wet-laid creping automation with sensor-based quality control to defend yield position against regional hub consolidation in India. Backward integration into Sumatra plantation networks reduces exposure to virgin pulp price volatility compressing long-term contract margins. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point for smart hygiene monitoring systems facing retrofit complexity with legacy dispenser infrastructure. Direct-to-consumer subscription models for hypoallergenic and bamboo-based variants capture share from supermarket shelf replenishment in Tokyo, Seoul, and Sydney apartment-dense districts. Channel partnerships with facility management providers enable aftermarket service revenue capture without capital-intensive manufacturing scale. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional hygiene specialists possessing localized product formats but lacking certified fiber sourcing expertise scarce outside Nordic and North American pulp regions. Five-to-ten year viability hinges on elemental chlorine-free processing line retrofit completion serving EU Ecolabel contract volumes. Watch for inflection in China's SAMR microbial limit enforcement timelines extending compliance friction for skin-contact tissue exports.| Strategic Initiative | Industry Significance |
|---|---|
| Elemental Chlorine-Free Processing Retrofit | REACH restrictions force 15-25% capacity conversion at EU-serving mills. |
| Smart Dispenser Infrastructure Integration | Marriott and Hilton pilot programs digitize restocking logistics in Singapore and Dubai. |
| Certified Fiber Sourcing Partnership | EU Ecolabel mandates pull premium-grade tissue volumes upward across German procurement. |
| Bamboo Plantation Supply Control | Sumatra and Kalimantan expansion feeds fastest-growing material share as consumers reject plastic. |
| Direct-to-Consumer Subscription Launch | Urban household replenishment in Tokyo and Seoul displaces wholesale dominance. |
Study Parameters
Cross-validation between primary interviews with pulp procurement directors, mill operations managers, hotel facility executives, and retail category buyers anchors the qualitative findings against secondary validation from customs trade data, SEC 10-K filings, EU Ecolabel certification databases, and pulp futures exchange records. Bottom-up demand modeling triangulates with top-down market sizing across wet-laid creping and air-laid bonding process segments.
Calibration against historical volume trajectories and capacity utilization rates at Brazilian and Indonesian pulp mills shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, end-user application, material sourcing tier, and sales channel mechanics. CAGRs derive from installed capacity expansion schedules, regulatory compliance timeline shifts, and e-commerce penetration curves in urban household replenishment.
Macroeconomic conditions sit as an overlay; deviation in pulp commodity pricing, freight rate volatility, or currency fluctuations across Southeast Asian manufacturing corridors would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby and Toddler Feeding Products and Accessories Market
Baby Products
Global Baby Mattresses Market
Baby Products
Baby Pacifier Market
Baby Products
Baby High Chair Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Kids Training Pant Market
Baby Products
Pregnancy Products Market
Baby Products
Baby Tableware Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Baby Swing Market
Baby Products
Canada Baby Care Products Market
Baby Products
US Baby Care Products Market
Baby Products
Baby Care and Mother Care Market
Baby Products
Soft Sole Baby Shoes Market