
 Work Shoes Market | 2026-2036
Work Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Work Shoes Market Analytics
Asset-light leasing models for industrial safety footwear is rewriting competitive dynamics, allowing smaller contractors to access certified protective equipment without capital outlay. Red Wing leverages its domestic manufacturing footprint to sustain premium positioning in unionized trades. Timberland PRO competes through direct-to-worksite distribution, while Caterpillar anchors its portfolio with composite-toe technology for energy-sector buyers.
Work shoes are engineered protective footwear constructed with reinforced toe caps, slip-resistant outsoles, and puncture-resistant midsoles, designed to shield workers from impact, compression, and electrical hazards in occupational environments. Leather and synthetic materials dominate construction, with leather commanding margin pools in premium tiers and synthetics gaining ground in lightweight healthcare applications. Composite-toe products lead volume in manufacturing and electrical trades where metal detection matters, while slip-resistant outsoles anchor demand in hospitality and food processing floors where OSHA-recordable slips drive replacement frequency.
ASTM International sets baseline impact and compression standards under F2413, while OSHA mandates hazard assessment and protective equipment provision under 29 CFR 1910.132, directly shaping procurement volume and specification requirements across U.S. industrial employers. The U.S. Department of Labor's enforcement posture on foot protection violations influences replacement cycle timing and brand compliance documentation. Stakeholders must monitor evolving state-level safety mandates and material sustainability disclosures as procurement criteria expand beyond baseline protection.
Market Dynamics
Leasing models for certified protective footwear are compressing capital barriers for smaller contractors while forcing traditional manufacturers to defend premium positioning through domestic production and direct-to-worksite logistics networks.
Growth Catalysts
- OSHA Enforcement Posture:Federal foot protection violation penalties accelerate replacement cycles across manufacturing and logistics employers. Inspection frequency in high-hazard industries sustains baseline procurement volume.
- Composite-Toe Adoption:Non-metallic toe caps penetrate electrical trades and secure facilities where metal detection protocols operate. Lighter weight drives worker acceptance and compliance rates.
- Food Processing Slips:Recordable slip incidents in hospitality and processing floors mandate specialized outsole specifications. Insurance carriers tie premium reductions to documented footwear programs.
Market Restraints
- Leather Input Volatility:Hide supply fluctuations and tanning capacity constraints compress margins for premium-tier manufacturers. Price hedging remains underdeveloped among mid-tier suppliers.
- Certification Concentration:ASTM F2413 testing infrastructure clusters in North American laboratories. Overseas manufacturers face extended validation timelines and shipping costs for compliance documentation.
- Synthetic Durability Ceiling:Healthcare and lightweight applications accept shorter product lifecycles. Industrial buyers resist synthetic uppers in heavy-abrasion environments despite weight advantages.
Strategic Opportunities
- State-Level Mandate Expansion:California and Washington propose safety footwear requirements beyond federal OSHA baselines. Early compliance positioning captures specification influence with state procurement officers.
- Healthcare Lightweight Segments:Extended-shift nursing and veterinary applications reward sub-500-gram constructions. Current industrial-focused portfolios underpenetrate these fatigue-sensitive roles.
- Worksite Direct Distribution:Employer-sponsored fitting programs bypass retail markup and size-availability friction. Union hiring halls and staffing agencies present consolidated access points.
Industry Challenges
- Metatarsal Guard Integration:Extended protection zones complicate last design and fit consistency. Returns and rework consume margin in made-to-order channels.
- Multi-Site Standardization:National employers struggle to harmonize specifications across state-regulated subsidiaries. Procurement fragmentation erodes volume leverage with suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Work Shoes Market |
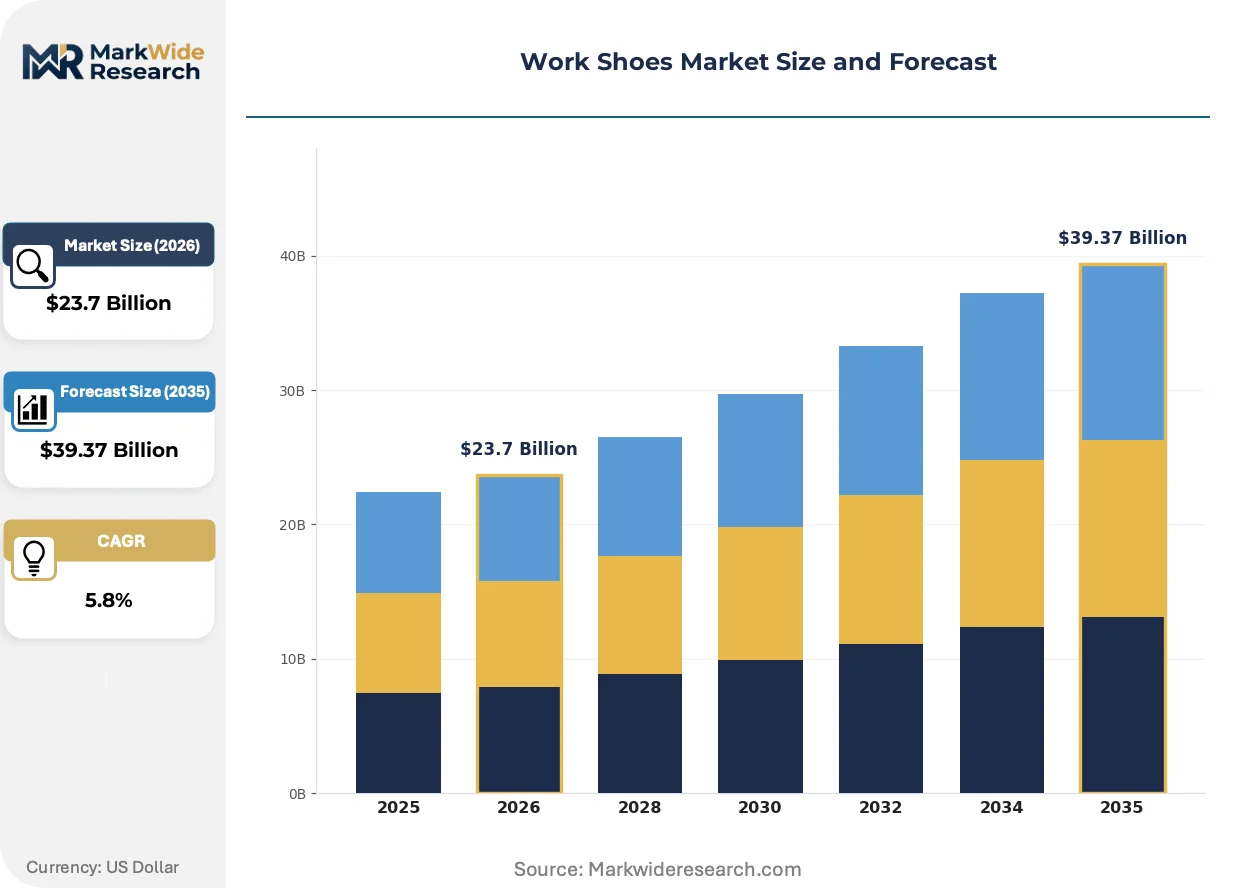
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel-Toe, Composite-Toe, Waterproof, Slip-Resistant End User: Construction, Manufacturing, Healthcare, Hospitality Material: Leather, Synthetic, Rubber, Textile Feature: Breathable, Shock-Absorbent, Anti-Slip, Electrical Hazard |
| Companies Covered | Red Wing, Timberland PRO, Caterpillar, U-Power, Georgia Boot, Wolverine, Ariat, Jalas, Brunt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Work Shoes Market Evolving Landscape
Material science breakthroughs and regulatory disclosure requirements are bifurcating the market into premium certified tiers and lightweight disposable categories, with distribution models adapting to serve each track.
Carbon-fiber and fiberglass toe cap technologies are rendering obsolete traditional steel reinforcement in electrical utility and airport ground crew applications. Utility cooperatives and municipal power authorities specify composite materials exclusively. The shift compresses metalworking supply chains while expanding polymer and resin supplier influence.
ASTM International's sustainability disclosure working group is advancing environmental footprint reporting requirements alongside mechanical performance standards. Large industrial employers now request lifecycle data in RFP evaluations. Premium domestic manufacturers leverage shorter supply chains to satisfy documentation demands faster than offshore competitors.
Employer-funded boot allowance programs are displacing individual purchase reimbursement across unionized construction and manufacturing sectors. Workers select from pre-approved catalogs at worksite fitting events. The Midwest and Gulf Coast petrochemical corridors show highest penetration of this consolidated procurement model.
Work Shoes Market Segmentation
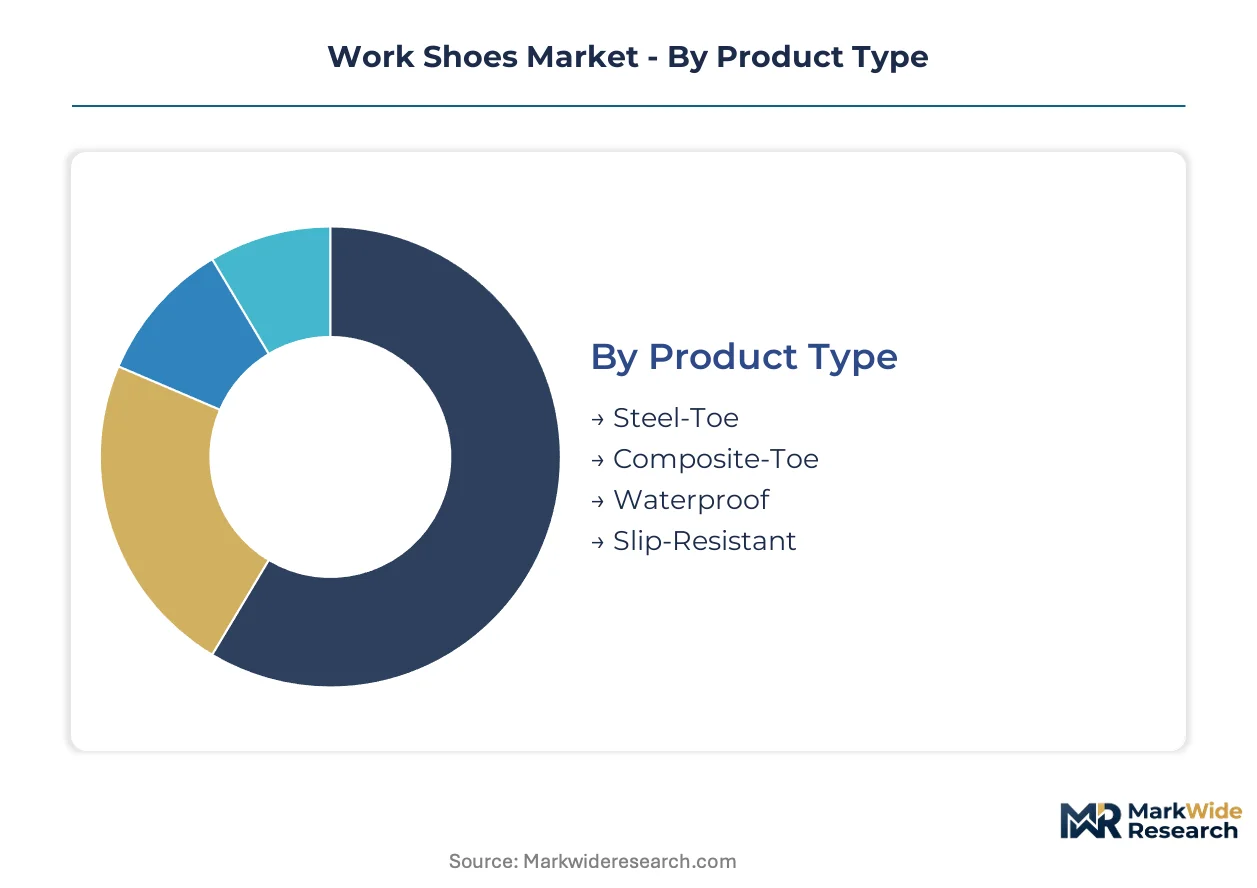
Work shoe segmentation reveals divergent engineering priorities across occupational hazards. ASTM F2413 compliance requirements fragment specifications by end-use risk profile, while material selection trades durability against weight constraints in extended-shift environments.
Product Type:
Protective toe technology spans metallic and non-metallic constructions calibrated to electrical, thermal, and detection-environment requirements.
- Composite-Toe:Fiberglass and carbon-fiber reinforcements eliminate conductivity risks in electrical utility work. Municipal power authorities and airport ground crews specify these exclusively where metal detection protocols operate. Lighter weight drives worker compliance rates above steel alternatives in manufacturing facilities.
- Steel-Toe:Traditional alloy caps deliver maximum impact resistance at lowest unit cost. Construction and heavy manufacturing procurement favors these where electrical hazards are absent and budget constraints dominate specification committees.
- Waterproof:Membrane-lined constructions seal against chemical splash and standing water in food processing and outdoor utility work. Shorter effective lifecycles require more frequent replacement schedules.
- Slip-Resistant:Specialized outsole compounds meet ASTM F2913 traction standards for hospitality and healthcare floors. Insurance carriers tie premium reductions to documented slip-prevention footwear programs.
The dominant share belongs to Steel-Toe, while Composite-Toe is closing the gap fastest.
End User:
Procurement volume concentrates where OSHA enforcement intensity intersects with high headcount operations.
- Construction:Union hiring halls and general contractors drive consolidated purchasing through employer-funded boot allowance programs. Federal project mandates require ASTM F2413 certification documentation.
- Manufacturing:Automotive and heavy equipment plants sustain replacement cycles through scheduled safety audits. Composite-toe penetration is highest here due to electrical maintenance exposure.
- Healthcare:Extended-shift nursing and veterinary applications reward sub-500-gram constructions. Current industrial-focused portfolios underpenetrate these fatigue-sensitive roles.
- Hospitality:Kitchen and housekeeping staff turnover accelerates replacement frequency. Slip-resistant specifications dominate procurement criteria over toe protection.
Construction commands the largest procurement volume, with Healthcare expanding most quickly as lightweight designs penetrate clinical settings.
Material:
Raw material selection balances abrasion resistance, chemical compatibility, and weight targets across duty cycles.
- Leather:Full-grain hides dominate premium tiers where break-in acceptance and longevity justify higher unit costs. Tanning capacity constraints and hide supply volatility compress margins for domestic manufacturers.
- Synthetic:Polyurethane and microfiber constructions reduce weight in healthcare and food service applications. Industrial buyers resist these in heavy-abrasion environments despite comfort advantages.
- Rubber:Injection-molded compounds form waterproof boots and specialized outsoles. Chemical resistance specifications favor these in petrochemical and agricultural chemical handling.
- Textile:Engineered mesh uppers maximize breathability in warm-climate outdoor work. Limited penetration outside utility and landscaping sectors due to durability concerns.
Leather retains margin leadership in premium tiers, while Synthetic materials are gaining share fastest in healthcare and lightweight segments.
Feature:
Performance attributes layer onto base protection to address environment-specific hazards and worker comfort thresholds.
- Electrical Hazard:Non-conductive soles and heels meet ASTM F2413-18 EH ratings for dry electrical environments. Utility cooperatives mandate these for linework and substation maintenance crews.
- Anti-Slip:Outsole tread patterns and compound formulations target coefficient-of-friction thresholds on wet and oily surfaces. Food processing and commercial kitchen procurement requires documented slip resistance.
- Breathable:Moisture-wicking linings and ventilated uppers reduce thermal stress in foundries and warm-climate outdoor work. Extended-shift acceptance depends on temperature regulation.
- Shock-Absorbent:Polyurethane midsoles and gel inserts attenuate impact transmission during concrete and hard surface work. Warehouse and distribution center specifications increasingly include energy-return metrics.
Anti-Slip features anchor the largest functional segment, with Electrical Hazard specifications climbing the fastest as composite-toe adoption spreads through electrical trades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial footwear trade deficit in protective occupational categories, importing specialized safety components while domestic tanneries and composite-material fabricators supply premium-grade leather and non-metallic toe cap technologies to regional assembly operations.
United States
Federal OSHA enforcement drives consistent replacement cycles across manufacturing and logistics sectors. The Department of Labor's inspection protocols under 29 CFR 1910.132 mandate hazard assessment documentation that shapes procurement specifications. Industrial concentrations in Houston's petrochemical corridor and Detroit's automotive belt sustain volume demand for ASTM F2413-certified composite-toe constructions.
Germany
Precision manufacturing and chemical processing operations anchor protective footwear demand in the Rhine-Ruhr and Bavarian industrial zones. The country's national occupational safety regulator enforces technical standards that exceed baseline EU requirements, favoring domestic producers with rapid certification turnaround. Stuttgart's automotive engineering cluster and Ludwigshafen's chemical corridor represent concentrated specification influence for metatarsal-guard and chemical-resistant boot categories.
China
Domestic infrastructure investment and export-oriented manufacturing sustain dual demand tracks for industrial safety footwear. The national standards administration maintains GB standard equivalency with ASTM impact resistance benchmarks to facilitate North American export access. The Yangtze River Delta manufacturing belt and Pearl River Delta export processing zones concentrate production capacity for synthetic-upper and rubber-outsole constructions.
India
Construction sector expansion and formalizing manufacturing employment drive protective footwear adoption beyond traditional informal procurement. The Bureau of Indian Standards is advancing occupational safety footwear specifications aligned with international test protocols. Industrial corridors in Gujarat's Sanand-Vithalapur belt and Tamil Nadu's Sriperumbudur orbit exhibit accelerating specification discipline among multinational contract manufacturers.
Brazil
Mining operations and agribusiness processing sustain demand for puncture-resistant and waterproof boot constructions in hazardous outdoor environments. The national health surveillance agency enforces occupational safety equipment compliance that elevates certified product penetration above regional neighbors. São Paulo state's manufacturing belt and Minas Gerais iron ore mining districts concentrate employer-funded protective equipment programs.
Work Shoes Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers: domestic manufacturers with integrated tanning and molding operations, regional assemblers sourcing certified components from specialized upstream suppliers, and direct-to-worksite distributors leveraging logistics networks to bypass traditional retail channels. Strategic archetypes include heritage workwear brands defending premium positioning through union trade relationships, industrial equipment licensors extending brand equity into protective footwear categories, and asset-light leasing operators compressing capital barriers for smaller contractor accounts. Dominant competitive moves center on vertical integration into domestic manufacturing to satisfy sustainability documentation requirements and direct-to-employer distribution partnerships that consolidate fragmented procurement.
Within the heritage domestic manufacturing tier, Red Wing and Georgia Boot exemplify producers leveraging captive tannery and molding operations to control material quality and certification documentation timelines. Timberland PRO occupies a position bridging outdoor recreation heritage with occupational specification discipline, while Caterpillar represents the industrial equipment licensor archetype extending brand recognition into energy and construction sector procurement channels. Wolverine and Ariat sit within the diversified workwear portfolio segment, serving multiple hazard categories through segmented brand architectures.
| Leading Market Players |
|---|
| Red Wing |
| Timberland PRO |
| Caterpillar |
| U-Power |
| Georgia Boot |
| Wolverine |
| Ariat |
| Jalas |
| Brunt |
| Others |
Value Network & Pricing Analysis
Composite-toe component fabrication clusters in North American polymer labs and Taiwanese carbon-fiber weaving operations, concentrating margin capture with domestic assemblers who control ASTM F2413 certification documentation timelines. Leather tanning capacity in the United States and Italy anchors premium-tier pricing power, while synthetic-upper sourcing from Southeast Asian textile mills compresses mid-tier margins through buyer consolidation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—ASTM F2413-18 EH electrical hazard ratings command 15-25% premiums over baseline impact-resistant tiers—and domestic manufacturing origin for sustainability documentation. Cost compression in synthetic-upper segments is intensifying because hospital GPOs and food processing chains consolidate procurement volumes. Unionized construction trades show lowest price sensitivity due to employer-funded boot allowance programs, while independent contractors in residential construction exhibit highest sensitivity to per-unit differentials.
Supply Chain Analysis
Export-control restrictions on advanced carbon-fiber grades limit composite-toe technology flows to non-allied manufacturing jurisdictions. Geographic supply concentration centers on China for synthetic uppers and rubber outsoles, Vietnam for textile components, and the United States for leather hides and domestic assembly. Raw material dependencies include full-grain leather from domestic tanneries, fiberglass and carbon-fiber reinforcements from specialty polymer suppliers, and petroleum-derived polyurethane midsoles. Single-source vulnerability concentrates in ASTM F2413 testing infrastructure, where North American laboratory capacity creates validation bottlenecks for offshore manufacturers. Distribution runs through direct-to-worksite fitting programs, employer-sponsored catalogs, and industrial supply distributors serving multi-site national accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Work Shoes Market functions as a regulatory-moat business where ASTM F2413 certification entrenchment and union trade relationships create switching costs that defend incumbent positioning. Network effects concentrate in employer-funded boot allowance programs that lock in pre-approved supplier catalogs across consolidated procurement channels.
For Market Incumbents: Insulate premium positioning through captive tanning operations and domestic molding capacity that accelerates sustainability documentation turnaround. Threats from asset-light leasing operators compress capital barriers for smaller contractors; counter through direct-to-worksite logistics networks and union hiring hall partnerships that consolidate fragmented procurement. Certification investment in emerging state-level mandates beyond federal OSHA baselines extends specification influence with procurement officers. For New Entrants and Emerging Players: Build out healthcare lightweight segments where sub-500-gram constructions remain underpenetrated by industrial-focused portfolios. Extended-shift nursing and veterinary applications offer the most penetrable white space, with fatigue-sensitive roles rewarding comfort-engineered designs over traditional durability metrics. Go-to-market execution should target GPO contracts and hospital system procurement committees rather than retail channels. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated domestic manufacturers with captive tannery and composite-material molding operations. Long-term viability across the projection horizon hinges on controlling certification documentation timelines as large industrial employers request lifecycle data in RFP evaluations. Watch for inflection signals in state-level safety mandate expansions beyond federal baselines, where early compliance positioning captures specification influence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Operations | Captive leather supply secures margin pools and accelerates ASTM documentation timelines for premium tiers. |
| Direct-to-Worksite Distribution Partnerships | Employer-sponsored fitting programs bypass retail markup and consolidate fragmented contractor procurement. |
| Composite-Toe Technology Licensing | Carbon-fiber and fiberglass formulations penetrate electrical utility and airport ground crew specifications exclusively. |
| State-Level Compliance Pre-Positioning | Early alignment with California and Washington safety mandates captures specification influence with procurement officers. |
| Healthcare Lightweight Portfolio Extension | Sub-500-gram constructions address fatigue-sensitive nursing and veterinary roles outside traditional industrial focus. |
Research Methodology
Initial hypotheses were tested against primary input from safety directors at industrial employers, procurement managers at union hiring halls, plant engineers in manufacturing facilities, and distribution channel partners serving multi-site accounts, then refined through secondary validation. Bottom-up demand modeling drew from OSHA enforcement data, ASTM F2413 certification records, and employer-funded boot allowance program disclosures. Top-down supply assessment incorporated customs records for leather and synthetic material flows, tannery capacity utilization reports, and composite-material fabricator output data. Triangulation across these sources calibrated volume and value estimates.
Demand-supply balance dynamics shaped the analytical framework across the analysis window. Segmentation dimensions modeled include protective toe technology, end-user industry, material construction, and performance feature attributes. CAGRs were derived from replacement cycle frequency analysis tied to OSHA inspection intensity and insurance carrier premium reduction programs. Industry-specific forecast inputs incorporated composite-toe adoption curves in electrical trades and slip-resistant specification penetration in food processing and hospitality floors.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian synthetic-upper manufacturers or rapid leasing model proliferation by asset-light operators would shift outcomes. Material shifts in ASTM International sustainability disclosure requirements or state-level safety mandate timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Work Boots Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Helmets Market
Protective Gear
Earplug Distributor Market
Protective Gear
China Pollution Mask Market
Protective Gear
Europe Lanyards Market
Protective Gear
Earplugs Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Military Boots Market
Protective Gear
Tactical Boots Market