
 Europe Protective Footwear Market | 2026-2036
Europe Protective Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Protective Footwear Market Foresight
The split between premium performance boots and commodity safety footwear is realigning procurement patterns across European industrial buyers. Honeywell International Inc. leverages its respiratory and PPE portfolio to bundle protective footwear with enterprise safety contracts. Bata Corporation anchors its position through dense wholesale distributor networks spanning Central and Eastern Europe. COFRA Holding AG specializes in Italian-made composite-toe systems for petrochemical and energy utility accounts.
Protective footwear encompasses safety boots and shoes engineered with reinforced toe caps, puncture-resistant midsoles, and slip-resistant outsoles to shield workers from impact, compression, and electrical hazards in occupational environments. Steel-toe variants retain dominance in heavy construction and mining applications where maximum impact resistance governs specification sheets, while composite-toe segments gain share among manufacturing and logistics operators seeking metal-free alternatives for lighter weight and thermal insulation. The construction industry vertical commands the largest revenue pool due to mandatory site-level PPE compliance, though oil and gas procurement carries premium margin concentration through flame-resistant and chemical-barrier specifications.
EU Regulation 2016/425 mandates CE marking and third-party conformity assessment for all protective footwear placed on the European market, forcing non-compliant imports into costly retesting or exit. ECHA's REACH restrictions on chromium VI in leather tanning and persistent fluorinated compounds in waterproof membranes are redirecting R&D spending toward bio-based polymers and water-repellent silicone finishes. Germany's KBA and France's ANSM do not directly regulate footwear, but national occupational safety inspectorates in both countries enforce workplace PPE directives with escalating site penalties. Stakeholders must track evolving harmonized EN ISO 20345 standards for toe protection and sole performance, as anticipated revisions to test protocols will obsolete current product lines and reshape supplier qualification criteria.
Market Dynamics
The EU PPE Regulation 2016/425 is compressing supplier margins through mandatory CE marking and third-party conformity assessment, forcing wholesale distributor networks to consolidate certification documentation and retest legacy inventory.
Growth Catalysts
- REACH restrictions on chromium VI:ECHA's tightening leather tanning standards are redirecting R&D budgets toward bio-based polymers and water-repellent silicone finishes, opening premium positioning for compliant manufacturers.
- German automotive corridor demand:Chemical plant and assembly line operators in Bavaria and Baden-Württemberg mandate composite-toe boots for lightweight thermal insulation, creating specification pull-through across Central European supply chains.
- Polish infrastructure acceleration:EU cohesion fund disbursements for road and rail projects in Silesia and Mazovia are expanding mandatory site-level PPE compliance pools for construction procurement.
Market Restraints
- Raw material concentration:Dependence on Italian and Portuguese leather tanneries for high-grade upper materials creates vulnerability to ECHA chemical restriction delays and input cost volatility.
- Certification timeline friction:EU Regulation 2016/425 mandates third-party notified body involvement for all new product lines, extending time-to-market by 8-14 months for non-EU origin manufacturers.
- Metal detector compatibility substitution:Logistics and airport ground handling operators in France and the Netherlands are specifying 100% composite-toe systems, eroding steel-toe residual demand in formerly dominant segments.
Strategic Opportunities
- Romanian and Bulgarian industrial expansion:Underpenetrated manufacturing bases in these EU member states lack established safety footwear distribution density, creating first-mover wholesale partnership potential.
- Flame-resistant chemical-barrier convergence:Petrochemical operators in the Port of Rotterdam cluster and Antwerp chemical belt seek integrated specifications combining EN ISO 20345 toe protection with EN 15090 firefighter boot thermal standards.
- Direct-to-plant digital procurement:Enterprise resource planning integration allowing site safety managers to bypass distributor markup is gaining traction among German automotive OEMs with centralized PPE purchasing.
Industry Challenges
- Composite materials engineering talent scarcity:Formulation chemists capable of optimizing carbon-fiber and fiberglass toe cap impact resistance-to-weight ratios command premium compensation and limited geographic mobility.
- EN ISO 20345 test protocol obsolescence risk:Anticipated revisions to slip-resistance and penetration-resistance testing standards threaten to invalidate current product line certifications mid-production cycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Protective Footwear Market |
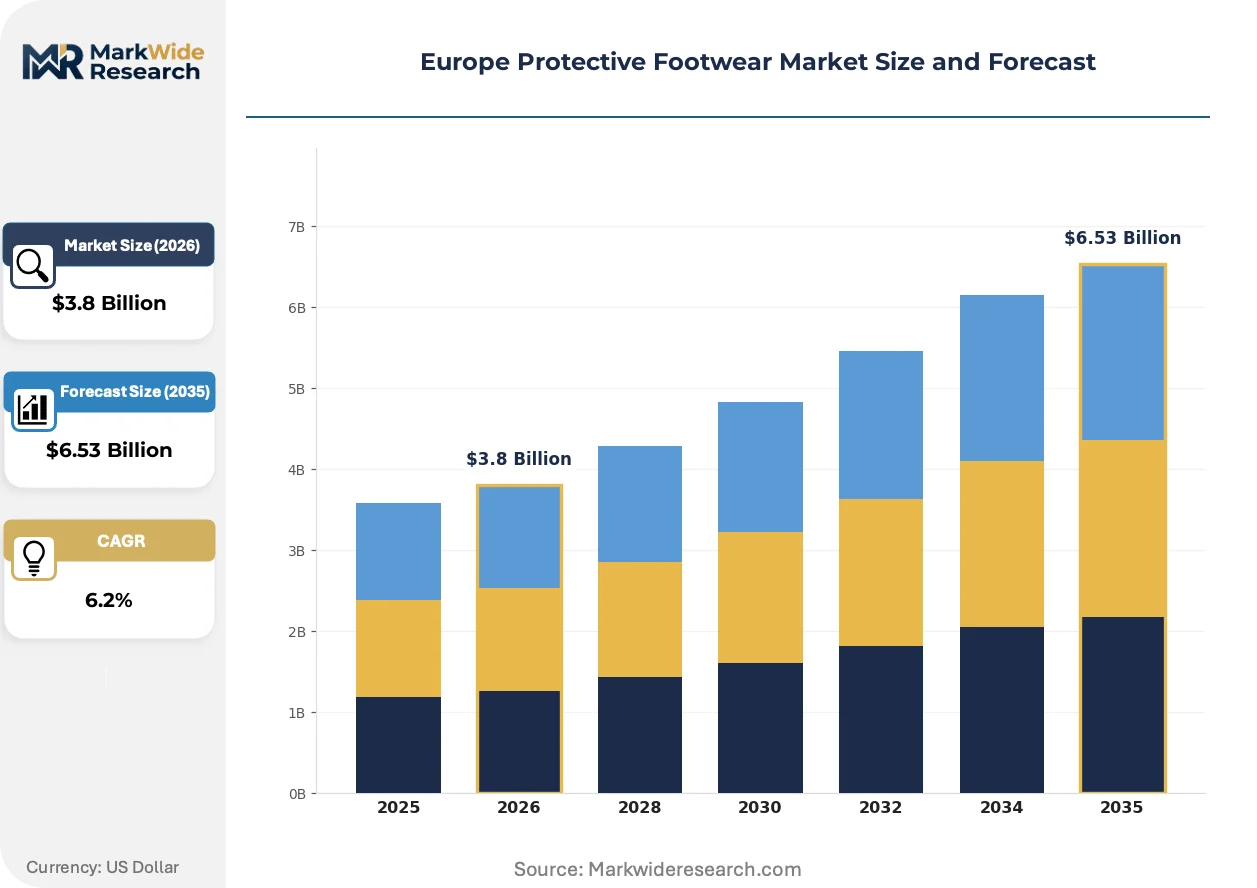
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Steel-Toe, Composite-Toe, Rubber, Waterproof Industry Vertical: Construction, Manufacturing, Oil & Gas, Mining End User: Workers, Industrial Operators, Emergency Responders, Healthcare Staff Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Honeywell International Inc., Bata Corporation, Wolverine World Wide Inc., VF Corporation, Dunlop Protective Footwear, Uvex Safety Group, COFRA Holding AG, ELTEN GmbH, Rock Fall Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Protective Footwear Market Shifts & Advancements
Material science advances and procurement digitization are restructuring how specifications propagate from regulatory text to factory floor, with three convergent forces redefining competitive positioning.
Carbon-fiber and fiberglass composite toe caps are consolidating specification share in manufacturing and logistics environments where thermal conductivity and metal-detector compatibility outweigh maximum impact ratings. Automotive final assembly plants in Stuttgart and Wolfsburg specify these systems exclusively, compressing steel-toe dominance to heavy construction and mining verticals where EN 20345 SB-P ratings remain non-negotiable.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances in waterproof membranes are forcing membrane suppliers toward silicone-based alternatives and bio-derived water repellents. French and German occupational safety inspectorates are escalating site penalty schedules for non-compliant PPE, concentrating compliance investment among distributors serving multinational accounts with cross-border workforce mobility.
Site-level safety managers are consolidating purchasing authority through enterprise safety contracts that bundle footwear with respiratory and fall-protection equipment. This behavior concentrates volume with integrated PPE portfolios and marginalizes standalone footwear specialists, particularly visible in German chemical and energy utility accounts where total cost of ownership modeling dominates vendor selection.
Europe Protective Footwear Market Segmentation
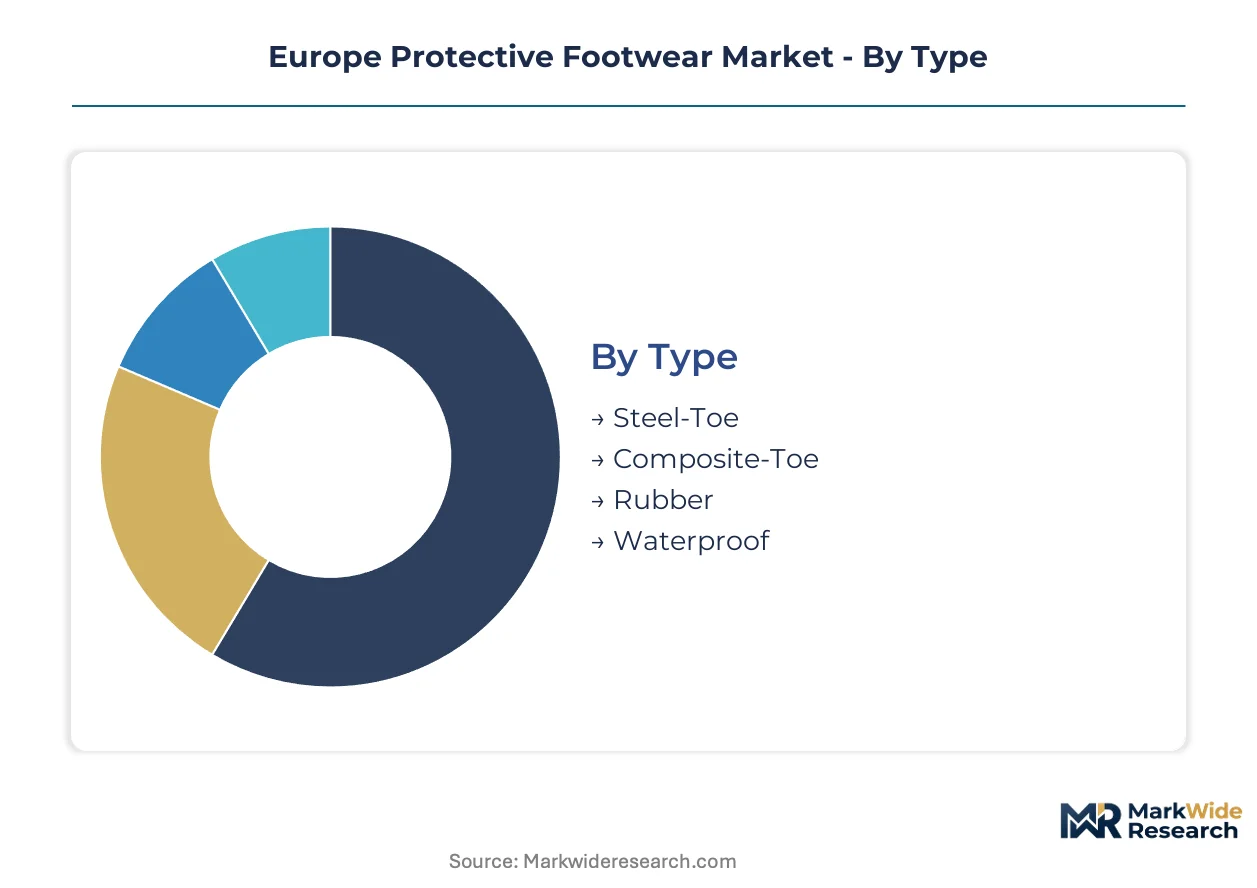
Certification requirements under EU Regulation 2016/425 fragment procurement specifications across toe-cap materials and end-use environments. Segmentation patterns reveal where EN ISO 20345 compliance costs concentrate and where composite alternatives displace legacy steel.
Type:
Steel-toe variants demand full third-party notified body assessment for CE marking, while composite systems face additional thermal insulation testing under anticipated protocol revisions.
- Steel-Toe:Traditional carbon steel toe caps deliver maximum impact resistance for EN 20345 SB-P ratings. Heavy construction sites in Poland and mining operations in Germany's Ruhr region mandate these specifications despite weight penalties.
- Composite-Toe:Carbon-fiber and fiberglass formulations achieve metal-detector compatibility with 30-40% weight reduction. Stuttgart automotive assembly plants and Rotterdam petrochemical facilities specify these systems exclusively for thermal insulation benefits.
- Rubber:PVC and nitrile rubber boots serve chemical splash protection in Antwerp chemical belt operations with EN 13832 acid resistance ratings.
- Waterproof:Silicone-finished leather and synthetic membrane constructions replace fluorinated compounds under REACH Annex XVII pressure, concentrating R&D investment among Italian tanneries.
Leading the category by volume: Steel-Toe. Growing fastest: Composite-Toe.
Industry Vertical:
Margin concentration varies sharply across verticals, with oil and gas procurement commanding premium pricing for multi-hazard specifications.
- Construction:Mandatory site-level PPE compliance across EU cohesion fund projects in Silesia and Mazovia drives volume procurement through wholesale distributor networks. EN 20345 S3 SRC ratings dominate specification sheets.
- Manufacturing:Bavarian chemical plants and Baden-Württemberg assembly lines prioritize lightweight composite systems with electrostatic discharge properties. Direct-to-plant digital procurement is gaining traction among German automotive OEMs.
- Oil & Gas:Flame-resistant and chemical-barrier specifications combine EN ISO 20345 toe protection with EN 15090 thermal standards in Rotterdam and Antwerp clusters.
- Mining:Subsurface operations in Poland's Silesian basin and Germany's remaining hard coal sites retain steel-toe dominance for maximum penetration resistance.
Highest margin capture: Oil & Gas. Steepest volume expansion: Construction.
End User:
Procurement authority consolidation distinguishes enterprise buyers from fragmented individual purchasing.
- Workers:Individual purchasers through specialty stores and online retail seek mid-tier S1-P and S3 certified boots for general industrial employment.
- Industrial Operators:Site safety managers at BASF Ludwigshafen and Volkswagen Wolfsburg bundle footwear with respiratory and fall-protection equipment under enterprise safety contracts.
- Emergency Responders:Fire services and civil defense units in France and Germany specify EN 15090-compliant integrated systems with thermal barrier properties.
- Healthcare Staff:Anti-slip and fluid-resistant requirements in German and Dutch hospital systems drive demand for washable synthetic constructions.
Contract concentration peaks with Industrial Operators. Procurement fragmentation highest among Workers.
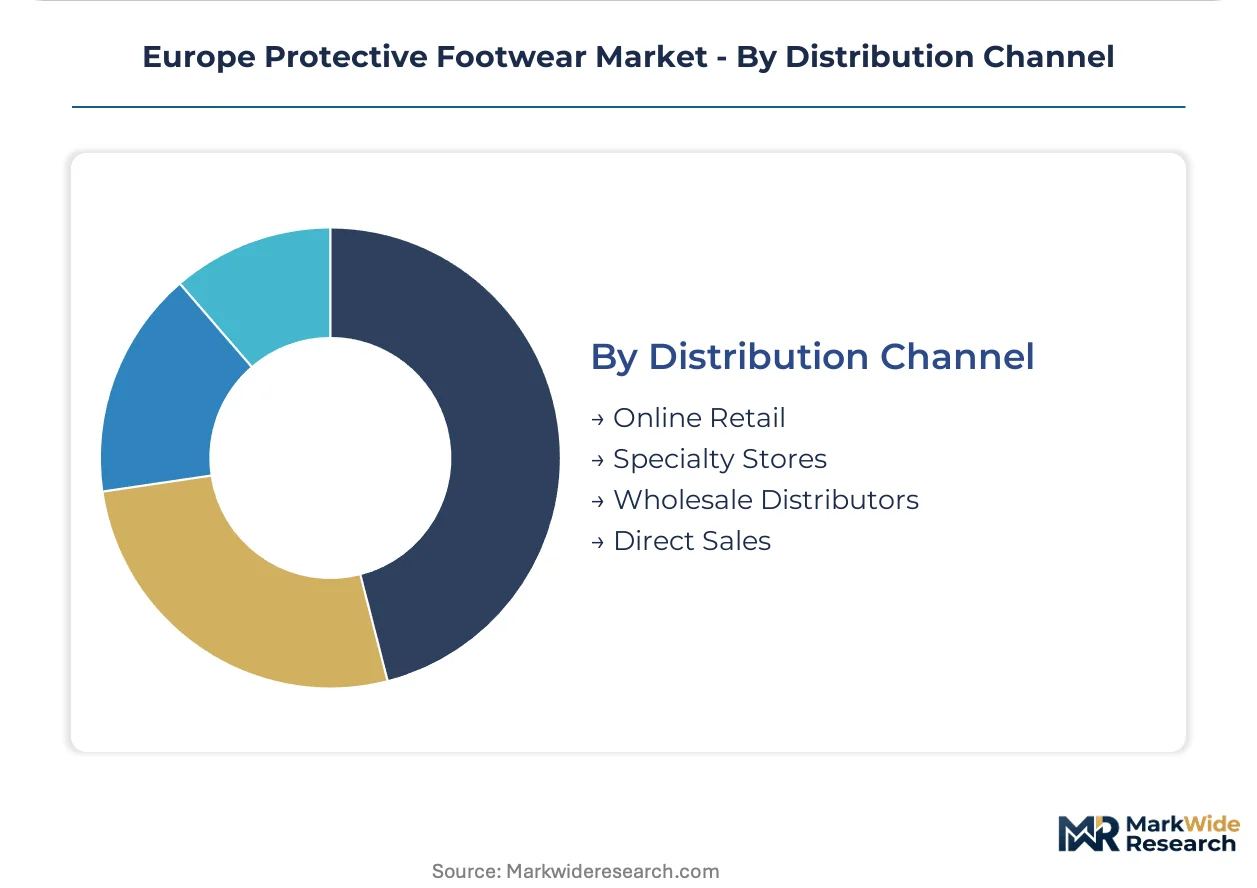
Distribution Channel:
Channel economics reflect certification documentation burdens and inventory carrying costs for CE-marked stock.
- Online Retail:Amazon Business and specialized PPE platforms serve small and mid-sized employers with standardized S3-rated products, bypassing distributor markup.
- Specialty Stores:Bata Corporation's dense Central and Eastern European network provides fitting services and immediate availability for construction sector walk-in demand.
- Wholesale Distributors:Consolidators like COFRA Holding AG manage certification documentation and retest legacy inventory for petrochemical and energy utility accounts.
- Direct Sales:Honeywell International leverages respiratory and PPE portfolio breadth to capture German automotive and chemical plant contracts through integrated safety procurement.
Volume leadership: Wholesale Distributors. Channel share expanding most quickly: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart automotive corridor anchors European demand for composite-toe protective footwear, with Volkswagen and Porsche assembly plants mandating metal-free specifications across their supplier networks. This industrial concentration radiates procurement standards throughout Central European supply chains.
Germany
Bavarian chemical plants and Baden-Württemberg automotive facilities drive composite-toe adoption for thermal insulation and electrostatic discharge compliance. The KBA enforces workplace PPE directives through escalating site penalties. BASF Ludwigshafen and Volkswagen Wolfsburg anchor enterprise safety contract consolidation.
France
Occupational safety inspectorates under ANSM jurisdiction intensify enforcement of EU Regulation 2016/425 compliance with documented site closures for violations. The Île-de-France logistics hub specifies 100% composite-toe systems for airport ground handling and warehousing operations.
Poland
EU cohesion fund disbursements accelerate road and rail infrastructure projects across Silesia and Mazovia provinces. Construction sector procurement expands mandatory site-level PPE compliance pools. Silesian basin mining retains steel-toe dominance for maximum penetration resistance.
Netherlands
The Port of Rotterdam petrochemical cluster seeks integrated specifications combining toe protection with flame-resistant standards. REACH Annex XVII enforcement tightens chemical restrictions on leather tanning inputs. Amsterdam logistics operators specify metal-detector-compatible footwear.
Italy
Italian tanneries concentrate R&D investment toward silicone-finished leather alternatives under ECHA pressure. COFRA Holding AG anchors wholesale distributor networks serving Central and Eastern European markets. Northern industrial regions supply premium composite-toe systems.
Europe Protective Footwear Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and distribution documentation burdens. The supplier base stratifies into three tiers: integrated PPE portfolios bundling footwear with respiratory equipment, specialized footwear manufacturers with dense wholesale networks, and regional distributors managing CE marking compliance. Consolidation pressures concentrate among distributors carrying legacy inventory requiring retesting under evolving EN ISO 20345 protocols.
Within the integrated safety portfolio tier, Honeywell International Inc. represents the archetype of bundling protective footwear with enterprise respiratory and fall-protection contracts. Bata Corporation occupies a position among established wholesale distributors with Central and Eastern European network density. COFRA Holding AG exemplifies specialized composite-toe manufacturing for petrochemical and energy utility accounts.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Bata Corporation |
| Wolverine World Wide Inc. |
| VF Corporation |
| Dunlop Protective Footwear |
| Uvex Safety Group |
| COFRA Holding AG |
| ELTEN GmbH |
| Rock Fall Ltd. |
| Others |
Supply & Pricing Matrix
Captive control over Italian and Portuguese leather tanneries anchors pricing power for premium-grade protective footwear, allowing integrated manufacturers to buffer ECHA chemical restriction costs while commodity competitors absorb margin compression from certification retesting.
Pricing Analysis
Uptime-based contract pricing dominates enterprise safety procurement, with German automotive OEMs and chemical plant operators paying premium rates for guaranteed stock availability and rapid replacement fulfillment. Three-tier pricing structure across premium composite-toe, standard steel-toe, and economy PVC boot levels separates certification complexity tiers. Cost compression in the economy segment is intensifying because REACH Annex XVII compliance forces reformulation of waterproof membranes. Small construction subcontractors exhibit highest price sensitivity, while petrochemical operators in Rotterdam and Antwerp clusters prioritize thermal barrier performance over unit cost.
Supply Chain Analysis
Freight cost volatility between Italian tanneries and Central European assembly plants is reshaping inventory positioning, with distributors holding larger safety stocks of CE-marked boots to bypass border delays. Raw material sourcing draws from Portuguese leather processors, German synthetic polymer suppliers, and Chinese carbon-fiber toe cap manufacturers. Single-source vulnerability concentrates in high-grade upper leather from ECHA-regulated Italian tanneries facing chromium VI restriction uncertainty. Distribution runs through wholesale consolidators managing certification documentation for multinational accounts with cross-border workforce mobility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
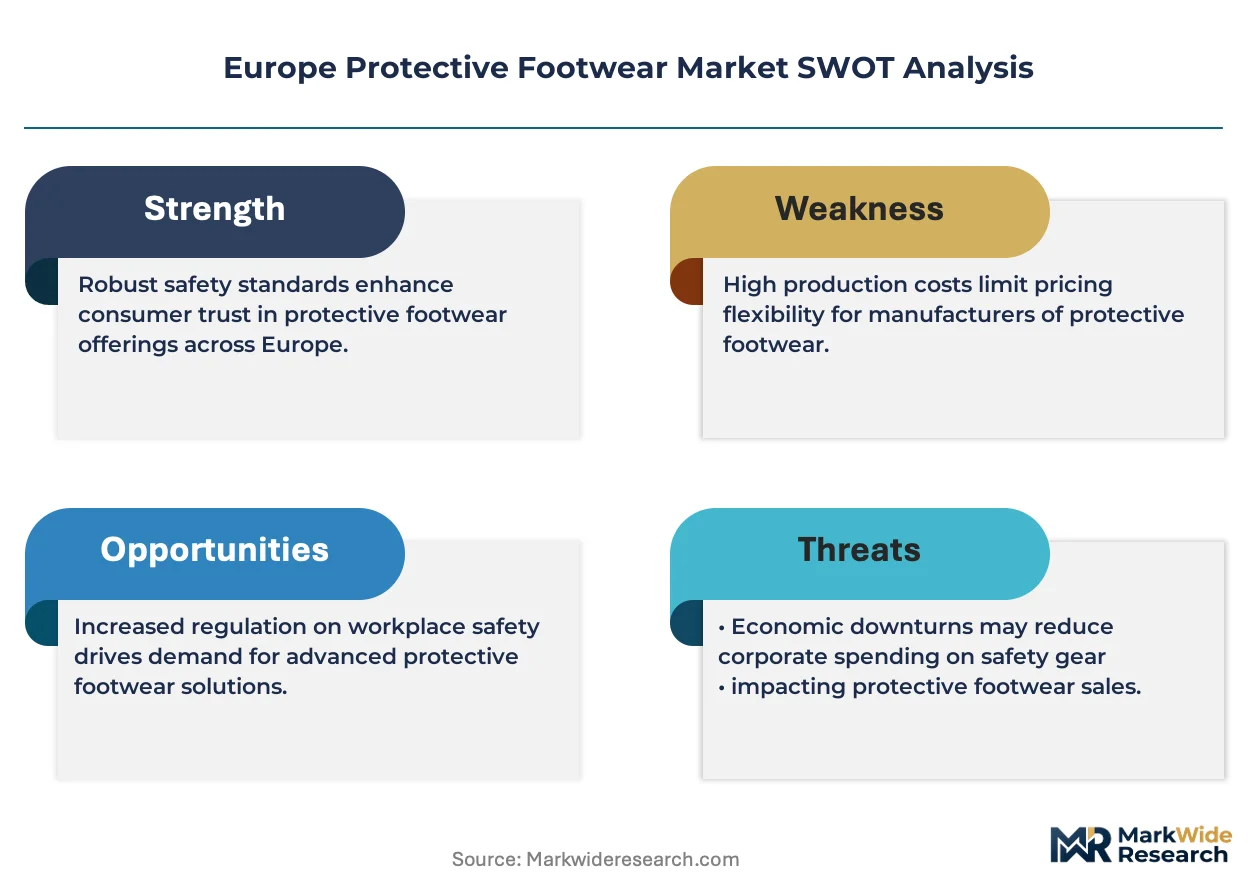
This market is becoming a vertical-integration race, with manufacturers acquiring tannery capacity to secure REACH-compliant leather supply and control input cost trajectories.
For Market Incumbents: Anchor market position through backward integration into Portuguese and Italian tannery operations, eliminating ECHA restriction exposure at the source. Consolidate certification documentation capabilities to capture distributor networks struggling with EU Regulation 2016/425 retesting burdens. Composite-toe patent portfolios represent the critical defensive lever against Asian manufacturers with cost-advantaged steel-toe production. For New Entrants and Emerging Players: Romanian and Bulgarian industrial safety managers remain underserved by established wholesale networks, offering first-mover partnership potential with local distributors. Direct-to-plant digital procurement platforms bypass incumbent distributor markups for mid-sized manufacturing accounts seeking S3-rated composite systems. White-label supply agreements with Italian composite-toe specialists provide fastest route to CE marking without notified body timeline friction. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated PPE conglomerates seeking footwear category completion. Long-term viability hinges on formulation chemistry capabilities for next-generation bio-based polymers replacing fluorinated waterproof membranes. Watch EN ISO 20345 protocol revision timing as inflection indicator for product line obsolescence risk across portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Operations | Secures REACH-compliant leather supply for German automotive corridor contracts. |
| Composite-Toe Patent Portfolio Expansion | Builds defensible IP position against Asian steel-toe cost competition. |
| Direct-to-Plant Digital Procurement Platform | Bypasses wholesale distributor markup for Bavarian chemical plant accounts. |
| CE Marking Certification Service Acquisition | Captures distributor networks struggling with EU Regulation 2016/425 retesting. |
| Flame-Resistant Chemical-Barrier R&D Partnership | Addresses Rotterdam petrochemical cluster integrated specification demand. |
Research Methodology
Trade association filings, ECHA regulatory databases, and EU customs records formed the secondary backbone, cross-referenced against primary interviews with safety footwear procurement managers at German automotive OEMs, Italian tannery technical directors, Polish construction site safety officers, and wholesale distributor network heads. Bottom-up volume estimates from end-use verticals were triangulated against top-down market sizing from trade flow analysis.
Historical trendline analysis of construction sector PPE procurement and automotive manufacturing employment anchored the forecast framework across the projection horizon. Segmentation modeling incorporated toe-cap material type, industry vertical hazard classification, end-user procurement authority level, and distribution channel structure. CAGRs were derived from regression analysis of infrastructure investment cycles and regulatory compliance cost trajectories, with EN ISO 20345 protocol revision scenarios stress-testing sensitivity bounds.
Revisions become necessary when ECHA expands REACH Annex XVII restrictions beyond current fluorinated compound scope, when EN ISO 20345 test protocol changes accelerate product line obsolescence, or when EU cohesion fund disbursement delays alter Polish construction sector PPE procurement timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Helmets Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Insect Repellent Market
Protective Gear
Military Boots Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Equestrian Helmets Market
Protective Gear
Work Boots Market
Protective Gear
China Pollution Mask Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Boxed Glove for Food Market
Protective Gear
Waterproof Cases Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Diving Suits Market
Protective Gear
Work Shoes Market
Protective Gear
Tactical Boots Market
Protective Gear
Global Mobile Phone Protective Cases Market