
 Earplugs Market | 2026-2036
Earplugs Market Size, Share, and Industry Trends Forecast 2026-2036
Earplugs Market Analysis
Industrial procurement officers are unwinding long-term contracts with legacy safety distributors as musicians and concertgoers drive premium earplug demand. 3M Company leverages its occupational safety channel dominance to supply foam disposables across manufacturing plants. Loop Earplugs specializes in frequency-filtering designs that preserve sound quality for live music environments. Etymotic Research anchors the high-fidelity musician segment with custom-molded in-ear technology.
Earplugs are passive hearing protection devices manufactured from polyurethane foam, silicone elastomer, or thermoplastic materials, designed to attenuate sound pressure levels by 15 to 33 decibels depending on NRR certification. Foam variants dominate industrial volume due to low unit cost and disposable protocols, while silicone reusable products command margin pools in consumer and professional audio channels. The sleeping application segment shows structural expansion as wellness-oriented consumers prioritize acoustic hygiene, whereas swimming and shooting remain niche use cases with concentrated seasonal demand.
OSHA mandates NRR-certified hearing protection in US workplaces above 85 decibel exposure thresholds, while the EU PPE Regulation requires CE marking and third-party conformity assessment for all commercial earplug sales. Germany's KBA and France's CNIL do not regulate this category, but ECHA REACH restrictions on isocyanates in polyurethane production constrain foam formulation options. Stakeholders must monitor evolving material compliance costs and decide whether to absorb certification investments or pivot toward silicone and wax alternatives with simpler regulatory pathways.
Market Dynamics
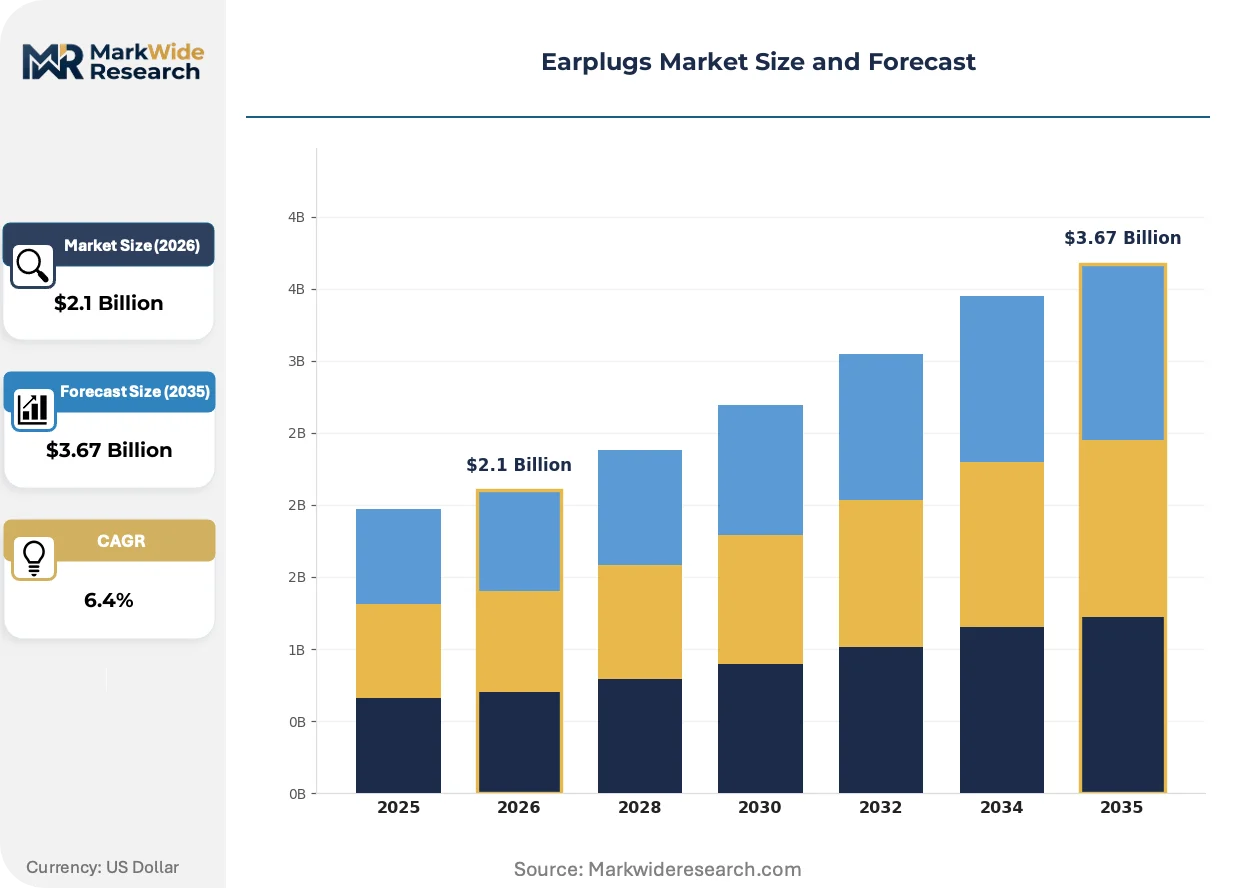
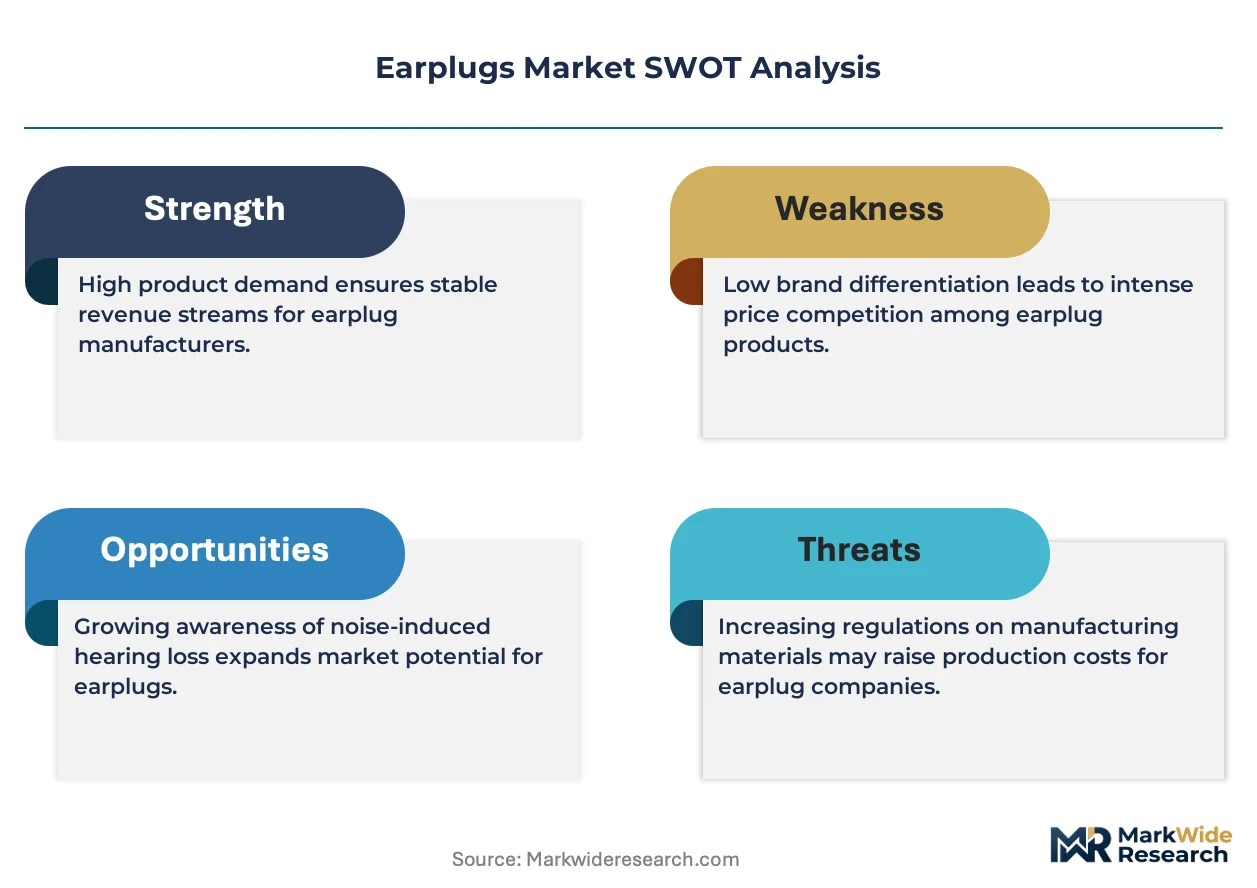
The earplugs market is undergoing a structural recalibration as occupational mandates tighten and consumer wellness priorities diverge from legacy industrial procurement patterns. Regulatory pressure on polyurethane foam formulations intersects with rising demand for frequency-preserving audio protection.
Growth Catalysts
- OSHA workplace mandates:US manufacturing facilities above 85 decibel thresholds must deploy NRR-certified protection, sustaining institutional volume for certified foam and silicone variants.
- Live music venue expansion:Concert attendance recovery in Germany and the Netherlands drives professional-grade filter earplug adoption among orchestras and touring musicians.
- Sleep hygiene prioritization:Wellness-oriented consumers in urban centers purchase reusable silicone and wax alternatives for acoustic environment control.
Market Restraints
- Isocyanate supply constraints:ECHA REACH restrictions on toluene diisocyanate in polyurethane production elevate raw material costs for disposable foam manufacturing.
- Single-source silicone dependency:Medical-grade silicone elastomer supply concentrates among German and Japanese specialty chemical producers.
- Fit variability limitations:Universal-fit foam products deliver inconsistent attenuation across diverse ear canal geometries, capping performance claims.
Strategic Opportunities
- India occupational safety expansion:Factory Act amendments and state-level enforcement in Maharashtra and Gujarat create nascent institutional demand for certified hearing protection.
- Custom-molded convergence:Smartphone-enabled 3D ear scanning paired with desktop photopolymer printing collapses bespoke fitting costs for musician segments.
- Direct-to-consumer channel bypass:Specialty audio retailers and venue merchandising displace legacy safety distributor intermediaries in premium filter categories.
Industry Challenges
- Audiologist certification bottlenecks:Custom-molded production requires licensed impression-taking, constraining scaling in markets with practitioner shortages.
- Multi-jurisdiction compliance layering:Simultaneous OSHA NRR, EU PPE Regulation, and emerging state-level requirements extend product validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earplugs Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Earplugs, Silicone Earplugs, Wax Earplugs, Reusable Earplugs Application: Sleeping, Traveling, Swimming, Shooting End User: Consumers, Industrial Workers, Musicians, Athletes Distribution Channel: Online Retail, Drugstores, Specialty Stores, Supermarkets |
| Companies Covered | 3M Company, Honeywell International Inc., Moldex-Metric Inc., Etymotic Research, Alpine Hearing Protection, EARGASM, Loop Earplugs, Uvex Safety Group, MSA Safety Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earplugs Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are forcing parallel innovation tracks across foam, silicone, and emerging biopolymer formulations. Manufacturers must now engineer for compliance durability alongside acoustic performance.
Precision acoustic filtering is fragmenting the musician and audio professional segment into specialized sub-categories. Loop and Etymotic-style frequency-preserving designs attenuate harmful peaks while maintaining speech and music clarity. Recording engineers and classical performers adopt these at accelerating rates. The technology is fragmenting what was historically a single industrial PPE category into distinct professional audio, consumer lifestyle, and occupational safety verticals with incompatible performance metrics.
EU REACH Annex XVII restrictions on isocyanates are compelling polyurethane foam reformulation across European manufacturing. Producers must validate alternative blowing agents and polyol chemistries without sacrificing NRR certification levels. German industrial suppliers face the steepest compliance costs, accelerating interest in thermoplastic elastomer and silicone alternatives with simpler substance authorization pathways.
Wellness retailers and pharmacy chains are capturing consumer earplug volume from hardware and safety distributors. CVS, Walgreens, and dedicated sleep stores stock reusable silicone and wax products with lifestyle branding. This channel rotation is most visible in US coastal metropolitan markets where acoustic hygiene discourse penetrates consumer consciousness ahead of occupational safety framing.
Earplugs Market Segmentation
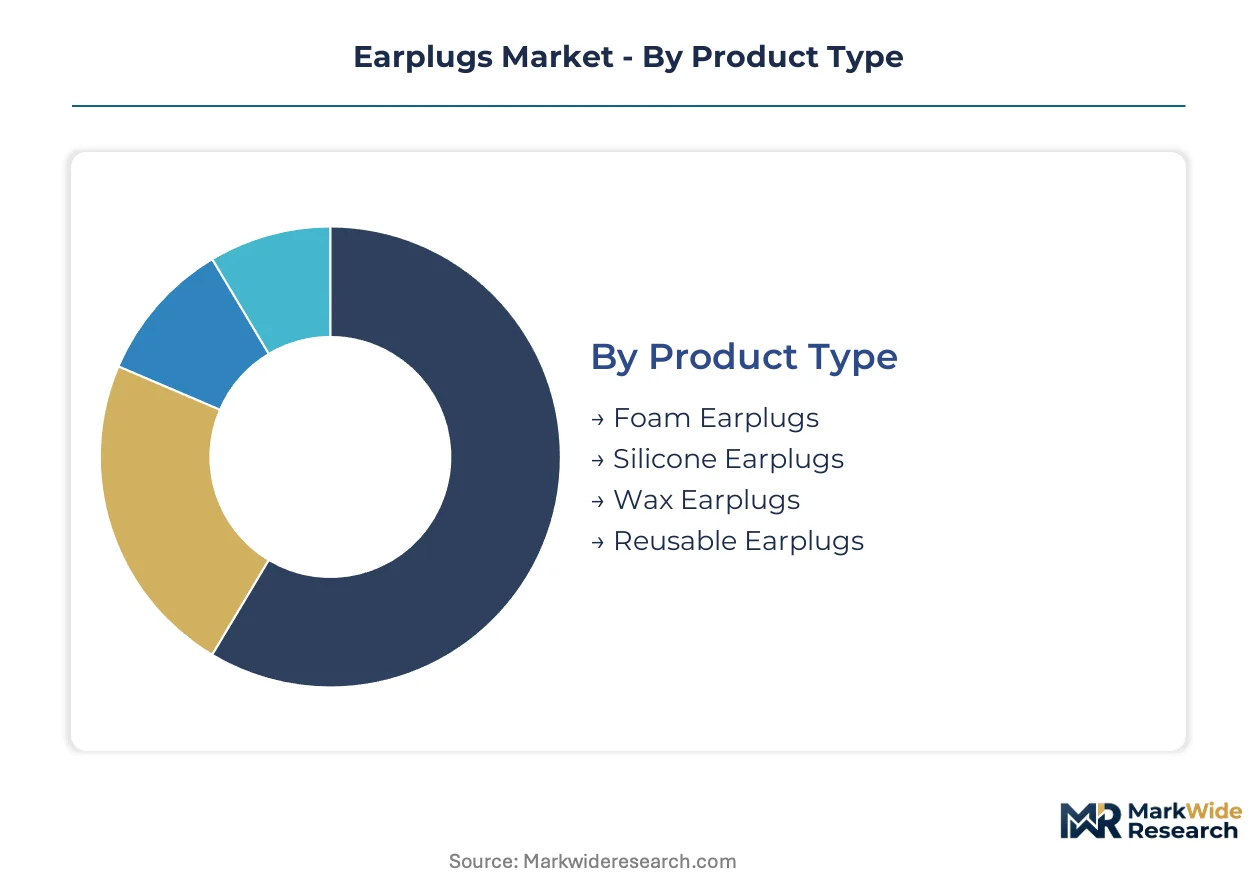
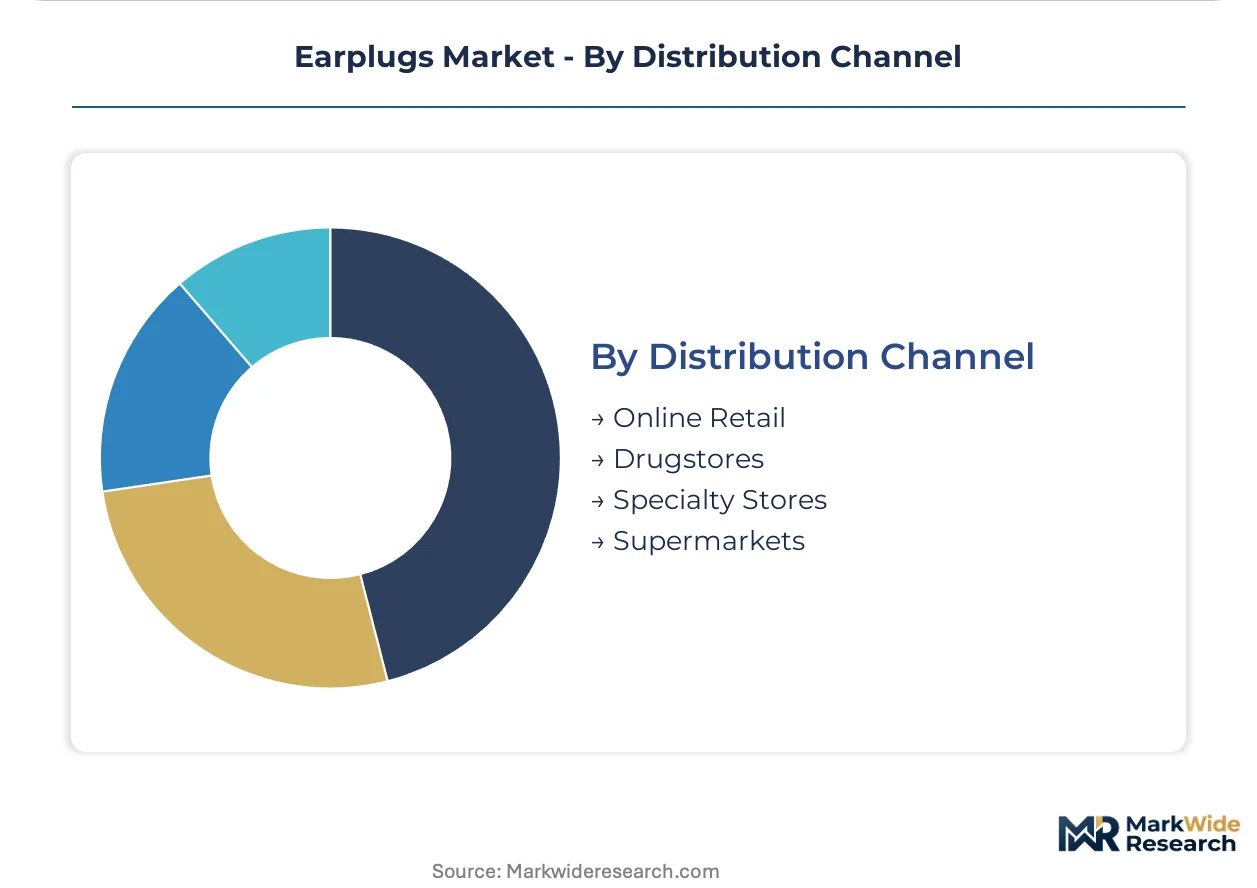
Earplugs fragment across incompatible performance metrics and procurement channels. Industrial buyers prioritize NRR certification and unit economics, while musicians and wellness consumers demand frequency preservation and aesthetic design. Channel bifurcation between safety distributors and lifestyle retailers forces manufacturers to maintain parallel product architectures.
Product Type:
Channel alignment varies sharply by material chemistry. Foam variants dominate institutional procurement through occupational safety distributors, while silicone and wax products flow through pharmacy chains and direct-to-consumer platforms.
- Foam Earplugs:Manufactured from polyurethane with single-use disposable protocols. Demand concentrates in US manufacturing facilities under OSHA mandates, though ECHA REACH restrictions on isocyanates elevate European production costs.
- Silicone Earplugs:Thermoplastic elastomer construction enables multiple reuse cycles with washability. Germany and Japan supply medical-grade silicone feedstock, constraining margin expansion for downstream molders serving musician and sleep segments.
- Wax Earplugs:Petroleum-derived formulations with moldable hand-warm application. Pharmacy chains in France and the Netherlands capture volume through acoustic hygiene positioning.
- Reusable Earplugs:Multi-material designs combining filter inserts with silicone or thermoplastic shells. Online retail and specialty audio stores displace legacy safety channels for frequency-filtering variants.
By volume, Foam Earplugs leads. By growth pace, Reusable Earplugs is ahead.
Application:
Cost tier stratification separates commodity disposables from premium positioned alternatives. Sleeping applications command unit price multiples over industrial foam through wellness branding and reusable architecture.
- Sleeping:Silicone and wax formulations designed for comfort during extended wear. Urban consumers in London, New York, and Tokyo drive demand through acoustic environment control prioritization.
- Traveling:Compact packaging and carry-case integration for transit noise attenuation. Airport retail and online travel accessory platforms capture this occasional-use segment.
- Swimming:Waterproof silicone designs preventing water ingress during aquatic activity. Seasonal demand concentrates in Mediterranean and Australian coastal markets with concentrated summer purchasing.
- Shooting:High-NRR protection for impulse noise from firearms. Specialized retailers and range pro shops serve this concentrated enthusiast segment with premium filter technology.
Sleeping applications generate highest per-unit margins. Traveling shows steepest expansion trajectory among occasional-use categories.
End User:
Customer type determines certification requirements and pricing architecture. Industrial procurement mandates NRR labeling, while musicians prioritize frequency response curves absent standardized metrics.
- Consumers:Wellness-oriented individuals purchasing through pharmacy and online channels for sleep, travel, and general noise reduction. Urban density and acoustic hygiene discourse expand addressable population.
- Industrial Workers:Manufacturing, construction, and logistics personnel under mandatory hearing protection protocols. OSHA and EU PPE Regulation compliance requirements sustain institutional volume.
- Musicians:Orchestral performers, touring artists, and audio engineers requiring attenuation without spectral distortion. Custom-molded and universal-fit filter designs fragment this premium segment.
- Athletes:Competitive shooters, swimmers, and motorsport participants with activity-specific protection needs. Niche positioning through specialty sporting goods retailers.
Industrial Workers represent largest volume base. Musicians climb the fastest on per-capita spending expansion.
Distribution Channel:
Supply concentration among German and Japanese silicone producers shapes channel economics. Direct-to-consumer platforms bypass distributor markups for premium filter categories.
- Online Retail:Amazon, direct brand sites, and specialty audio platforms capturing musician and wellness segments. Smartphone-enabled fitting tools reduce return rates for universal-fit products.
- Drugstores:CVS, Walgreens, and European pharmacy chains stocking sleep and travel SKUs with lifestyle merchandising. Impulse placement drives trial for wax and silicone reusables.
- Specialty Stores:Hearing clinics, music retailers, and shooting ranges providing expert guidance and custom fitting services. Audiologist certification requirements constrain scaling.
- Supermarkets:Mass-market foam disposables in bulk packaging for price-sensitive industrial and consumer buyers. Limited shelf space for premium positioned alternatives.
Online Retail gains share fastest. Drugstores retain volume leadership in consumer lifestyle categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export polyurethane foam and silicone earplug components to industrial buyers across the United States and European Union, while Chinese molders supply bulk disposable foam to price-sensitive procurement channels in Southeast Asia and Latin America.
United States
OSHA mandates NRR-certified hearing protection in manufacturing facilities exceeding 85 decibel exposure thresholds, sustaining institutional volume for foam and silicone variants. The Department of Labor enforces penalty structures for non-compliance that elevate procurement priority. Industrial clusters in Michigan automotive plants and Texas petrochemical corridors drive concentrated demand for disposable foam protocols.
Germany
Strict occupational hearing protection mandates under the EU PPE Regulation exceed most member-state enforcement rigor, creating premium positioning for certified reusable products. ECHA REACH restrictions on toluene diisocyanate constrain polyurethane foam formulation options for domestic producers. Manufacturing concentration in Bavaria and North Rhine-Westphalia centers on medical-grade silicone elastomer processing for musician and sleep segments.
China
Expanding manufacturing employment in Zhejiang and Guangdong provinces generates nascent institutional demand for basic hearing protection as provincial safety bureaus tighten enforcement. The State Administration for Market Regulation oversees GB standard alignment with international PPE certification. Yangtze River Delta chemical producers supply polyurethane precursors to both domestic molders and export-oriented fabricators serving European industrial distributors.
India
Factory Act amendments in Maharashtra and Gujarat create emerging compliance obligations for hearing protection in textile and pharmaceutical manufacturing. The Bureau of Indian Standards develops indigenous certification frameworks for industrial PPE that parallel OSHA NRR methodologies. Mumbai-Pune and Ahmedabad-Vadodara industrial corridors represent the primary addressable procurement zones for certified foam and silicone variants.
Japan
Precision manufacturing culture in Aichi Prefecture and Osaka-Kobe industrial zones sustains demand for high-attenuation protection in metalworking and electronics assembly. METI guidelines encourage proactive hearing conservation programs that exceed statutory minima. Tokyo metropolitan wellness consumers purchase premium reusable silicone products through pharmacy and direct-to-consumer channels for sleep and transit applications.
Earplugs Market Vendor Landscape
Listed leaders compete with private specialists across certification breadth and channel access, creating a tiered structure where scale advantages in foam disposables coexist with margin capture in premium filter designs. Occupational safety conglomerates leverage distributor relationships for institutional procurement, while audio-focused specialists bypass intermediaries through direct-to-consumer platforms. Two archetypes dominate: diversified safety conglomerates with regulatory certification depth, and narrow specialists with acoustic engineering credentials. Competitive moves center on portfolio diversification into adjacent hearing protection categories and geographic expansion through regulatory certification stacking.
Within the diversified safety tier, 3M Company and Honeywell International Inc. exemplify scale-driven certification breadth across OSHA and EU PPE frameworks. Etymotic Research occupies a position among acoustic engineering specialists, representing the high-fidelity musician segment archetype where frequency-preserving technology commands premium positioning. These three entities collectively illustrate the market's bifurcation between institutional volume and professional audio margin pools.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Moldex-Metric Inc. |
| Etymotic Research |
| Alpine Hearing Protection |
| EARGASM |
| Loop Earplugs |
| Uvex Safety Group |
| MSA Safety Incorporated |
| Others |
Supply Flow & Price Mechanics
Capacity utilization disparities between German silicone elastomer producers and Chinese foam molders create divergent cost floors across the earplug category. Scale advantages in polyurethane batch processing anchor disposable pricing, while medical-grade silicone feedstock scarcity elevates reusable product entry costs.
Pricing Analysis
Current-generation frequency-filtering designs command substantial premiums over prior-generation foam disposables and next-generation photopolymer-printed custom molds. Three-tier pricing structure across premium, standard, and economy levels separates NRR-certified industrial foam from musician-grade silicone filters and bespoke audiologist-fitted products. Price differentiation stems from certification grade and vertical integration depth, with OSHA NRR labeling requirements adding compliance costs to institutional tiers. Pricing pressure stems from ECHA REACH restrictions on toluene diisocyanate, which elevates European foam production costs. Industrial procurement officers exhibit highest price sensitivity, while touring musicians demonstrate lowest sensitivity due to hearing damage risk exposure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for polyurethane precursor shipments. Raw material supply concentrates in Germany, Japan, and China, with German producers dominating medical-grade silicone elastomer and Chinese chemical plants supplying foam polyols. Component dependencies include toluene diisocyanate, polyether polyols, and platinum-cured silicone resins. Single-source vulnerability characterizes medical-grade silicone feedstock, where German and Japanese specialty chemical producers control global capacity. Distribution runs through occupational safety distributors for institutional volume and direct-to-consumer platforms for premium filter categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The earplug category fragments across incompatible performance metrics, creating niche capture opportunities as wellness consumers diverge from legacy industrial procurement patterns. Demand-side shifts toward acoustic hygiene discourse in urban centers generate white-space for lifestyle-positioned entrants.
For Market Incumbents: Fortify certification breadth across OSHA NRR and EU PPE frameworks to defend institutional contracts against emerging filter specialists. Expand backward integration into polyurethane precursor production to offset ECHA REACH compliance cost inflation. Prioritize channel control through exclusive safety distributor relationships in Michigan automotive and Texas petrochemical corridors.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships enables European market entry ahead of full substance authorization timelines. Target India's Maharashtra and Gujarat industrial corridors where Factory Act amendments create nascent compliance demand without entrenched supplier relationships. Deploy smartphone-enabled ear scanning for custom-molded convergence, collapsing audiologist dependency for musician segment penetration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer filter brands with subscription replenishment models for replaceable acoustic inserts. Five-to-ten year viability favors specialists with acoustic engineering credentials over commodity foam producers facing raw material cost compression. Monitor ECHA substance authorization timelines as inflection indicator for silicone alternative adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Photopolymer Printing Integration | Smartphone ear scanning collapses custom-molded fitting costs for musician segments. |
| REACH-Compliant Foam Reformulation | Alternative polyol chemistries preserve NRR certification amid isocyanate restrictions. |
| Direct-to-Consumer Channel Buildout | Specialty audio platforms displace legacy safety distributor markups in premium tiers. |
| India Certification Stacking | BIS framework alignment captures Factory Act amendment procurement in western states. |
| Silicone Feedstock Security | Long-term agreements with German and Japanese specialty chemical producers anchor margin stability. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with occupational safety procurement officers, acoustic engineers at filter specialists, audiologists performing custom impressions, and plant managers at polyurethane foam facilities. Secondary validation drew from OSHA enforcement databases, ECHA REACH substance authorization registers, EU PPE Regulation conformity assessment records, and customs trade data for silicone elastomer flows. Bottom-up volume estimates from end-use application sizing were triangulated against top-down market value reconstructions.
Across the analysis window, the forecasting framework modeled product type segmentation, application use case, end user archetype, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections incorporating enforcement intensity trends for workplace hearing protection mandates. Industry-specific inputs included NRR certification adoption curves and smartphone-enabled fitting tool penetration rates.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation in OSHA penalty structures or ECHA substance authorization timelines would warrant model refresh. Forecasts reflect base-case assumptions regarding isocyanate supply continuity and silicone feedstock pricing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Mobile Protective Cases Market
Protective Gear
Waterproof Boots Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Earplug Distributor Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Equestrian Helmets Market
Protective Gear
Helmets Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Cooking Gloves Market
Protective Gear
Boxed Glove for Food Market
Protective Gear
Dust Covers Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Hand Gloves Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Work Shoes Market