
 Flavored Condoms Market | 2026-2036
Flavored Condoms Market Size, Share, and Industry Trends Forecast 2026-2036
Flavored Condoms Market Foresight
Pharmacy retail is pivoting toward sexual wellness aisles as a destination category, displacing back-shelf placement. Reckitt Benckiser Group plc leverages its Durex brand strength to dominate pharmacy and supermarket channels across Europe and Asia. Mankind Pharma anchors the Indian market through aggressive pricing and deep distribution into tier-two and tier-three cities. Karex Berhad competes as a contract manufacturer, supplying private-label flavored condoms to multiple retail banners worldwide.
Flavored condoms are sheathed barrier devices incorporating taste- and scent-imparting additives, typically water-based lubricants with food-grade flavoring agents, manufactured through dip-molding of latex or synthetic elastomers followed by post-cure washing and lubrication. Their primary commercial purpose is dual: pregnancy prevention and sexually transmitted infection protection with enhanced user acceptability through sensory differentiation. Strawberry and chocolate flavor types occupy the volume-leading position in mature Western markets, while mint variants register the fastest trajectory in tropical climates where cooling sensation drives preference. Latex material sustains dominant share due to cost structure and established manufacturing infrastructure, though polyisoprene is capturing margin pools among latex-allergic consumers willing to pay premium positioning.
FDA 510(k) medical device clearance and CE marking under the EU MDR govern material biocompatibility, tensile strength, and flavoring agent safety for flavored condoms in their respective jurisdictions. India's CDSCO and BIS standards add layer requirements for local market access, particularly around labeling language and shelf-life validation. Stakeholders must monitor evolving regulatory divergence between jurisdictions as flavoring agent approval lists tighten in Europe under EFSA scrutiny while remaining more permissive in emerging markets.
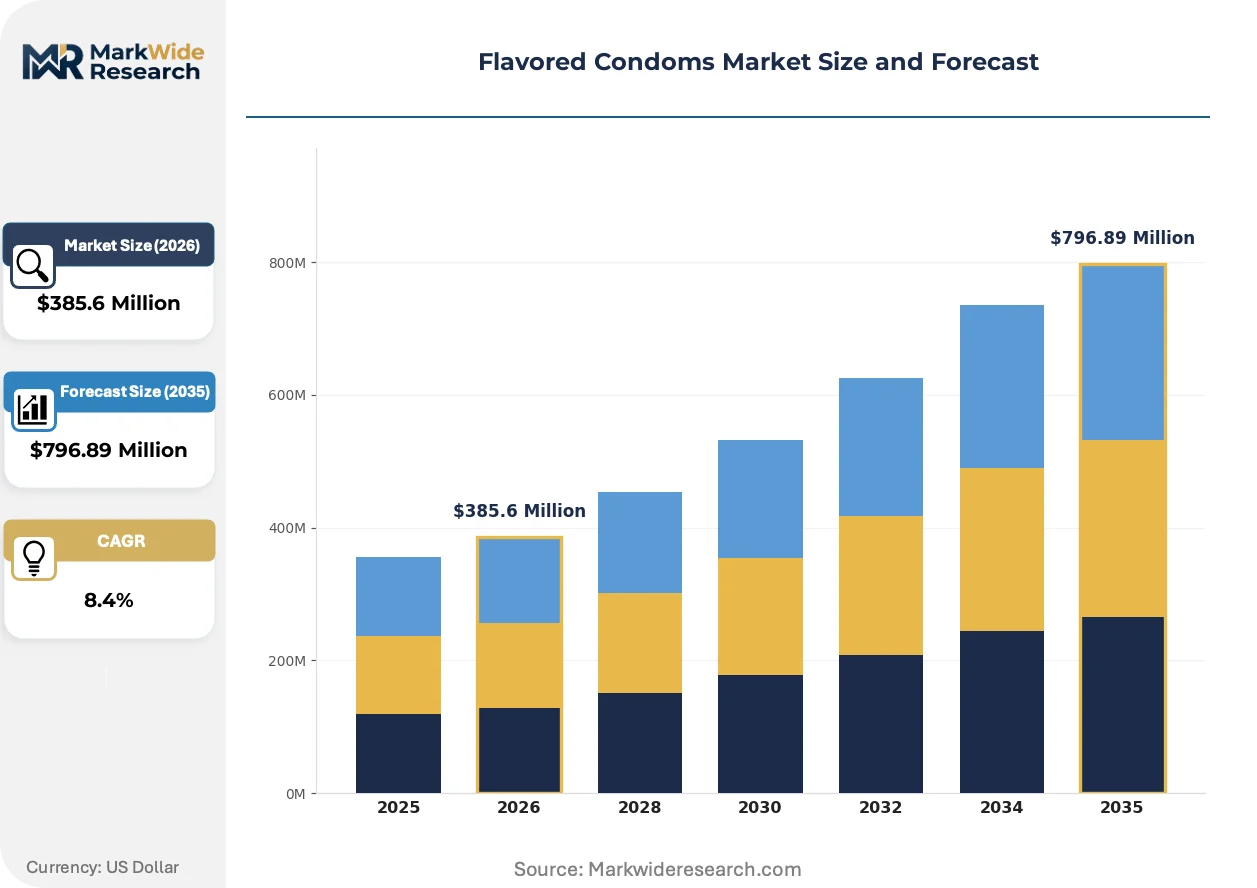
Market Dynamics
Pharmacy retail chains are repositioning sexual wellness from back-shelf obscurity to front-of-store destination categories, forcing manufacturers to reformulate for visible packaging compliance and sensory differentiation at point-of-sale.
Growth Catalysts
- E-commerce penetration:Online pharmacies and direct-to-consumer platforms bypass traditional retail gatekeepers, enabling discrete purchasing and subscription-based replenishment models that expand addressable user bases.
- CE marking under EU MDR:Harmonized medical device standards reduce cross-border compliance costs for manufacturers, accelerating product launches across European single-market territories.
- Polyisoprene substitution:Synthetic elastomer formulations capture latex-allergic consumers previously excluded from flavored barrier protection, opening premium pricing tiers without reformulation complexity.
Market Restraints
- Natural rubber latex price volatility:Plantation supply disruptions in Southeast Asia transmit directly to input costs, compressing margins for commodity-grade producers unable to pass through increases.
- Flavoring agent regulatory divergence:EFSA scrutiny of food-contact additives in Europe tightens approved substance lists faster than FDA 510(k) pathways, forcing dual-formulation inventories.
- Private-label concentration:Contract manufacturing dominance by Malaysian and Thai producers consolidates pricing power upstream, limiting brand-owner margin negotiation leverage.
Strategic Opportunities
- Tier-two Indian cities:Underpenetrated distribution beyond metro corridors offers volume expansion as disposable incomes rise and pharmacy modernization penetrates secondary urban centers.
- Subscription pharmacy integration:Partnerships with recurring-delivery health platforms embed flavored variants into preventive care bundles, reducing customer acquisition costs.
- Cooling-sensation variants:Mint and menthol formulations tailored to tropical climates address unmet sensory preferences in Brazil and Southeast Asian markets.
Industry Challenges
- Biocompatibility testing timelines:FDA 510(k) clearance for novel flavoring agents extends development cycles, delaying product launches relative to formulation completion.
- Cross-contamination control:Shared manufacturing lines between flavored and unflavored variants require validated cleaning protocols that constrain batch sequencing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavored Condoms Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Mint, Banana, Strawberry, Chocolate, Vanilla, Coffee Material: Latex, Polyurethane, Polyisoprene, Lambskin, Nitrile End User: Adults, Couples, Singles, LGBTQ+ Community, Health-Conscious Consumers Sales Channel: Pharmacies, Online Retailers, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Mankind Pharma, Mayer Laboratories Inc., Reckitt Benckiser Group plc, Pasante, Okamoto Industries, Inc., Church & Dwight Co., Inc., Veru Inc., Trustex, Karex Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavored Condoms Market Shifts & Advancements
Automation in coating and lubrication processes is compressing unit economics while regulatory tightening around medical device traceability forces serialization investments across production networks.
Automated dip-molding systems with real-time thickness monitoring are automating quality assurance that previously required manual sampling, enabling continuous production runs that reduce per-unit labor content. Mid-scale manufacturers in India and Thailand are retrofitting legacy lines with vision-based inspection modules to maintain FDA 510(k) compliance without greenfield capital deployment. The technology is automating defect detection at speeds that compress rejection rates and reduce warranty exposure for private-label suppliers.
EFSA's expanding scrutiny of food-grade additives under REACH-aligned frameworks is reclassifying certain flavoring agents from permitted to restricted status, forcing reformulation of strawberry and chocolate variants sold in European Economic Area markets. Manufacturers with dual-continent portfolios face inventory segmentation costs as approved substance lists diverge between Brussels and Washington regulatory spheres. Latex-allergic product lines with polyisoprene substrates encounter accelerated compliance reviews due to synthetic elastomer biocompatibility documentation requirements.
Direct-to-consumer pharmacy platforms are unbundling sexual wellness from general merchandise purchasing, creating discrete subscription categories that bypass traditional retail margin stacking. Urban millennials in São Paulo and Mumbai demonstrate highest adoption of auto-replenishment models, shifting volume from impulse-buy supermarket placement to planned digital procurement. This channel migration pressures legacy distributors to develop last-mile logistics partnerships or cede volume to vertically integrated e-pharmacy operators.
Flavored Condoms Market Segmentation
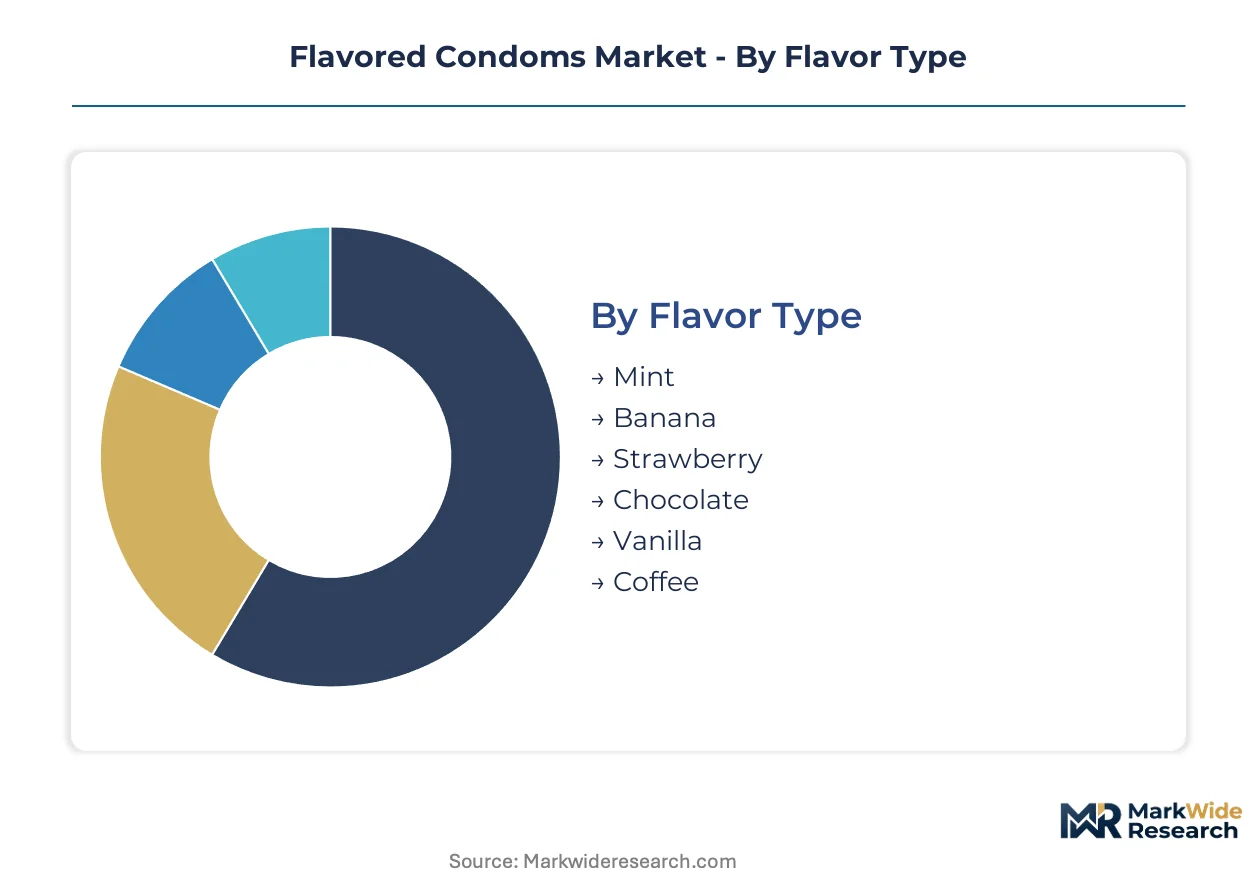
Segmentation in the flavored condoms market reveals how formulation chemistry, material science, and channel economics create distinct profit pools. Manufacturers must align R&D investment with the specific biocompatibility and sensory requirements of each category to capture margin premiums.
Flavor Type:
Supply concentration in water-based lubricant chemistry favors producers with in-house flavoring agent compounding capabilities, particularly those serving regulated medical device markets with validated additive sourcing.
- Strawberry:Formulated with ester-based flavoring agents dissolved in water-soluble lubricant bases, this variant dominates Western European and North American pharmacy shelves where familiar fruit profiles reduce purchase hesitation among first-time buyers. Demand concentrates in the United States and Germany where DTC pharmacy platforms feature strawberry in subscription starter bundles.
- Chocolate:Cocoa-derived and synthetic chocolate flavoring requires higher additive loadings to mask latex odor, increasing raw material costs but commanding shelf placement in premium sexual wellness aisles. Brazil and Mexico show strongest uptake where chocolate aligns with established confectionery preferences.
- Mint:Menthol-infused formulations deliver cooling sensations through thermoreceptor activation, with particular traction in tropical climates where temperature contrast drives sensory differentiation.
- Banana:Ester-heavy flavoring profiles target Southeast Asian markets with established banana consumption patterns, though regulatory scrutiny of isoamyl acetate concentrations varies by jurisdiction.
- Vanilla:Vanillin-based variants offer formulation stability and extended shelf life, appealing to private-label manufacturers prioritizing supply chain simplicity over sensory novelty.
- Coffee:Roasted alkaloid flavoring attracts urban millennial demographics in São Paulo and Mumbai where coffee culture intersects with wellness purchasing.
Today's leader: Strawberry. Tomorrow's challenger: Mint.
Material:
Cost tier differentiation separates commodity latex producers from synthetic elastomer specialists serving allergy-excluded populations willing to pay premium positioning.
- Latex:Natural rubber formulations dominate unit economics through established dip-molding infrastructure across Malaysia and Thailand, with FDA 510(k) and CE marking pathways well-documented for medical device classification. India and Brazil drive volume demand where price sensitivity favors established material platforms.
- Polyisoprene:Synthetic elastomer alternatives eliminate type I hypersensitivity risks while maintaining tensile strength parity with latex, opening premium tiers in the United States and United Kingdom where latex allergy diagnosis rates are highest. Reckitt Benckiser and Ansell have consolidated polyisoprene flavored variants under distinct sub-brands.
- Polyurethane:Thermoplastic formulations enable thinner wall specifications and heat conductivity advantages, though higher material costs limit penetration to specialty retail.
- Nitrile:Synthetic rubber alternatives offer chemical resistance and extended shelf stability, primarily serving institutional procurement rather than consumer retail.
- Lambskin:Natural membrane products from sheep intestines provide sensation transmission unmatched by synthetic barriers, though pore size excludes STI protection and restricts positioning to pregnancy prevention segments.
Volume dominance: Latex. Margin expansion: Polyisoprene.
End User:
Application-based segmentation maps sensory preferences to distinct relationship contexts and health literacy levels, shaping packaging communication and channel placement.
- Couples:Paired purchasing decisions prioritize mutual sensory acceptance and shared flavor preferences, driving demand for multi-flavor variety packs in pharmacy and supermarket channels.
- Singles:Individual procurement emphasizes discretion and portability, with single-unit packaging and neutral branding preferred in convenience retail.
- Adults:Broad demographic targeting captures routine preventive behavior without lifestyle segmentation, representing the default positioning for mass-market SKUs.
- LGBTQ+ Community:Inclusive marketing and community-specific distribution partnerships create brand loyalty in urban centers with established queer health infrastructure.
- Health-Conscious Consumers:Ingredient transparency and organic additive claims attract purchasers scrutinizing lubricant compositions and flavoring agent sourcing.
Core volume: Adults. Advocacy-driven expansion: LGBTQ+ Community.
Sales Channel:
Customer type migration from impulse to planned purchasing is redistributing volume across channel formats with divergent margin structures and working capital requirements.
- Online Retailers:Direct-to-consumer platforms and e-pharmacies enable discrete subscription replenishment with auto-replenishment algorithms, capturing urban millennial cohorts in São Paulo, Mumbai, and London who prioritize convenience over immediate availability.
- Pharmacies:Front-of-store sexual wellness destination categories in CVS, Walgreens, and Boots deliver professional endorsement credibility and insurance-adjacent purchasing contexts.
- Supermarkets:Mass retail placement captures impulse and routine grocery basket integration, though shelf space competition constrains flavor variety.
- Specialty Stores:Adult retail and sexual wellness boutiques offer experiential purchasing environments with staff consultation and sample availability.
- Convenience Stores:Immediate-need fulfillment with limited SKU depth serves travel and unplanned purchasing contexts at premium unit pricing.
Fastest volume shift: Online Retailers. Enduring trust anchor: Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate manufacturing to jurisdictions with lower cost-of-compliance burdens while maintaining FDA 510(k) equivalence through validated quality systems.
United States
DTC pharmacy platforms and subscription wellness services drive demand concentration in urban coastal metros. FDA 510(k) medical device clearance requirements enforce rigorous biocompatibility documentation for flavoring agents. Brooklyn and Austin health-tech clusters incubate direct-to-consumer brands bypassing traditional retail gatekeepers.
India
Pharmacy modernization in tier-two cities unlocks volume expansion as disposable incomes rise and sexual wellness normalizes. CDSCO and BIS standards govern local market access with specific labeling language requirements. Ahmedabad and Pune manufacturing zones host contract producers serving domestic and export markets with cost-optimized latex formulations.
Brazil
Tropical climate preferences favor mint and cooling-sensation variants where thermoreceptor activation drives sensory differentiation. ANVISA pharmaceutical regulations align with Mercosur harmonization efforts for cross-border trade. São Paulo's e-pharmacy ecosystem leads Latin American subscription adoption for discrete replenishment models.
Germany
CE marking under EU MDR governs medical device classification with EFSA scrutiny tightening approved flavoring substance lists. Berlin and Hamburg sexual wellness retail corridors professionalize category placement with pharmacist consultation services. Private-label penetration remains elevated as pharmacy chains consolidate procurement around contract manufacturers.
Malaysia
Natural rubber latex plantation proximity sustains raw material cost advantages for commodity-grade production. Malaysian Medical Device Authority regulations facilitate export-oriented manufacturing with FDA 510(k) equivalence pathways. Kuala Lumpur and Selangor industrial zones concentrate dip-molding capacity serving global private-label demand.
Flavored Condoms Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consumer-facing brands capturing margin premiums in pharmacy and DTC channels while OEM suppliers dominate volume through retail banner private-label programs. Market structure tilts toward upstream concentration in Malaysian and Thai production clusters, downstream fragmentation across regional brand portfolios. Three archetypes define competitive positioning: multinational FMCG conglomerates with sexual wellness divisions, regional pharmaceutical marketers with deep distribution, and pure-play contract manufacturers with scale-driven unit economics. Capacity expansion and strategic partnerships with e-pharmacy platforms constitute the dominant competitive moves reshaping channel access.
Within the contract manufacturing tier, Karex Berhad exemplifies scale-driven OEM supply to multiple retail banners worldwide. Among branded pharmaceutical marketers, Mankind Pharma anchors the Indian market through aggressive pricing and tier-two city penetration. Reckitt Benckiser Group plc occupies a position as the multinational conglomerate leveraging Durex brand equity across European and Asian pharmacy channels. These three represent the archetypal split between production-scale specialists, regional market-builders, and global brand owners competing through different margin and volume vectors.
| Leading Market Players |
|---|
| Mankind Pharma |
| Mayer Laboratories Inc. |
| Reckitt Benckiser Group plc |
| Pasante |
| Okamoto Industries, Inc. |
| Church & Dwight Co., Inc. |
| Veru Inc. |
| Trustex |
| Karex Berhad |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA 510(k) medical device tiers and commodity-grade private-label offerings creates parallel pricing architectures that feed directly into supply chain sourcing strategies. Premium polyisoprene variants command three-tier pricing structures across premium, standard, and economy levels by embedding biocompatibility documentation costs into unit economics, while commodity latex production in Malaysia and Thailand anchors spot-market pricing sensitive to plantation yield cycles.
Pricing Analysis
Distributor margin stacking in pharmacy retail channels compresses netbacks to manufacturers by fifteen to twenty-five percentage points relative to direct-to-consumer platforms. Price differentiation hinges on FDA 510(k) certification tier and brand equity accumulated through sustained pharmacy shelf placement. Pricing pressure stems from private-label concentration among Malaysian contract manufacturers, forcing branded players toward subscription models to escape margin erosion. Health-conscious consumers in the United States and United Kingdom demonstrate lowest price sensitivity, while price-sensitive volume concentrates in Indian tier-two cities where Mankind Pharma anchors aggressive entry-point positioning.
Supply Chain Analysis
Natural rubber latex supply rests on plantation networks concentrated across Malaysia, Thailand, and Indonesia, with synthetic polyisoprene feedstocks drawing from petrochemical complexes in the United States and South Korea. Critical inputs span centrifuged latex, food-grade flavoring agents, and water-based lubricant bases. Single-source vulnerability pervades menthol and cooling-agent sourcing from Indian specialty chemical producers. Distribution runs through pharmacy wholesale consignment, e-pharmacy direct fulfillment, and retail banner private-label programs with divergent working capital requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavored condoms function as a regulatory compounder where FDA 510(k) clearance timelines and EFSA additive scrutiny create defensive moats around validated manufacturers. CE marking under EU MDR emerges as the pivotal milestone accelerating cross-border product launches and consolidating procurement around compliant suppliers.
For Market Incumbents: To counter private-label pricing pressure from Malaysian contract manufacturers, Durex and Church & Dwight should deepen backward integration into flavoring-agent compounding and secure captive polyisoprene supply from South Korean petrochemical partners. Certification investment in accelerated FDA 510(k) pathways for novel cooling-sensation formulations preserves premium positioning against commodity erosion. For New Entrants and Emerging Players: Latex-allergic consumers in the United Kingdom and urban Germany represent an underserved buyer archetype willing to pay premium positioning for validated polyisoprene alternatives. Tier-two Indian pharmacy modernization offers penetrable white-space where digital-first brands can bypass legacy distributor relationships. Direct-to-consumer subscription models with auto-replenishment algorithms provide the most viable go-to-market angle against entrenched retail shelf dominance. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA 510(k) backlog delays and EFSA regulatory divergence strand sub-scale manufacturers without dual-continent compliance capabilities. Long-term viability favors contract manufacturers with validated quality systems serving multiple retail banners, or branded players with locked pharmacy distribution. Watch ANVISA harmonization progress with Mercosur standards as the inflection signal for Latin American production footprint decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Flavoring-Agent Compounding Integration | Backward integration into food-grade additive sourcing reduces EFSA compliance exposure and protects margin pools. |
| Polyisoprene Capacity Expansion | Synthetic elastomer production in South Korea and the United States captures latex-allergic premium tiers. |
| E-Pharmacy Subscription Partnership | Auto-replenishment integration with Boots and CVS digital platforms displaces impulse-buy volume. |
| Cooling-Sensation Formulation Pipeline | Menthol and thermoreceptor-activating variants address unmet tropical climate preferences in Brazil and Southeast Asia. |
| Dual-Jurisdiction Regulatory Filing | Parallel FDA 510(k) and CE marking submissions accelerate European and North American market access. |
Research Methodology
Multiple input streams — regulatory filing databases, trade customs records, and pharmacy procurement systems — were reconciled to construct demand and supply estimates. Primary interviews with FDA regulatory consultants, EMA notified body representatives, pharmacy category buyers, and contract manufacturing procurement heads were validated against secondary sources including FDA 510(k) clearance databases, EFSA additive safety opinions, CDSCO registration filings, and ANVISA pharmaceutical regulations. Bottom-up unit economics from dip-molding operations and top-down pharmacy channel audits were triangulated to anchor volume projections.
Historical shipment data were cross-referenced against panel input from manufacturing executives to calibrate growth assumptions across the projection horizon. Segmentation modeling incorporated flavor type, material substrate, end-user relationship context, and sales channel format. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Industry-specific forecast inputs included natural rubber latex price indices and e-pharmacy subscription adoption curves in São Paulo, Mumbai, and London.
Underlying measurement precision varies by segment; FDA 510(k) cleared products and pharmacy-tracked channels carry tighter precision than gray-market imports and convenience retail estimates. Forecasts reflect assumptions around regulatory approval timelines and plantation yield stability. Regulatory divergence between EFSA and FDA additive lists, alongside natural rubber price volatility, warrants ongoing watch as primary revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Boxed Glove for Food Market
Protective Gear
Insect Repellent Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Cooking Gloves Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Dust Covers Market
Protective Gear
Pet Control Devices Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Helmet Lining Market
Protective Gear
Military Boots Market
Protective Gear
Waterproof Cases Market
Protective Gear
Tactical Boots Market