
 Dust Covers Market | 2026-2036
Dust Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Dust Covers Market Foresight
Polyethylene film is pivoting toward recycled-content grades as converters seek lower virgin resin exposure. Donaldson Company leverages its filtration engineering heritage to anchor industrial-grade cover performance. Camfil AB sustains clean-air credibility that extends into contamination-sensitive cover applications. Nederman Holding AB competes through integrated dust collection and protection system bundling.
Dust covers are protective enclosures manufactured from woven or extruded polymer sheets, typically ranging from 4 to 12 mil thickness, designed to shield machinery, vehicles, and stored goods from particulate accumulation, moisture ingress, and UV degradation. Heavy-Duty Covers dominate margin pools where mining and construction equipment operators prioritize puncture resistance over unit cost. Custom-Fit Covers capture expanding demand from precision automation OEMs requiring dimensional tolerances that prevent abrasive contact with sensitive actuator surfaces. The Vinyl material segment retains strength in outdoor furniture applications where weatherability certifications determine specification adherence.
EPA NESHAP standards for particulate matter shape industrial cover specifications by mandating sealed containment during equipment idle periods. REACH substance restrictions in Europe limit certain phthalate plasticizers in vinyl formulations, redirecting compounder R&D toward bio-based alternatives. OSHA workplace dust exposure limits in the US create compliance-driven procurement protocols for manufacturing facility managers. Stakeholders must monitor evolving polymer recycling certification schemes that will soon differentiate supply-qualified vendors from specification-limited competitors.
Market Dynamics
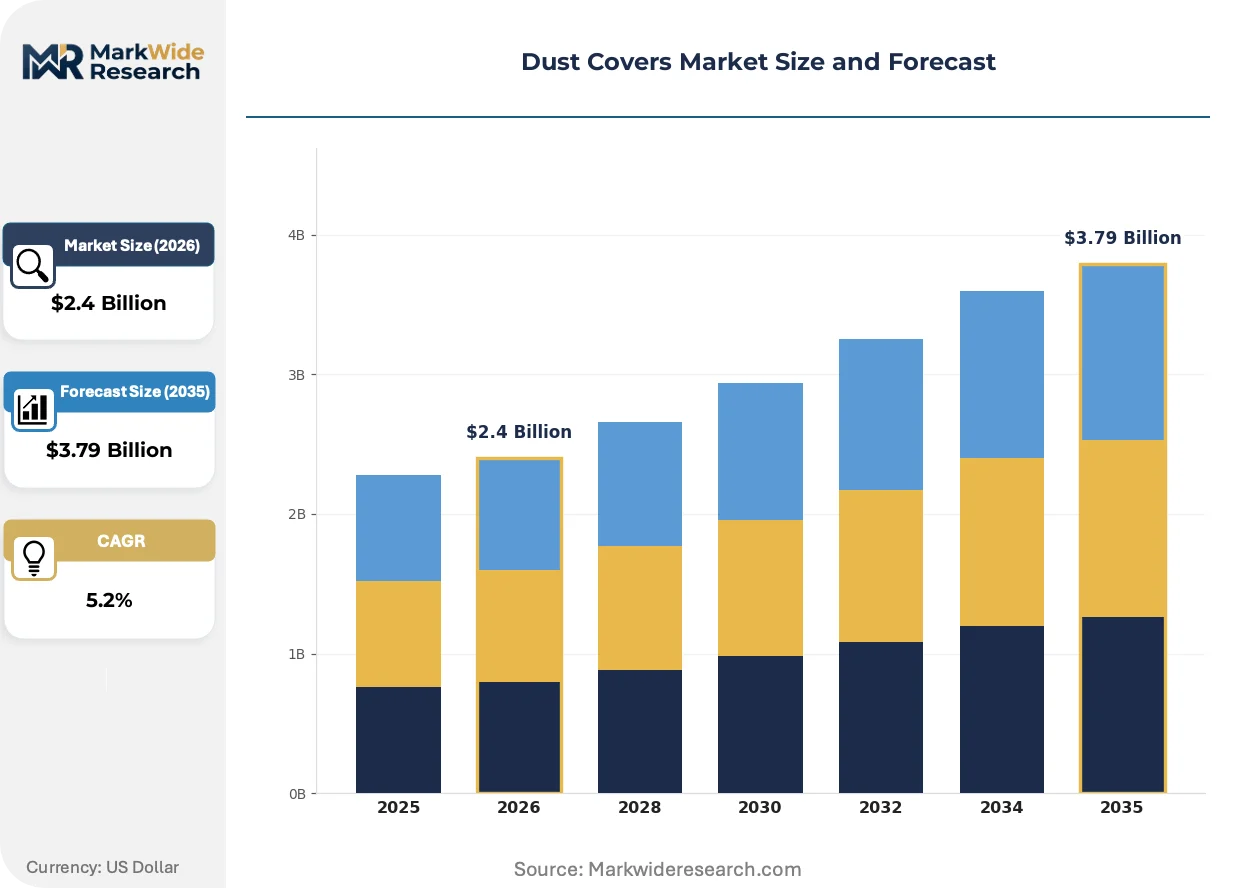
Factory automation expansion is compressing cover replacement cycles as precision equipment demands contamination-free idle states. REACH substance restrictions and EPA NESHAP particulate standards are simultaneously tightening material specifications and sealed-containment protocols.
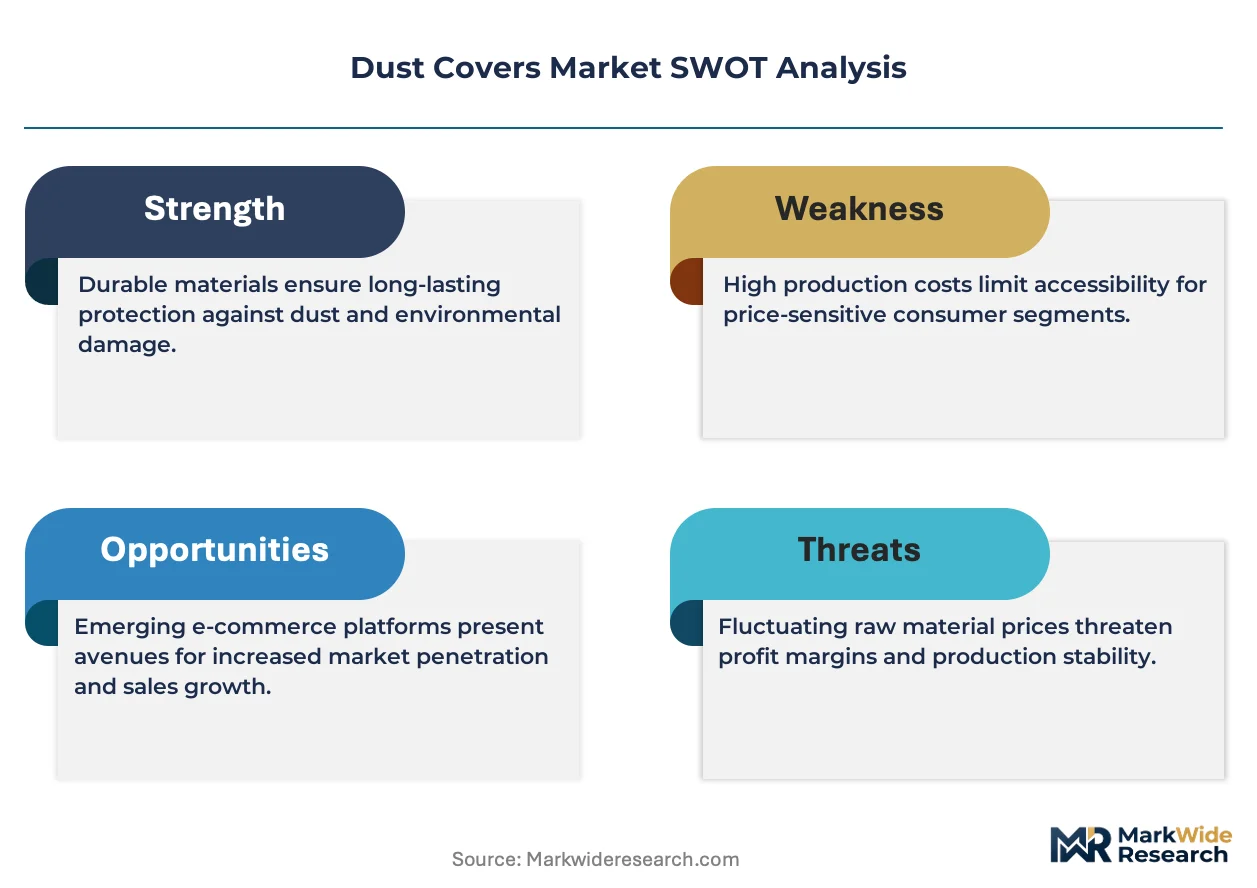
Growth Catalysts
- EPA NESHAP Standards:Mandated sealed containment during equipment idle periods drives specification-grade cover procurement across US manufacturing facilities.
- China Factory Automation:Expansion of precision robotics lines in Guangdong and Jiangsu provinces requires custom-fit protective solutions with sub-millimeter dimensional tolerances.
- Recycled Polyethylene Film:Converter investment in post-consumer resin processing infrastructure lowers virgin resin exposure and qualifies suppliers for emerging polymer certification schemes.
Market Restraints
- Phthalate Substitution Costs:REACH restrictions on legacy plasticizers in vinyl formulations force compounders toward bio-based alternatives with 15-25% raw material cost premiums.
- Regional Supply Concentration:Woven polymer sheet production clusters in Shandong Province create single-geography dependency risks for global cover distributors.
- Technical Performance Ceiling:12-mil thickness limits in extruded polyethylene constrain puncture resistance for heavy-duty mining equipment applications.
Strategic Opportunities
- India Manufacturing Corridors:Underpenetrated demand in Tamil Nadu and Gujarat industrial zones offers first-mover positioning ahead of PLI scheme maturation.
- Integrated Dust Collection Bundling:Convergence of protective covers with Nederman-style extraction systems creates specification lock-in for facility-wide contamination control.
- EU Green Deal Procurement:Public tender preference for recycled-content materials opens channel access for certified sustainable film converters.
Industry Challenges
- Polymer Chemist Talent Scarcity:Formulation expertise for bio-based plasticizer integration remains concentrated among legacy compounders with limited knowledge transfer.
- Certification Timeline Compression:Emerging polymer recycling certification schemes require 18-24 month validation cycles that outpace contract award windows.
- Legacy Equipment Integration:Custom-fit cover installation on pre-2015 automation lines demands retroactive dimensional surveying that delays deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust Covers Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Covers, Custom-Fit Covers, Standard Covers, Multi-Purpose Covers Material: Polyethylene, Vinyl, Canvas, Polyester Application: Automotive, Industrial Equipment, Outdoor Furniture, Household Items End User: Manufacturers, Retailers, Homeowners, Contractors |
| Companies Covered | Donaldson Company, Camfil AB, Ecolab, Nederman Holding AB, Dust Control Technologies, Quaker Houghton Corporation, Global Road Technology, Bai Er Rui Trade Co., Limited, Hexion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust Covers Market Shifts & Advancements
Material science advances and regulatory stringency are fragmenting the supplier base into certified specialists versus specification-limited generalists. Three developments are compressing competitive timelines.
Multi-layer co-extruded barrier films are decentralizing cover performance hierarchies by enabling mid-tier converters to match legacy puncture resistance at reduced gauge thickness. Precision automation OEMs in Germany and Japan are adopting these structures for actuator protection. The technology is decentralizing margin capture from established heavy-duty specialists toward regional film processors with co-extrusion capability.
REACH substance restrictions are forcing vinyl compounders toward bio-based plasticizer portfolios ahead of 2025 authorization sunset dates. Industrial cover specifications in France and Germany now require phthalate-free formulation certificates for public infrastructure tenders. Vinyl segment suppliers are responding with accelerated R&D partnerships with bio-polyol producers to maintain specification eligibility.
Buyers are consolidating cover procurement under facility-wide contamination control contracts that unbundle after-sales service from product supply. Automotive OEMs in Michigan and Bavaria are leading this transition toward multi-year performance agreements. The pattern is most visible in Germany where CSRD reporting requirements pressure procurement departments to document supplier ESG compliance across extended contract terms.
Dust Covers Market Segmentation
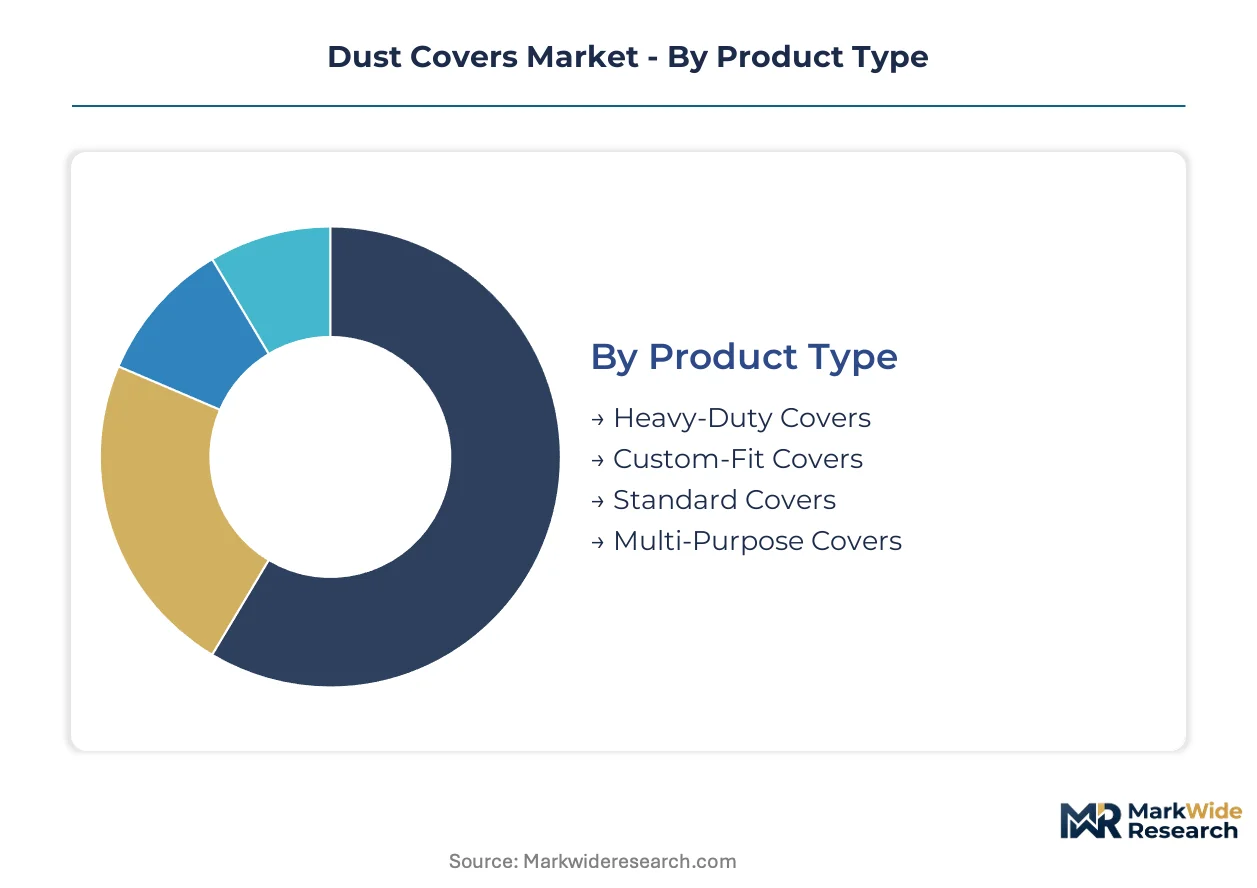
Dust cover procurement channels fragment across certification requirements that vary by end-use sensitivity. Material specifications and dimensional tolerances determine which segments qualify for precision automation contracts versus commodity replacement cycles.
Product Type:
Certification burdens concentrate in Custom-Fit Covers requiring sub-millimeter dimensional tolerances for actuator protection, while Heavy-Duty Covers face mining sector puncture-resistance protocols.
- Heavy-Duty Covers:Woven polymer sheets ranging 10-12 mil thickness with reinforced grommet patterns withstand abrasive mining and construction environments. Demand concentrates in Shandong Province manufacturing clusters where excavator fleet operators prioritize puncture resistance over unit cost in MEE dust emission compliance scenarios.
- Custom-Fit Covers:Precision-cut extruded films engineered to equipment CAD specifications prevent abrasive contact with sensitive robotics surfaces. Guangdong and Jiangsu automation corridors require these solutions for ISO-certified cleanroom idle states where particulate contamination voids warranty coverage.
- Standard Covers:Off-the-shelf polyethylene sheets serve general warehouse storage with minimal certification overhead.
- Multi-Purpose Covers:Adjustable-strap designs cross automotive and household applications without specification-grade material requirements.
Leading the category by volume: Standard Covers. Growing fastest: Custom-Fit Covers.
Material:
Cost tiers separate specification-grade films from commodity alternatives, with REACH-compliant vinyl commanding premium positioning against recycled-content polyethylene.
- Polyethylene:Co-extruded barrier films with post-consumer resin content now achieve 8-10 mil performance parity at reduced gauge. Converter investment in recycling infrastructure qualifies suppliers for EU Green Deal procurement preferences across German and French public infrastructure tenders.
- Vinyl:Weatherability-certified formulations dominate outdoor furniture applications where UV degradation resistance determines specification adherence. ECHA authorization sunset dates are forcing compounders toward bio-based plasticizer portfolios with 15-25% raw material cost premiums.
- Canvas:Natural fiber blends retain niche positioning in heritage equipment restoration segments.
- Polyester:Woven technical textiles serve high-temperature industrial environments requiring thermal stability beyond polymer film limits.
Polyethylene dominates volume throughput. Vinyl maintains margin concentration despite reformulation costs.
Application:
Customer type stratification separates OEM specification contracts from aftermarket replacement cycles across contamination-sensitive end-uses.
- Automotive:Paint shop and assembly line cover procurement integrates with CSRD-mandated supplier ESG documentation. Michigan and Bavaria OEMs are consolidating multi-year performance agreements that unbundle after-sales service from product supply.
- Industrial Equipment:EPA NESHAP sealed-containment mandates during idle periods drive specification-grade procurement across US manufacturing facilities. OSHA workplace dust exposure limits create compliance-driven protocols for facility managers.
- Outdoor Furniture:Consumer-grade weatherability certifications determine retail channel placement without industrial regulatory overhead.
- Household Items:Price-sensitive demand channels favor thin-gauge polyethylene without performance certification requirements.
Industrial Equipment anchors revenue concentration. Automotive applications are expanding most quickly.
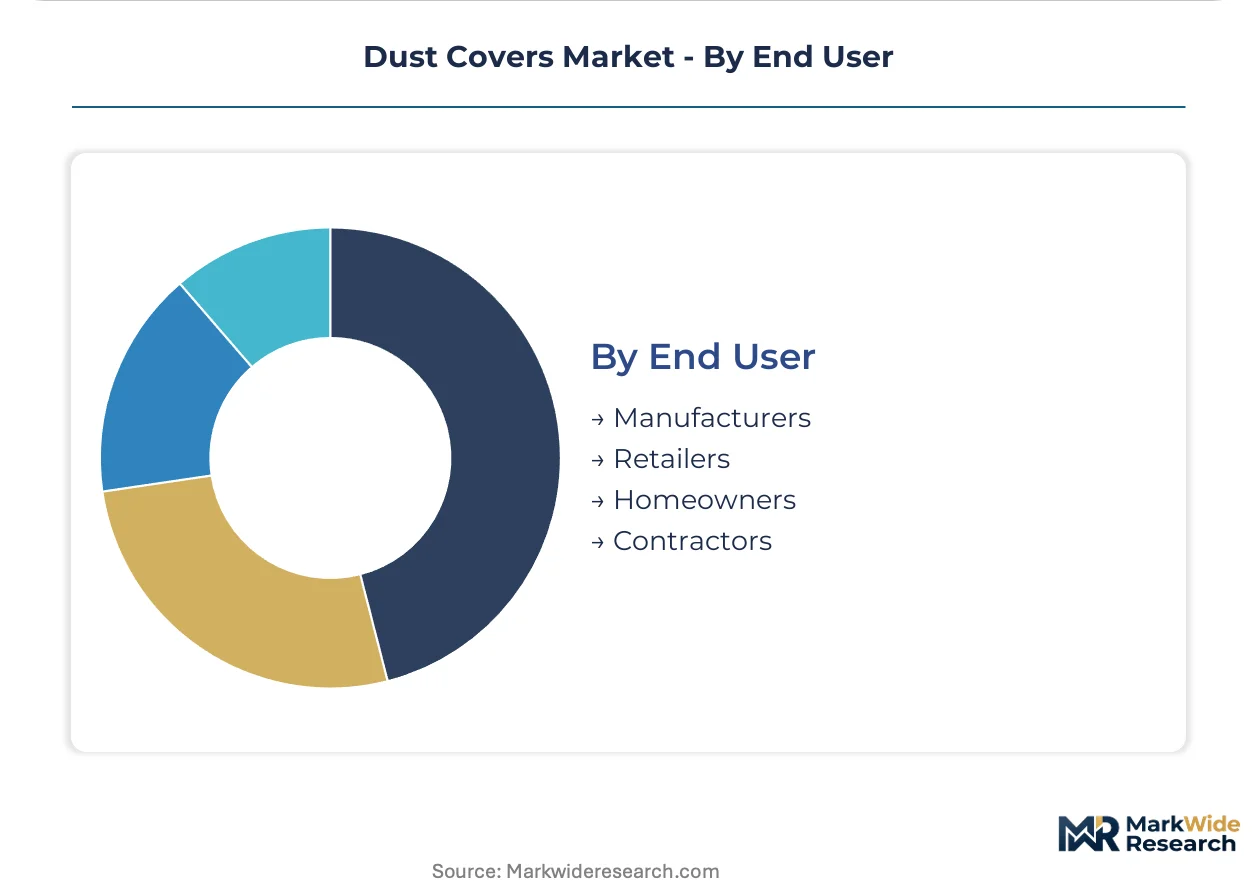
End User:
Procurement scale and contract duration separate enterprise manufacturing agreements from fragmented retail and consumer channels.
- Manufacturers:Factory automation expansion in China and India drives bulk contracting for precision-fit solutions with 18-24 month validation cycles. PLI scheme maturation in Tamil Nadu and Gujarat corridors is accelerating specification-grade demand.
- Contractors:Project-based procurement of Heavy-Duty Covers for construction and mining fleets operates on compressed replacement cycles tied to equipment utilization rates.
- Retailers:Seasonal inventory management of Standard and Multi-Purpose Covers follows consumer weather patterns without long-term contracting structures.
- Homeowners:Discretionary replacement demand concentrates in North American and European outdoor living segments.
Manufacturers command procurement volume. Contractor segment shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Guangdong Province concentrate precision manufacturing demand that shapes regional procurement patterns across industrial protection markets.
United States
EPA NESHAP particulate standards mandate sealed containment during equipment idle periods across Michigan automotive corridors and Texas petrochemical clusters. OSHA workplace dust exposure limits create compliance-driven procurement protocols for facility managers in these regions. Detroit-area OEMs consolidate multi-year performance agreements that unbundle after-sales service from product supply.
China
Factory automation expansion in Jiangsu and Guangdong provinces drives specification-grade cover demand for precision robotics lines. MEE dust emission compliance scenarios in Shandong Province manufacturing clusters prioritize puncture-resistant solutions for excavator fleet operators. Yangtze River Delta automation corridors require sub-millimeter dimensional tolerances for ISO-certified cleanroom idle states.
Germany
CSRD reporting requirements pressure procurement departments in Bavaria to document supplier ESG compliance across extended contract terms. REACH substance restrictions force compounders toward bio-based plasticizer portfolios ahead of authorization sunset dates. Stuttgart automotive OEMs lead the transition toward facility-wide contamination control contracts.
India
PLI scheme maturation in Tamil Nadu and Gujarat industrial zones accelerates specification-grade demand for precision-fit solutions. BIS standards for industrial equipment protection create certification benchmarks for domestic manufacturers. Mumbai-Pune manufacturing corridors attract first-mover positioning ahead of contract award windows.
Japan
METI industrial standards for contamination-sensitive manufacturing shape cover specifications in Kansai and Chubu robotics clusters. JIS certification requirements determine supplier eligibility for automotive paint shop procurement. Nagoya-area precision automation OEMs adopt multi-layer co-extruded barrier films for actuator protection.
Dust Covers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade procurement favoring certified specialists while commodity replacement cycles sustain regional fabricators. The vendor base organizes into three tiers: integrated filtration engineering groups, dedicated polymer film converters, and diversified industrial chemical suppliers. Consolidation pressure concentrates among mid-tier converters lacking co-extrusion capability or recycling certification infrastructure. Dominant competitive moves include backward integration into resin processing and geographic expansion through distributor network acquisition.
Within the integrated engineering tier, Donaldson Company and Nederman Holding AB exemplify archetypes that leverage filtration heritage into protective cover specifications. Camfil AB occupies a position among clean-air specialists extending credibility into contamination-sensitive applications. These three represent distinct strategic postures: machinery-anchored system bundling, extraction-integrated protection solutions, and air-quality-certified material specification.
| Leading Market Players |
|---|
| Donaldson Company |
| Camfil AB |
| Ecolab |
| Nederman Holding AB |
| Dust Control Technologies |
| Quaker Houghton Corporation |
| Global Road Technology |
| Bai Er Rui Trade Co., Limited |
| Hexion |
| Others |
Supply & Pricing Matrix
Automotive OEM procurement consolidation in Michigan and Bavaria anchors contract-based long-term offtake structures that unbundle after-sales service from product supply. Specification-grade cover vendors capture pricing power through ISO-certified dimensional tolerances while commodity converters face margin compression from recycled-content polyethylene oversupply.
Pricing Analysis
Short lead-time premiums of 20-30% apply to custom-fit cover orders requiring sub-millimeter tolerances for Guangdong automation corridors. Three-tier pricing structure across REACH-certified vinyl, recycled-content polyethylene, and standard-grade films differentiates by certification level and after-sales bundling. Cost compression in commodity polyethylene stems from converter investment in post-consumer resin processing infrastructure. Mining fleet operators in Shandong Province show lowest price sensitivity, prioritizing puncture resistance over unit cost in MEE compliance scenarios.
Supply Chain Analysis
Single-source vulnerability sits with woven polymer sheet production clusters in Shandong Province, where excavator fleet cover demand concentrates. Raw material flows draw from Saudi Arabian virgin resin, Chinese post-consumer recycling infrastructure, and German bio-based plasticizer development. Tariff exposure on polyethylene imports into the European Union threatens margin stability for distributors serving German automotive OEMs. Distribution runs through regional fabricator networks in China and integrated filtration engineering channels in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification timeline compression is forcing mid-tier converters without co-extrusion capability toward exit or acquisition, consolidating share among recycling-certified specialists.
For Market Incumbents: To counter bio-based plasticizer cost premiums eroding vinyl margins, compounders should deepen captive supply of bio-polyol feedstocks through backward integration into agricultural processing partnerships. REACH authorization sunset dates demand accelerated R&D expenditure to maintain specification eligibility in French and German public infrastructure tenders. For New Entrants and Emerging Players: Enter via underpenetrated PLI scheme corridors in Tamil Nadu and Gujarat, where first-mover positioning ahead of contract award windows offers specification-grade procurement access. Target precision automation OEMs in Jiangsu Province with multi-layer co-extruded barrier films that match legacy puncture resistance at reduced gauge thickness. For Investors and Strategic Acquirers: The window for entry favors converters with recycling certification infrastructure and co-extrusion capability. Acquisition targets should demonstrate validated post-consumer resin processing partnerships and existing supplier relationships with Yangtze River Delta automation clusters. Monitor ECHA authorization timeline adherence as the inflection indicator for vinyl segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polyol Supply | Secures feedstock access for REACH-compliant vinyl formulations ahead of authorization deadlines. |
| Recycling Certification Investment | Qualifies suppliers for EU Green Deal procurement preferences in German public tenders. |
| Co-Extrusion Capability Expansion | Enables mid-tier converters to match heavy-duty puncture resistance at reduced material gauge. |
| Geographic Expansion via Distributor Acquisition | Establishes presence in underpenetrated India manufacturing corridors ahead of PLI maturation. |
| Integrated Dust Collection Bundling | Creates specification lock-in through Nederman-style facility-wide contamination control contracts. |
Research Methodology
Document review covered EPA NESHAP filings, ECHA authorization databases, and Chinese MEE dust emission standards, complemented by interviews with plant engineers at precision automation OEMs, procurement leads at automotive manufacturers, compounder R&D directors, and aftermarket service heads. Secondary validation drew from customs trade data, SEC 10-K disclosures, and BIS certification records. Bottom-up demand modeling triangulated against top-down polymer consumption estimates.
Segment-level projections across product type, material grade, and application vertical fed into analytical frameworks spanning the projection horizon. CAGRs derived from equipment fleet expansion rates, automation penetration curves, and regulatory compliance mandate timelines. Industry-specific inputs included MEE enforcement intensity in Shandong Province and CSRD reporting adoption among Stuttgart-area OEMs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH authorization accelerations or polyethylene resin price spikes. Assumptions reflect documented regulatory timelines and announced converter capacity investments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Helmets Market
Protective Gear
Tactical Boots Market
Protective Gear
Boxed Glove for Food Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Waterproof Boots Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Diving Suits Market
Protective Gear
Insect Repellent Market
Protective Gear
China Pollution Mask Market
Protective Gear
Flavored Condoms Market
Protective Gear
Waterproof Cases Market
Protective Gear
Work Shoes Market
Protective Gear
Helmet Lining Market