
 Earplug Distributor Market | 2026-2036
Earplug Distributor Market Size, Share, and Industry Trends Forecast 2026-2036
Earplug Distributor Market Insights
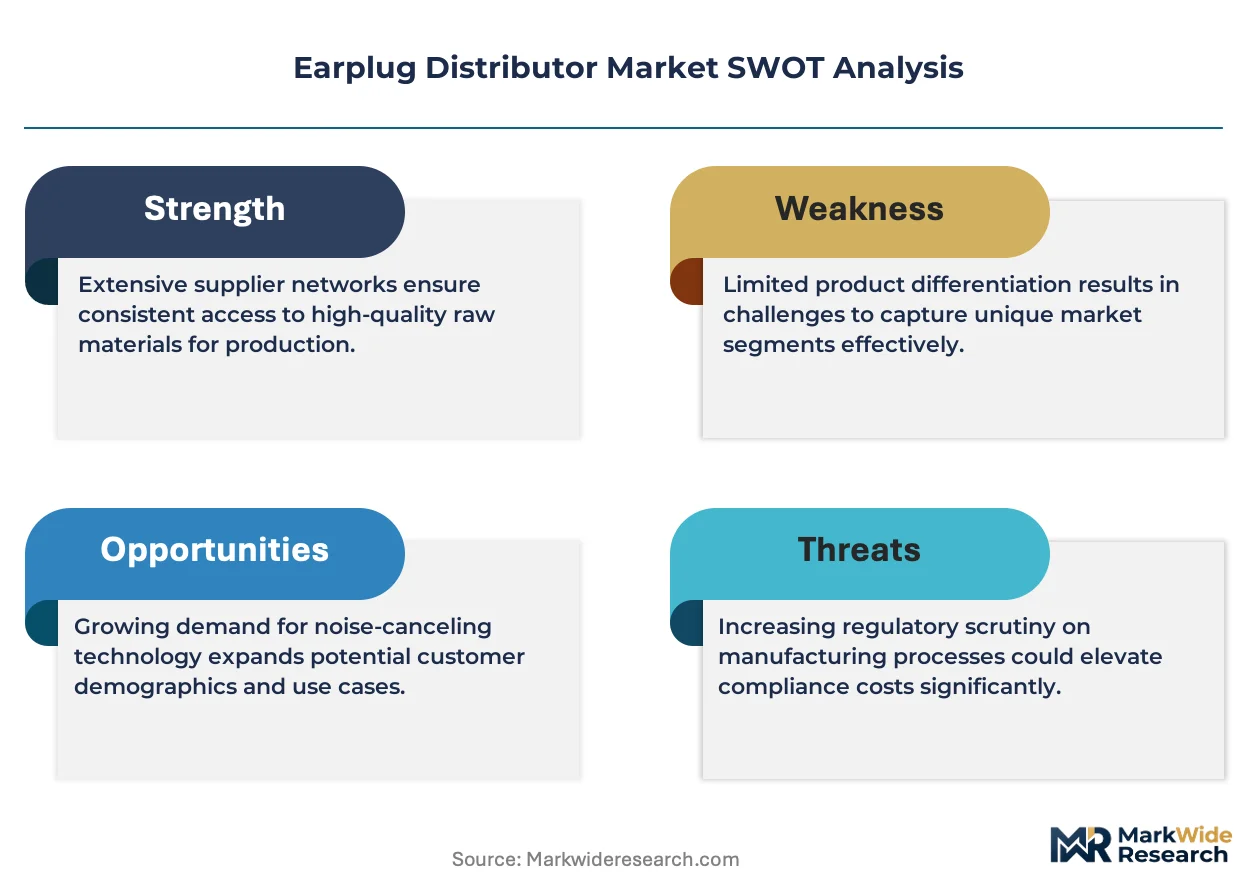
The capital-intensity divergence between mass-market foam producers and precision custom-fit laboratories is reorganizing distributor tier structures. 3M Company leverages its integrated raw-material supply chain to sustain price competitiveness at industrial scale. Honeywell International Inc. anchors its distributor relationships through ANSI-certified testing protocols and dedicated safety channel programs. Moldex-Metric Inc. differentiates via domestic U.S. manufacturing and rapid-turn private-label capabilities.
An earplug distributor operates as an intermediary entity that procures, warehouses, and resells hearing protection devices—typically constructed from polyurethane foam, silicone elastomer, or thermoplastic materials—to commercial and retail endpoints. These distributors manage inventory velocity across attenuation ratings measured in Noise Reduction Rating decibel values, serving occupational health programs, consumer wellness retailers, and recreational sporting goods channels. Foam earplugs occupy the highest volume tier due to disposable economics and bulk industrial procurement, while custom-fit earplugs concentrate margin pools through audiologist-mediated fitting services and recurring replacement cycles. Silicone earplugs represent the fastest-growing material segment among swimmers and musicians seeking reusable, moldable alternatives.
OSHA hearing conservation standards mandate baseline attenuation verification and annual audiometric testing for exposed workers, directly shaping distributor product certification requirements. ANSI S3.19-1974 and EN 352-2 standards govern laboratory testing protocols, creating compliance barriers for uncertified imports. The EU Green Deal chemical restrictions are beginning to pressure polyurethane foam formulations, compelling distributors to monitor REACH substance-of-very-high-concern listings. Stakeholders must decide whether to deepen supplier audits for sustainable material alternatives or accept margin compression from reformulation costs.
Market Dynamics
OSHA hearing conservation mandates are compressing procurement cycles across industrial distributors, forcing inventory repositioning toward certified attenuation SKUs while custom-fit laboratories capture premium sleep-aid and musician segments through audiologist-mediated channels.
Growth Catalysts
- Industrial Safety Mandates:OSHA hearing conservation standards mandate annual audiometric testing and baseline attenuation verification for exposed workers, forcing manufacturing and construction employers into bulk foam earplug procurement cycles.
- Polyurethane Foam Economics:Disposable single-use foam earplugs deliver unit costs below ten cents at industrial scale, sustaining volume dominance across manufacturing procurement budgets in the United States and Germany.
- EU Green Deal Chemical Pressure:REACH substance-of-very-high-concern listings targeting isocyanates in polyurethane formulations are accelerating distributor audits for sustainable material alternatives ahead of anticipated restrictions.
Market Restraints
- Raw Material Concentration:Polyurethane foam precursor supply concentrates among Asian petrochemical complexes, exposing distributors to freight cost volatility and tariff exposure on imported attenuation devices.
- Certification Friction:ANSI S3.19-1974 laboratory testing protocols create compliance barriers for uncertified imports, limiting distributor sourcing flexibility and extending new supplier onboarding timelines.
- Silicone Reusable Substitution:Moldable silicone alternatives threaten foam volume growth among swimmers and musicians seeking multi-use economics, compressing replacement frequency in premium consumer segments.
Strategic Opportunities
- Underpenetrated Sleep-Aid Retail:Pharmacy and wellness chains in Japan represent whitespace for custom-fit earplug fitting services, where audiologist-mediated channels remain underdeveloped relative to United States penetration.
- Smart Attenuation Convergence:Integration of active noise cancellation electronics with passive foam cores opens premium positioning for industrial distributors serving high-decibel precision manufacturing environments.
- Private-Label Acceleration:Rapid-turn domestic manufacturing capabilities enable distributor-owned brand development, capturing margin pools currently absorbed by 3M and Honeywell channel programs.
Industry Challenges
- Audiologist Network Scarcity:Custom-fit earplug scaling depends on certified hearing healthcare professional density, creating geographic coverage gaps that constrain laboratory service expansion into secondary United States markets.
- Reformulation Capex Burden:REACH-compliant polyurethane foam development requires dedicated R&D facilities and toxicology testing budgets that mid-tier distributors cannot absorb without supplier partnership restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earplug Distributor Market |
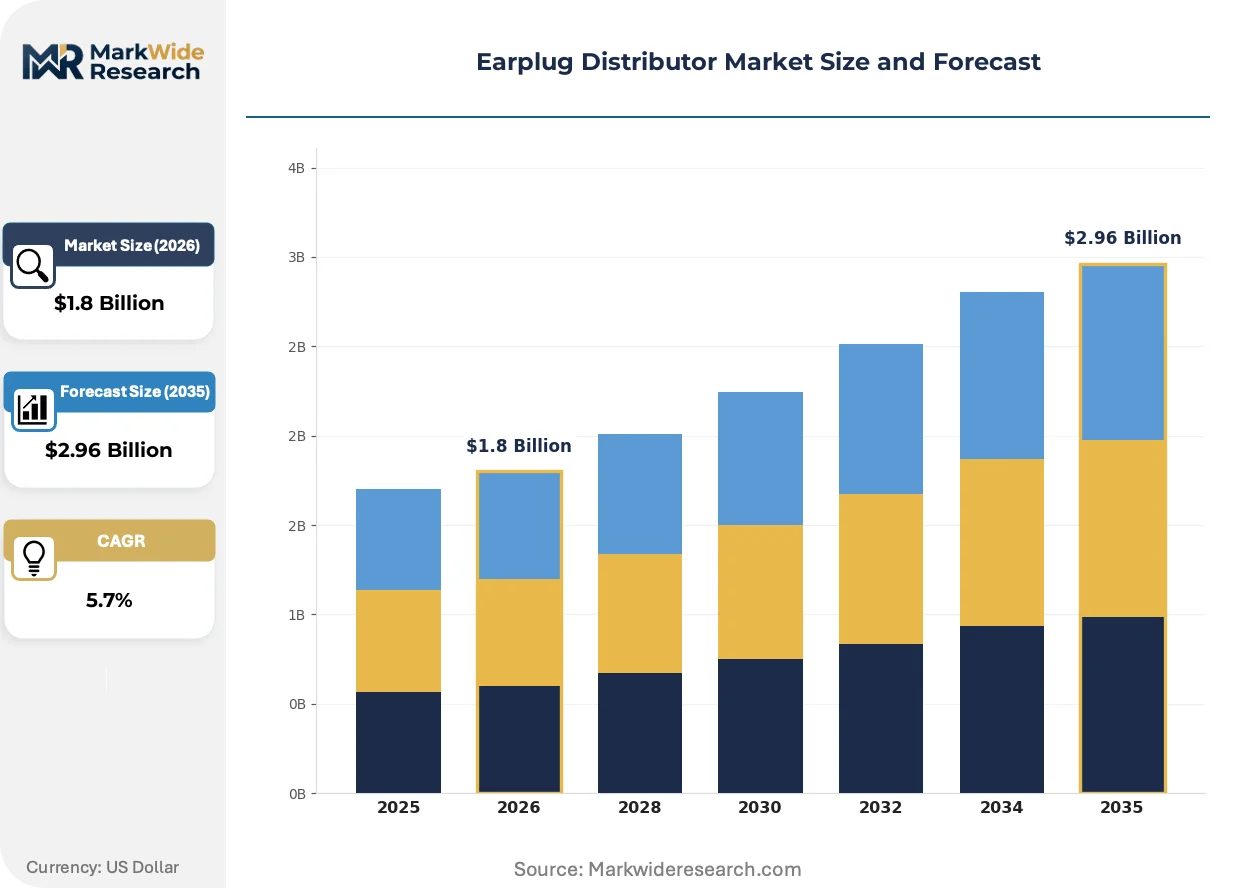
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Earplugs, Silicone Earplugs, Wax Earplugs, Custom-Fit Earplugs Application: Noise Reduction, Sleeping, Swimming, Shooting End User: Consumers, Industrial Workers, Musicians, Athletes Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | 3M Company, Honeywell International Inc., Moldex-Metric Inc., Radians Inc., Magid Glove & Safety Manufacturing Company LLC, Cordova Safety Products, NMC, Brady, Horizon Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earplug Distributor Market Trends and Innovations
Material science advances and regulatory chemical scrutiny are splitting the earplug distributor market into parallel supply chains—one optimized for disposable industrial volume, the other engineered for precision-fitted premium segments with recurring replacement economics.
Smart attenuation technology is bifurcating the industrial safety segment. Active noise cancellation electronics integrated into passive foam cores now serve precision manufacturing workers in semiconductor cleanrooms and aircraft engine testing facilities. Adoption concentrates among employers with noise exposure exceeding 100 decibels where communication clarity remains critical. This convergence is compressing traditional passive-only distributor margins while creating premium SKU tiers with 3-5 year replacement cycles versus foam's daily disposal rate.
REACH substance-of-very-high-concern listings are forcing polyurethane foam reformulation across European distributor portfolios. ECHA evaluations targeting isocyanate exposure risks threaten existing supply chain configurations for foam earplugs serving German industrial markets. Distributors are responding by deepening supplier audits for bio-based polyol alternatives, though certified attenuation performance under ANSI S3.19-1974 remains unproven for next-generation formulations.
Pharmacy channel consolidation is reshaping consumer earplug procurement patterns. CVS and Walgreens shelf-space reductions for disposable foam SKUs favor silicone reusable alternatives with higher unit margins and lower restocking frequency. This rotation is most visible in United States suburban markets where sleep-aid category management now prioritizes moldable silicone over bulk foam multipacks, compressing distributor volume commitments to mass retail while elevating specialty audiology clinic partnerships.
Earplug Distributor Market Segmentation
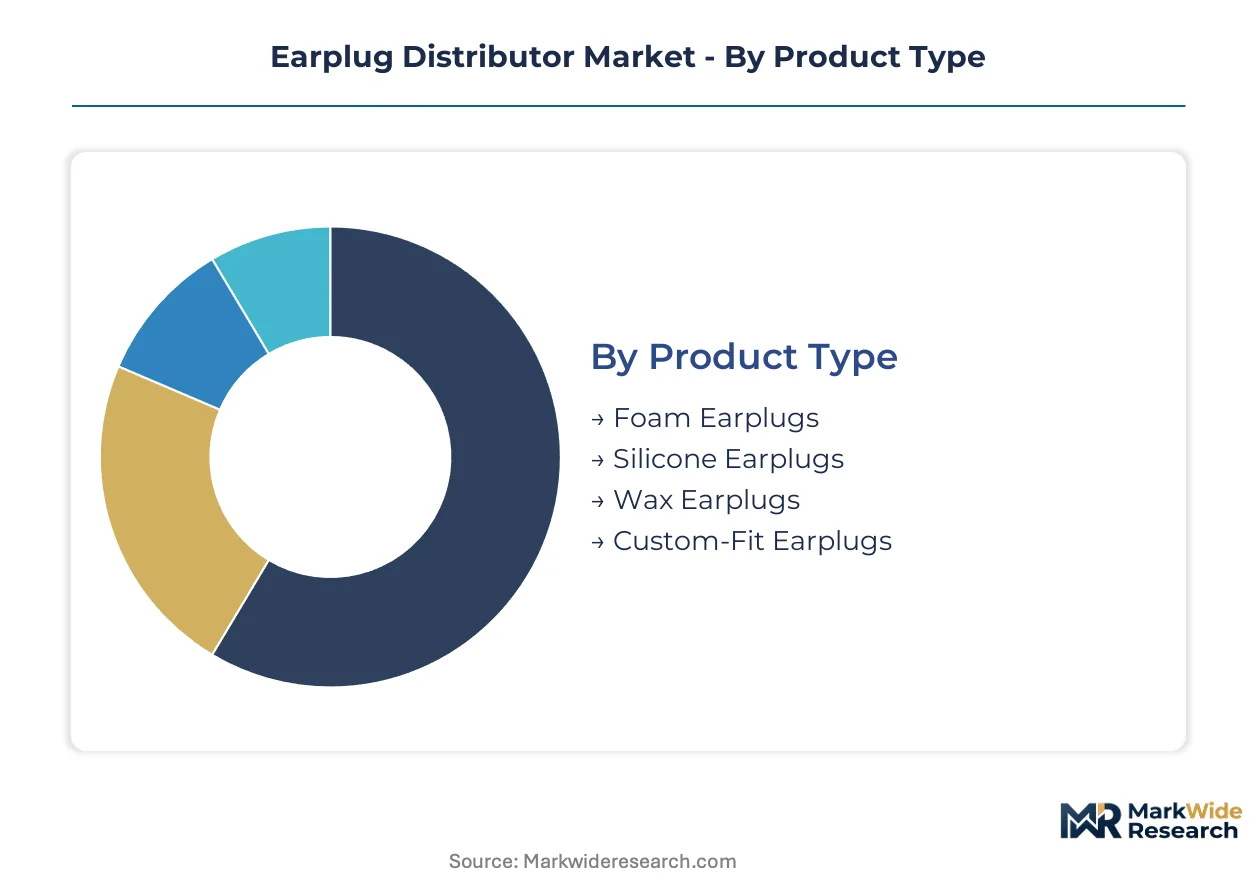
Distributor procurement patterns diverge sharply between disposable industrial volume and precision-fitted premium channels. Material composition and fitting methodology determine margin structure, replacement frequency, and regulatory certification burden across each segment tier.
Product Type:
Silicone and custom-fit alternatives exert mounting substitution pressure on foam dominance, particularly in consumer wellness and professional audio segments where reusability commands premium positioning.
- Foam Earplugs:Polyurethane foam construction delivers single-use attenuation with NRR ratings typically ranging 29-33 decibels. Manufacturing and construction employers in the United States and Germany drive bulk procurement cycles under OSHA hearing conservation mandates, though REACH chemical scrutiny threatens European supply stability.
- Silicone Earplugs:Moldable silicone elastomer enables multi-use economics with 5-10 day replacement intervals. Swimmers and musicians in Japan and Germany favor this segment for watertight seals and frequency-preserved audio clarity, compressing foam growth in premium consumer tiers.
- Wax Earplugs:Cotton-impregnated beeswax formulations offer moldable comfort for sleep-aid users seeking complete occlusion without ear canal pressure.
- Custom-Fit Earplugs:Audiologist-mediated thermoplastic impressions deliver personalized attenuation profiles for professional musicians and industrial workers requiring communication clarity in high-decibel environments.
Foam earplugs retain volume leadership; silicone alternatives hold the steepest expansion curve.
Application:
Cost tier stratification separates mandated occupational procurement from discretionary wellness purchases, with pricing elasticity varying tenfold across use cases.
- Noise Reduction:Industrial safety programs mandate baseline attenuation verification under OSHA standards, forcing manufacturing employers into certified foam bulk purchasing with documented NRR compliance.
- Sleeping:Pharmacy and wellness channel consolidation favors silicone and wax alternatives with higher unit margins and lower shelf restocking frequency in United States suburban markets.
- Swimming:Watertight silicone designs prevent otitis externa among competitive swimmers and recreational aquatic users.
- Shooting:Electronic hearing protection with passive foam cores serves precision marksmen requiring ambient sound awareness alongside impulse noise attenuation.
Noise reduction commands procurement volume; sleeping applications deliver the fastest margin expansion.
End User:
Customer type determines distributor channel strategy, with industrial procurement running through safety distributors while musicians and athletes access products via specialty audiology clinics and sporting goods retailers.
- Consumers:Pharmacy and supermarket channels serve sleep-aid and travel comfort needs with impulse-purchase price points below five dollars.
- Industrial Workers:Manufacturing and construction employers in Germany and the United States drive bulk foam procurement under tightening hearing conservation enforcement.
- Musicians:Custom-fit laboratories capture premium positioning through audiologist-mediated fitting services with recurring replacement cycles.
- Athletes:Swimmers and shooters demand specialized attenuation profiles combining watertight seals or electronic ambient awareness.
Industrial workers anchor procurement tonnage; musicians generate the highest per-unit distributor margins.
Distribution Channel:
Supply concentration in Asian petrochemical complexes shapes channel economics, with direct import models compressing traditional distributor margins in online retail while specialty stores preserve value-added fitting services.
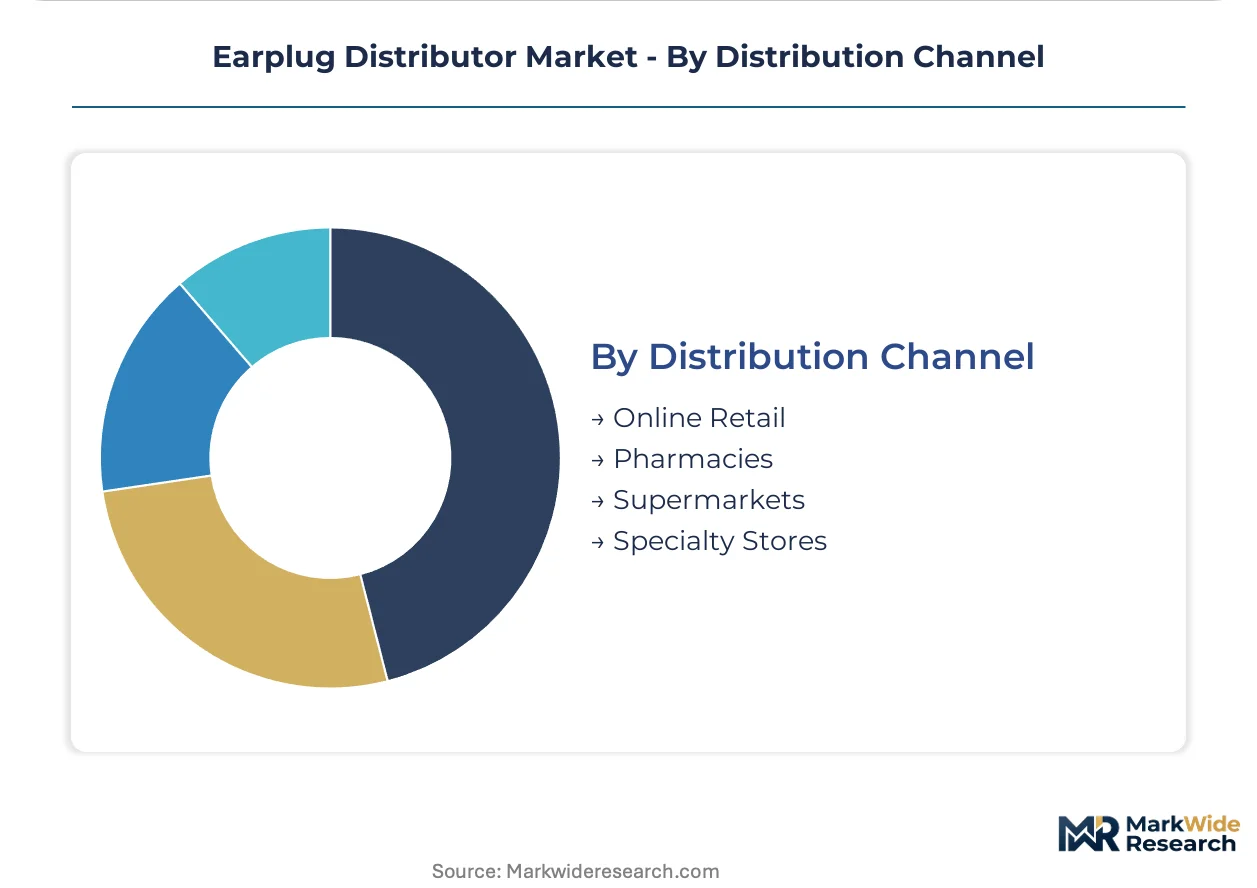
- Online Retail:Amazon and direct-to-consumer platforms aggregate bulk foam purchasing for industrial buyers and subscription-model sleep-aid replenishment.
- Pharmacies:CVS and Walgreens shelf-space rotations favor silicone reusable SKUs with higher turnover efficiency and reduced inventory carrying costs.
- Supermarkets:Mass retail placement captures impulse travel and hardware aisle purchases with economy-tier foam multipacks.
- Specialty Stores:Audiology clinics and sporting goods retailers deliver custom-fit services and electronic hearing protection with trained fitting support.
Online retail captures volume velocity; specialty stores defend margin through service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial procurement channels, where REACH compliance premiums and audiologist network density sustain margin structures unavailable to distributors serving price-sensitive bulk buyers in emerging Asian markets.
United States
OSHA hearing conservation enforcement tightens across manufacturing corridors in Ohio and Michigan, compelling construction and automotive employers into certified attenuation procurement cycles. The Department of Labor mandates documented NRR verification and annual audiometric testing for exposed workers above 85 decibels. Industrial distributors in the Chicago-Gary manufacturing cluster reposition inventory toward ANSI-certified SKUs as compliance audits intensify.
Germany
REACH substance-of-very-high-concern listings targeting isocyanates in polyurethane formulations pressure foam earplug supply stability. ECHA regulatory timelines accelerate distributor audits for bio-based polyol alternatives ahead of anticipated restrictions. Audiologist-mediated custom-fit laboratories in Bavaria and North Rhine-Westphalia capture premium sleep-aid and professional musician segments through recurring replacement economics.
Japan
Pharmacy and wellness chains in Tokyo and Osaka represent underpenetrated whitespace for custom-fit earplug fitting services. METI industrial safety guidelines shape procurement patterns for precision manufacturing employers. Swimmers and musicians in the Kansai region drive silicone earplug demand for watertight seals and frequency-preserved audio clarity.
China
Polyurethane foam precursor supply concentrates in Yangtze River Delta petrochemical complexes, exposing distributors to freight cost volatility and tariff exposure on exported attenuation devices. MIIT standards govern domestic hearing protection certification. Manufacturing employers in the Pearl River Delta face rising compliance requirements as workplace safety enforcement tightens.
United Kingdom
Post-Brexit regulatory divergence from EU REACH frameworks creates certification friction for distributors serving cross-channel supply chains. The Health and Safety Executive maintains hearing conservation requirements parallel to historical EU directives. Industrial procurement in the Midlands manufacturing belt favors rapid-turn domestic sourcing to navigate customs complexity.
Earplug Distributor Market Competitive Landscape
Concentration sits with integrated raw-material suppliers and domestic manufacturing specialists who control upstream foam formulation or downstream fitting service networks. The vendor base stratifies across three tiers: multinational conglomerates with captive chemical supply, mid-cap domestic manufacturers with private-label agility, and specialized audiology laboratories with recurring replacement economics. Scale-driven players deepen backward integration into polyurethane precursor supply, while premium-tier competitors anchor positioning through audiologist partnership density.
Among the named participants, 3M Company exemplifies the integrated conglomerate archetype through captive raw-material supply chains. Honeywell International Inc. occupies a position within the certification-heavy industrial safety tier. Moldex-Metric Inc. represents the domestic manufacturing specialist archetype with rapid-turn private-label capabilities. These three anchors illustrate the competitive divergence between volume-driven foam distribution and precision-fitted premium channel development.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Moldex-Metric Inc. |
| Radians Inc. |
| Magid Glove & Safety Manufacturing Company LLC |
| Cordova Safety Products |
| NMC |
| Brady |
| Horizon Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day foam earplug inventory cycles at industrial distributors compress pricing power when Yangtze River Delta petrochemical disruptions spike polyurethane precursor costs, forcing buyers toward strategic stockpiling or premium silicone alternatives.
Pricing Analysis
Configured-to-order custom-fit pricing commands four-to-six-fold premiums over standard foam SKUs, with audiologist-mediated services and ANSI-certified attenuation verification driving differentiation. Three-tier pricing structure across premium custom-fit, standard silicone reusable, and economy foam disposable levels stratifies procurement budgets. Pricing pressure stems from REACH-compliant polyurethane reformulation costs as ECHA isocyanate scrutiny intensifies. Manufacturing employers in Germany and the United States exhibit highest price sensitivity at bulk industrial scale, while musicians and sleep-aid consumers in Japan show lowest elasticity for precision-fitted alternatives.
Supply Chain Analysis
Just-in-time inventory strategies dominate foam earplug distribution, though REACH regulatory uncertainty pushes select distributors toward strategic stockpiling of certified polyurethane inventory. Raw material supply concentrates in China, Germany, and the United States, with isocyanate-based polyol production anchored in Asian petrochemical complexes. Formulation chemistry depends on toluene diisocyanate, polyether polyols, and silicone elastomer feedstocks. Single-source vulnerability from Yangtze River Delta concentration exposes distributors to freight cost volatility and tariff exposure. Distribution runs through industrial safety distributors, audiology clinic networks, and pharmacy retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone reusable alternatives and smart attenuation electronics pose acute substitution threats that foam-centric distributors must navigate through material diversification and premium channel development.
For Market Incumbents: Compound defensive positioning through backward integration into bio-based polyol R&D partnerships ahead of REACH restriction timelines, while deepening audiologist network density in underpenetrated Japanese pharmacy channels to capture recurring custom-fit replacement economics.
For New Entrants and Emerging Players: Anchor in Tokyo-Osaka pharmacy whitespace for audiologist-mediated fitting services, where METI industrial safety awareness and sleep-aid category growth create penetrable entry points through direct clinic partnerships rather than mass retail competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates divesting non-core hearing protection divisions; mid-cap domestic manufacturers with rapid-turn private-label capabilities and established ANSI certification infrastructure offer strongest five-to-ten-year viability as regulatory compliance barriers intensify. Monitor ECHA substance-of-very-high-concern listing announcements as inflection indicators for polyurethane supply chain restructuring velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | Bio-based polyol development secures European market access ahead of ECHA isocyanate restrictions. |
| Audiologist Network Expansion | Clinic partnerships in Japan capture premium sleep-aid and musician segments with recurring revenue. |
| Smart Attenuation Integration | Active noise cancellation electronics serve semiconductor cleanrooms requiring communication clarity. |
| Private-Label Manufacturing Scale-Up | Domestic rapid-turn capabilities capture margin pools from 3M and Honeywell channel programs. |
| Industrial Safety Distributor Consolidation | OSHA compliance audit intensity favors scaled distributors with ANSI-certified SKU breadth. |
Research Methodology
Cross-validation between distributor procurement data and regulatory filing analysis anchors the qualitative findings. Primary interviews with industrial safety procurement managers, audiology clinic operators, pharmacy category buyers, and foam manufacturing plant directors combined with secondary validation from OSHA enforcement records, ECHA substance evaluations, and customs trade data. Bottom-up SKU-level volume analysis triangulates against top-down industrial employment exposure estimates across manufacturing corridors.
Sensitivity analysis around polyurethane precursor cost volatility and REACH restriction timelines shapes the analytical framework. Segmentation dimensions span material composition, fitting methodology, end-user archetype, and distribution channel across the projection horizon. CAGRs derive from attenuation device replacement frequency modeling and occupational health program penetration rates. Industry-specific inputs include audiologist network density indices and OSHA compliance audit intensity scores.
Decision-makers should treat outputs as directional under stable regulatory enforcement and raw material supply assumptions; material deviation would warrant model refresh. Revision becomes warranted when ECHA substance-of-very-high-concern listings or MIIT domestic certification requirements cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Work Boots Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Heated Goggles Market
Protective Gear
Safety Shoes Market
Protective Gear
Helmets Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Diving Suits Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Combat Boots Market
Protective Gear
Waterproof Cases Market
Protective Gear
Dust Covers Market
Protective Gear
Bungee Cords and Accessories Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Tactical Boots Market
Protective Gear
Home Outdoor Pest Control Devices Market