
 Boxed Glove for Food Market | 2026-2036
Boxed Glove for Food Market Size, Share, and Industry Trends Forecast 2026-2036
Boxed Glove for Food Market Insights
FDA Food Code updates around bare-hand contact restrictions is shifting the cost-of-entry calculus for foodservice operators, mandating disposable barrier use across prep and service lines. Hartalega Holdings Berhad leverages its nitrile-dominant capacity to anchor supply contracts with North American distributors. Kossan Rubber Industries Berhad competes through integrated latex and synthetic lines that sustain margin flexibility. Ansell Limited differentiates via ASTM and ISO-certified product portfolios that command specification in regulated processing environments.
Boxed gloves for food denote single-use or limited-use hand protection distributed in retail-ready cartons, typically manufactured from nitrile, vinyl, latex, or polyethylene films with thickness specifications ranging from 3 to 8 mil for puncture resistance and tactile sensitivity. These products serve primarily to prevent biological and allergen cross-contamination between food handlers and consumable products across commercial and institutional settings. Nitrile gloves occupy the fastest-expanding material position due to latex allergy prevalence and superior chemical resistance against sanitizers and fats. Disposable gloves dominate volume flows through food processing and catering channels, while reusable silicone and neoprene variants retain niche positions in high-temperature processing segments where extended wear cycles justify capital investment.
FDA approval requirements, CE marking under EU food contact regulations, and ASTM barrier-performance standards collectively shape product qualification pathways and OEM sourcing decisions across major economies. Compliance divergence between FDA 21 CFR 177.2600 rubber specifications and EU Framework Regulation 1935/2004 creates formulation complexity for multinational suppliers serving dual markets. Stakeholders must monitor evolving state-level plasticizer restrictions and compostability mandates that threaten incumbent vinyl and polyethylene formulations.
Market Dynamics
Quick-service restaurant chains and centralized kitchen operations are consolidating procurement around standardized glove specifications, creating volume concentration that favors suppliers with certified manufacturing scale and multi-site distribution capability.
Growth Catalysts
- FDA Food Code bare-hand contact barriers:Updated requirements mandate disposable glove use across prep and service lines, expanding addressable demand in commercial foodservice.
- Nitrile material substitution:Latex allergy prevalence and superior chemical resistance against sanitizers and fats accelerate conversion from vinyl and natural rubber alternatives.
- Franchise standardization programs:National quick-service chains specify uniform barrier protection across locations, locking in multi-year supply agreements with qualified vendors.
Market Restraints
- Acrylonitrile price volatility:Nitrile glove production depends on petrochemical feedstocks exposed to energy market fluctuations, compressing margin predictability for converters.
- Malaysian supply concentration:Dominant nitrile capacity clusters in Southeast Asian manufacturing zones, creating geographic vulnerability to logistics disruption or trade policy shifts.
- EU Framework Regulation 1935/2004 compliance divergence:Formulation requirements for food contact materials differ from FDA 21 CFR 177.2600 specifications, raising qualification costs for dual-market suppliers.
Strategic Opportunities
- Compostable polymer development:State-level plasticizer restrictions and organic waste mandates create white space for biodegradable barrier alternatives in environmentally regulated jurisdictions.
- Cloud kitchen infrastructure:Delivery-optimized food preparation facilities require high-throughput disposable protection with minimal storage footprint, favoring compact carton formats.
- ASTM D6319-certified portfolio expansion:Medical-grade barrier standards increasingly specified for high-risk food processing segments, enabling premium positioning for certified manufacturers.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, CE marking, and ISO 9001 qualification processes extend product launch cycles by 12-18 months for new formulations.
- Automated dispensing integration:High-volume operators require glove dispensing systems compatible with existing hygiene infrastructure, demanding custom carton dimensions and perforation patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boxed Glove for Food Market |
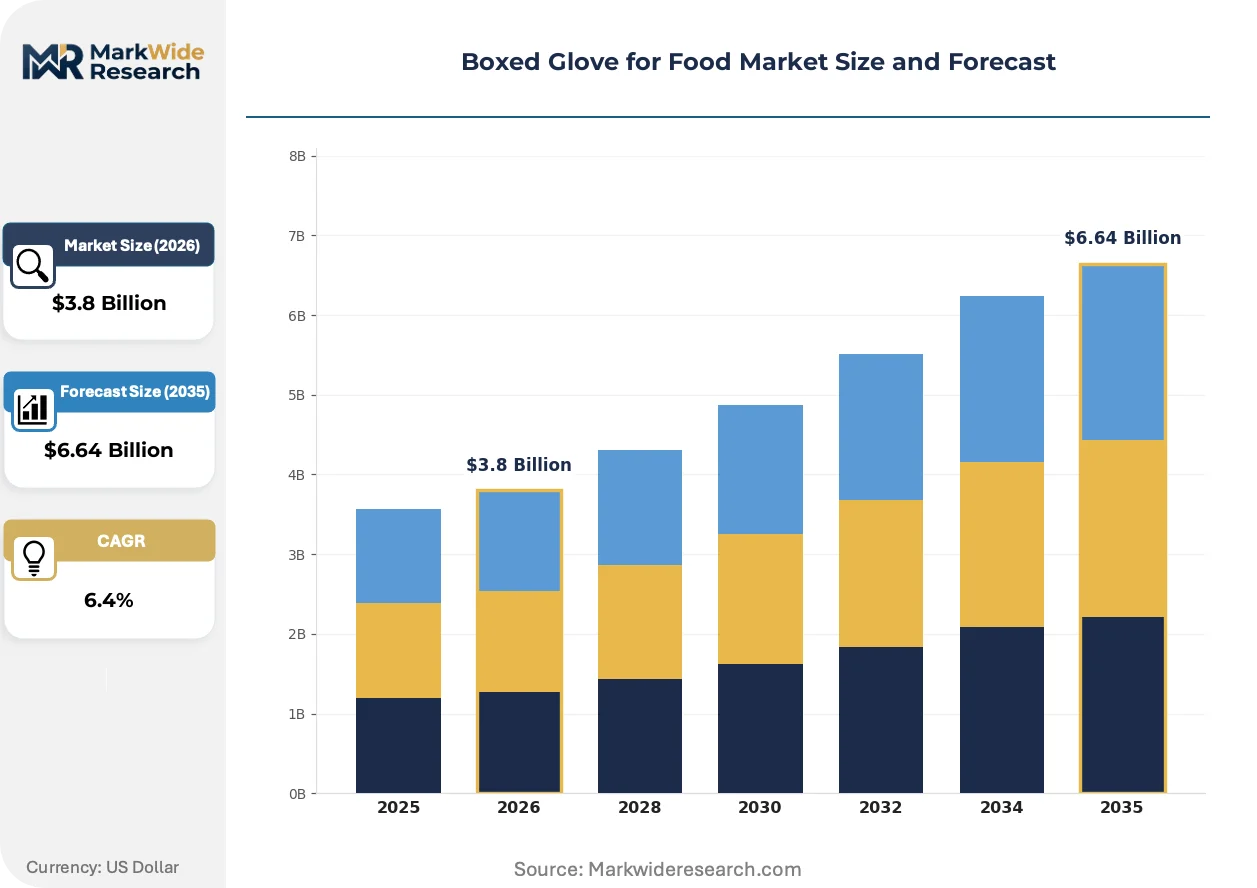
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Gloves, Reusable Gloves, Nitrile Gloves, Latex Gloves Material: Nitrile, Vinyl, Latex, Polyethylene Application: Food Processing, Catering, Food Handling, Food Delivery Compliance Standard: FDA Approved, CE Certified, ASTM Compliant, ISO Certified |
| Companies Covered | Top Glove Corporation Berhad, Hartalega Holdings Berhad, Kossan Rubber Industries Berhad, Ansell Limited, Sri Trang Gloves, Supermax Corporation Berhad, Semperit, AMMEX, Brightway Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boxed Glove for Food Market Trends and Innovations
Active reshaping in this market centers on material science advancement, regulatory harmonization pressure, and procurement consolidation among multi-site foodservice operators seeking supply security.
Biodegradable nitrile formulations incorporating plant-based plasticizers are decentralizing sourcing decisions away from traditional petrochemical-dependent supply chains. Mid-sized regional distributors in California and Germany are piloting compostable alternatives to meet corporate sustainability commitments. This material transition is decentralizing procurement authority from centralized purchasing departments to facility-level sustainability officers with localized vendor relationships.
REACH restrictions on phthalate plasticizers are forcing reformulation of vinyl glove lines intended for European food contact applications. Manufacturers serving EU markets must eliminate DINP and DEHP compounds or exit the segment entirely. German and French distributors are accelerating qualification of phthalate-free alternatives ahead of 2025 enforcement deadlines, creating first-mover advantage for compliant suppliers.
Direct contracting between glove converters and national restaurant chains is compressing traditional distribution tiers. Group purchasing organizations are losing volume share as operators consolidate spend with single-source manufacturers offering guaranteed supply and custom branding. This channel restructuring is most visible in the United States, where franchise systems with 500-plus locations negotiate master agreements bypassing regional distributors entirely.
Boxed Glove for Food Market Segmentation
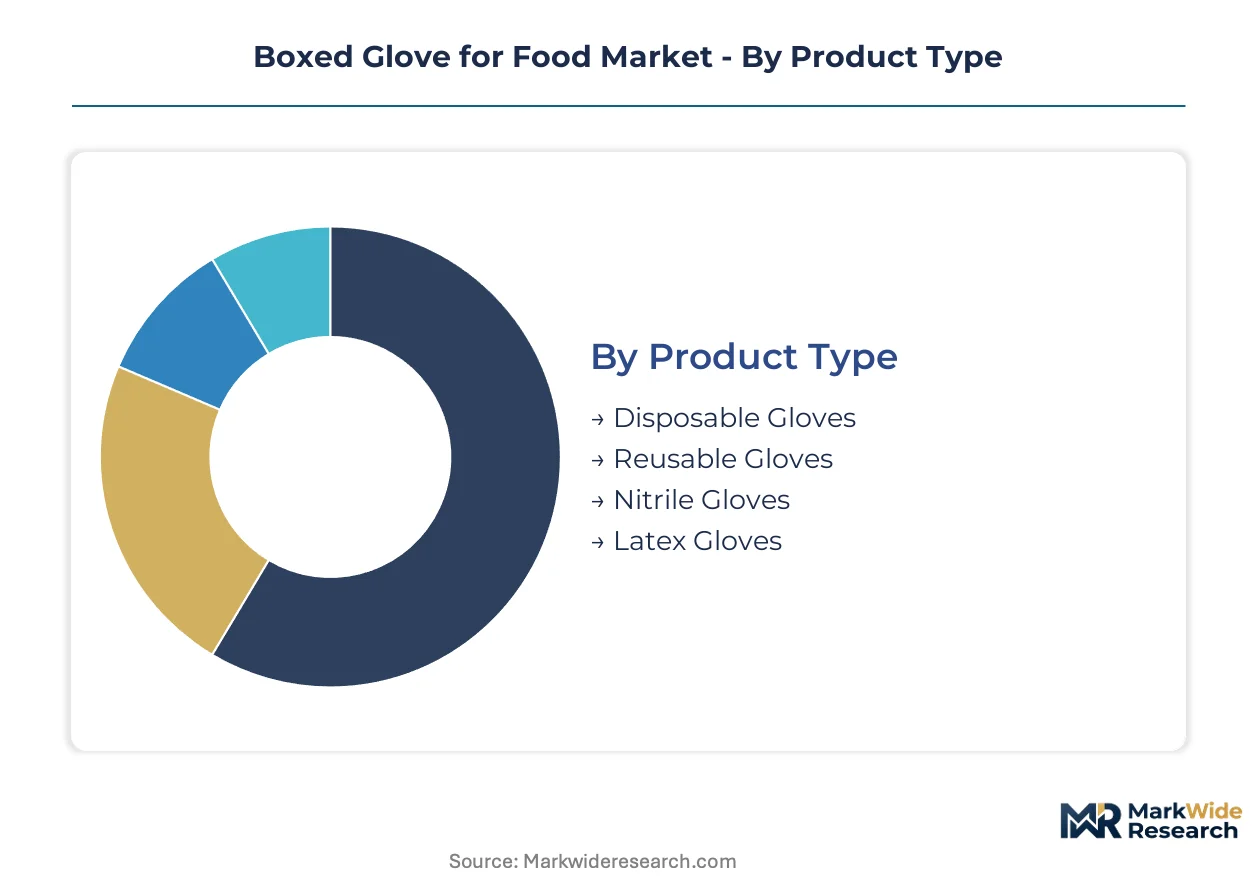
Segmentation in the boxed glove for food market determines procurement strategy, certification pathways, and margin architecture. Material chemistry and compliance tier selection directly shape unit economics and customer lock-in potential across foodservice channels.
Product Type:
Capital intensity varies sharply across product categories, with nitrile-dominant manufacturing requiring the heaviest upfront investment in polymerization and dipping-line infrastructure.
- Disposable Gloves:Single-use barrier protection manufactured through continuous dipping processes with high-volume output economics. Quick-service restaurant chains in the United States specify these exclusively across prep and service lines to satisfy FDA Food Code bare-hand contact mandates.
- Reusable Gloves:Silicone and neoprene variants engineered for extended wear cycles in high-temperature processing environments. Centralized kitchen operations and industrial food processing facilities in Germany absorb these for capital-intensive applications where heat resistance justifies laundering infrastructure.
- Nitrile Gloves:Synthetic rubber formulations delivering puncture resistance and chemical compatibility with sanitizers.
- Latex Gloves:Natural rubber derivatives facing demand erosion due to allergen prevalence in foodservice workforces.
Disposable gloves absorb the bulk of installed capacity; nitrile gloves are expanding most quickly.
Material:
Raw material selection dictates supply security, price volatility exposure, and regulatory qualification burden across manufacturing footprints.
- Nitrile:Acrylonitrile-butadiene copolymer delivering superior chemical resistance against fats and sanitizers alongside latex-allergy mitigation. Malaysian production clusters supply North American distributors facing FDA 21 CFR 177.2600 compliance requirements.
- Vinyl:Polyvinyl chloride formulations facing reformulation pressure from REACH phthalate restrictions in European markets.
- Latex:Natural rubber harvested from Hevea brasiliensis plantations concentrated in Southeast Asia.
- Polyethylene:Low-density film gloves serving cost-sensitive catering and food handling applications with minimal barrier specifications.
Nitrile commands the steepest expansion trajectory; polyethylene retains volume leadership in emerging market price tiers.
Application:
End-use concentration shapes carton sizing, distribution frequency, and customer relationship intensity across the value chain.
- Food Processing:High-volume industrial operations requiring ASTM-certified barrier performance for contamination control. USDA-inspected facilities in the United States specify medical-grade nitrile for raw protein handling segments.
- Catering:Event and institutional foodservice demanding compact storage formats and rapid changeover capability.
- Food Handling:Retail deli and bakery counter operations with moderate throughput and standardized hygiene protocols.
- Food Delivery:Cloud kitchen and last-mile packaging operations optimized for minimal storage footprint and high-throughput dispensing.
Food processing absorbs dominant manufacturing allocation; food delivery is climbing the fastest as delivery-optimized infrastructure proliferates.
Compliance Standard:
Certification tier functions as a pricing and market access gatekeeper, with multi-standard qualification extending product development cycles substantially.
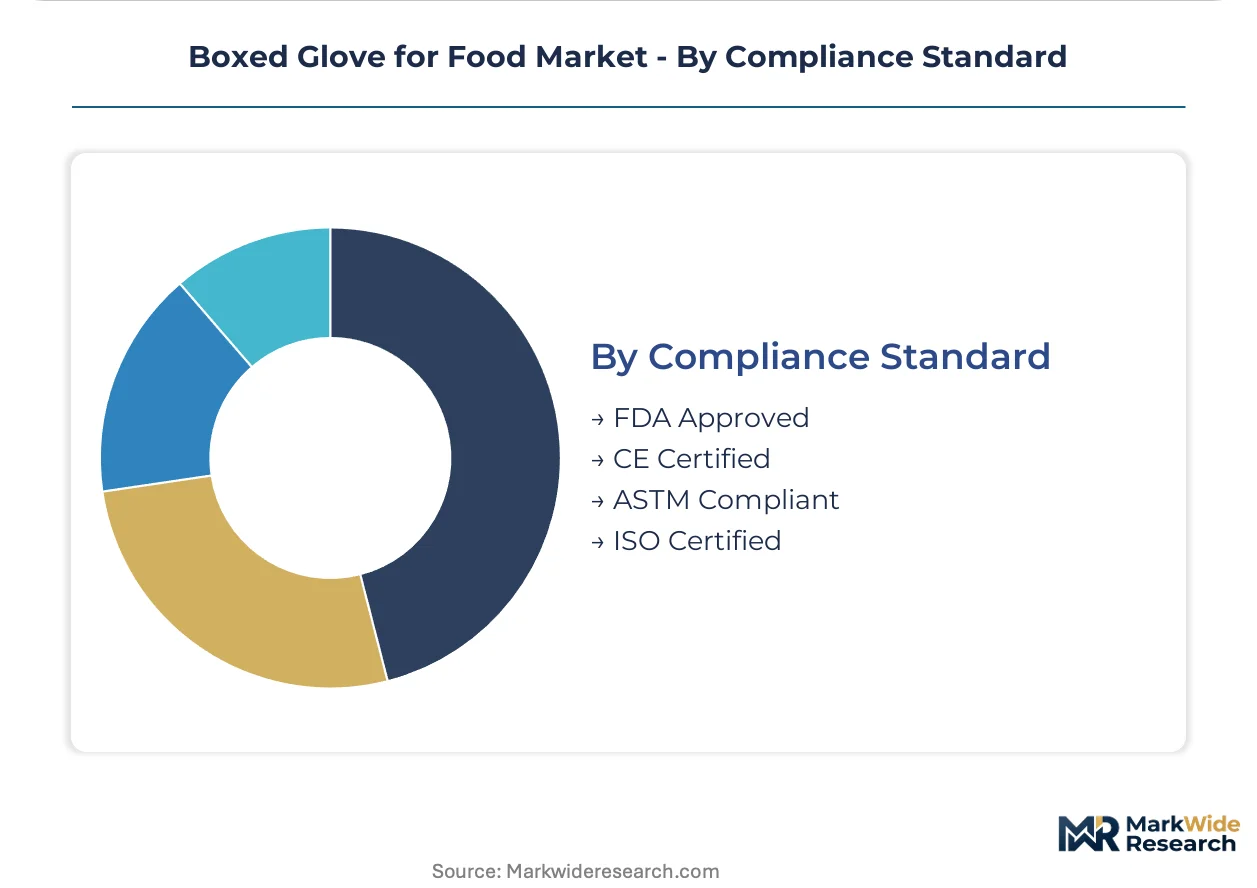
- FDA Approved:21 CFR 177.2600 rubber specifications governing food contact surfaces in United States commerce. Domestic quick-service chains mandate this designation for master supply agreements, creating qualification backlog for new market entrants.
- CE Certified:EU Framework Regulation 1935/2004 compliance enabling market access across European Economic Area member states.
- ASTM Compliant:D6319 medical-grade barrier standards increasingly specified for high-risk food processing segments.
- ISO Certified:9001 quality management systems supporting multinational vendor qualification and audit standardization.
FDA approval anchors North American procurement decisions; CE certification is gaining share fastest as European sustainability mandates tighten formulation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's Port Klang Free Zone concentrates nitrile glove manufacturing capacity, drawing petrochemical feedstock through integrated supply corridors and anchoring export flows toward North American foodservice distributors.
United States
Quick-service restaurant chains with 500-plus locations drive standardized procurement programs mandating FDA 21 CFR 177.2600 compliance. The FDA Food Code bare-hand contact restrictions tighten enforcement across state health departments. Chicago and Dallas metropolitan areas concentrate cloud kitchen infrastructure where high-throughput disposable glove consumption accelerates.
Germany
REACH phthalate restrictions force vinyl glove reformulation ahead of enforcement deadlines. The Federal Institute for Risk Assessment tightens scrutiny on food contact materials containing DINP and DEHP compounds. Frankfurt and Hamburg distribution hubs accelerate qualification of phthalate-free alternatives for catering and institutional foodservice channels.
Malaysia
Petrochemical integration near Port Klang and Klang Valley clusters sustains nitrile-dominant manufacturing scale. The Malaysian Investment Development Authority incentivizes capacity expansion through Pioneer Status tax holidays. Selangor state hosts vertically integrated dipping-line operations supplying North American distributors under long-term master agreements.
China
Shandong and Zhejiang provinces expand vinyl and polyethylene glove output for cost-sensitive emerging market tiers. SAMR strengthens food contact material oversight under GB standards harmonization with international frameworks. Qingdao port infrastructure supports carton-format exports toward Southeast Asian and Middle Eastern food processing markets.
Thailand
Natural rubber harvesting in southern provinces sustains latex glove production for price-sensitive institutional buyers. The Thailand Board of Investment promotes medical and food-grade rubber product manufacturing through zone-based incentives. Hat Yai industrial estates concentrate dipping facilities serving Japanese and Australian foodservice import specifications.
Boxed Glove for Food Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Market structure concentrates around Southeast Asian manufacturing clusters where petrochemical integration and labor arbitrage sustain margin architecture. Three archetypes dominate: vertically integrated Malaysian producers with captive nitrile supply, European-certified portfolio specialists commanding premium specification, and Chinese volume fabricators serving emerging market price tiers. Competitive moves center on capacity expansion in tax-incentivized zones and direct contracting with national restaurant chains that bypass traditional distribution tiers.
Among Malaysian-dominant producers, Hartalega Holdings Berhad, Kossan Rubber Industries Berhad, and Top Glove Corporation Berhad exemplify the vertically integrated archetype. These entities occupy positions where nitrile polymerization and continuous dipping-line capacity anchor supply security for North American distributors. Ansell Limited represents the certification-specialist tier, with ASTM and ISO-compliant portfolios commanding specification in regulated processing environments. The competitive dynamic pits scale-driven Malaysian supply against European and Australian quality-tier positioning, with Chinese fabricators capturing volume in price-sensitive segments.
| Leading Market Players |
|---|
| Top Glove Corporation Berhad |
| Hartalega Holdings Berhad |
| Kossan Rubber Industries Berhad |
| Ansell Limited |
| Sri Trang Gloves |
| Supermax Corporation Berhad |
| Semperit |
| AMMEX |
| Brightway Group |
| Others |
Pricing and Supply Chain Analysis
Captive nitrile polymerization in Malaysian manufacturing clusters anchors both supply security and pricing power for converters serving North American foodservice distributors. This backward integration into acrylonitrile-butadiene feedstocks insulates dominant producers from spot market volatility while locking in multi-year contract premiums with quick-service restaurant chains.
Pricing Analysis
Short lead-time premiums command pricing separation from standard contract tiers, with spot inventory discounts widening during periods of Malaysian port congestion. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASTM certification grade and FDA 21 CFR 177.2600 compliance status. Cost compression in economy-grade vinyl lines is intensifying because Chinese polyethylene exporters are absorbing tariff exposure to maintain volume share. Cloud kitchen operators exhibit the highest price sensitivity due to minimal storage infrastructure, while USDA-inspected protein processors accept premium positioning for medical-grade barrier specifications.
Supply Chain Analysis
Dual-sourcing requirements mandated by national restaurant chains force North American distributors to qualify secondary suppliers beyond Malaysian incumbents. Geographic supply concentrates in Malaysia, Thailand, and China, with nitrile dipping lines drawing from petrochemical feedstocks anchored in Port Klang and Klang Valley clusters. Raw material dependencies rest on acrylonitrile monomer, natural rubber latex, and polyvinyl chloride resin. Single-source vulnerability persists around Malaysian nitrile capacity exposed to labor policy shifts and energy cost fluctuations. Distribution runs through group purchasing organizations losing share to direct master agreements with vertically integrated manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained nitrile capacity in Malaysian manufacturing zones props pricing power for qualified converters, with Port Klang infrastructure bottlenecks limiting rapid supply expansion. This capacity ceiling sustains margin architecture for incumbents with validated FDA compliance pathways.
For Market Incumbents: To counter direct contracting erosion from national restaurant chains bypassing distributors, anchor market position through ASTM D6319 certification investment and captive acrylonitrile supply expansion in Selangor tax-incentive zones. Lock in multi-year master agreements with cloud kitchen infrastructure operators before secondary suppliers achieve qualification timelines. For New Entrants and Emerging Players: The premium-to-economy price-point gap in compostable nitrile formulations opens white-space targeting in California and Germany ahead of state-level organic waste mandate enforcement. Penetrate facility-level sustainability officer procurement authority with phthalate-free alternatives for European catering channels. Pursue pilot qualification programs with mid-sized regional distributors lacking Malaysian direct relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking food contact material diversification. Five-to-ten year viability favors converters with dual FDA-CE qualification infrastructure and established dipping-line capacity. Target acquisition archetype: mid-sized Malaysian producers with Pioneer Status tax holidays and uncontracted nitrile polymerization capacity. Monitor FDA Food Code adoption velocity across state health departments as inflection indicator for demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Polymer Development | Plant-based plasticizer formulations satisfy California and German organic waste mandates ahead of enforcement deadlines. |
| ASTM D6319 Certification Investment | Medical-grade barrier standards unlock premium positioning in USDA-inspected raw protein handling segments. |
| Direct Master Agreement Expansion | Bypassing GPO distribution tiers captures volume from quick-service chains with 500-plus location standardization programs. |
| Phthalate-Free Vinyl Reformulation | REACH-compliant alternatives secure European catering channel access before DINP and DEHP enforcement deadlines. |
| Cloud Kitchen Dispensing System Integration | Custom carton dimensions compatible with automated hygiene infrastructure lock in high-throughput delivery-optimized facilities. |
Research Methodology
Trade databases, FDA 21 CFR compliance registries, and Malaysian Investment Development Authority capacity filings formed the secondary backbone of this analysis. Primary interviews with foodservice procurement directors, glove converter plant managers, distribution channel partners, and regulatory affairs specialists at quick-service restaurant chains combined with this secondary validation. Bottom-up and top-down triangulation cross-referenced shipment volumes from Port Klang export data against distributor inventory turns in Chicago and Dallas metropolitan areas.
Bottom-up modeling segmented volume and value across material chemistry, compliance tier, and end-use application throughout the forecast period. The analytical framework incorporated nitrile substitution rates from vinyl and latex alternatives, franchise standardization program adoption curves, and cloud kitchen infrastructure buildout trajectories. CAGRs were derived from weighted average growth across these segmentation dimensions, with acrylonitrile price elasticity and Malaysian ringgit exchange rate volatility as industry-specific forecast inputs.
Underlying measurement precision varies by segment; disposable nitrile volumes carry tighter precision than emerging compostable alternatives due to established trade data availability. Forecasts reflect assumptions around FDA Food Code enforcement consistency and REACH phthalate restriction implementation timelines. A model refresh is warranted upon material change in Malaysian labor policy or acrylonitrile feedstock supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Work Shoes Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Europe Lanyards Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Helmet Lining Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Global Mobile Phone Protective Cases Market
Protective Gear
Helmets Market
Protective Gear
Military Boots Market
Protective Gear
Pet Control Devices Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Diving Suits Market
Protective Gear
Equestrian Helmets Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Bungee Cords and Accessories Market