
 Diphenyl Sulfone Market | 2026-2036
Diphenyl Sulfone Market Size, Share, and Industry Trends Forecast 2026-2036
Diphenyl Sulfone Market Outlook
Specialized organic synthesis expertise is unwinding capacity bottlenecks as European and North American chemical engineering labor pools shrink. Huaian Shuangying Chemical leverages backward integration into benzene feedstock to protect margin structures. Sino-High (China) anchors volume supply through dedicated sulfonation lines serving polymer producers. Nantong Volant-chem corp. differentiates via pharmaceutical-grade certification that unlocks regulated end-uses.
Diphenyl sulfone is an aromatic sulfone compound with the formula (C6H5)2SO2, typically manufactured through Friedel-Crafts sulfonylation or oxidation of diphenyl sulfide, valued for thermal stability above 240°C and chemical inertness. It serves primarily as a high-performance polymer modifier, solvent, and intermediate in specialty chemical synthesis. Industrial grade material dominates volume throughput due to commodity pricing in polymer production, while pharmaceutical grade commands premium positioning through GMP-aligned purification protocols. Adhesives applications are gaining share as electronics miniaturization drives demand for thermally stable bonding agents. Dye synthesis represents a mature demand pocket with slower expansion trajectories.
REACH registration requirements in Europe and China's MEE emission standards are elevating compliance costs for sulfonation-based production. The EPA in the United States monitors benzene derivative handling under TSCA, shaping facility siting decisions. BIS certification pathways in India are emerging as a gate for import-qualified supply. Stakeholders must track regulatory divergence between jurisdictions to optimize manufacturing location and grade portfolio decisions.
Market Dynamics
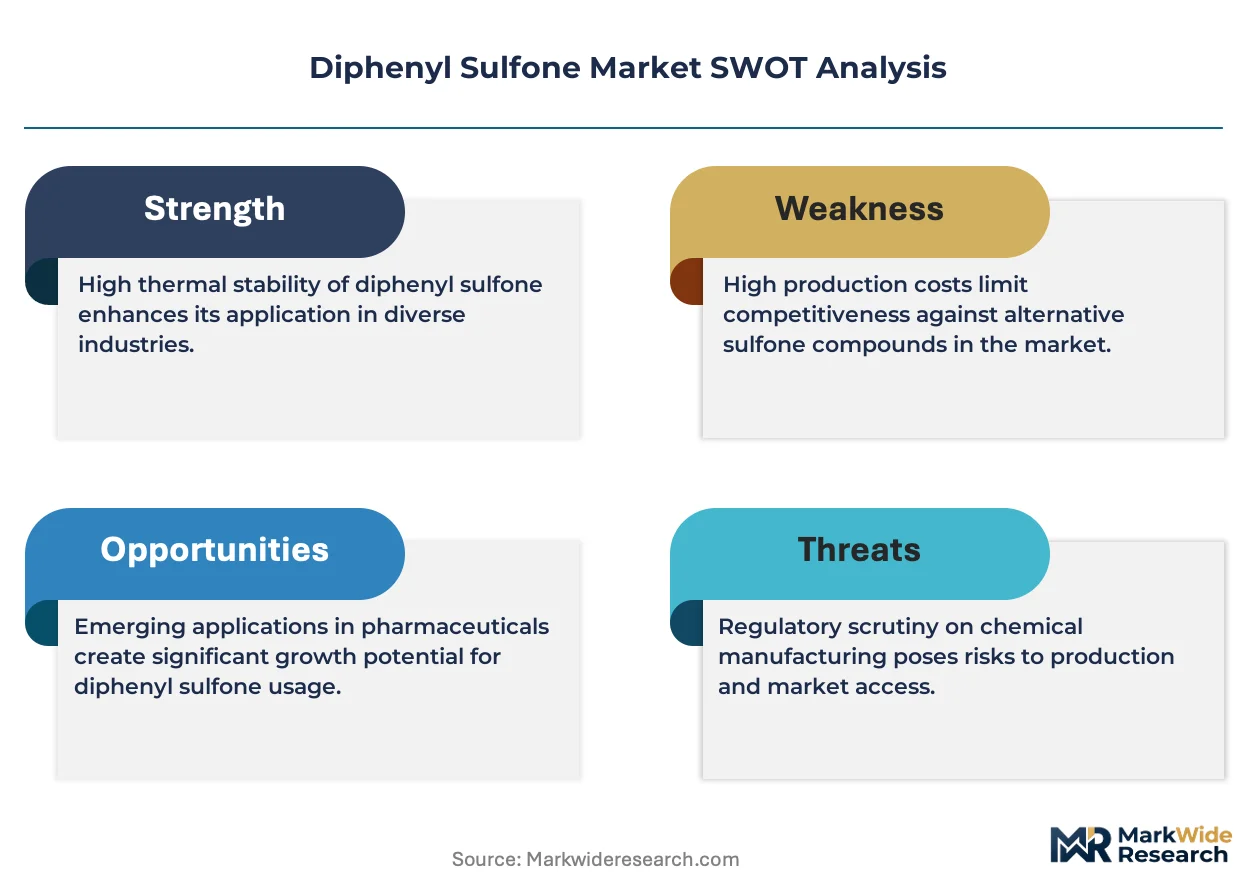
REACH registration requirements and China's MEE emission standards are forcing sulfonation-based producers to reconfigure process chemistry, tightening feedstock access for non-integrated operators while advantaging benzene-backward-integrated suppliers in East China's chemical corridor.
Growth Catalysts
- Polymer-grade demand acceleration:Specialty polymer manufacturers in Germany and Japan are expanding procurement of pharmaceutical-grade material for high-temperature engineering resins. This pull is concentrating volume through certified supply channels.
- Electronics miniaturization:Adhesives applications are gaining share as thermally stable bonding agents displace conventional epoxies in semiconductor packaging and display assembly.
- Dual carbon policy enforcement:China's dual carbon goals are tightening process emission standards, accelerating closure of non-compliant sulfonation capacity and consolidating effective supply under integrated producers.
Market Restraints
- Benzene feedstock volatility:Crude-linked aromatic pricing transmits directly to diphenyl sulfone production economics, compressing margins for non-captive producers during upstream cost spikes.
- East China supply concentration:Demand is concentrating in East China's chemical manufacturing corridor, creating geographic vulnerability to regional logistics disruptions or environmental enforcement waves.
- Sulfonation process limitation:Conventional Friedel-Crafts sulfonylation generates sulfur dioxide byproducts that require costly abatement, constraining capacity expansion in jurisdictions with stringent MEE or EPA monitoring.
Strategic Opportunities
- Pharmaceutical-grade certification expansion:GMP-aligned purification protocols unlock regulated end-uses in active pharmaceutical ingredient synthesis, commanding premium positioning over industrial-grade material.
- India import qualification pathway:BIS certification requirements are emerging as a gate for import-qualified supply, creating first-mover advantage for producers achieving compliance ahead of domestic capacity maturation.
- Continuous flow sulfonation:Microreactor technology convergence with process analytical chemistry enables real-time quality control, reducing batch-to-batch variation for electronics-grade specifications.
Industry Challenges
- Specialized organic synthesis expertise scarcity:European and North American chemical engineering labor pools are shrinking, unwinding capacity bottlenecks as retirement waves outpace graduate pipeline replenishment.
- Pharmaceutical-grade compliance timeline:GMP certification requires 18-24 month validation cycles, delaying revenue recognition for capacity investments targeting regulated end-uses.
- Multi-jurisdiction regulatory divergence:Stakeholders must track divergence between REACH, TSCA, and MEE frameworks to optimize manufacturing location and grade portfolio decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diphenyl Sulfone Market |
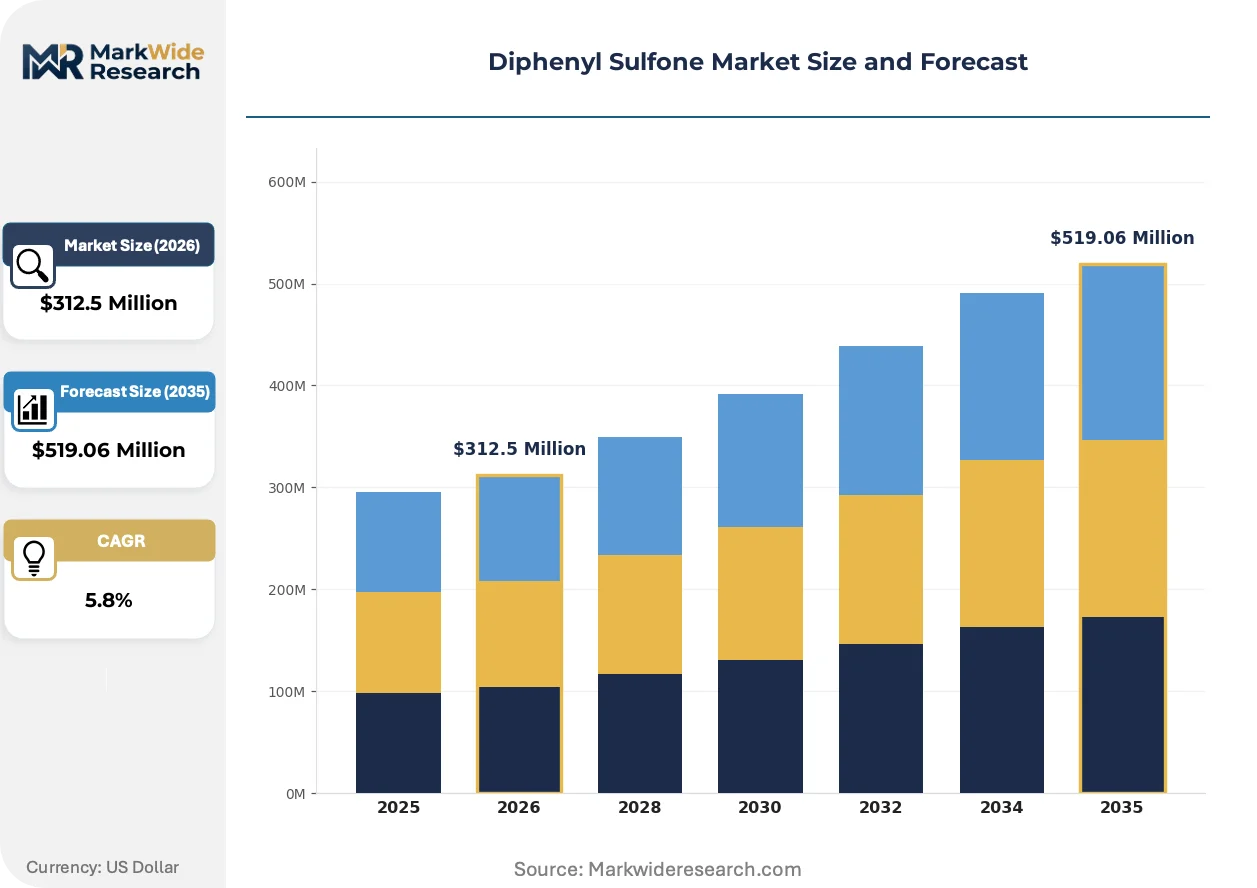
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Chemical Intermediate Application: Polymer Production, Dye Synthesis, Chemical Reagent, Adhesives End User: Plastic Manufacturers, Pharmaceutical Companies, Textile Industry, Paints & Coatings Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Huaian Shuangying Chemical, Sino-High (China), Nantong Volant-chem corp., Suzhou Yinsheng Chemical, Jiangsu Kangxiang Industrial Group, Unibest Industrial, Sinolite Industrial Co., Xiangshui Modern Chemical, HANGZHOU TOPMATE CHEMICAL CO., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diphenyl Sulfone Market Strategic Shifts
Process intensification and regulatory tightening are reshaping competitive positioning in diphenyl sulfone production, with technology adoption separating integrated operators from commodity-dependent competitors.
Continuous flow microreactor sulfonation is decomposing conventional batch production economics. Electronics-grade polymer manufacturers in Japan and South Korea are adopting this technology at pilot scale. The shift is decomposing minimum efficient scale thresholds, enabling smaller-footprint facilities to achieve pharmaceutical-grade purity without legacy capital intensity.
REACH authorization requirements for benzene derivatives are elevating compliance documentation burdens. ECHA registration dossiers now demand extended toxicological datasets for sulfone intermediates. European polymer compounders are responding by consolidating supplier bases onto REACH-registered producers with full substance volume tracking.
Certification-driven specification tightening is compressing switching cycles among polymer producers. Long-term supply agreements with embedded quality audits are displacing spot procurement in high-performance resin applications. This pattern is most visible in German automotive supply chains, where OEM material qualification requirements propagate upstream to diphenyl sulfone feedstock selection.
Diphenyl Sulfone Market Segmentation
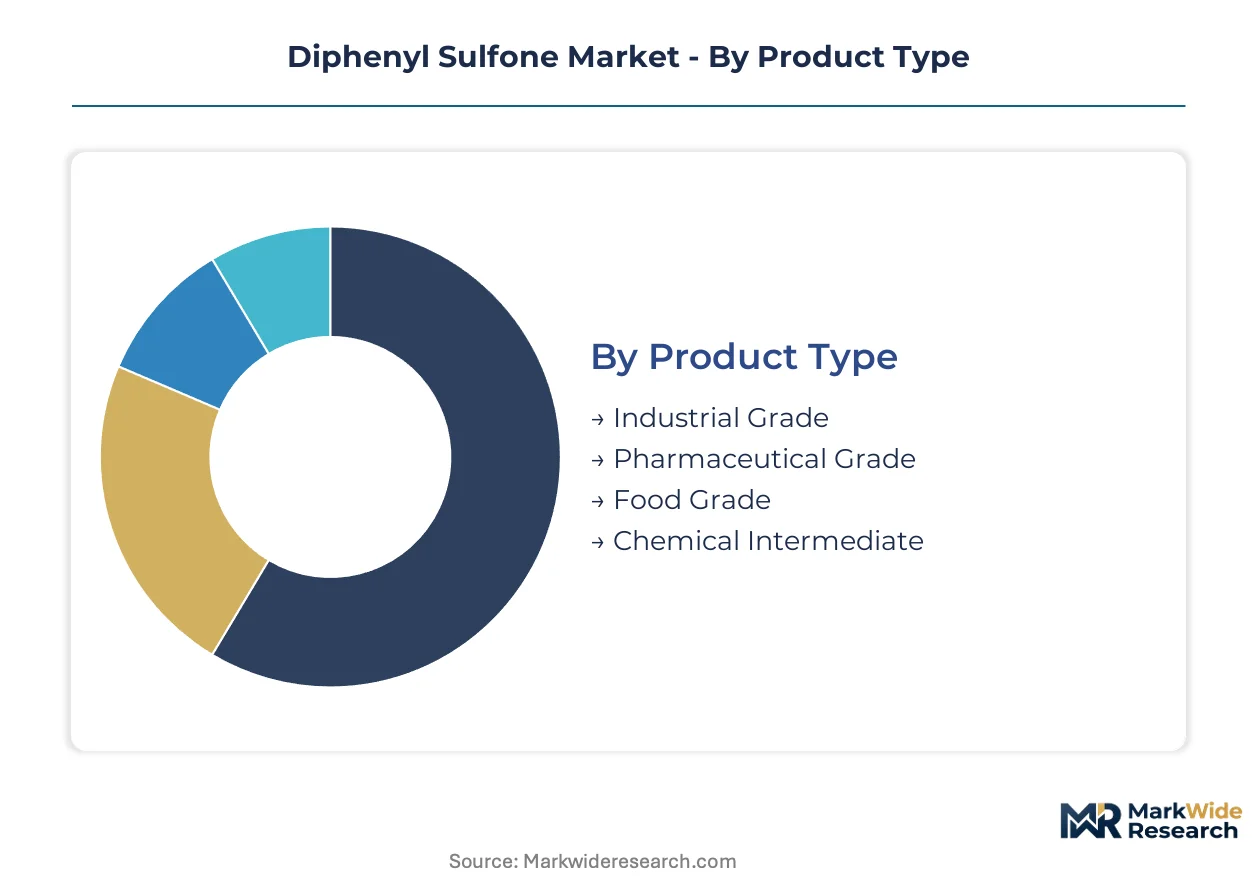
Diphenyl sulfone demand fragments across purity tiers and end-use specifications that carry divergent regulatory burdens. Certification requirements from ECHA, FDA, and BIS create non-substitutable supply channels that reshape competitive boundaries between segments.
Product Type:
REACH registration dossiers and GMP validation protocols impose tiered compliance costs that stratify producer capabilities across purity grades.
- Industrial Grade:Material meeting basic thermal stability thresholds above 240°C serves polymer compounding and solvent applications without purification overhead. East China's chemical corridor concentrates volume supply for this specification, with benzene-backward-integrated producers capturing margin protection during feedstock volatility.
- Pharmaceutical Grade:GMP-aligned purification protocols eliminate sulfonation byproducts below pharmacopeial thresholds for active pharmaceutical ingredient synthesis. German and Japanese specialty polymer manufacturers are expanding procurement through certified channels that command premium positioning over commodity material.
- Food Grade:Compliance with national food contact regulations limits viable supplier pools to facilities with dedicated production lines and migration testing capabilities.
- Chemical Intermediate:Purity specifications vary by downstream reaction requirements, with custom synthesis houses negotiating batch-specific certificates of analysis.
Industrial grade handles the majority of throughput; pharmaceutical grade is expanding most quickly on share.
Application:
End-use thermal performance requirements and electronics industry miniaturization trends are reallocating volume across functional applications.
- Polymer Production:High-temperature engineering resins in automotive and aerospace supply chains demand sulfone modifiers with consistent melt flow indices. German OEM material qualification requirements propagate upstream to feedstock selection, consolidating supplier bases onto REACH-registered producers.
- Adhesives:Thermally stable bonding agents displace conventional epoxies in semiconductor packaging and display assembly as device geometries shrink. South Korean and Japanese electronics manufacturers are qualifying sulfone-based formulations at pilot scale.
- Dye Synthesis:Mature demand pocket with slower expansion trajectories as textile processing shifts toward waterless coloration technologies.
- Chemical Reagent:Laboratory and pilot-scale consumption follows academic and corporate R&D spending cycles with limited price elasticity.
Polymer production commands the largest volume position; adhesives applications are climbing the fastest.
End User:
Customer technical capabilities and qualification timelines segment procurement patterns across manufacturing sophistication tiers.
- Plastic Manufacturers:Compounders with in-house polymerization expertise specify sulfone content for heat deflection temperature targets in automotive underhood components. Long-term supply agreements with embedded quality audits are displacing spot procurement in this channel.
- Pharmaceutical Companies:API synthesis operations require 18-24 month GMP certification cycles that delay revenue recognition for qualifying suppliers. India's CDSCO and BIS pathways are emerging as gates for import-qualified supply.
- Textile Industry:Dye intermediates consumption tracks regional apparel manufacturing shifts with limited specification differentiation.
- Paints & Coatings:High-performance industrial coatings specify sulfone additives for chemical resistance in marine and infrastructure applications.
Plastic manufacturers absorb the dominant share of industrial-grade volume; pharmaceutical companies drive the steepest specification escalation.
Distribution Channel:
Shipment scale and customer technical support requirements determine channel economics across geographic markets.
- Direct Sales:Large polymer producers and pharmaceutical manufacturers negotiate frame contracts with volume commitments and audit rights. This channel concentrates in Germany, Japan, and the United States where qualification documentation burdens favor established supplier relationships.
- Distributors:Regional chemical distributors stock industrial-grade material for mid-tier compounders and smaller synthesis operations. Inventory positioning in Rotterdam, Singapore, and Shanghai hubs reduces lead times for non-contracted demand.
- Wholesale:Bulk material aggregation serves commodity applications with limited specification variance and price-sensitive procurement.
- Online Retail:Laboratory-scale packaging for research quantities bypasses traditional distributor markups through specialized chemical e-commerce platforms.
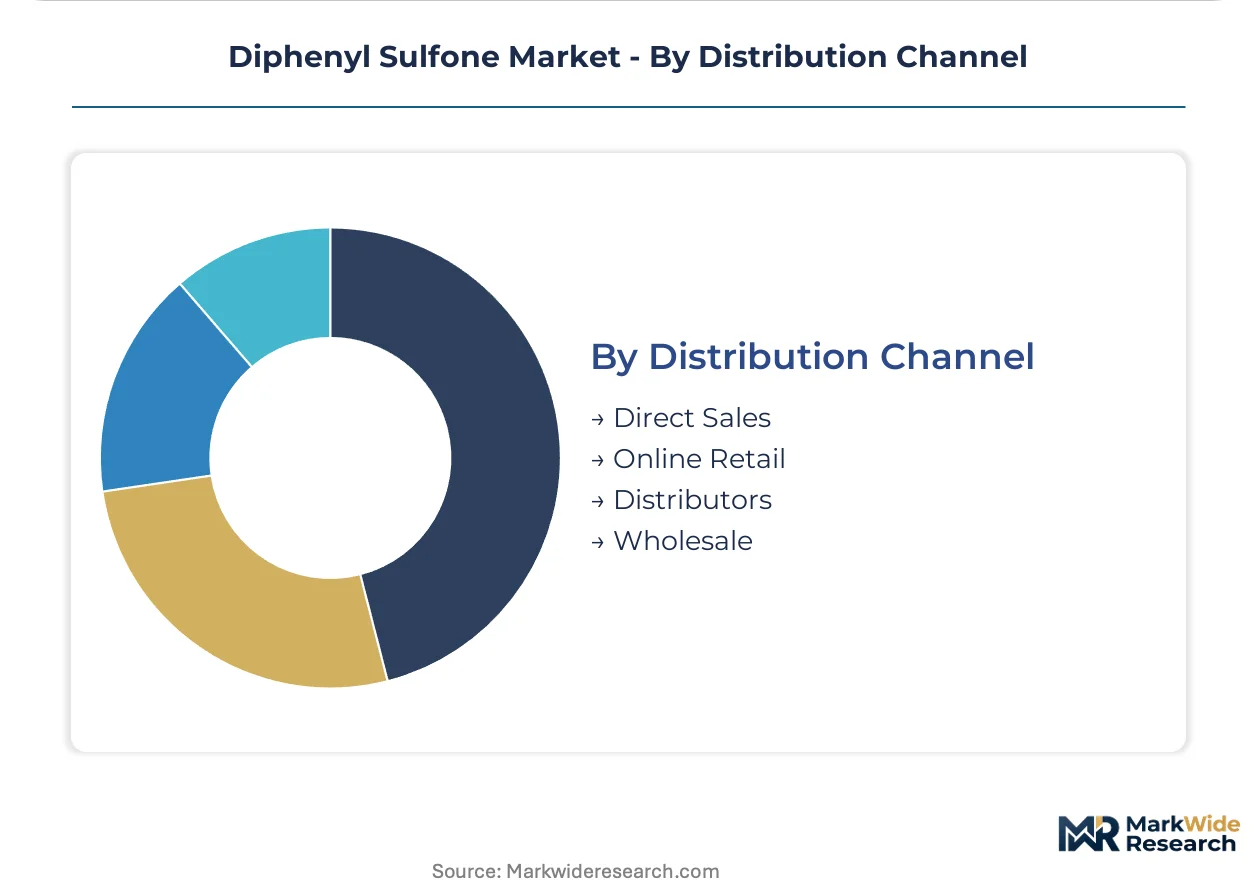
Direct sales channels handle the majority of pharmaceutical-grade volume; distributor networks are gaining share fastest in industrial-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes diphenyl sulfone predominantly for industrial-grade polymer modification, while Germany and Japan concentrate procurement on pharmaceutical-grade material for regulated end-uses, creating a bifurcated demand geography.
China
East China's chemical manufacturing corridor anchors volume throughput, with specialty polymer producers and electronics adhesive formulators driving procurement. MEE emission standards under the dual carbon policy framework are shuttering non-compliant sulfonation capacity. Jiangsu and Zhejiang provinces concentrate effective supply under benzene-backward-integrated operators.
Germany
Automotive OEM material qualification requirements propagate upstream to sulfone feedstock selection, consolidating supplier bases onto REACH-registered producers. ECHA authorization dossiers for benzene derivatives elevate compliance documentation burdens. The Ruhr industrial region and Bavarian chemical clusters host polymer compounders specifying consistent melt flow indices.
Japan
Electronics-grade polymer manufacturers and semiconductor packaging adhesive formulators are qualifying sulfone-based materials at pilot scale. METI chemical handling protocols shape facility siting and process chemistry decisions. The Kanto and Kansai industrial corridors concentrate demand from display assembly and high-temperature resin applications.
United States
Specialty chemical synthesis houses and laboratory-scale consumers follow R&D spending cycles with limited price elasticity. EPA benzene derivative monitoring under TSCA shapes import and handling protocols. The Gulf Coast petrochemical corridor and Midwest manufacturing belt represent primary consumption nodes.
India
Active pharmaceutical ingredient synthesis operations and emerging polymer compounding capacity are creating import-qualified demand channels. BIS certification pathways and CDSCO registration requirements function as gates for supply qualification. Maharashtra and Gujarat industrial zones concentrate early procurement from multinational pharmaceutical manufacturers.
Diphenyl Sulfone Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with benzene feedstock control separating margin-protected operators from commodity-exposed competitors. The vendor base clusters around three archetypes: backward-integrated aromatic producers, dedicated sulfonation specialists with certification depth, and regional distributors serving spot industrial demand. Capacity expansion and pharmaceutical-grade certification represent the dominant competitive moves, as qualification timelines create defensive moats.
Among Chinese sulfonation specialists, Huaian Shuangying Chemical, Sino-High (China), and Nantong Volant-chem corp. occupy positions spanning the integration spectrum. Huaian Shuangying Chemical exemplifies feedstock-anchored competitive positioning through upstream benzene control. Sino-High (China) represents volume-focused supply architecture through dedicated production lines. Nantong Volant-chem corp. sits within the certification-differentiated tier, with pharmaceutical-grade alignment unlocking regulated end-use access.
| Leading Market Players |
|---|
| Huaian Shuangying Chemical |
| Sino-High (China) |
| Nantong Volant-chem corp. |
| Suzhou Yinsheng Chemical |
| Jiangsu Kangxiang Industrial Group |
| Unibest Industrial |
| Sinolite Industrial Co. |
| Xiangshui Modern Chemical |
| HANGZHOU TOPMATE CHEMICAL CO. |
| Others |
Value Chain & Pricing Dynamics
Thermally stable epoxy displacement by sulfone-based adhesives in semiconductor packaging is redrawing procurement geography toward East China's chemical corridor while compressing margin structures for non-integrated European compounders. This substitution dynamic concentrates volume pricing power among benzene-backward-integrated producers who capture feedstock volatility protection unavailable to toll manufacturers.
Pricing Analysis
Long-term offtake contracts with embedded quality audits dominate pharmaceutical-grade procurement from German and Japanese polymer manufacturers, while industrial-grade material trades through spot channels vulnerable to benzene cost spikes. Price differentiation separates GMP-certified supply from commodity industrial grades, with REACH registration burdens amplifying premiums for documented substance tracking. Cost compression in industrial tiers intensifies as MEE enforcement shutters non-compliant sulfonation capacity. Polymer compounders with in-house formulation expertise exhibit lowest price sensitivity; spot-buying textile dye houses face acute margin pressure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for REACH-registered material sourced from Jiangsu and Zhejiang provinces. Production gravity centers on China, Germany, and Japan, with feedstock access drawing from benzene, sulfur trioxide, and aluminum chloride inputs. Single-source vulnerability concentrates in East China's chemical corridor where environmental enforcement waves trigger abrupt supply interruptions. Distribution runs through direct sales channels for certified pharmaceutical grades and regional distributor networks for commodity industrial material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against sulfone displacement risk from bio-based epoxy alternatives and cyclic olefin thermoplastics as electronics miniaturization accelerates specification churn.
For Market Incumbents: Secure captive benzene supply through backward integration or long-term feedstock offtake to insulate margin structures from aromatic volatility. Anchor customer relationships via embedded quality audits and REACH dossier support that raises switching costs for German automotive compounders. For New Entrants and Emerging Players: Pharmaceutical-grade certification gaps in India's CDSCO pathway offer white-space entry ahead of domestic capacity maturation. Target BIS-compliant import qualification as the most penetrable regulatory channel, deploying technical service bundling to differentiate from commodity traders. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors benzene-integrated specialists with certification depth over pure-play sulfonation operators. Acquisition screening should prioritize Jiangsu-based producers with MEE-compliant assets and active GMP validation pipelines. Monitor CDSCO registration acceleration as the inflection signal for India demand maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive benzene supply protects margin structures during feedstock volatility spikes. |
| GMP Certification Investment | Pharmaceutical-grade validation unlocks regulated API synthesis end-uses. |
| Long-term Supply Agreement | Embedded audit rights cement relationships with German automotive OEM supply chains. |
| Continuous Flow Technology Adoption | Microreactor sulfonation reduces batch variation for electronics-grade specifications. |
| Joint Venture | Local partnerships navigate BIS certification complexity in Maharashtra and Gujarat zones. |
Study Parameters
Initial hypotheses were tested against primary input from plant managers at sulfonation facilities, procurement leads at German polymer compounders, distribution channel partners in Rotterdam and Singapore hubs, and technical R&D directors at Japanese electronics adhesive formulators, then refined against customs trade data, ECHA registration dossiers, SEC 10-K chemical sector filings, and MEE enforcement bulletins. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates.
Variance decomposition across grade tier, end-use industry, and regional production hub segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from installed capacity expansion schedules, qualification timeline assumptions, and substitution elasticity estimates for epoxy displacement in semiconductor packaging applications.
Underlying assumptions cover sustained REACH enforcement, MEE compliance continuity, and benzene feedstock availability, with deviation risk concentrated in environmental regulatory acceleration or aromatic supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzhydrol Market
Chemicals
Trimethylamine Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Carcinogenic Chemical Alternatives Market
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
Flatting Agents Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Iso Nonanol Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Potassium Permanganate Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Global P-Phenylenediamine Market