
 Superphosphoric Acid (SPA) Market | 2026-2036
Superphosphoric Acid (SPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Superphosphoric Acid (SPA) Market Insights
Polyphosphoric acid formulations is restructuring the economics of concentrated phosphate products by displacing lower-P2O5 alternatives in premium fertilizer blends. Nutrien Ltd. leverages its integrated potash-phosphate network to control upstream sulfur and phosphate rock access. The Mosaic Company anchors North American production through Florida-based mining and acid manufacturing complexes. Yara International ASA competes on ammonia integration, pairing its nitrogen expertise with downstream phosphoric acid upgrading.
Superphosphoric acid is a polyphosphoric acid solution containing 70-76% P2O5, produced by dehydrating orthophosphoric acid under controlled thermal conditions to form short-chain polyphosphates that sequester micronutrients and improve fertilizer compatibility. Its primary industrial purpose centers on manufacturing high-analysis liquid fertilizers and phosphate-based specialty chemicals where nutrient concentration and chelation properties outweigh standard acid economics. Liquid formulations dominate volume throughput due to their compatibility with bulk blending infrastructure and foliar application systems, while granular grades command margin premiums in controlled-release and specialty crop segments. The agriculture application channel leads absolute consumption, though horticulture is displacing commodity field crops as the fastest-growing demand pocket for acid-grade purity.
EPA fertilizer labeling requirements under FIFRA, REACH polyphosphate registration protocols in Europe, and Brazil's MAPA fertilizer quality standards collectively determine product specifications and market access thresholds for cross-border acid trade. These frameworks elevate compliance costs for non-integrated traders while rewarding producers with captive technical-grade certification capacity. Stakeholders must monitor evolving heavy-metal thresholds and carbon-border adjustment mechanisms as these reshape cost structures faster than feedstock economics alone.
Market Dynamics
Dehydration technology advancement is compressing production economics for superphosphoric acid, enabling shorter polyphosphate chains that improve micronutrient chelation without sacrificing nutrient density targets.
Growth Catalysts
- Brazil MAPA fertilizer quality standards:Stringent purity benchmarks for acid-grade inputs are filtering out marginal producers and concentrating demand among certified suppliers serving the Cerrado soybean corridor.
- Liquid-grade formulation compatibility:Specialty fertilizer blenders are migrating toward higher P2O5 density solutions that integrate seamlessly with existing bulk blending infrastructure and foliar application systems.
- EU F-Gas Regulation tightening:REACH compliance frameworks are elevating technical-grade certification requirements, rewarding producers with captive laboratory and registration capabilities.
Market Restraints
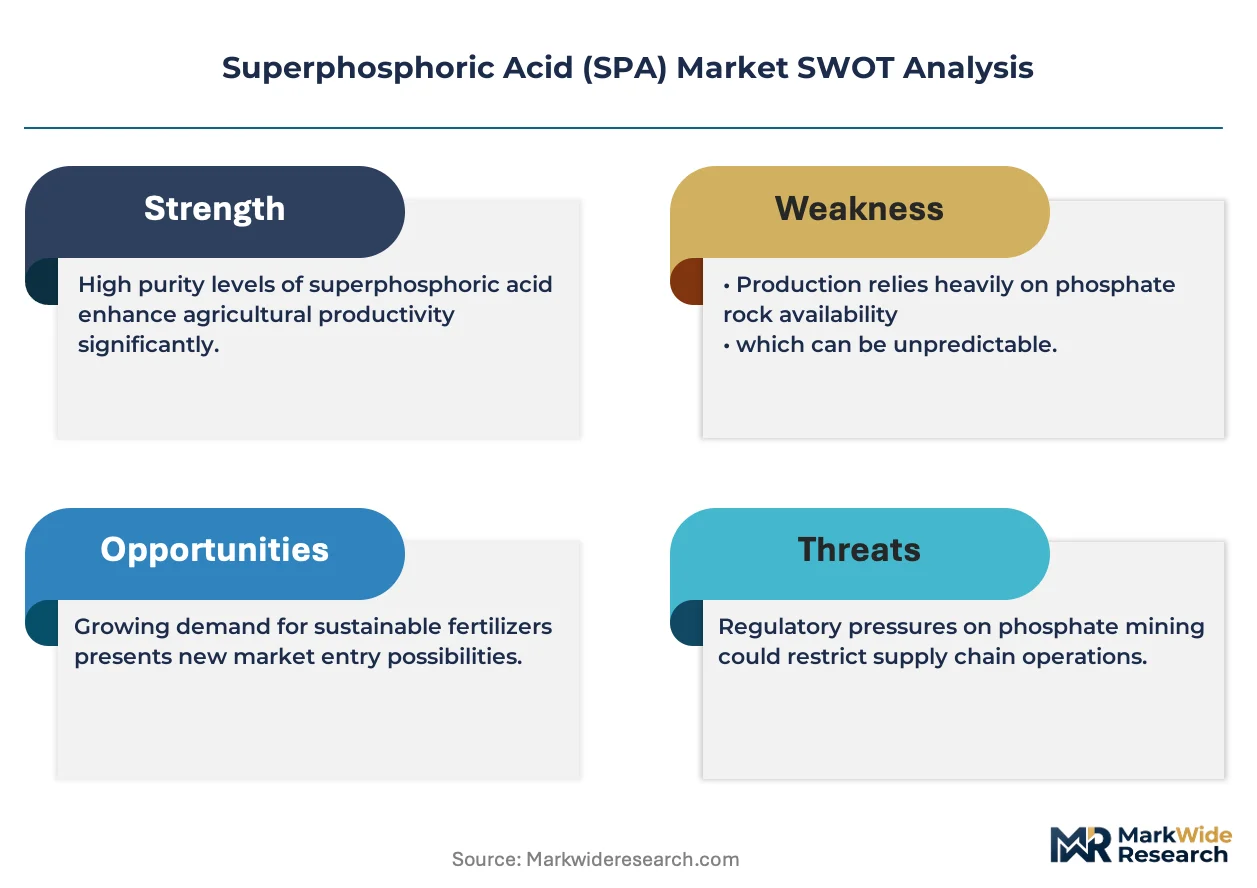
- Sulfur feedstock volatility:Sulfuric acid price swings directly transmit to superphosphoric acid production economics, compressing margins for non-integrated processors lacking captive sulfur recovery.
- Florida phosphate rock concentration:North American acid manufacturing remains tethered to a narrow geographic band of mining operations, creating hurricane and logistics exposure.
- Orthophosphoric acid substitution:Lower-cost standard acid alternatives continue to capture price-sensitive commodity fertilizer volumes, limiting SPA penetration in bulk field crop applications.
Strategic Opportunities
- Horticulture channel expansion:Specialty crop producers in California and Spain are demanding acid-grade purity levels that command margin premiums unavailable in commodity agriculture.
- Carbon-border adjustment mechanisms:Emerging EU carbon accounting rules for imported fertilizers are creating first-mover advantages for producers with verified low-carbon production pathways.
- Controlled-release fertilizer convergence:Polyphosphate short-chain chemistry is merging with polymer coating technologies to enable synchronized nutrient release for high-value permanent crops.
Industry Challenges
- REACH polyphosphate registration timelines:Extended ECHA evaluation periods for novel acid formulations are delaying market entry by 18-36 months and freezing R&D pipelines.
- Legacy blending equipment incompatibility:Retrofitting bulk fertilizer terminals to handle corrosive high-concentration liquids requires capital outlays that fragment adoption across distributor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superphosphoric Acid (SPA) Market |
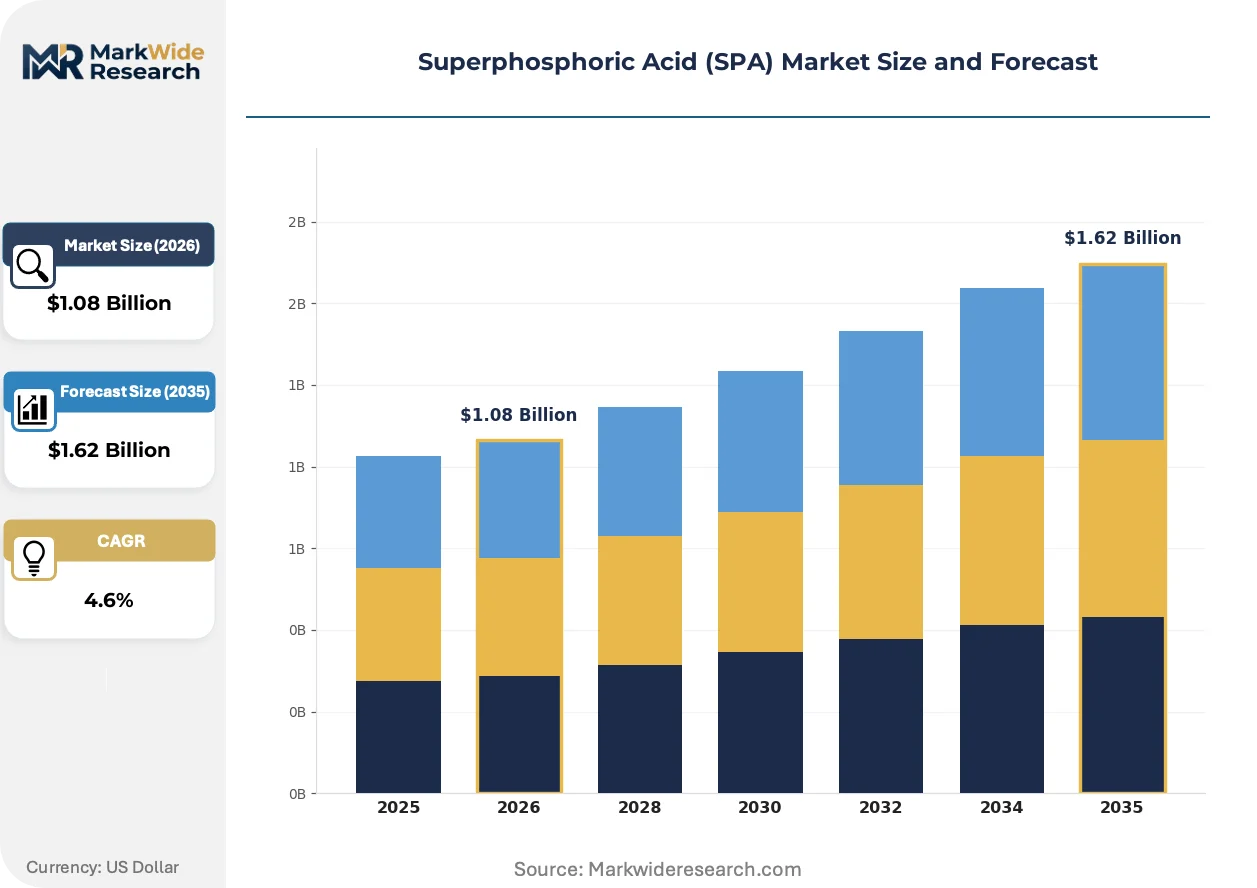
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.62 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powdered, Fertilizer Application: Agriculture, Horticulture, Landscaping, Soil Improvement End Use Industry: Chemicals, Fertilizers, Food & Beverage, Pharmaceuticals Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Nutrien Ltd., The Mosaic Company, Yara International ASA, OCP Group, ICL Group Ltd., PJSC PhosAgro, EuroChem Group AG, J.R. Simplot Company, Novaphos Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superphosphoric Acid (SPA) Market Trends and Innovations
Process intensification and regulatory precision are jointly elevating technical barriers to superphosphoric acid production, separating integrated manufacturers from merchant traders.
Membrane filtration systems for acid purification are automating impurity removal at dehydration facilities, allowing continuous rather than batch processing. Brazilian specialty blenders are adopting these systems fastest to meet MAPA heavy-metal thresholds. The technology is automating quality control steps that previously required manual sampling and laboratory verification, compressing certification cycles from weeks to days.
REACH polyphosphate registration protocols in Europe are mandating granular toxicological and environmental fate data for acid-grade inputs. ECHA's expanded substance evaluation workload is extending authorization timelines and freezing formulation innovation. Horticulture-focused producers with existing technical-grade dossiers are capturing share from commodity suppliers lacking registration bandwidth.
Direct procurement relationships between large-scale soybean operators and acid manufacturers are displacing traditional distributor intermediaries in Brazil's Mato Grosso and Goiás states. These arrangements specify P2O5 concentration, polyphosphate chain length, and micronutrient compatibility in annual contracts. The shift is most visible among 10,000+ hectare operations seeking supply security for intensive double-cropping rotations.
Superphosphoric Acid (SPA) Market Segmentation
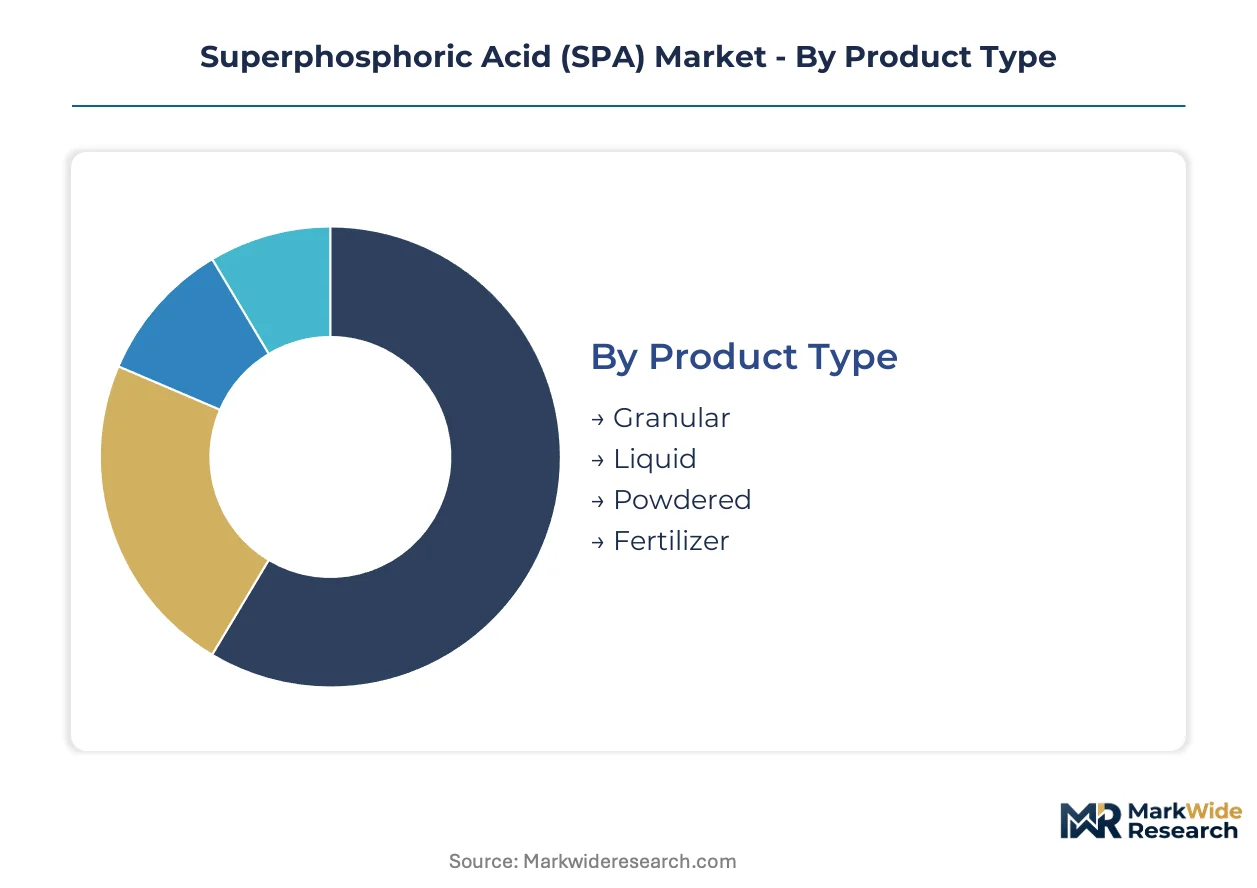
Superphosphoric acid segmentation reveals how certification burdens, application chemistry, and supply chain configuration fragment commercial opportunity across distinct product grades and customer channels. Each segment carries divergent regulatory loads and margin structures that reshape competitive positioning.
Product Type:
REACH polyphosphate registration protocols and Brazil MAPA fertilizer quality standards impose tiered certification requirements across physical forms, with liquid grades facing streamlined handling approvals while granular variants trigger extended ECHA toxicological evaluations.
- Liquid:Dominant volume format containing 70-76% P2O5 in solution, compatible with bulk blending infrastructure and foliar application systems. Demand concentrates among Brazilian specialty fertilizer blenders serving the Cerrado soybean corridor, where MAPA heavy-metal thresholds favor certified continuous-processing facilities. The grade captures margin premiums through micronutrient chelation properties that orthophosphoric acid cannot replicate.
- Granular:Solid-phase polyphosphate with controlled-release characteristics for permanent crops. Horticulture producers in California and Spain drive specification intensity, requiring acid-grade purity levels that command price premiums unavailable in commodity agriculture. Extended ECHA authorization timelines for novel granular formulations freeze R&D pipelines and reward incumbents with existing technical-grade dossiers.
- Powdered:Fine-particle polyphosphate for specialty chemical synthesis and precision blending applications. Food & Beverage and Pharmaceutical end-use industries impose the most stringent heavy-metal thresholds.
- Fertilizer:Commodity-grade blended formulations where SPA serves as a P2O5 density booster. Price-sensitive field crop applications limit penetration against standard acid alternatives.
Growing fastest: Liquid. Leading the category by volume: Liquid.
Application:
End-use chemistry dictates formulation specifications, with soil-implanted applications requiring longer polyphosphate chain stability than foliar or surface treatments.
- Agriculture:Dominant consumption channel for high-analysis liquid fertilizers in intensive row-crop rotations. Brazil's Mato Grosso and Goiás states anchor absolute volume through direct procurement contracts between large-scale soybean operators and acid manufacturers.
- Horticulture:Specialty crop segments demanding acid-grade purity levels for permanent crops and controlled-release systems. California and Spain producers specify P2O5 concentration and polyphosphate chain length in annual supply agreements.
- Landscaping:Turf and ornamental applications with moderate nutrient density requirements. Municipal and commercial grounds maintenance contracts favor cost-optimized formulations.
- Soil Improvement:Remediation and amendment applications where polyphosphate chelation properties address micronutrient lock-up in alkaline soils.
Leading the category by volume: Agriculture. Expanding most quickly: Horticulture.
End Use Industry:
Downstream regulatory intensity varies sharply, with food-contact and pharmaceutical applications triggering multi-jurisdictional approval cascades that commodity fertilizer channels avoid.
- Chemicals:Intermediate production for phosphate-based specialty compounds and industrial catalysts. Technical-grade certification requirements filter out non-integrated merchant traders.
- Fertilizers:Primary industrial purpose centering on high-analysis liquid fertilizer manufacturing. Brazil MAPA standards and EU F-Gas Regulation compliance frameworks determine market access thresholds.
- Food & Beverage:Acidulant and pH control applications requiring food-grade purity certification. FDA and EFSA approval pathways impose extended validation timelines.
- Pharmaceuticals:Excipient and active ingredient precursor applications with the most stringent analytical specifications. EMA and national pharmaceutical regulators mandate granular toxicological data.
Leading the category by volume: Fertilizers. Steepest expansion trajectory: Chemicals.
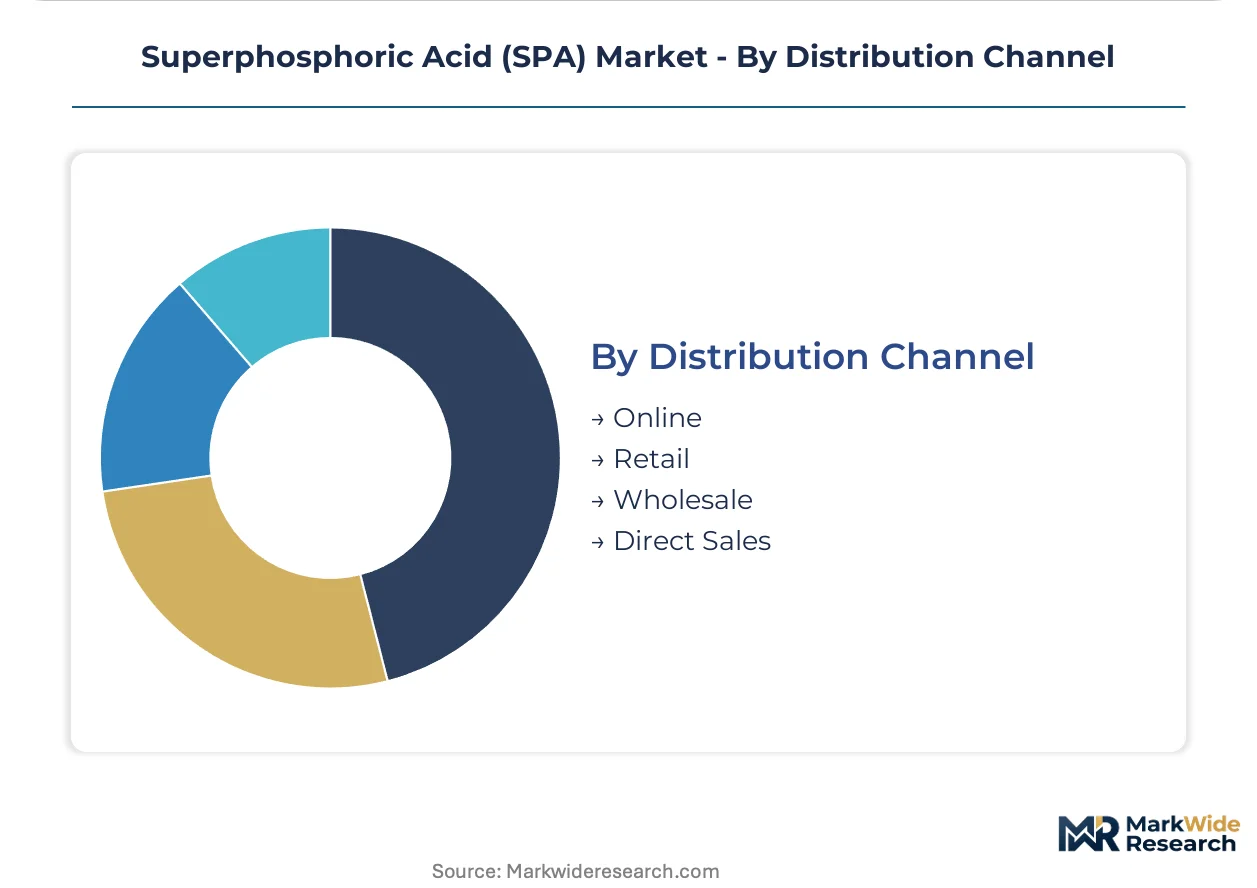
Distribution Channel:
Channel economics reflect customer scale and specification complexity, with large-volume agricultural buyers bypassing intermediaries while fragmented horticulture demand sustains distributor networks.
- Direct Sales:Annual contracts between acid manufacturers and 10,000+ hectare soybean operations in Brazil's Cerrado corridor. Specifications cover P2O5 concentration, polyphosphate chain length, and micronutrient compatibility.
- Wholesale:Bulk fertilizer terminals and regional distributor networks serving mid-scale agricultural blenders. Retrofitting infrastructure for corrosive high-concentration liquids fragments adoption.
- Retail:Packaged formulations for specialty crop producers and landscaping contractors. Margin compression from handling and inventory costs limits penetration.
- Online:Emerging procurement channel for technical-grade specifications and small-volume orders. Digital platforms reduce search costs for horticulture producers seeking certified suppliers.
Leading the category by volume: Direct Sales. Gaining share fastest: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for superphosphoric acid concentrates in agricultural corridors where phosphate-intensive crop rotations and regulatory certification requirements intersect, with Brazil's Cerrado soybean belt anchoring absolute volume and the EU's REACH framework filtering supplier access.
Brazil
MAPA fertilizer quality standards enforce stringent heavy-metal thresholds that marginal producers cannot meet. Direct procurement contracts between acid manufacturers and 10,000+ hectare soybean operations in Mato Grosso and Goiás displace traditional distributor networks. The Cerrado corridor dominates consumption through intensive double-cropping rotations.
United States
Florida phosphate rock mining complexes anchor North American acid manufacturing capacity. EPA fertilizer labeling requirements under FIFRA determine cross-state shipment specifications. Hurricane exposure and logistics constraints create supply vulnerability for merchant processors lacking integrated sulfur recovery.
Germany
ECHA polyphosphate registration protocols extend authorization timelines for novel acid formulations. REACH compliance frameworks reward producers with captive technical-grade certification capacity. The Rhine-Ruhr chemical cluster houses dehydration technology suppliers automating impurity removal systems.
Spain
Horticulture producers in Valencia and Murcia specify P2O5 concentration and polyphosphate chain length in annual supply agreements. EU F-Gas Regulation tightening elevates purity benchmarks for acid-grade inputs. Mediterranean specialty crop segments command margin premiums unavailable in commodity agriculture.
China
Dual carbon goals reshape fertilizer import accounting for downstream phosphate products. NMPA and MIIT standards govern technical-grade acid specifications for domestic specialty chemical synthesis. Yangtze River Delta chemical processors integrate membrane filtration systems for continuous rather than batch processing.
Superphosphoric Acid (SPA) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated mining-acid producers commanding upstream sulfur and phosphate rock access while merchant traders face margin compression from feedstock volatility. The structure consolidates around three archetypes: captive producers with integrated sulfur recovery, regional blenders with MAPA certification, and specialty chemical houses with REACH dossiers. Competitive moves center on dehydration technology licensing and backward integration into phosphate rock mining.
Within the integrated producer tier, Nutrien Ltd. and The Mosaic Company exemplify North American players with captive upstream access, while Yara International ASA anchors European ammonia-phosphate integration. These three occupy positions that non-integrated processors cannot replicate without sulfur hedging or long-term rock offtake agreements.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| The Mosaic Company |
| Yara International ASA |
| OCP Group |
| ICL Group Ltd. |
| PJSC PhosAgro |
| EuroChem Group AG |
| J.R. Simplot Company |
| Novaphos Corporation |
| Others |
Pricing and Supply Chain Analysis
Dehydration-technology specialists concentrated in Germany's Rhine-Ruhr chemical cluster command wage premiums that widen spreads between certified premium-grade SPA and commodity orthophosphoric acid alternatives. Labor-cost differentials between automated continuous-processing facilities and batch-operations in emerging production zones stratify pricing tiers across liquid, granular, and powdered grades.
Pricing Analysis
Volume throughput concentrates in liquid formulations traded on long-term contract structures, while margin capture concentrates in granular and powdered grades serving horticulture and pharmaceutical channels. Price differentiation rests on MAPA certification status and REACH technical-grade dossier completeness, with Brazilian blenders paying premiums for heavy-metal-compliant continuous-process material. Pricing pressure intensifies from sulfuric acid feedstock volatility transmitting directly to non-integrated processors. Commodity fertilizer blenders exhibit highest price sensitivity, whereas California specialty crop producers demonstrate lowest sensitivity due to acid-grade purity requirements.
Supply Chain Analysis
Brazil's domestic-content mandates under MAPA fertilizer quality standards are reshaping sourcing patterns toward locally certified dehydration facilities. Geographic supply concentration centers on Florida, Morocco, and Russia for phosphate rock feedstock, with sulfur recovery operations tethered to oil and gas processing corridors. Raw material dependencies span phosphate rock, elemental sulfur, and thermal energy inputs. Supply chain risk crystallizes around hurricane exposure to Florida mining complexes. Distribution runs through direct procurement contracts between acid manufacturers and large-scale Cerrado soybean operators, displacing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated producers with captive sulfur recovery and technical-grade certification capacity, with REACH registration timelines and MAPA compliance burdens forcing marginal merchant traders toward exit.
For Market Incumbents: Deploy backward integration into phosphate rock mining to secure feedstock access against Florida hurricane disruption and Moroccan export policy shifts. Deepen membrane filtration technology licensing to Brazilian specialty blenders seeking MAPA heavy-metal compliance, converting equipment sales into long-term acid offtake agreements. Anchor position through direct procurement relationships with 10,000+ hectare soybean operators in Mato Grosso and Goiás.
For New Entrants and Emerging Players: Mid-scale horticulture producers in Spain's Valencia and Murcia regions represent an underserved buyer archetype seeking acid-grade purity without volume minimums imposed by integrated majors. Enter through online procurement platforms reducing search costs for certified suppliers, leveraging REACH dossier preparation services as a wedge to downstream acid supply relationships. Target controlled-release fertilizer convergence with polymer coating technology partners.
For Investors and Strategic Acquirers: Re-rating potential sits with dehydration-technology licensors possessing automated impurity removal systems given EU carbon-border adjustment mechanisms favoring verified low-carbon production pathways. Acquisition focus should center on Brazilian regional blenders with MAPA certification and existing direct sales infrastructure. Monitor ECHA polyphosphate registration timeline compression as inflection indicator for formulation innovation pipeline thaw.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive supply of Florida or Moroccan rock secures margin against sulfur volatility. |
| Membrane Filtration Technology Licensing | Automated impurity removal compresses MAPA certification cycles from weeks to days. |
| Direct Procurement Contract Structuring | Annual specifications with Cerrado soybean operators displace distributor intermediaries. |
| REACH Technical-Grade Dossier Investment | Existing ECHA registrations reward incumbents with 18-36 month entry barriers. |
| Carbon-Border Adjustment Compliance Program | Verified low-carbon pathways capture EU fertilizer import preference. |
Research Methodology
Independent corroboration across plant managers at dehydration facilities, procurement leads at Brazilian specialty fertilizer blenders, distribution channel partners in the Cerrado corridor, and technical R&D directors at membrane filtration suppliers underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings of integrated phosphate producers, ANVISA regulatory filings, and ECHA registration databases. Bottom-up volume estimates from facility-level capacity utilization triangulate against top-down demand models built on crop rotation intensity and fertilizer application rates.
Rate-of-change decomposition across the projection horizon separates volume growth from value expansion, with segmentation modeling spanning product type, application channel, end-use industry, and distribution configuration. CAGRs derive from weighted average of historical trajectory and structural shift intensity, incorporating sulfur feedstock price elasticity, MAPA certification adoption curves, and polyphosphate chain length preference evolution in specialty crop segments.
Revisions become necessary when ECHA accelerates or delays polyphosphate registration evaluations, when Brazil's MAPA tightens heavy-metal thresholds beyond current membrane filtration capabilities, or when carbon-border adjustment mechanisms impose unanticipated compliance costs on imported acid. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Sodium Ethylate Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Pentanedione Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Menadione Market
Chemicals
Chloroplatinic Acid Market
Chemicals
Whitening Ingredients Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
De-Icing Agents Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Benzoyl Alcohol Market
Chemicals
1, 4 Butanediol Market
Chemicals
Flatting Agents Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Hydrogen Chloride Market