
 Asia-Pacific Organic Acid Market | 2026-2036
Asia-Pacific Organic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Organic Acid Market Outlook
Multi-source procurement of agricultural feedstocks is realigning supply security for organic acid producers across the region. BASF SE leverages its integrated petrochemical networks to secure propylene-derived acetic acid volumes. Cargill anchors fermentation supply chains through corn and sugarcane sourcing partnerships in Thailand and Australia. Henan Jindan Lactic Acid Technology dominates domestic lactic acid output with captive starch processing in Henan province.
Organic acids comprise carboxylic compounds produced through petrochemical oxidation or microbial fermentation, typically at purity grades between 80% and 99.5% depending on end-use specifications, serving primarily as acidulants, preservatives, and chemical intermediates. Acetic acid claims the largest volume share given its role in vinyl acetate monomer and purified terephthalic acid production, while lactic acid registers the fastest structural expansion on the back of polylactic acid biopolymer demand. Citric acid retains mature margin pools in food and beverage applications, though pharmaceutical-grade specifications command premium pricing from cosmetic firms and healthcare providers.
China's MEE enforces wastewater discharge limits on fermentation facilities, while India's BIS mandates purity benchmarks for food-grade acid imports, and Japan's METI promotes bio-based production through JIS standards alignment. These frameworks elevate compliance costs for smaller chemical producers while accelerating consolidation among certified manufacturers. Stakeholders must monitor feedstock price volatility and regulatory harmonization progress to calibrate capacity investments across the region.
Market Dynamics
Fermentation-based production systems face mounting pressure from China's dual carbon goals and wastewater discharge limits enforced by the MEE, forcing capacity owners toward integrated biorefinery models that capture carbon and recycle process water.
Growth Catalysts
- Food-grade acid demand:Southeast Asian food manufacturers expand acetic acid consumption for preservative and flavoring applications in processed seafood and ready-to-eat meals.
- Polylactic acid biopolymer pull:Packaging converters across Japan and South Korea are scaling polylactic acid adoption, driving structural expansion in lactic acid fermentation capacity.
- GB standards compliance:China's tightening emissions benchmarks for fermentation facilities are accelerating consolidation among certified producers with captive starch processing capabilities.
Market Restraints
- Feedstock price volatility:Corn and sugarcane procurement costs fluctuate with monsoon patterns across Thailand and Australia's agricultural belts, compressing margin predictability for fermentation operators.
- Supply concentration risk:Henan province dominates China's domestic lactic acid output through captive starch processing, creating geographic single-point vulnerability for regional supply security.
- Regulatory friction:India's BIS mandates purity benchmarks for food-grade acid imports that elevate compliance timelines and testing costs for cross-border shipments.
Strategic Opportunities
- Pharmaceutical-grade citric acid:India's pharmaceutical corridor presents unmet demand for excipient-grade citric acid in generic drug formulation, commanding premium pricing from cosmetic firms and healthcare providers.
- Bio-based production incentives:Japan's METI promotes fermentation-derived organic acids through JIS standards alignment, creating regulatory tailwind for certified domestic manufacturers.
- Multi-source feedstock partnerships:Cargill's corn and sugarcane sourcing networks across Thailand and Australia demonstrate viable templates for supply security through geographic diversification.
Industry Challenges
- Skill gap in bioprocess engineering:Fermentation facilities across Vietnam and Indonesia face shortages of trained operators capable of managing continuous culture systems at industrial scale.
- Capex intensity for wastewater treatment:China's MEE discharge limits require anaerobic digester and membrane bioreactor investments that strain balance sheets of mid-cap chemical producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Organic Acid Market |
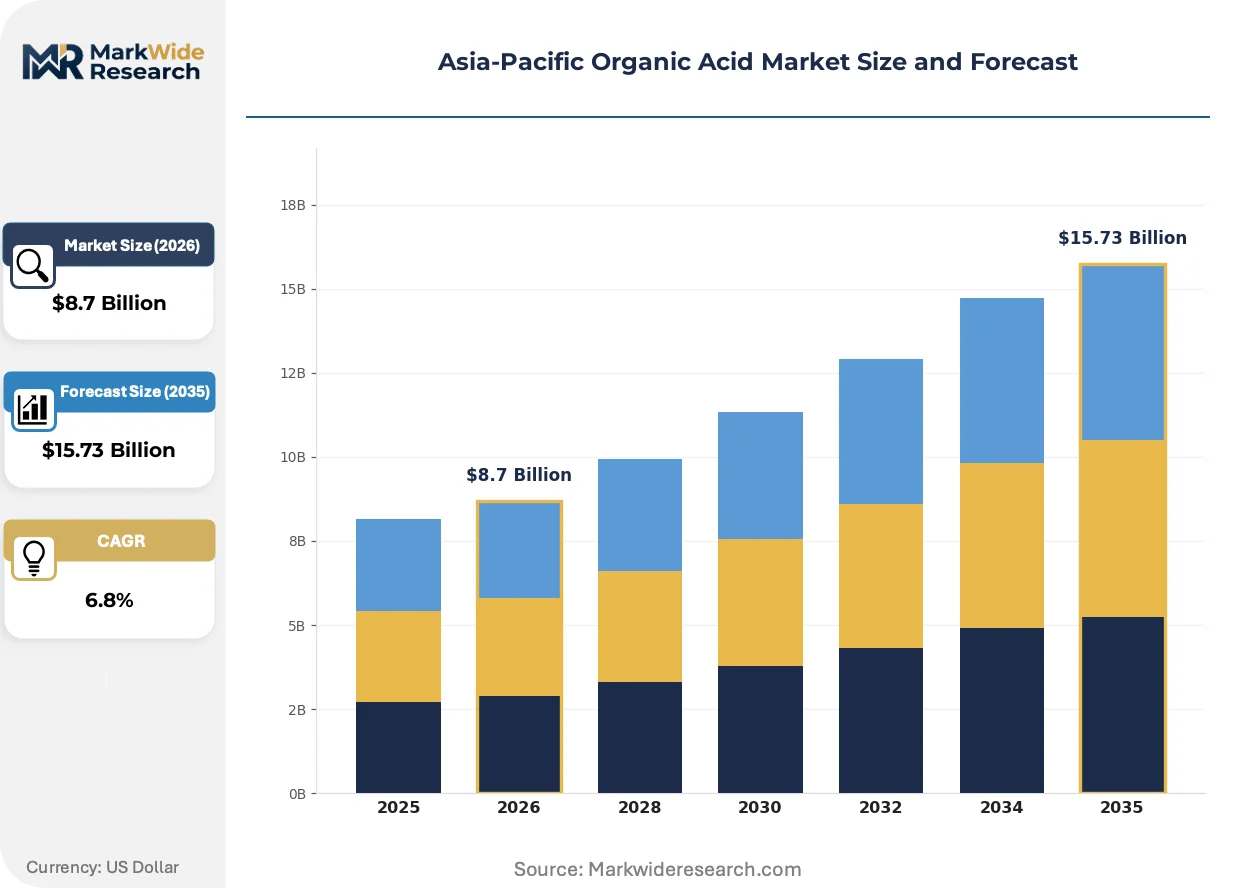
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Acid, Lactic Acid, Citric Acid, Fumaric Acid Application: Food & Beverage, Agriculture, Pharmaceuticals, Personal Care Distribution Channel: Online, Distributors, Hypermarkets, Retail Stores End User: Food Manufacturers, Chemical Producers, Cosmetic Firms, Healthcare Providers |
| Companies Covered | BASF SE, Cargill, Corbion, Eastman Chemical Company, Henan Jindan Lactic Acid Technology, Archer Daniels Midland Company, Tate & Lyle, Dow Chemical Company, DuPont de Nemours, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Organic Acid Market Strategic Shifts
Continuous fermentation technology and cell-free enzymatic synthesis are compressing batch cycle times while regulatory pressure on carbon intensity reshapes where producers locate capacity across the region.
Cell-free enzymatic synthesis is modularizing organic acid production by eliminating the need for live culture maintenance in bioreactors. Pharmaceutical and fine chemical manufacturers in Japan and South Korea are piloting these systems for citric acid and lactic acid derivatives. The technology is modularizing facility footprints, enabling distributed production nodes that reduce transport costs and carbon exposure.
China's GB standards for fermentation emissions are tightening discharge limits on chemical oxygen demand and total nitrogen. Facilities in Shandong and Jiangsu provinces must retrofit anaerobic digestion and membrane filtration systems or face operating suspension. Food-grade acid producers with integrated wastewater treatment are capturing market share from non-compliant competitors facing import restrictions into India's pharmaceutical corridor.
Buyers in the Asia-Pacific organic acid market are consolidating procurement through long-term offtake agreements with fermentation operators holding verified sustainability credentials. Major food and beverage conglomerates across Southeast Asia now require mass-balance certification for acetic acid and citric acid purchases. This behavioral shift is most visible in Thailand's processed food sector, where multinational brands are disqualifying spot-market suppliers lacking third-party carbon accounting.
Asia-Pacific Organic Acid Market Segmentation
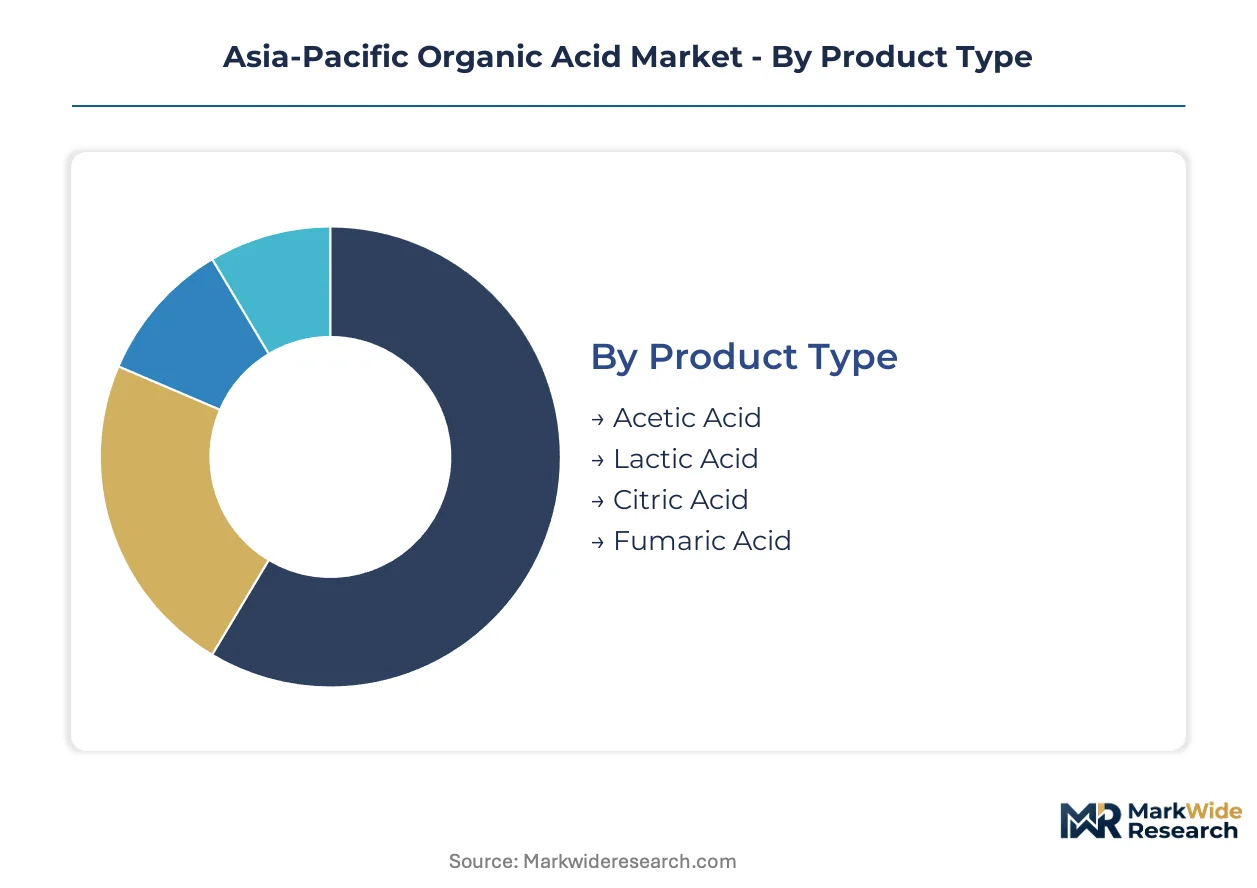
Organic acid purchasing patterns across Asia-Pacific diverge sharply by end-use purity requirements and regulatory compliance burdens. Food-grade specifications command mass-volume fermentation capacity, while pharmaceutical-grade segments extract premium returns through excipient certification.
Product Type:
Upgrade cycles in industrial chemistry are displacing older acid stocks with fermentation-derived alternatives that meet tightening emissions standards.
- Acetic Acid:Petrochemical oxidation and methanol carbonylation yield this C2 carboxylic acid at purity grades between 80% and 99.5%. Vinyl acetate monomer producers across China's Shandong province consume the largest volumes, though GB standards compliance is forcing capacity consolidation toward integrated biorefinery operators.
- Lactic Acid:Microbial fermentation of starch hydrolysates produces this chiral hydroxy acid with stereochemical purity critical for polylactic acid polymerization. Packaging converters in Japan and South Korea are scaling PLA adoption, pulling fermentation capacity expansion across Thailand and Australia's sugarcane belts.
- Citric Acid:Aspergillus niger fermentation generates this tricarboxylic acid for acidulant and chelating applications. India's pharmaceutical corridor sources excipient-grade material for generic drug formulation.
- Fumaric Acid:Maleic anhydride isomerization or fermentation routes yield this dicarboxylic acid for unsaturated polyester resins. Food acidulant applications in Southeast Asian processed seafood sectors provide secondary demand.
Acetic acid sits at the top of the volume ranking, with lactic acid climbing the fastest.
Application:
Margin structures across application segments stratify by certification tier, with pharmaceutical and food-grade specifications capturing value above industrial commodity grades.
- Food & Beverage:Acidulant and preservative functions in processed seafood, ready-to-eat meals, and beverage formulations drive acetic acid and citric acid procurement. Southeast Asian food manufacturers are consolidating procurement through long-term offtake agreements with mass-balance certified suppliers.
- Agriculture:Soil acidification and feed additive applications consume lower-purity fermentation grades. Australia's grain belt and Thailand's aquaculture sectors anchor regional demand for acidulant-supplemented feed formulations.
- Pharmaceuticals:Excipient-grade citric acid and lactic acid serve as pH adjusters and buffering agents in generic drug manufacturing. India's BIS mandates purity benchmarks that elevate compliance timelines for cross-border shipments.
- Personal Care:Cosmetic-grade lactic acid functions as a humectant and pH adjuster in skincare formulations. Premium pricing from Japanese and South Korean cosmetic firms rewards fermentation operators with verified sustainability credentials.
Food and beverage applications command the largest share of fermentation output, while pharmaceutical-grade segments are gaining share fastest.
Distribution Channel:
Channel selection in organic acid procurement tracks buyer scale and certification requirements, with large-volume food manufacturers bypassing intermediaries.
- Online:Digital platforms facilitate spot-market transactions for standard-grade industrial acids, though food and pharmaceutical buyers rarely source through this channel given traceability requirements.
- Distributors:Regional chemical distributors maintain inventory positions across China's coastal provinces and India's pharmaceutical corridor, offering technical support and logistics coordination for mid-scale buyers.
- Hypermarkets:Food-grade acids in consumer packaging reach small-scale food processors and institutional kitchens through Thailand's modern retail networks.
- Retail Stores:Specialty chemical retailers in Japan and South Korea supply laboratory-scale quantities to research institutions and small cosmetic formulators.
Distributors handle the largest volume flows, with direct online procurement expanding most quickly among industrial commodity buyers.
End User:
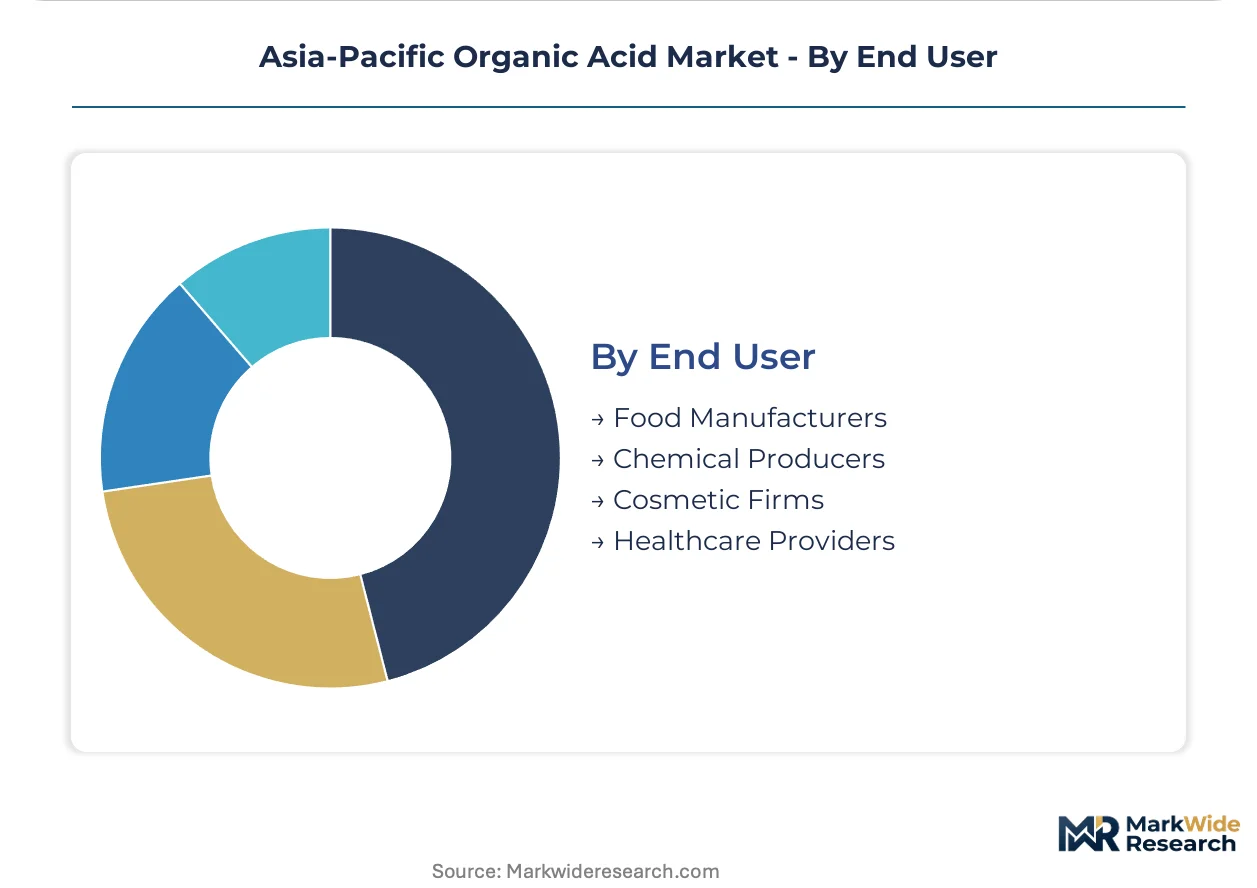
End-user concentration in organic acid demand follows the geographic clustering of downstream manufacturing, with chemical producers and food manufacturers dominating procurement volumes.
- Food Manufacturers:Processed seafood and ready-to-eat meal producers across Southeast Asia specify mass-balance certified acetic acid and citric acid to meet multinational brand procurement standards.
- Chemical Producers:Vinyl acetate monomer and purified terephthalic acid manufacturers in China's Shandong and Jiangsu provinces consume petrochemical-derived acetic acid at industrial scale.
- Cosmetic Firms:Japanese and South Korean skincare brands source pharmaceutical-grade lactic acid through verified fermentation supply chains, rewarding suppliers with third-party carbon accounting.
- Healthcare Providers:Hospital pharmacies and generic drug manufacturers in India's pharmaceutical corridor procure excipient-grade citric acid for parenteral and oral formulations.
Food manufacturers and chemical producers together dominate volume offtake, with cosmetic firms expanding their share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors fermentation capacity expansion as China's dual carbon goals force industrial acid producers toward integrated biorefinery models.
China
Vinyl acetate monomer manufacturers in Shandong and Jiangsu provinces drive acetic acid consumption at industrial scale. The MEE enforces wastewater discharge limits on fermentation facilities, compelling anaerobic digester investments. Henan province dominates domestic lactic acid output through captive starch processing operations.
India
Generic drug manufacturers in the pharmaceutical corridor source excipient-grade citric acid for parenteral formulations. The BIS mandates purity benchmarks for food-grade acid imports, elevating compliance timelines for cross-border shipments. Maharashtra and Gujarat clusters concentrate fermentation capacity for domestic acidulant supply.
Japan
Packaging converters scale polylactic acid adoption, pulling lactic acid demand from fermentation operators. METI promotes bio-based production through JIS standards alignment, creating regulatory tailwind for certified domestic manufacturers. The Kanto region houses pilot facilities for cell-free enzymatic synthesis systems.
Thailand
Processed seafood manufacturers expand acetic acid procurement for preservative applications in ready-to-eat meals. Monsoon patterns disrupt corn and sugarcane feedstock costs, compressing margin predictability for fermentation operators. Cargill anchors supply security through multi-source agricultural partnerships across the central plains.
Australia
Grain belt agriculture consumes lower-purity fermentation grades for feed additive formulations. The country's national environmental regulator enforces discharge standards on bioprocessing facilities. Queensland and New South Wales host expanded sugarcane-derived lactic acid capacity serving Japanese biopolymer demand.
Asia-Pacific Organic Acid Market Competitive Environment
Global majors compete with regional champions across feedstock access and certification tiers. The vendor base stratifies between petrochemical oxidation operators and fermentation specialists, with mid-cap producers facing consolidation pressure from compliance costs. Three archetypes dominate: integrated chemical conglomerates with captive raw material networks, agricultural processors leveraging crop sourcing scale, and domestic champions with provincial government backing. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players secure multi-source feedstock arrangements.
Among German-based chemical conglomerates, BASF SE occupies a position exemplifying integrated petrochemical networks securing propylene-derived volumes. Cargill represents the agricultural processor archetype through corn and sugarcane sourcing partnerships. Henan Jindan Lactic Acid Technology anchors the domestic champion tier with provincial captive starch capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Cargill |
| Corbion |
| Eastman Chemical Company |
| Henan Jindan Lactic Acid Technology |
| Archer Daniels Midland Company |
| Tate & Lyle |
| Dow Chemical Company |
| DuPont de Nemours |
| Others |
Value Chain & Pricing Dynamics
Mass-balance certification requirements from multinational food brands are forcing fermentation operators to upgrade wastewater treatment and carbon accounting systems, compressing margins for uncertified suppliers while rewarding integrated biorefinery operators with pricing power.
Pricing Analysis
Input-cost pass-through from corn and sugarcane procurement dominates pricing dynamics across Thailand and Australia's agricultural belts. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade specifications captures value from excipient certification and purity benchmarks. Cost compression in food-grade acetic acid is intensifying because monsoon-driven feedstock volatility erodes margin predictability for standalone fermentation operators. Small-scale industrial buyers exhibit highest price sensitivity, while Japanese cosmetic firms purchasing pharmaceutical-grade lactic acid demonstrate lowest sensitivity due to sustainability credential requirements.
Supply Chain Analysis
Single-source vulnerability sits with Henan province's captive starch processing operations, which anchor China's domestic lactic acid output. Geographic supply concentration spans China, Thailand, and India, with Shandong and Jiangsu provinces hosting acetic acid capacity and Maharashtra-Gujarat clusters anchoring Indian fermentation. Raw material dependencies center on corn, sugarcane, and cassava starch hydrolysates. Regulatory restriction risk manifests through India's BIS purity mandates and China's MEE discharge limits. Distribution runs through regional chemical distributors maintaining inventory positions across coastal provinces, with direct long-term offtake agreements expanding among certified fermentation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific organic acid market reads as a late-cycle quality story, with downstream buyers consolidating procurement around mass-balance certified suppliers and pharmaceutical-grade specifications commanding structural premium expansion.
For Market Incumbents: Lock in multi-source feedstock partnerships across Thailand and Australia's sugarcane belts to neutralize monsoon-driven margin volatility. Deepen backward integration into captive starch processing to defend against emerging biorefinery competitors with integrated carbon capture. Prioritize anaerobic digester investments ahead of China's MEE enforcement waves to capture market share from non-compliant operators facing import restrictions into India's pharmaceutical corridor. For New Entrants and Emerging Players: The 40-60% price-point gap between pharmaceutical-grade and industrial-grade citric acid presents the most penetrable white-space opportunity. Target India's pharmaceutical corridor with excipient-grade capacity, where BIS compliance timelines have created supply bottlenecks for cross-border shipments. Pursue joint venture structures with established corn processors in Thailand to shortcut feedstock security challenges and accelerate certification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap fermentation operators holding verified sustainability credentials and captive agricultural processing in defensible geographies. Five-to-ten year viability favors producers with provincial government backing and integrated wastewater treatment already deployed. Watch for MEE enforcement acceleration in Shandong and Jiangsu as the inflection indicator for consolidation timing among non-compliant capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Processing | Cargill's corn and sugarcane sourcing networks demonstrate viable templates for supply security through geographic diversification. |
| Green Manufacturing Transition | Cell-free enzymatic synthesis pilot facilities in Japan's Kanto region enable modular production footprints with reduced carbon exposure. |
| Long-term Supply Agreement | Thailand's processed seafood manufacturers are consolidating acetic acid procurement through mass-balance certified offtake contracts. |
| Joint Venture | Queensland and New South Wales partnerships anchor expanded sugarcane-derived lactic acid capacity serving Japanese biopolymer demand. |
| Capacity Expansion | Henan province's captive starch operations dominate domestic lactic acid output, creating geographic concentration risk for regional supply security. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, procurement leads at downstream food manufacturers, distribution channel partners, and technical R&D directors with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Historical reference periods spanning fermentation capacity utilization trends and feedstock price cycles anchored the projection horizon. The analytical framework modeled segmentation across grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from slope analysis of normalized growth trajectories. Key forecast inputs included China's MEE enforcement intensity and Japan's METI bio-based production incentive trajectories.
Caveats apply where regulatory enforcement acceleration or feedstock price shocks could materially shift the outlook. Forecasts reflect assumptions about certification adoption rates and biorefinery capital deployment patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Organic Acids Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
Phenol Market
Organic Chemicals
Europe Cycloalkanes Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
Chlorocyclopentane Market