
 Humic Acid Market | 2026-2036
Humic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Humic Acid Market Analysis
Specialty crop producers is unwinding commodity grain farmers' historical dominance in humic acid procurement. The Andersons, Inc. leverages its grain elevator network to push private-label humic formulations into Midwestern farm supply channels. Humintech GmbH anchors European demand through certified organic product lines aligned with EFSA guidelines. Black Earth Humic LP dominates Canadian peat-derived humic sourcing, controlling extraction sites across Alberta's boreal zone.
Humic acid comprises a complex mixture of humic substances—primarily humic and fulvic acids—extracted from decomposed organic matter such as leonardite, peat, or composted biomass, with carbon content typically ranging from 50% to 60% and molecular weights spanning 2,000 to 300,000 Daltons. Its primary commercial purpose centers on chelating soil micronutrients, improving cation exchange capacity, and stimulating root-zone microbial activity in agricultural and environmental applications. Liquid humic acid leads volume sales due to compatibility with fertigation systems, while soluble humic acid commands premium positioning in greenhouse hydroponics where rapid dissolution prevents emitter clogging. Granular humic acid occupies mature demand in bulk field applications, whereas powdered formats retain niche strength in blended fertilizer manufacturing.
The EPA regulates humic acid products marketed with pesticidal claims under FIFRA, while the USDA National Organic Program governs certifier-approved sources for organic crop production. State-level fertilizer registration requirements in California and Florida create fragmented compliance burdens for interstate suppliers. Stakeholders must monitor evolving soil carbon credit protocols, as verification standards for humic acid's net carbon impact remain unsettled across voluntary offset registries.
Market Dynamics
Specialty crop producers are unwinding commodity grain farmers' historical dominance in humic acid procurement, driven by precision nutrient management requirements and carbon credit verification protocols that favor high-value horticultural systems over broadacre row crops.
Growth Catalysts
- EU Fertilizing Products Regulation:Tightening organic input certification requirements across member states is compelling conventional fertilizer blenders to reformulate with certified humic sources to retain market access.
- Fertigation system compatibility:Liquid humic acid formulations integrate seamlessly with drip irrigation infrastructure, accelerating adoption among Brazilian Cerrado soybean operators expanding into double-crop corn rotations.
- Peat extraction sites:Canadian boreal zone leonardite deposits provide high-carbon feedstock for North American premium-grade humic production, anchoring regional supply security.
Market Restraints
- Leonardite price volatility:Input costs fluctuate with fossil fuel extraction economics and competing industrial demand for low-rank coal derivatives.
- Alberta boreal zone concentration:Canadian peat-derived humic sourcing depends on a limited geographic extraction footprint vulnerable to provincial environmental permitting delays.
- FIFRA pesticidal claim friction:EPA jurisdiction over products marketed with biostimulant-adjacent language creates interstate registration burdens and label restriction uncertainty.
Strategic Opportunities
- Soil carbon credit protocols:Voluntary offset registries in Australia and Canada are developing verification standards that could monetize humic acid's net carbon impact for agricultural producers.
- Hydroponic greenhouse channels:Soluble humic acid formats for emitter-clog-sensitive systems remain underdeveloped in Mediterranean protected-crop zones.
- USDA National Organic Program alignment:Certified organic product lines capture price premiums in California specialty vegetable supply chains.
Industry Challenges
- Carbon quantification expertise:Verification methodology development requires agronomic scientists capable of bridging soil chemistry and offset registry accounting protocols.
- State fertilizer registration fragmentation:California and Florida maintain divergent compliance requirements that complicate interstate distribution logistics for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humic Acid Market |
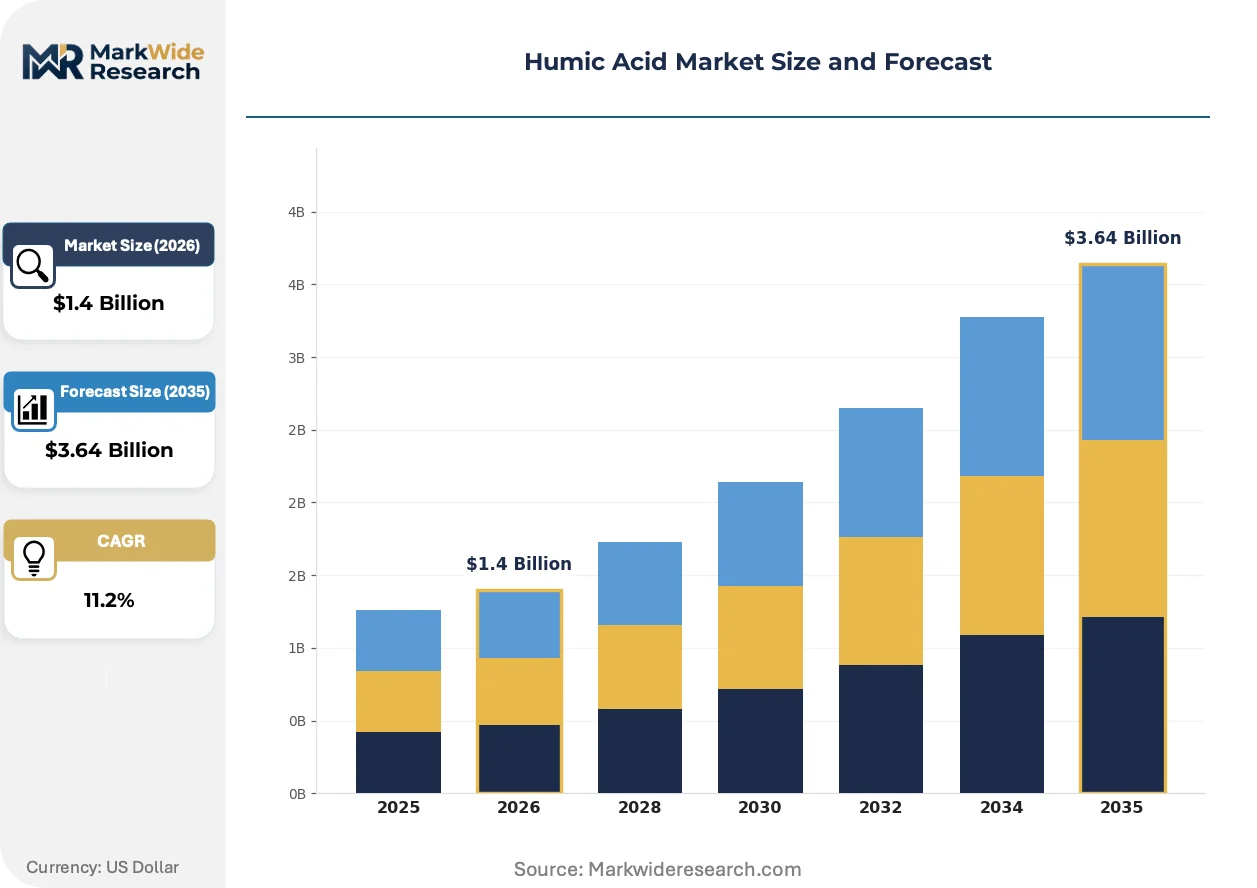
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Humic Acid, Granular Humic Acid, Powdered Humic Acid, Soluble Humic Acid Application: Agriculture, Horticulture, Environmental Remediation, Soil Conditioning End Use Industry: Agricultural Sector, Landscaping, Waste Management, Mining Distribution Channel: Online Sales, Direct Sales, Retail Outlets, Distributors |
| Companies Covered | Humintech GmbH, The Andersons, Inc., BASF SE, Humic Growth Solutions, Inc., Black Earth Humic LP, Biolchim S.p.A., Agbest Technology Co. Limited, Cifo SRL, Arctech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humic Acid Market Emerging Trajectories
Extraction technology advancement and regulatory classification refinement are compressing production economics while expanding addressable application segments beyond traditional agricultural channels.
Microbial fermentation-derived humic substances are supplanting geologically extracted leonardite in premium greenhouse formulations. Dutch hydroponic lettuce operators adopted fermentation-sourced fulvic acid at scale during the 2022-2024 period. This biotechnology pathway is compressing reliance on finite peat reserves while enabling batch-to-batch consistency impossible with variable-grade mined feedstocks.
REACH substance registration requirements for humic acid imports into the European Economic Area tightened documentation burdens for non-EU producers during 2023. The regulation forces third-country suppliers to commission full toxicological dossiers or partner with EU-based formulators holding existing registrations. German and Dutch distribution intermediaries captured margin by consolidating import compliance functions for Asian and North American producers.
Direct-to-grower digital platforms are fragmenting traditional farm supply cooperative channels for humic acid procurement. Brazilian Cerrado operators now source liquid formulations through agtech-enabled input marketplaces that bypass legacy distributor markups. This channel shift concentrates price transparency pressure on Midwestern US grain elevator networks that historically controlled private-label humic distribution.
Humic Acid Market Segmentation
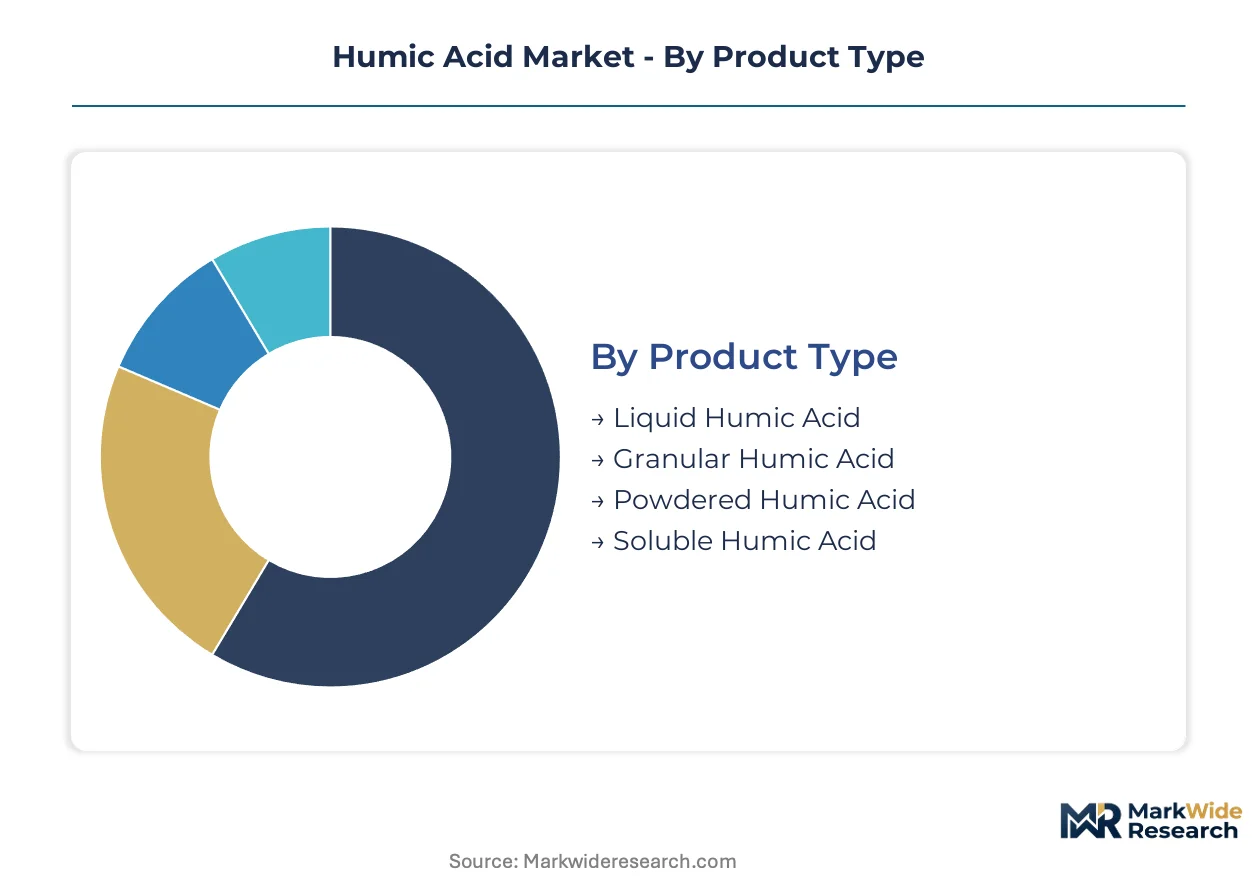
Humic acid procurement patterns diverge sharply across formulation chemistry and application intensity. Regulatory classification of each product type determines compliance burden, while end-use sector selection dictates margin structure and channel access.
Product Type:
EPA FIFRA jurisdiction and state fertilizer registration requirements fragment competitive positioning across physical formats.
- Liquid Humic Acid:Aqueous suspensions with 12-15% humic substance concentration enable direct injection into fertigation lines without pre-dissolution. Brazilian Cerrado soybean operators deploy this format for double-crop corn rotations where drip infrastructure dominates. Established volume favors liquid formulations; emerging adoption favors soluble grades in greenhouse hydroponics.
- Granular Humic Acid:Compressed pellets or prills with slow-release characteristics suit broadcast spreading equipment common in Midwestern US commodity grain operations. Alberta boreal zone leonardite feedstock supplies North American bulk demand, though transport economics limit radius from extraction sites.
- Powdered Humic Acid:Fine-ground material with 60%+ carbon content serves blended fertilizer manufacturing where dry mixing equipment predominates.
- Soluble Humic Acid:Ultra-fine particle size ensures rapid dissolution for emitter-sensitive hydroponic systems; EFSA-aligned organic certification commands greenhouse premium positioning.
Volume leadership concentrates in liquid and granular formats; soluble and powdered segments capture specialty margin premiums.
Application:
Carbon credit verification protocols and input cost recovery timelines reshape sector prioritization for suppliers.
- Agriculture:Broadacre row crop and specialty vegetable production deploy humic acid for chelated micronutrient delivery and cation exchange capacity improvement. California specialty crop producers drive precision application adoption under USDA National Organic Program certification requirements.
- Horticulture:Protected-crop greenhouse operators in Mediterranean zones adopt soluble formats for soilless substrate systems where root-zone microbial stimulation accelerates harvest cycles.
- Environmental Remediation:Heavy metal chelation and soil reconstruction applications at mining-impacted sites leverage humic acid's complexation chemistry for pollutant immobilization.
- Soil Conditioning:Large-scale land reclamation and construction site rehabilitation use bulk granular applications for organic matter restoration in degraded substrates.
Revenue concentration tilts toward agriculture; horticulture delivers steepest expansion trajectory as protected-crop acreage expands.
End Use Industry:
Customer procurement sophistication and technical specification requirements determine channel strategy and pricing architecture.
- Agricultural Sector:Farm operators and cooperative purchasing groups dominate volume procurement, with Brazilian Cerrado and US Midwest representing anchor demand basins. Direct-to-grower digital platforms are fragmenting traditional elevator-network distribution.
- Landscaping:Turf management and ornamental plant operations require consistent batch quality for aesthetic outcome predictability, favoring certified organic product lines.
- Waste Management:Composting facility operators and landfill capping projects use humic acid for odor control and methane suppression in anaerobic decomposition management.
- Mining:Post-extraction site rehabilitation and tailings stabilization represent emerging demand as jurisdictional closure bonding requirements tighten.
Agricultural sector procurement maintains volume dominance; mining rehabilitation represents fastest-climbing adoption curve.
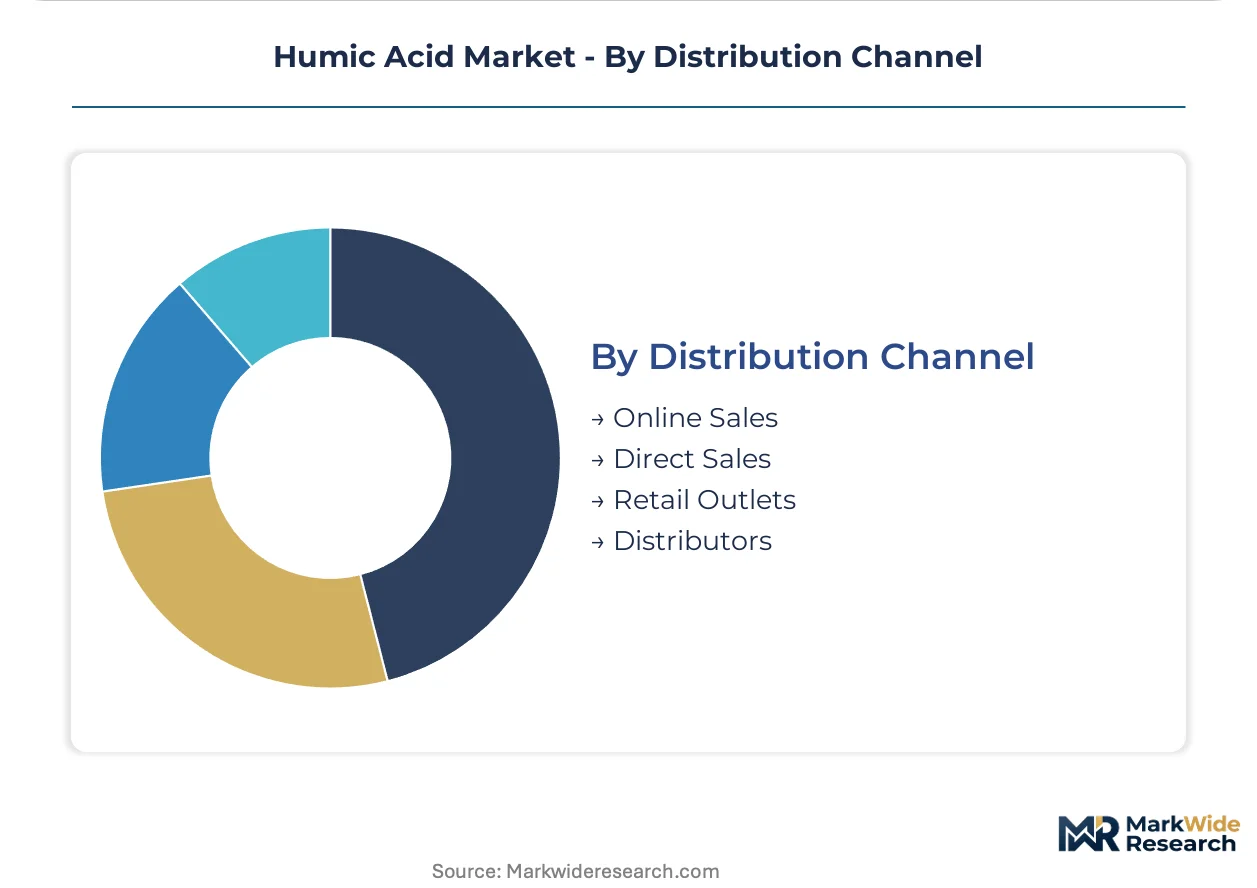
Distribution Channel:
Channel selection determines margin capture, technical support obligation, and customer relationship depth.
- Direct Sales:Manufacturer-to-grower relationships enable custom formulation and agronomic advisory bundling for large-scale specialty crop operations. The Andersons' grain elevator network exemplifies this channel's historical control over Midwestern private-label distribution.
- Distributors:Regional agricultural supply wholesalers consolidate inventory risk and provide last-mile logistics for fragmented farm bases.
- Online Sales:Agtech-enabled marketplaces concentrate price transparency and enable Brazilian Cerrado operators to bypass legacy markup structures.
- Retail Outlets:Farm supply stores and garden centers serve hobbyist and small-scale landscaping demand with packaged consumer formats.
Direct and distributor channels retain agricultural sector control; online sales gain share fastest among digitally-enabled commercial growers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leonardite extraction concentrates in Alberta's boreal zone and Brazil's Cerrado anchors demand expansion for precision nutrient management. Regulatory divergence across major agricultural economies fragments compliance architecture for humic acid suppliers.
United States
Midwestern grain elevator networks retain distribution control for private-label humic formulations serving commodity row crops. EPA FIFRA jurisdiction over pesticidal claim products creates interstate registration friction for multi-regional suppliers. California specialty vegetable producers drive precision application adoption under USDA National Organic Program certification requirements in the Central Valley.
Brazil
Cerrado soybean operators expanding into double-crop corn rotations deploy liquid humic acid through drip irrigation infrastructure. ANVISA alignment with international organic input standards tightens import documentation for non-certified suppliers. São Paulo-based agtech marketplaces fragment traditional cooperative procurement channels for commercial growers.
Germany
EU Fertilizing Products Regulation compliance compels conventional fertilizer blenders to reformulate with certified humic sources. ECHA REACH substance registration requirements force third-country suppliers to commission toxicological dossiers or partner with EU-based formulators. North Rhine-Westphalia distribution intermediaries consolidate import compliance functions for Asian and North American producers.
Canada
Alberta boreal zone peat extraction sites provide high-carbon feedstock for North American premium-grade humic production. Health Canada PMRA and provincial environmental permitting delays create supply vulnerability for the limited geographic extraction footprint. Ontario greenhouse operators in the Leamington cluster adopt fermentation-sourced alternatives to reduce peat dependence.
China
Domestic leonardite reserves in Xinjiang and Inner Mongolia support captive supply for agricultural humic production. MEE environmental compliance tightening around mining-impacted site rehabilitation creates demand for heavy metal chelation applications. Shandong Peninsula fertilizer manufacturers integrate backward into humic extraction to secure feedstock for blended product lines.
Humic Acid Market Vendor Landscape
Concentration sits with vertically integrated extractors and regional formulation specialists rather than multinational agrochemical conglomerates. The competitive terrain divides between leonardite miners controlling upstream feedstock, toll manufacturers serving private-label distributors, and certified organic specialists capturing greenhouse premiums. Three archetypes dominate: boreal zone peat extractors with captive carbon reserves, fermentation technology platforms displacing mined feedstocks, and grain-elevator-linked distributors with embedded Midwestern farm relationships. Capacity expansion into soluble formats and strategic partnerships with carbon credit verification protocols represent the dominant competitive vectors.
Within the extraction-control archetype, Black Earth Humic LP exemplifies regional feedstock dominance through Alberta-based leonardite sourcing, while Humintech GmbH occupies a position as the European organic certification anchor. The Andersons, Inc. represents the elevator-network distribution model that historically controlled Midwestern private-label channels. These three companies illustrate the structural segmentation between upstream resource control, regulatory compliance specialization, and downstream logistics integration that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Humintech GmbH |
| The Andersons, Inc. |
| BASF SE |
| Humic Growth Solutions, Inc. |
| Black Earth Humic LP |
| Biolchim S.p.A. |
| Agbest Technology Co. Limited |
| Cifo SRL |
| Arctech Inc. |
| Others |
Supply Flow & Price Mechanics
Alberta boreal zone extraction economies anchor North American price floors through captive leonardite reserves, while Brazilian Cerrado fertigation scale compresses liquid formulation premiums. Scale-driven feedstock control separates premium soluble grades from commodity granular tiers.
Pricing Analysis
Volume-discount tiering structures stratify across premium soluble, standard liquid, and economy granular levels. Price differentiation rests on EFSA-aligned organic certification and carbon content grade, with fermentation-sourced fulvic acid commanding greenhouse premiums over mined leonardite. Cost compression in liquid formulations is intensifying because agtech marketplaces expose legacy distributor markups. Commodity grain cooperatives exhibit highest price sensitivity; California specialty vegetable producers under USDA National Organic Program requirements show lowest.
Supply Chain Analysis
Canada and Brazil anchor upstream humic acid production through Alberta peat extraction and Cerrado demand clustering respectively. Raw material dependencies draw from leonardite deposits, fermentation bioreactor capacity, and composted biomass feedstocks. Single-source vulnerability concentrates in Alberta's limited boreal zone footprint exposed to provincial environmental permitting delays. Distribution runs through grain elevator networks in the US Midwest and agtech-enabled direct platforms in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Humic acid market fragmentation creates entry niches as digital procurement platforms disintermediate legacy cooperative channels and fermentation technology opens biotechnology pathways.
For Market Incumbents: Compound feedstock security through Alberta leonardite lease consolidation or fermentation capacity partnerships. Anchor certification investment against EU Fertilizing Products Regulation tightening and USDA National Organic Program alignment requirements. Defend against microbial fermentation substitutes by locking long-term supply agreements with Brazilian Cerrado operators. For New Entrants and Emerging Players: Differentiate on fermentation-derived batch consistency for Dutch and Ontario greenhouse operators seeking peat independence. Target Mediterranean protected-crop zones with soluble formats for emitter-clog-sensitive hydroponic infrastructure. Pursue carbon credit verification protocol partnerships as the go-to-market anchor for Australian and Canadian agricultural producers. For Investors and Strategic Acquirers: Fermentation technology platforms with established greenhouse supply relationships represent the priority acquisition archetype. Long-term viability hinges on biotechnology pathways displacing finite peat reserves over the coming decade. Watch for soil carbon credit registry standardization as the inflection signal validating humic acid's monetizable carbon impact.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leonardite Reserves | Alberta boreal zone lease consolidation secures high-carbon feedstock for premium-grade production. |
| Fermentation Technology Scale-Up | Microbial bioreactor capacity reduces peat dependence and enables batch-to-batch consistency for greenhouse operators. |
| EU Fertilizing Products Certification | EFSA-aligned organic product lines unlock premium positioning in German and Dutch reformulation demand. |
| Carbon Credit Protocol Partnership | Australian and Canadian offset registry alignment monetizes soil carbon impact for agricultural producers. |
| Agtech Marketplace Channel Development | Direct-to-grower platforms bypass legacy distributor markups in Brazilian Cerrado procurement. |
Methodological Framework
Operator-level perspectives from extraction site managers, fertilizer formulation chemists, greenhouse operations directors, and agricultural cooperative procurement leads anchored the qualitative base. Secondary validation drew from EPA FIFRA registration databases, USDA National Organic Program certified operations lists, EU ECHA REACH substance filings, and Brazilian ANVISA import documentation. Bottom-up volume triangulation against top-down regulatory filing aggregation ensured cross-verified demand estimates.
Sensitivity analysis tested leonardite price volatility bands, fermentation technology cost curves, and carbon credit protocol adoption timelines across the projection horizon. Segmentation modeling spanned formulation chemistry, application intensity, and regional regulatory cluster dimensions. CAGRs derived from feedstock availability constraints, fertigation infrastructure deployment rates, and organic certification penetration curves.
Material uncertainties — EU Fertilizing Products Regulation enforcement timing, Alberta provincial permitting delays, and soil carbon credit verification standardization — sit outside the modeled envelope. Forecasts reflect assumptions around biotechnology substitution rates and digital procurement platform adoption. Recalibration cycles align with material shifts in regulatory classification and carbon accounting protocol development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Dioxolane Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
Chloroethylene Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Chlorinated Methane Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
Anthracene Market
Organic Chemicals
Phenol Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Global Benzoic Acid Market