
 Global Ketones Market | 2026-2036
Global Ketones Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ketones Market Foresight
Specialty chemical producers in Germany and the United States is pivoting toward bio-based ketone routes to reduce fossil feedstock exposure. Eastman Chemical Company leverages integrated acetyl chain infrastructure to sustain cost-advantaged methyl ethyl ketone supply across industrial solvent markets. Pruvit Ventures, Inc. anchors the exogenous ketone supplement segment with direct-to-consumer distribution, while HVMN Inc. differentiates through research partnerships targeting metabolic health applications.
Ketones are organic compounds characterized by a carbonyl group bonded to two carbon atoms, typically produced through dehydrogenation of secondary alcohols or oxidation of hydrocarbons, with boiling points and solvent power varying by carbon chain length and substitution pattern. They serve primarily as industrial solvents, chemical intermediates, and increasingly as nutritional supplements harnessing beta-hydroxybutyrate for energy metabolism. Acetone and methyl ethyl ketone dominate volume flows across coatings and adhesive applications where rapid evaporation rates command procurement priority. Pharmaceutical-grade ketones carry the strongest margin pools due to stringent USP and EP monograph compliance, while fermentation-derived ketones are gaining traction among cosmetic producers seeking renewable feedstock credentials.
EPA oversight of volatile organic compound emissions shapes ketone solvent formulation standards in the United States, while REACH registration requirements in Europe enforce full toxicological dossiers for cyclohexanone and benzophenone imports. China's SAMR implements GB standards for food-contact ketone residues, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions while positioning manufacturing assets to serve both industrial solvent and high-purity pharmaceutical grade demand streams.
Market Dynamics
Pharmaceutical manufacturers are intensifying demand for USP-grade ketones as active pharmaceutical ingredient synthesis expands, while EPA and REACH compliance costs simultaneously compress margins for commodity solvent producers.
Growth Catalysts
- Pharmaceutical API expansion:Specialty ketones serve as critical intermediates in corticosteroid and hormone synthesis, with CDSCO in India accelerating bulk drug park approvals.
- REACH registration completion:Full toxicological dossiers for cyclohexanone and methyl isobutyl ketone have clarified import pathways into European chemical manufacturing clusters.
- Bio-based fermentation routes:Engineered yeast strains now convert lignocellulosic feedstock into acetone and butanol, offering renewable credentials for cosmetic formulators.
Market Restraints
- Propylene feedstock volatility:Acetone and phenol production remains tethered to refinery propylene supply, exposing margins to crude oil price swings.
- Chinese supply concentration:Shandong and Jiangsu provinces control over half of global methyl ethyl ketone capacity, creating single-point vulnerability.
- Waterborne coating substitution:Low-VOC acrylic emulsions are displacing ketone-based lacquers in furniture and automotive refinish applications.
Strategic Opportunities
- Brazilian pharmaceutical manufacturing:ANVISA's streamlined GMP certification for imported ketone intermediates opens API synthesis outsourcing.
- Exogenous ketone supplements:Direct-to-consumer metabolic health products bypass traditional pharmaceutical distribution, capturing premium pricing.
- EU Green Deal biorefinery incentives:Fermentation-derived ketones qualify for carbon border adjustment exemptions and green public procurement preference.
Industry Challenges
- Pharmacopeial compliance timelines:USP and EP monograph testing for residual solvents extends batch release cycles by four to six weeks.
- Specialized chemical engineering talent:Dehydrogenation reactor design and safety management expertise concentrates among aging workforces in Germany and the United States.
- Legacy DCS integration:Continuous ketone plants require costly distributed control system upgrades to implement advanced process analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ketones Market |
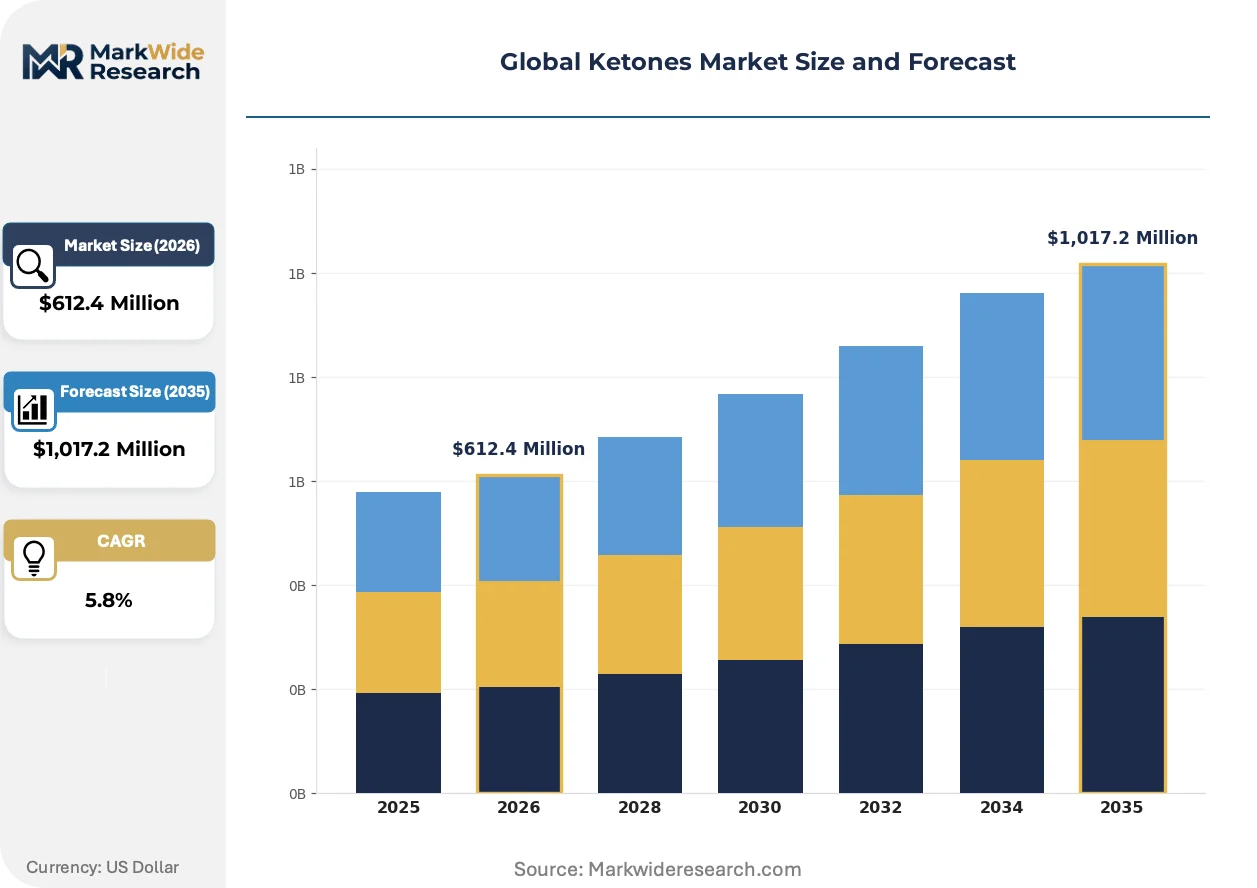
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetone, Methyl Ethyl Ketone, Cyclohexanone, Benzophenone, Mesityl Oxide, Others Application: Solvents, Pharmaceuticals, Food Additives, Fragrances, Plasticizers, Coatings End User Industry: Paints & Coatings Manufacturers, Pharmaceutical Firms, Food Processing Units, Cosmetic Producers, Adhesive Suppliers Manufacturing Process: Dehydrogenation, Oxidation, Hydrogenation, Fermentation, Distillation, Extraction |
| Companies Covered | Perfect Keto, HVMN Inc., Pruvit Ventures, Inc., Ketologic, Ketoneaid Inc., Eastman Chemical Company, Zenwise Health, Nutrex Research, Nestlé Health Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ketones Market Shifts & Advancements
Biotechnology-enabled production routes and tightening environmental compliance are fragmenting the traditional petrochemical ketone value chain into parallel specialty and commodity tracks.
Precision fermentation of ketone bodies is decentralizing supply geography by enabling distributed production near end-use pharmaceutical and nutraceutical facilities. Contract development and manufacturing organizations in the United States and Denmark are installing modular 50,000-liter bioreactors for on-demand beta-hydroxybutyrate supply. This distributed manufacturing model is compressing freight costs and customs exposure for high-purity pharmaceutical grades.
REACH authorization requirements for benzophenone and cyclohexanone derivatives are forcing reformulation across European adhesive and coating sectors. ECHA's 2023 sunset date extensions for specific uses have created temporary reprieve windows, but downstream formulators are accelerating solvent substitution programs. German automotive OEMs are now requiring suppliers to certify ketone-free interior coating systems to preempt future regulatory liability.
Direct-to-consumer distribution is disintermediating traditional nutraceutical wholesale channels for exogenous ketone supplements. Subscription-based replenishment models capture recurring revenue while bypassing pharmacy and mass retail slotting fees. This channel shift concentrates marketing spend on digital customer acquisition in North American and Australian metabolic health segments, where practitioner recommendation carries less purchase influence than in European markets.
Global Ketones Market Segmentation
Ketone specifications diverge sharply between commodity solvent grades and pharmacopeial-compliant variants, creating parallel procurement ecosystems with incompatible quality benchmarks. Manufacturers must position production assets against either high-volume industrial offtake or premium pharmaceutical intermediates.
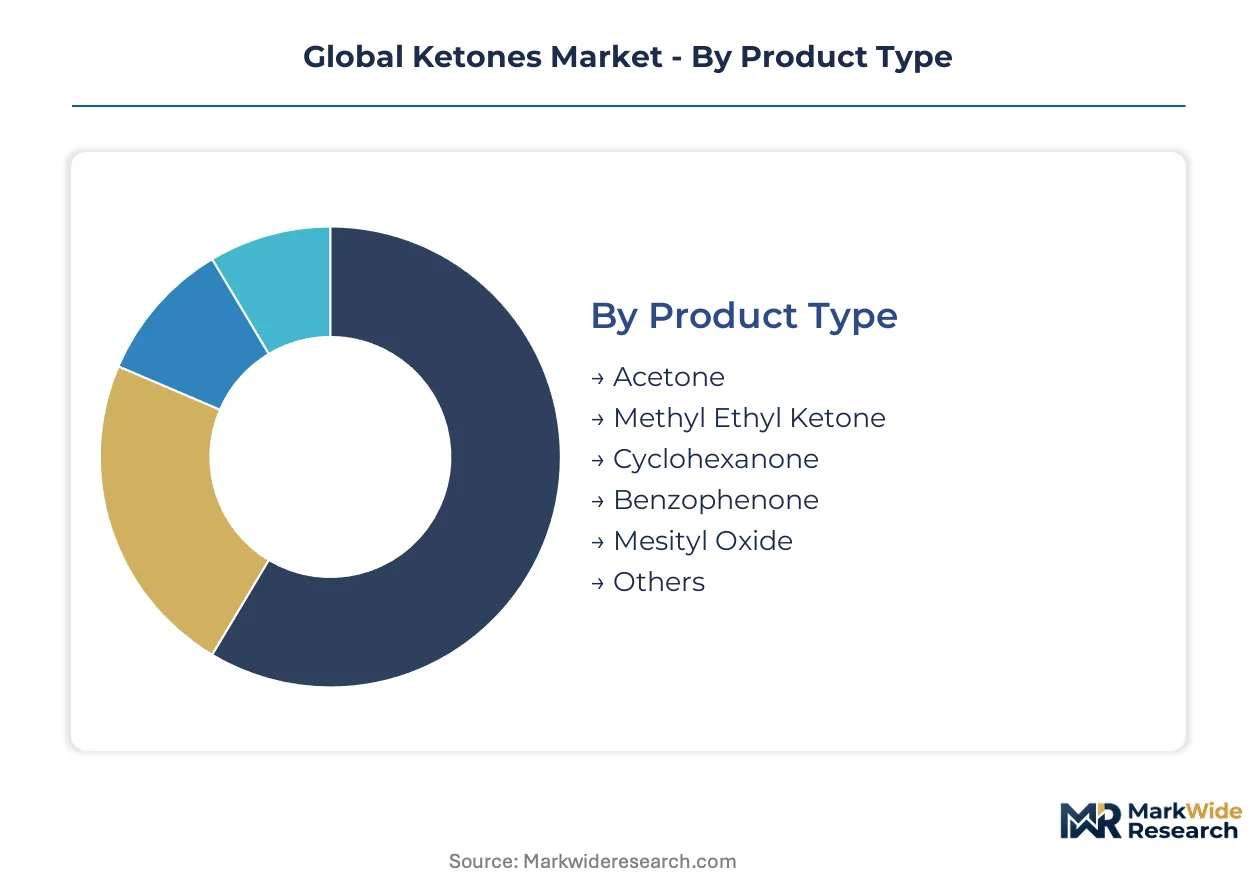
Product Type:
Carbon chain length and substitution patterns define evaporation rates, solvent power, and regulatory classification across the ketone family.
- Acetone:The simplest ketone with a three-carbon skeleton serves as the universal polar aprotic solvent for coatings and adhesive formulations. Demand concentrates in China and Germany where automotive refinish and furniture manufacturing clusters maintain steady offtake despite waterborne substitution pressure.
- Methyl Ethyl Ketone:This four-carbon ketone delivers intermediate evaporation rates prized in high-solids coating systems. Procurement from Shandong and Jiangsu provinces in China dominates global supply, creating vulnerability to regional logistics disruptions and export license fluctuations.
- Cyclohexanone:Six-membered ring structure enables nylon intermediate synthesis and specialty solvent applications.
- Benzophenone:Aromatic diaryl ketone functions as UV stabilizer and fragrance fixative in cosmetic formulations.
- Mesityl Oxide:Unsaturated ketone serves as solvent and chemical intermediate for methyl isobutyl ketone production.
- Others:Specialty ketones including diisobutyl ketone and methyl isobutyl ketone address niche extraction and dewaxing applications.
Mature deployment sits with Acetone across industrial solvent markets. Newer deployment is concentrated in Benzophenone as cosmetic formulators seek UV protection credentials.
Application:
End-use specifications range from technical purity for coatings to USP-grade for API synthesis, fragmenting supplier qualification requirements.
- Solvents:Ketones dissolve resins, oils, and cellulose derivatives across paint, adhesive, and extraction processes. Demand is concentrating in automotive OEM coating lines in Germany and the United States as manufacturers balance VOC compliance against drying speed requirements.
- Pharmaceuticals:USP-grade ketones function as reaction media and purification solvents for corticosteroid and hormone synthesis. CDSCO in India is accelerating bulk drug park approvals, expanding ketone intermediate demand for export-oriented API manufacturing.
- Food Additives:Trace ketone residues in flavoring compounds require SAMR compliance in China and FDA food-contact notifications.
- Fragrances:Benzophenone and ionone derivatives provide fixative and floral notes in fine perfumery.
- Plasticizers:Cyclohexanone derivatives modify polymer flexibility in PVC compounding.
- Coatings:Architectural and industrial finishes exploit ketone solvency for high-build film formation.
Established volume flows through Solvents. Steepest expansion trajectory is appearing in Pharmaceuticals as CDSCO and FDA filings multiply.
End User Industry:
Customer technical capabilities separate specification-tolerant commodity buyers from monograph-compliant pharmaceutical purchasers.
- Paints & Coatings Manufacturers:Formulators blend ketone solvents to balance flash point, evaporation curve, and resin compatibility. Procurement concentrates among German automotive OEM suppliers now certifying ketone-free interior systems to preempt REACH authorization liability.
- Pharmaceutical Firms:API synthesizers demand certificate-of-analysis documentation for every batch, extending release cycles. Contract development and manufacturing organizations in the United States and Denmark are installing modular bioreactors to compress supply chains for beta-hydroxybutyrate.
- Food Processing Units:Flavor houses require food-grade ketone derivatives with residue limits under GB standards in China.
- Cosmetic Producers:Formulators seek renewable ketone credentials through fermentation-derived routes for clean-label positioning.
- Adhesive Suppliers:Tape and label manufacturers exploit ketone solvency for pressure-sensitive adhesive compounding.
Concentrated buying power sits with Paints & Coatings Manufacturers. Emerging procurement sophistication is appearing among Cosmetic Producers.
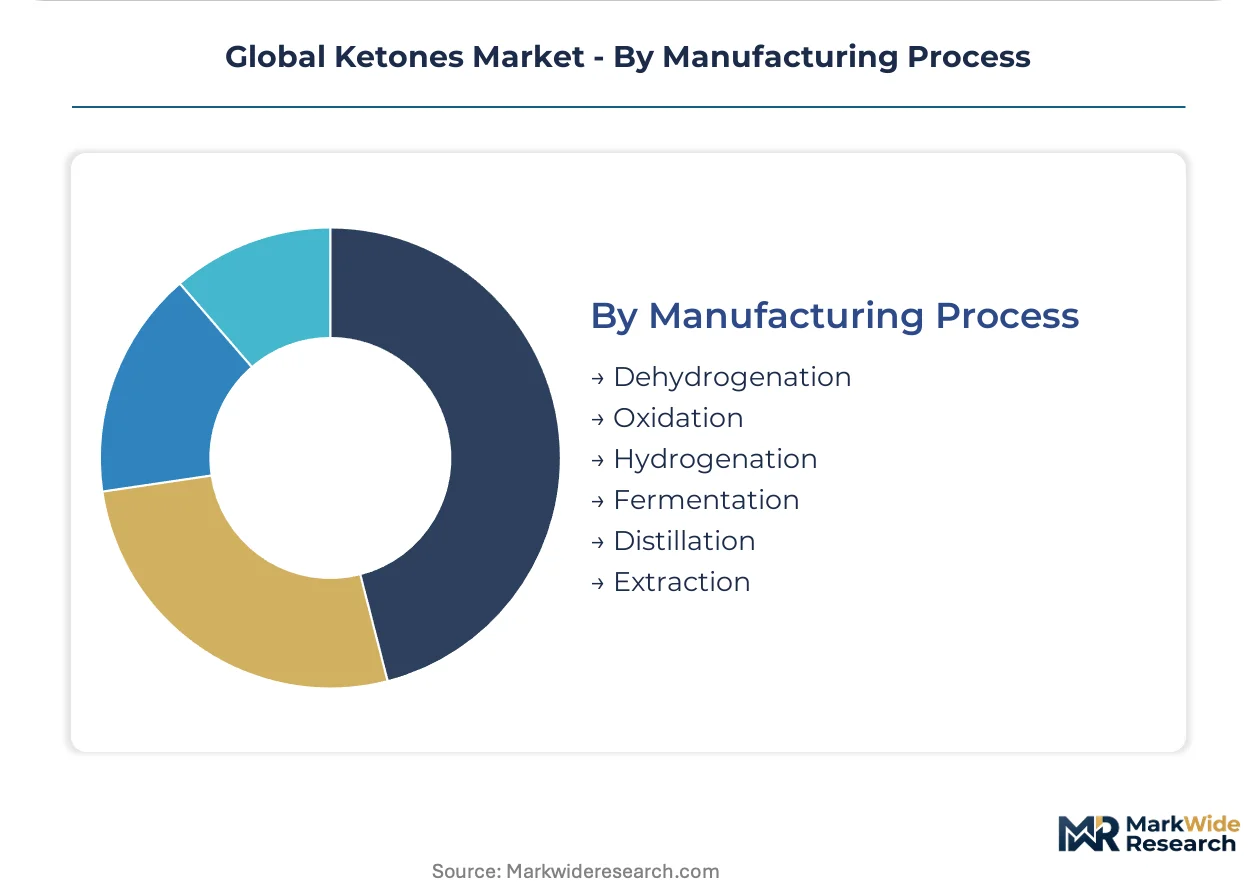
Manufacturing Process:
Process selection determines feedstock exposure, capital intensity, and carbon intensity credentials.
- Dehydrogenation:Secondary alcohol vapor-phase conversion over copper or zinc oxide catalysts dominates methyl ethyl ketone and cyclohexanone production. Reactor design expertise concentrates among aging workforces in Germany and the United States, constraining capacity expansion.
- Oxidation:Liquid-phase hydrocarbon oxidation with air or peroxides yields acetone and phenol co-products. Propylene feedstock volatility from refinery supply exposes margins to crude oil price swings.
- Hydrogenation:Selective reduction of unsaturated ketones produces saturated derivatives for specific solvent applications.
- Fermentation:Engineered yeast strains convert lignocellulosic biomass into acetone and butanol, qualifying for EU Green Deal biorefinery incentives and carbon border adjustment exemptions.
- Distillation:Purification separates ketone grades from reaction mixtures and byproduct streams.
- Extraction:Liquid-liquid separation recovers ketones from dilute aqueous streams in specialty applications.
Conventional deployment remains with Dehydrogenation and Oxidation. Fermentation is gaining share fastest among cosmetic and nutraceutical suppliers seeking renewable feedstock documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene feedstock availability in Shandong province anchors China's dominance in methyl ethyl ketone output. German chemical clusters leverage integrated acetyl chains for acetone derivatives. Indian bulk drug parks expand pharmaceutical-grade ketone demand.
China
Shandong and Jiangsu provinces control over half of global methyl ethyl ketone capacity, creating concentrated supply vulnerability. SAMR implements GB standards for food-contact ketone residues, tightening purity benchmarks for export-oriented manufacturers. Qingdao and Nanjing chemical parks expand specialty solvent output for coatings and adhesive applications.
Germany
REACH registration requirements enforce full toxicological dossiers for cyclohexanone and benzophenone imports. ECHA's 2023 sunset date extensions for specific uses created temporary reprieve windows for downstream formulators. Leverkusen and Ludwigshafen chemical clusters pivot toward bio-based ketone routes to reduce fossil feedstock exposure.
United States
EPA oversight of volatile organic compound emissions shapes ketone solvent formulation standards across industrial applications. FDA guidance on food-grade ketones tightens purity benchmarks for nutritional supplement applications. Texas and Louisiana Gulf Coast refineries supply propylene feedstock for acetone and phenol co-production.
India
CDSCO accelerates bulk drug park approvals, expanding ketone intermediate demand for export-oriented API manufacturing. Pharmaceutical manufacturers intensify demand for USP-grade ketones as corticosteroid and hormone synthesis expands. Hyderabad and Ahmedabad chemical corridors deepen specialty solvent procurement for contract research organizations.
Brazil
ANVISA streamlined GMP certification for imported ketone intermediates, opening API synthesis outsourcing opportunities. Pharmaceutical manufacturing clusters in São Paulo and Rio de Janeiro states expand procurement of USP-grade solvents. Local formulators seek fermentation-derived ketone credentials for cosmetic clean-label positioning.
Global Ketones Market Competitive Landscape
Global majors compete with regional champions across integrated petrochemical infrastructure versus specialized nutraceutical distribution. The vendor base separates into three tiers: multinational chemical conglomerates with acetyl chain integration, direct-to-consumer supplement specialists, and contract fermentation providers. Strategic moves center on backward integration into bio-based feedstock supply and geographic expansion into pharmaceutical manufacturing corridors.
Within the industrial solvent tier, Eastman Chemical Company exemplifies integrated acetyl chain operators. Among exogenous ketone supplement specialists, Pruvit Ventures, Inc. and HVMN Inc. occupy positions reflecting divergent channel strategies—direct-to-consumer distribution versus research partnership positioning. These three anchors illustrate the market's bifurcation between commodity chemical scale and premium nutraceutical branding.
| Leading Market Players |
|---|
| Perfect Keto |
| HVMN Inc. |
| Pruvit Ventures, Inc. |
| Ketologic |
| Ketoneaid Inc. |
| Eastman Chemical Company |
| Zenwise Health |
| Nutrex Research |
| Nestlé Health Science |
| Others |
Supply & Pricing Matrix
Captive acetyl chain integration at Eastman Chemical and comparable multinationals anchors both supply security and pricing power across industrial ketone grades. This backward control over propylene feedstock and intermediate chemistry insulates margin structures from crude volatility while enabling certificate-of-analysis documentation that pharmaceutical buyers demand.
Pricing Analysis
Certificate-of-analysis bundling separates USP-grade pharmaceutical ketones from unbundled technical solvent grades, with testing documentation commanding 15-25% premiums. Three-tier pricing structure across pharmaceutical, food-grade, and industrial solvent levels reflects compliance burden divergence. Cost compression in commodity acetone and methyl ethyl ketone is intensifying because Shandong capacity expansions outpace coatings demand growth. Contract research organizations and API manufacturers show lowest price sensitivity due to batch release liability, while furniture coating formulators face acute substitution pressure from waterborne acrylics.
Supply Chain Analysis
Aging dehydrogenation reactor expertise in Germany and the United States constrains capacity expansion timelines and maintenance scheduling flexibility. Manufacturing gravity centers on China for methyl ethyl ketone, Germany for acetone derivatives, and India for pharmaceutical-grade output. Feedstock exposure draws from refinery propylene supply, lignocellulosic biomass for fermentation routes, and phenol co-production economics. Single-source vulnerability concentrates in Shandong and Jiangsu provinces where export license fluctuations disrupt spot availability. Distribution runs through integrated chemical distributors for industrial grades and direct pharmaceutical procurement channels for USP monograph compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines and EPA VOC enforcement are compressing weaker commodity solvent players into distressed exit scenarios. Consolidation pressure favors integrated operators with captive feedstock positions and pharmacopeial certification capabilities.
For Market Incumbents: Cement acetyl chain control through selective phenol-ketone co-production investments in Texas and Louisiana Gulf Coast corridors. Prioritize USP and EP monograph testing infrastructure to capture corticosteroid synthesis demand from CDSCO-registered Indian bulk drug parks. Waterborne coating substitution and benzophenone REACH sunset dates threaten legacy solvent volumes. For New Entrants and Emerging Players: Contract fermentation buyers in Danish and North American cosmetic corridors represent underserved procurement sophistication seeking renewable ketone credentials. Modular bioreactor deployment for beta-hydroxybutyrate supply to pharmaceutical CDMOs offers lowest competitive density. Direct-to-consumer subscription models bypass pharmacy slotting fees and capture recurring metabolic health revenue. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated chemical conglomerates seeking bio-based route capabilities and pharmacopeial grade positioning. Five-to-ten year viability hinges on carbon border adjustment alignment and fermentation yield economics. Monitor EU Green Deal biorefinery incentive allocation rates as inflection signal for renewable ketone cost parity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstock Supply | Fermentation-derived acetone qualifies for EU carbon border adjustment exemptions. |
| USP Monograph Testing Infrastructure Investment | Certificate-of-analysis documentation extends batch release cycles but captures pharmaceutical margin pools. |
| Modular Bioreactor Deployment for Pharmaceutical CDMOs | Distributed beta-hydroxybutyrate production compresses freight costs and customs exposure. |
| Direct-to-Consumer Subscription Channel Development | Digital customer acquisition bypasses pharmacy and mass retail slotting fees. |
| Ketone-free Interior Coating Certification Program | German automotive OEM supplier requirements preempt future REACH authorization liability. |
Research Methodology
Document review covered FDA food-contact guidance, ECHA REACH registration dossiers, and CDSCO bulk drug park approval records, complemented by interviews with plant managers at Shandong and Jiangsu chemical parks, procurement leads at German automotive OEM coating suppliers, regulatory affairs specialists at exogenous ketone supplement distributors, and technical R&D directors at fermentation technology providers. Secondary validation drew from customs trade data, SEC 10-K filings of integrated chemical operators, and SAMR GB standard publications. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic scenario testing.
Segment-level volume and value trajectories across the projection horizon reflect discrete modeling of pharmaceutical-grade, food-grade, and industrial solvent tiers. Analytical framework incorporated carbon chain length, substitution pattern, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand forecasting and capacity utilization sensitivity analysis. Industry-specific inputs included propylene feedstock price scenarios, fermentation yield improvement curves, and REACH authorization sunset date compliance cost estimates.
Revisions become necessary when ECHA authorization timelines accelerate, EPA VOC thresholds tighten, or CDSCO bulk drug park approval rates deviate from baseline assumptions. Forecasts reflect documented regulatory trajectories and disclosed capacity expansion plans. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Asia-Pacific Organic Acid Market
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
US Humate Market
Organic Chemicals
Cyclic Ketones Market