
 Digital Manufacturing Software Market | 2026-2036
Digital Manufacturing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Manufacturing Software Market Analysis
Aftermarket service revenue is rewriting how software vendors capture lifetime value from industrial clients. Siemens leverages its digital twin portfolio to anchor long-term maintenance contracts across automotive and aerospace accounts. PTC sustains differentiation through its IoT integration layer that connects field assets to engineering design environments. Autodesk competes on accessibility, extending cloud-native CAD tools to mid-market machinery builders that previously lacked enterprise-grade digital infrastructure.
Digital manufacturing software encompasses computer-aided design, manufacturing execution systems, product lifecycle management, and cloud-based solutions that orchestrate physical production through digital models, typically operating via real-time data exchange protocols with sub-second latency requirements for closed-loop process control. Its primary purpose is to eliminate information latency between engineering design, production scheduling, and shop-floor execution. Manufacturing execution systems currently occupy the largest margin pool as they sit at the convergence of operational technology and enterprise IT, creating vendor stickiness through deep system integration. Cloud-based solutions represent the fastest-expanding segment as heavy machinery and electronics manufacturers migrate from capital-intensive on-premises deployments to subscription models that reduce upfront implementation risk.
The EU AI Act and FDA's software-as-a-medical-device framework are tightening validation requirements for AI-enabled manufacturing software, forcing vendors to build audit trails and explainability into machine learning modules that optimize production parameters. Germany's KBA and Japan's METI are extending automotive cybersecurity standards into manufacturing software supply chains, creating compliance barriers for non-integrated point solutions. Stakeholders must evaluate whether their current platform architecture can absorb emerging regulatory mandates without fragmenting into incompatible compliance modules.
Market Dynamics
Automotive OEMs in Germany are compressing their digital twin deployment timelines from multi-year waterfall implementations to agile rollouts across supplier tiers, forcing software vendors to re-architect integration protocols for faster time-to-value.
Growth Catalysts
- EU AI Act compliance mandates:Manufacturers must embed explainability into AI-driven process optimization tools, creating pull for validated software platforms that pre-integrate audit trails.
- Real-time quality synchronization:Automotive production lines now require sub-second latency between MES and shop-floor sensors to enable closed-loop defect correction before value-add processing.
- German supplier network density:Tier-1 and Tier-2 component manufacturers cluster around Stuttgart and Munich, creating concentrated demand for interoperable digital infrastructure.
Market Restraints
- Legacy OT-IT integration costs:Brownfield factories require expensive protocol translation layers to connect decades-old programmable logic controllers with cloud-native MES platforms.
- Semiconductor supply volatility:Persistent shortages of industrial-grade edge computing chips delay hardware refreshes needed to run advanced simulation workloads.
- Cybersecurity certification fragmentation:Japan's METI and Germany's KBA impose diverging automotive cybersecurity standards, forcing vendors to maintain parallel compliance tracks.
Strategic Opportunities
- Mid-market machinery builders:European metalworking and packaging equipment manufacturers previously excluded from enterprise digitalization now access cloud-native CAD through subscription tiers.
- AI-enabled predictive maintenance:Convergence of physics-based simulation with machine learning anomaly detection opens recurring revenue streams anchored to uptime guarantees.
- FDA software-as-medical-device pathway:Manufacturers of diagnostic equipment and implantable devices must validate digital thread traceability, creating specialized demand for compliant PLM modules.
Industry Challenges
- Cross-functional talent scarcity:Organizations struggle to hire engineers fluent in both operational technology protocols and cloud software architecture.
- Multi-year certification timelines:Medical device and aerospace software validation cycles extend 18-36 months, compressing vendor R&D amortization windows.
- Interoperability standard delays:Competing digital twin data formats from industry consortia fragment integration roadmaps and inflate customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Manufacturing Software Market |
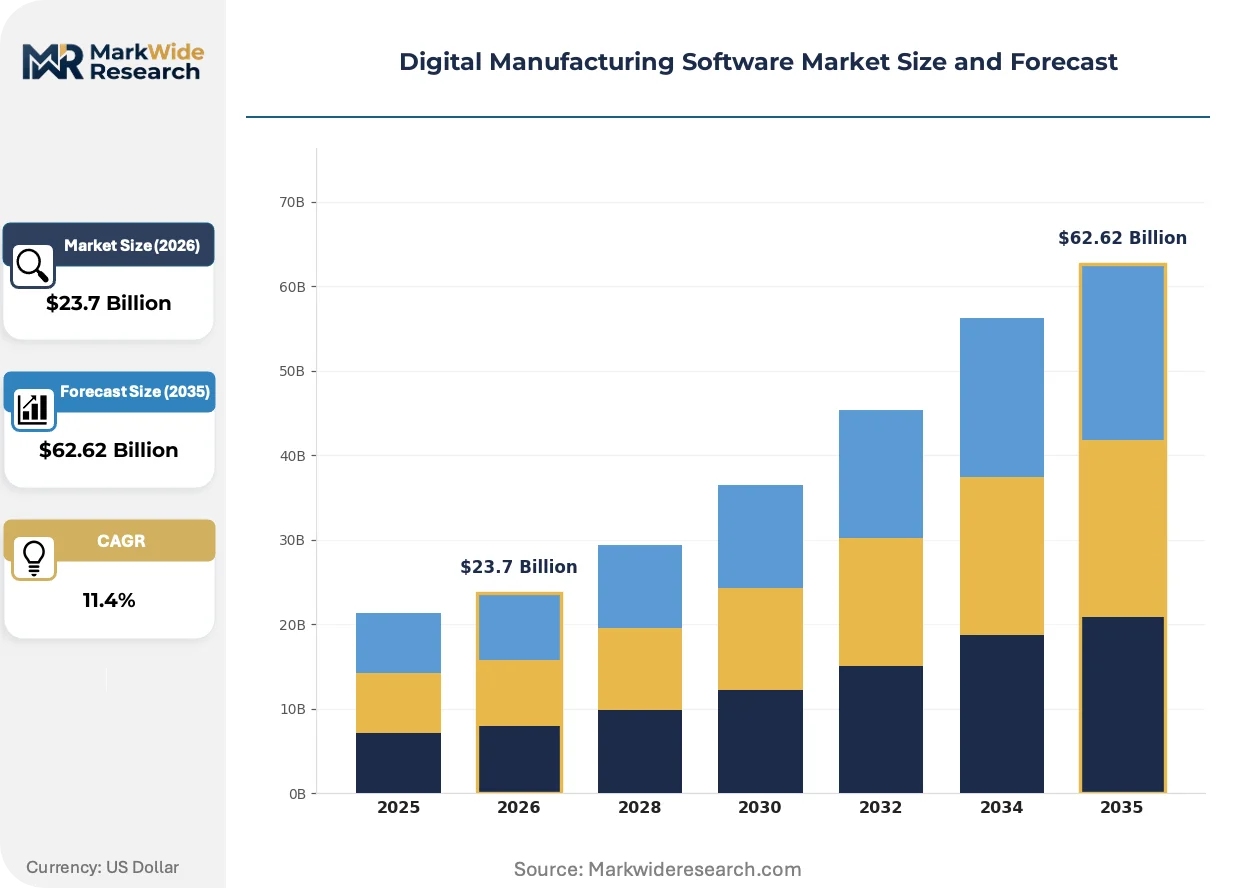
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computer-Aided Design, Manufacturing Execution Systems, Product Lifecycle Management, Cloud-Based Solutions Technology: IoT Integration, Artificial Intelligence, Machine Learning, Robotics End User: Aerospace, Automotive Manufacturers, Electronics, Heavy Machinery Deployment: On-Premises, SaaS, Hybrid, Others |
| Companies Covered | Siemens, PTC, Dassault Systemes, Autodesk, Rockwell Automation, SAP, Hexagon, Ansys, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Manufacturing Software Market Emerging Trajectories
Software architectures are pivoting from monolithic enterprise suites to composable microservices that let manufacturers activate specific capabilities without full-platform commitments.
Digital twin technology is virtualizing physical production assets into persistent simulation environments that mirror real-time equipment behavior. Automotive OEMs in Germany deploy these models across battery cell assembly and powertrain machining lines. Siemens and PTC are compressing commissioning timelines by validating process parameters in virtual environments before physical line startup.
The EU AI Act is mandating algorithmic transparency for AI-enabled process optimization tools used in safety-critical manufacturing. Vendors must now document training data provenance and decision pathways for regulatory inspection. German automotive suppliers are prioritizing platforms with pre-built explainability modules to accelerate compliance certification.
Aftermarket service contracts are unbundling from initial software licenses as manufacturers seek outcome-based relationships tied to production uptime. Heavy machinery builders in Japan and aerospace MRO providers in France now procure digital manufacturing capabilities through performance-guaranteed subscriptions. This shift concentrates vendor risk while extending customer lifetime value capture.
Digital Manufacturing Software Market Segmentation
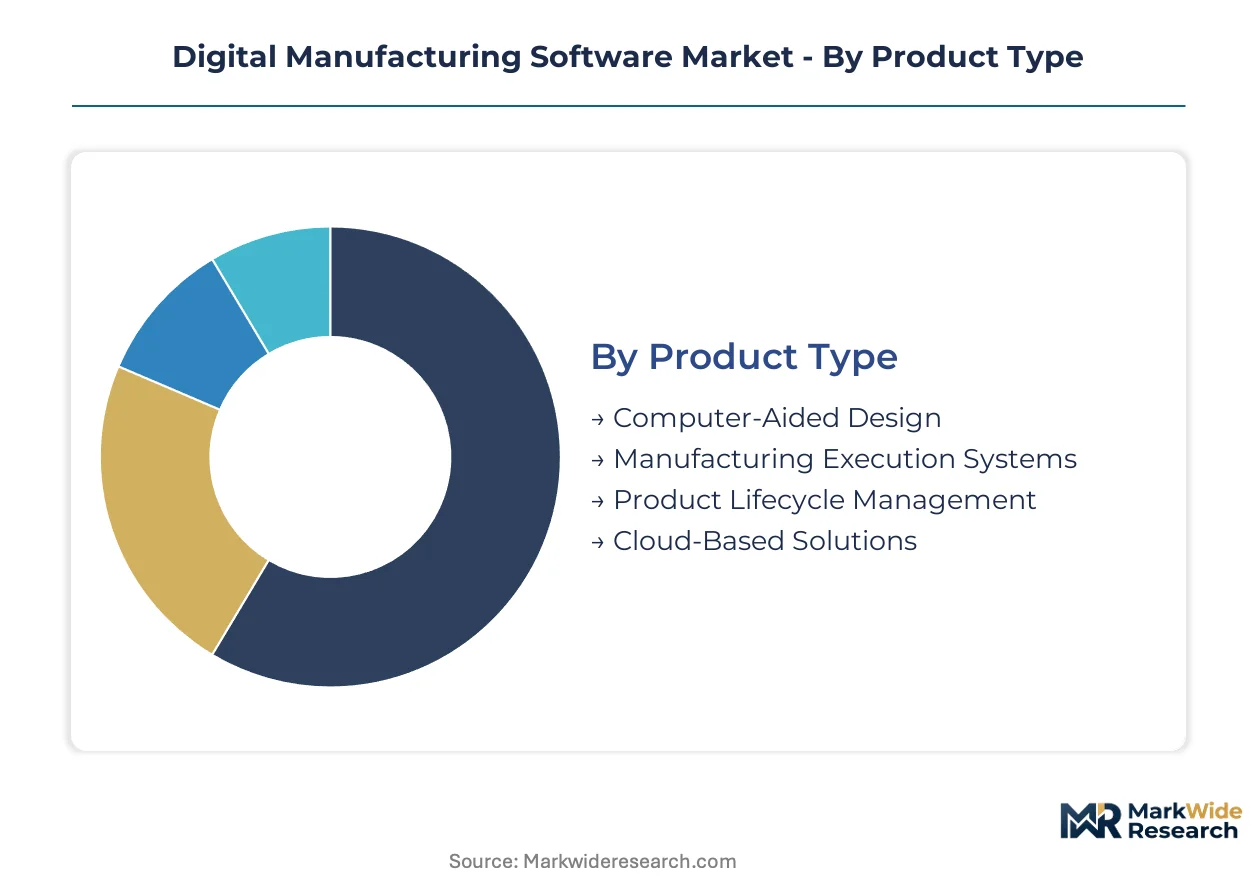
Segmentation in digital manufacturing software determines how vendors allocate R&D resources across fundamentally different sales cycles. Product types range from perpetual-license CAD tools with decade-long refresh intervals to cloud-native MES platforms renewing annually. Technology layers impose distinct latency requirements, while deployment models dictate customer acquisition economics and support infrastructure.
Product Type:
Cycle times diverge sharply across product categories, with cloud solutions refreshing quarterly while on-premise PLM deployments span multi-year horizons.
- Computer-Aided Design:Desktop and cloud-native design environments enable geometric modeling, simulation preprocessing, and generative design workflows. Demand concentrates among mid-market machinery builders in Germany adopting subscription tiers to replace legacy perpetual licenses.
- Manufacturing Execution Systems:Shop-floor orchestration platforms synchronize production scheduling, quality data, and inventory tracking through real-time OT-IT integration. Automotive OEMs in Stuttgart and Munich drive deployment as they compress supplier tier rollouts from waterfall to agile implementations.
- Product Lifecycle Management:Centralized data vaults manage engineering revisions, BOM hierarchies, and regulatory documentation across extended supply chains. FDA software-as-medical-device pathways force diagnostic equipment manufacturers to validate digital thread traceability.
- Cloud-Based Solutions:Browser-hosted manufacturing applications eliminate on-premise infrastructure requirements. Heavy machinery and electronics manufacturers migrate from capital-intensive deployments to reduce upfront implementation risk.
Manufacturing Execution Systems anchors the volume base while Cloud-Based Solutions gains share at the steepest rate.
Technology:
Technology layers stratify by integration complexity, with IoT protocols requiring extensive edge hardware deployment while machine learning modules demand continuous model retraining infrastructure.
- IoT Integration:Sensor-to-cloud data pipelines connect field assets to engineering environments through industrial protocols. PTC sustains differentiation through proprietary connectivity layers linking shop-floor equipment to design systems.
- Artificial Intelligence:Algorithmic process optimization tools adjust production parameters based on real-time quality feedback. EU AI Act mandates force explainability module integration for safety-critical manufacturing applications.
- Machine Learning:Pattern recognition systems detect equipment anomalies and predict maintenance windows from operational telemetry. Physics-based simulation convergence creates recurring revenue streams anchored to uptime guarantees.
- Robotics:Motion planning and collision avoidance software orchestrates autonomous material handling and assembly operations. Automotive battery cell assembly lines in Germany deploy these capabilities for precision welding and component placement.
IoT Integration captures the largest installed base while Machine Learning expands most quickly through predictive maintenance attach rates.
End User:
End-use concentration varies by regulatory intensity, with aerospace and medical device manufacturers imposing 18-36 month validation cycles while automotive accelerates deployment timelines.
- Aerospace:Airframe and propulsion system manufacturers require traceable digital threads for certification compliance. Multi-year software validation timelines compress vendor R&D amortization windows.
- Automotive Manufacturers:OEMs and Tier-1 suppliers synchronize global production networks through digital twin platforms. German automotive OEMs compress deployment timelines across supplier tiers.
- Electronics:Semiconductor and consumer device producers manage high-mix, high-volume manufacturing with rapid product transitions. Cloud migration reduces capital intensity for capital-constrained operations.
- Heavy Machinery:Construction and mining equipment builders pursue outcome-based service contracts tied to production uptime. Japanese manufacturers procure capabilities through performance-guaranteed subscriptions.
Automotive Manufacturers dominate current procurement volume while Heavy Machinery shows the steepest expansion trajectory through aftermarket service unbundling.
Deployment:
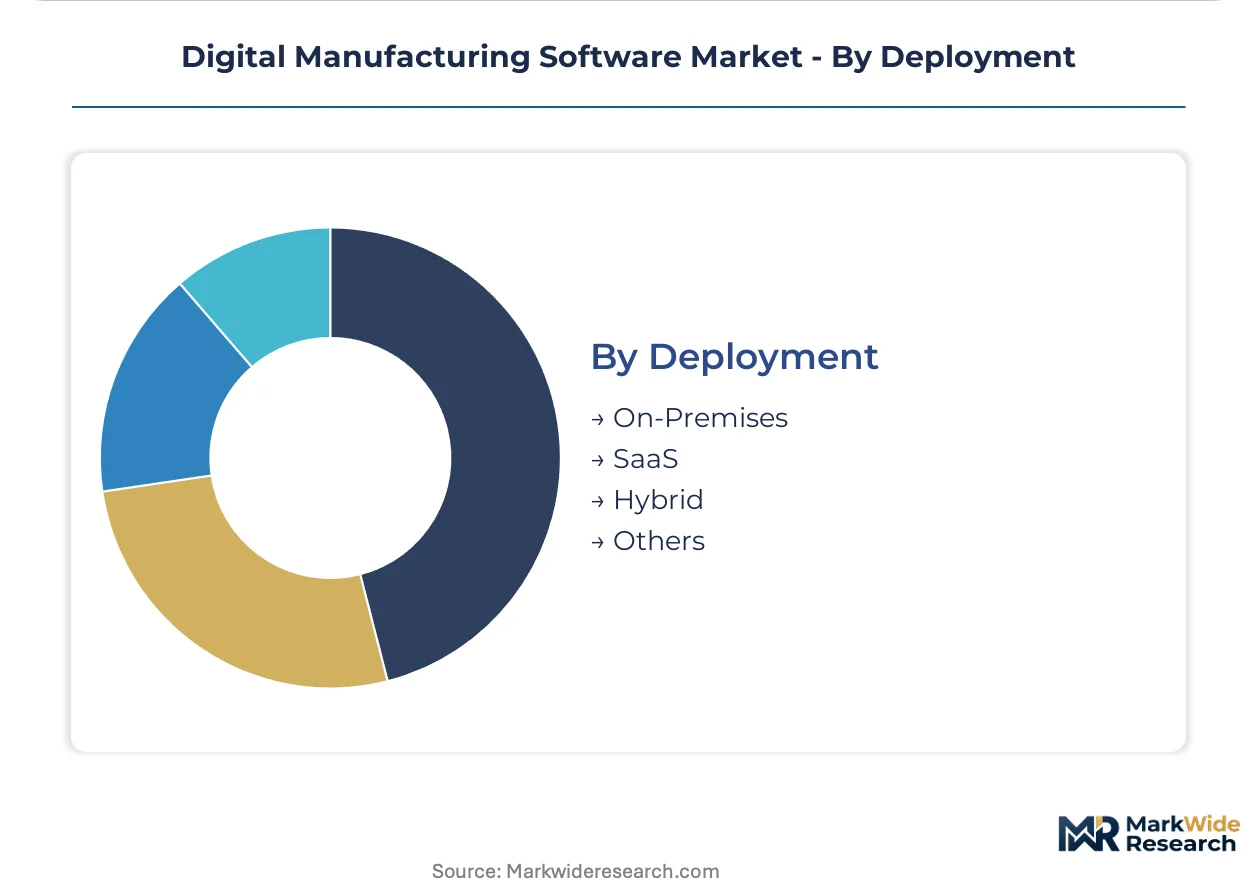
Deployment economics separate by customer IT maturity, with hybrid architectures bridging air-gapped legacy systems and cloud-native workloads.
- On-Premises:Self-hosted installations maintain data sovereignty and customize integration with legacy OT infrastructure. Brownfield factories require expensive protocol translation layers for PLC connectivity.
- SaaS:Multi-tenant cloud deliveries reduce implementation risk through subscription pricing and automatic updates. Mid-market machinery builders previously excluded from enterprise digitalization now access equivalent capabilities.
- Hybrid:Split architectures retain sensitive design data on-premise while pushing analytics workloads to cloud infrastructure. Germany's KBA automotive cybersecurity standards complicate cross-border data flow architectures.
- Others:Edge-deployed and private cloud configurations serve specialized latency or compliance requirements. Industrial-grade edge computing chip shortages delay hardware refreshes needed for advanced simulation.
On-Premises retains the largest legacy footprint while SaaS climbs the fastest as subscription models displace perpetual licenses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and their supplier networks concentrate procurement of digital manufacturing software, though deployment patterns diverge across regulatory environments and industrial clusters in the United States, Japan, China, and France.
United States
FDA software-as-medical-device pathways drive validation requirements for diagnostic equipment manufacturers. The IRA manufacturing incentives accelerate domestic semiconductor fabrication facility construction. Austin and Phoenix clusters host new fab projects deploying integrated digital twin platforms for process qualification.
Germany
Automotive OEMs compress digital twin deployment timelines across Tier-1 and Tier-2 supplier networks. The EU AI Act mandates explainability modules for AI-enabled process optimization tools. Stuttgart and Munich industrial corridors concentrate demand for interoperable MES platforms with sub-second latency capabilities.
Japan
Heavy machinery builders pursue outcome-based service contracts tied to production uptime guarantees. METI automotive cybersecurity standards extend into manufacturing software supply chains. Nagoya and Osaka manufacturing belts deploy predictive maintenance modules anchored to physics-based simulation convergence.
China
Domestic battery cell assembly lines drive demand for robotics motion planning and collision avoidance software. MIIT industrial internet initiatives promote cloud-native MES adoption among mid-market electronics manufacturers. Shenzhen and Shanghai clusters lead migration from capital-intensive on-premise deployments to subscription models.
France
Aerospace MRO providers procure digital manufacturing capabilities through performance-guaranteed subscriptions. ANSM and CNIL data governance requirements complicate cross-border digital thread architectures. Toulouse and Paris-Saclay aerospace clusters impose 18-36 month software validation cycles for airframe digital thread traceability.
Digital Manufacturing Software Market Vendor Landscape
Industrial conglomerates and pure-play software vendors split the market between integrated platform ecosystems and specialized connectivity layers. Siemens anchors the conglomerate archetype with deep OT-IT integration capabilities spanning digital twins and automation hardware. PTC occupies the connectivity specialist position through proprietary IoT integration layers. Autodesk exemplifies the cloud-native accessibility play targeting mid-market machinery builders previously excluded from enterprise digital infrastructure. Competitive moves concentrate on strategic partnerships with semiconductor equipment vendors and portfolio diversification into AI-enabled predictive maintenance modules.
Within the integrated platform tier, Siemens and Dassault Systemes represent conglomerate-backed vendors leveraging decades of industrial automation heritage. PTC anchors the connectivity specialist archetype with field asset-to-engineering linkages. Autodesk occupies the cloud-native accessibility position, extending browser-hosted CAD tools to European metalworking and packaging equipment manufacturers through subscription tiers that reduce upfront implementation risk.
| Leading Market Players |
|---|
| Siemens |
| PTC |
| Dassault Systemes |
| Autodesk |
| Rockwell Automation |
| SAP |
| Hexagon |
| Ansys |
| Oracle |
| Others |
Supply Flow & Price Mechanics
Stuttgart's automotive supplier corridor concentrates MES platform capacity, and this geographic density amplifies pricing power for vendors with pre-integrated EU AI Act compliance modules. Tier-1 manufacturers in this cluster face compressed negotiation leverage when sourcing validated digital infrastructure.
Pricing Analysis
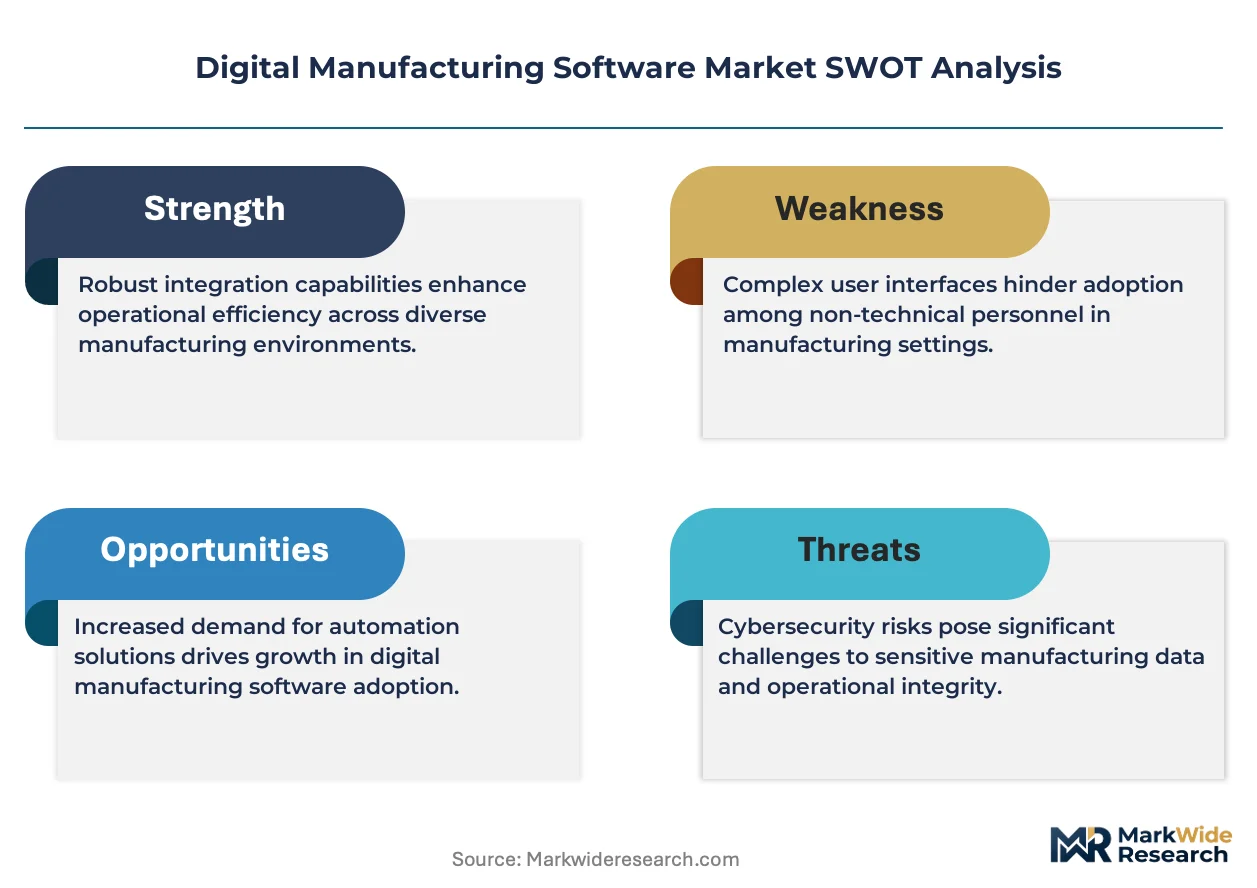
Aftermarket service contracts now drive lifetime value capture, with subscription renewals and uptime-guaranteed maintenance agreements outpacing initial license revenue. Three-tier pricing structure across premium, standard, and economy levels separates enterprise digital twin suites from mid-market SaaS tiers and entry-level CAD subscriptions. Price differentiation rests on certification depth, with FDA-validated PLM modules and KBA-compliant cybersecurity stacks commanding substantial premiums over uncertified alternatives. Pricing pressure stems from cloud-native entrants undercutting perpetual-license incumbents in the mid-market machinery segment. Japanese heavy equipment manufacturers exhibit lowest price sensitivity due to outcome-based procurement models, while European metalworking SMEs face acute budget constraints.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Jabil, and Flex holding substantial industrial edge computing assembly capacity across Taiwan, Mexico, and China. Software supply draws from semiconductor fabrication in Taiwan and South Korea, industrial sensor production in Germany and Japan, and cloud infrastructure concentrated in US and European hyperscale regions. Supply chain risk centers on persistent shortages of industrial-grade edge computing chips that delay hardware refreshes for simulation workloads. Distribution runs through direct enterprise sales teams for large automotive OEMs, supplemented by systems integrator partnerships for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a platform-economics inflection where composable microservices architectures displace monolithic suites, driven by the OPC UA over TSN interoperability push enabling plug-and-play module integration.
For Market Incumbents: Build switching-cost moats through deeper OT-IT protocol integration that embeds vendor technology into brownfield automation infrastructure. Siemens and Dassault Systemes should accelerate pre-certification of AI explainability modules against EU AI Act requirements before smaller competitors achieve validation. Capacity addition in Stuttgart and Munich supplier corridors will anchor regional support density. Certification investment in FDA software-as-medical-device pathways opens defensive positioning against cloud-native PLM entrants targeting diagnostic equipment manufacturers. For New Entrants and Emerging Players: French aerospace MRO providers present underpenetrated demand for performance-guaranteed digital manufacturing subscriptions, with validation timelines currently excluding most SaaS vendors. Mid-market packaging equipment manufacturers in Northern Italy lack accessible cloud-native MES options, creating white-space for browser-hosted platforms with reduced implementation risk. A channel partnership strategy with regional systems integrators accelerates credibility without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounding play because subscription migration in industrial software extends customer lifetime value while concentrating vendor risk on uptime outcomes. Acquisition targets should display vertical-specific AI module development, particularly in predictive maintenance anchored to physics-based simulation. The signal to watch is Tier-1 automotive supplier consolidation of point solutions into preferred vendor platforms, which would accelerate mid-market acquisition activity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies MES, PLM, and digital twin modules through OPC UA over TSN protocols for German automotive OEMs. |
| Strategic Partnership | Aligns software vendors with semiconductor equipment manufacturers for co-validated process qualification workflows. |
| Acquisition of Specialist Firm | Absorbs AI explainability startups to accelerate EU AI Act compliance certification for safety-critical manufacturing. |
| Geographic Expansion | Establishes localized support infrastructure in Stuttgart and Munich corridors for compressed supplier tier rollouts. |
| Product Launch | Introduces pre-certified FDA software-as-medical-device PLM modules for diagnostic equipment manufacturers. |
Methodological Framework
The analysis maps CAD, MES, PLM, and cloud-native solution sub-sectors, each validated through CTOs, plant engineers, OEM procurement teams, and aftermarket service heads at industrial manufacturers. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, and vehicle production databases. Bottom-up and top-down triangulation reconciles vendor-reported bookings with end-user deployment tracking.
Assumption sets held regulatory timelines fixed while varying cloud migration velocity and semiconductor supply recovery patterns across the modeling period. Segmentation dimensions include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derive from installed base evolution and annual recurring revenue expansion rates, with AI module attach rates and predictive maintenance contract penetration as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native entrants or accelerated EU AI Act enforcement would shift outcomes. Specific risk factors include cybersecurity certification fragmentation between Japan's METI and Germany's KBA, and interoperability standard delays from competing digital twin consortia. Quarterly review of Tier-1 automotive supplier platform consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Global Automatic Content Recognition (ACR) Market
Digital Solutions
Marketing Automation Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Transit Station Display Board Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Global Recommendation Search Engine Market
Digital Solutions
Core Graphics Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
North America Digital Signage Market