
 Procure-To-Pay Solutions Market | 2026-2036
Procure-To-Pay Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Procure-To-Pay Solutions Market Outlook
Mid-market enterprises are reorganizing their procurement technology stacks, displacing legacy ERP modules with dedicated Procure-To-Pay suites. SAP Ariba leverages its network effect across indirect spend categories to sustain enterprise retention. Coupa dominates North American mid-market penetration with configurable workflow engines. GEP SMART anchors complex direct-material procurement for manufacturing clients through AI-powered sourcing optimization.
Procure-To-Pay Solutions encompass software platforms that automate the complete procurement lifecycle from requisition through vendor payment, typically integrating e-sourcing, contract management, invoice matching, and treasury settlement through API-connected cloud architectures. The primary commercial purpose centers on reducing maverick spend, enforcing compliance guardrails, and accelerating cash-flow cycles across decentralized buying organizations. Cloud-Based deployment leads absolute revenue contribution as IT departments retire on-premise maintenance burdens, while Invoice Management captures disproportionate margin pools due to OCR-to-ERP reconciliation complexity. Supplier Management represents the fastest-growing segment as ESG due diligence and dual-source mandates expand vendor master data requirements.
ISO 27001 certification shapes vendor selection criteria for European buyers under GDPR data residency requirements, while the EU AI Act imposes algorithmic transparency obligations on automated procurement recommendations. US federal contractors face DFARS cybersecurity mandates that restrict cloud deployment options for defense-adjacent supply chains. Stakeholders must monitor evolving e-invoicing mandates from tax authorities in Brazil, Italy, and Saudi Arabia, where real-time reporting requirements are forcing platform interoperability investments.
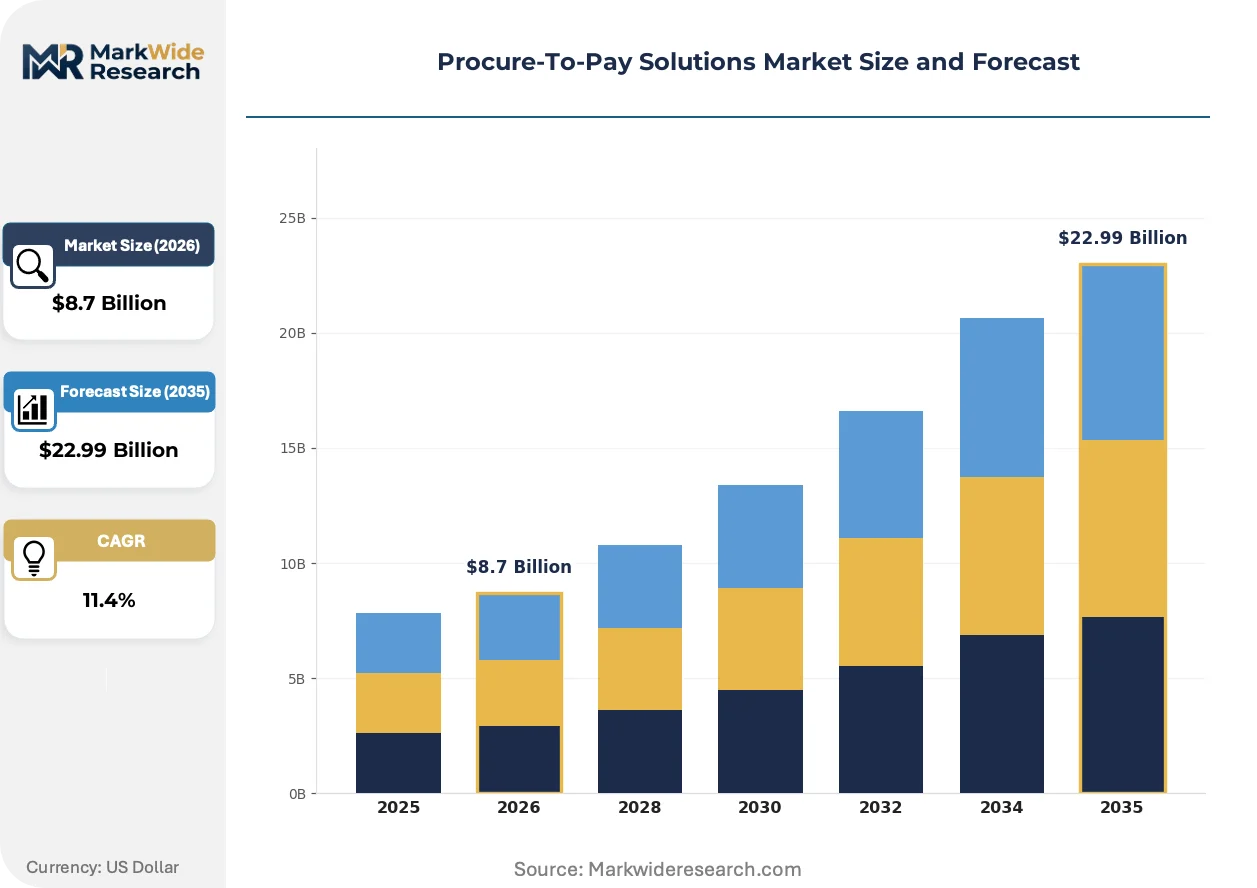
Market Dynamics
Cloud-native architectures are decomposing monolithic ERP procurement modules into API-orchestrated microservices, forcing buyers to re-evaluate integration taxonomies and data residency protocols across distributed supplier networks.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated procurement recommendation engines now require auditable decision trails, accelerating replacement of black-box legacy systems with explainable AI platforms in German industrial manufacturing.
- E-invoicing real-time reporting requirements:Brazil's Nota Fiscal Eletrônica and Italy's SDI mandates force platform interoperability investments, creating pull-through demand for unified Procure-To-Pay suites with native tax authority connectivity.
- Mid-market cloud migration urgency:IT departments at North American distributors with 500-5,000 employees are retiring on-premise maintenance burdens, prioritizing SaaS solutions with pre-built ERP connectors.
Market Restraints
- ISO 27001 certification cost barriers:European mid-market buyers face six-figure compliance investments for data residency and security audits, slowing vendor consolidation timelines.
- Legacy ERP integration complexity:SAP ECC and Oracle E-Business Suite environments require custom middleware development, extending implementation cycles and inflating professional services dependencies.
- Supplier data standardization gaps:Inconsistent vendor master data formats across tier-2 and tier-3 manufacturing suppliers in China fragment API connectivity roadmaps.
Strategic Opportunities
- ESG due diligence automation:CSRD reporting requirements in the European Union create whitespace for carbon-accounting modules embedded within supplier management workflows.
- India's PLI scheme manufacturing expansion:Domestic electronics and pharmaceutical production incentives are spawning greenfield procurement technology deployments at contract manufacturers in Gujarat and Tamil Nadu.
- OCR-to-ERP reconciliation convergence:Machine learning document extraction fused with blockchain-verified invoice hashing is opening premium pricing tiers for touchless accounts payable automation.
Industry Challenges
- Procurement-IT skill bifurcation:Organizations struggle to hire professionals fluent in both category management strategy and cloud API architecture, creating implementation bottlenecks.
- Multi-jurisdiction compliance layering:Simultaneous adherence to GDPR data residency, EU AI Act algorithmic governance, and sector-specific e-invoicing mandates requires continuous platform reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Procure-To-Pay Solutions Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Invoice Management, Purchase Order Management, Supplier Management, Payment Processing Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS Industry Vertical: Manufacturing, Retail, Healthcare, Financial Services End User: Corporations, SMEs, Government Agencies, Non-Profits |
| Companies Covered | Ivalua, JAGGAER, SAP Ariba, Medius, Basware, Coupa, GEP SMART, Procurify, Oracle Procurement Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Procure-To-Pay Solutions Market Strategic Shifts
Artificial intelligence is rewriting the technical foundation of spend management, shifting competitive advantage from feature breadth to inference speed and training data exclusivity across supplier networks.
Embedded machine learning for spend classification is decomposing traditional category taxonomy structures. Mid-market manufacturing buyers in Germany and the United States are deploying natural language processing to auto-categorize free-text requisitions, collapsing the time from purchase request to approved purchase order from days to minutes.
The EU AI Act's risk-based classification system imposes documentation burdens on high-stakes automated sourcing decisions. Procurement platforms serving defense and healthcare supply chains must now maintain algorithmic impact assessments, redirecting R&D investment toward explainability interfaces rather than predictive accuracy alone.
Buying organizations are unbundling source-to-pay suites into best-of-breed components. Finance leaders at industrial distributors in France and the Netherlands are selecting specialized e-sourcing, contract lifecycle management, and invoice automation tools, integrating through iPaaS layers rather than accepting vendor lock-in for marginal functionality gains.
Procure-To-Pay Solutions Market Segmentation
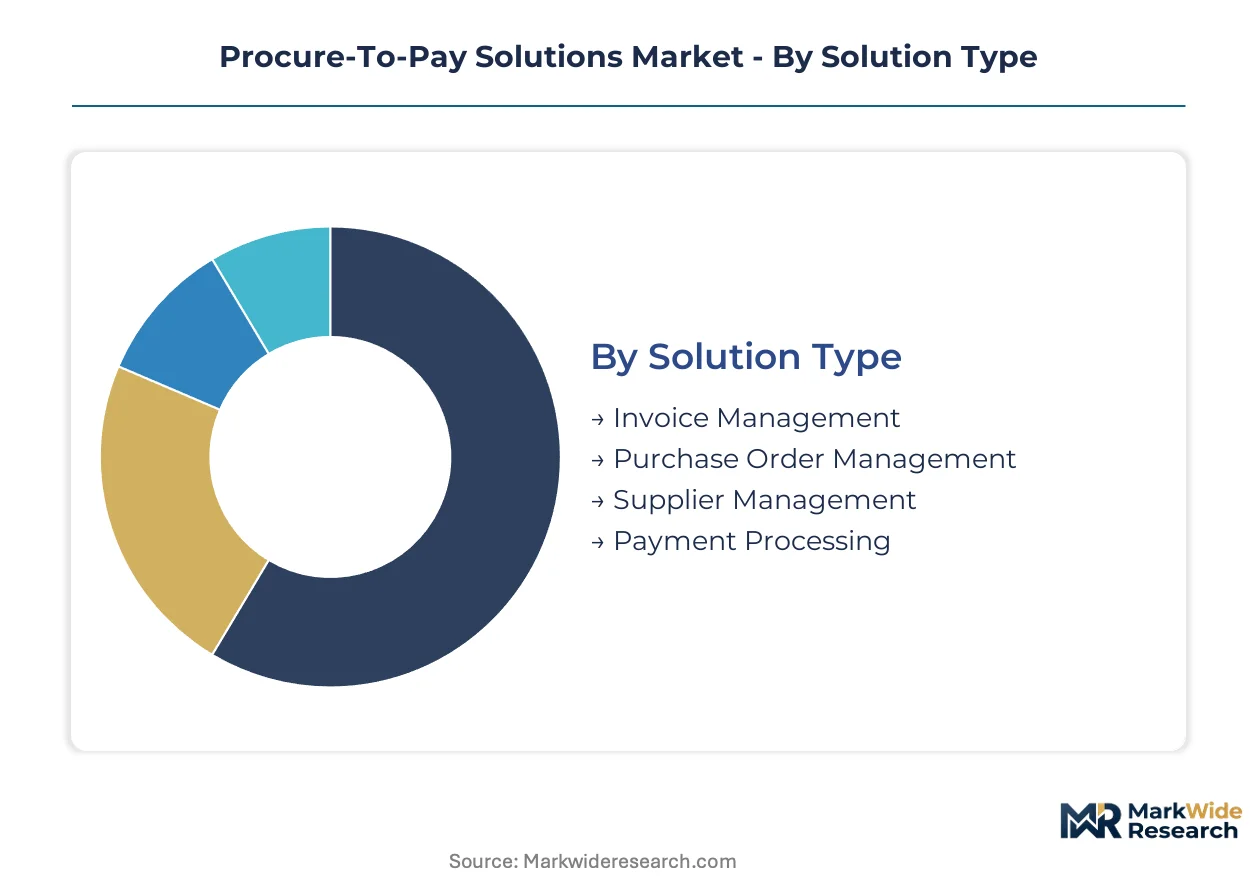
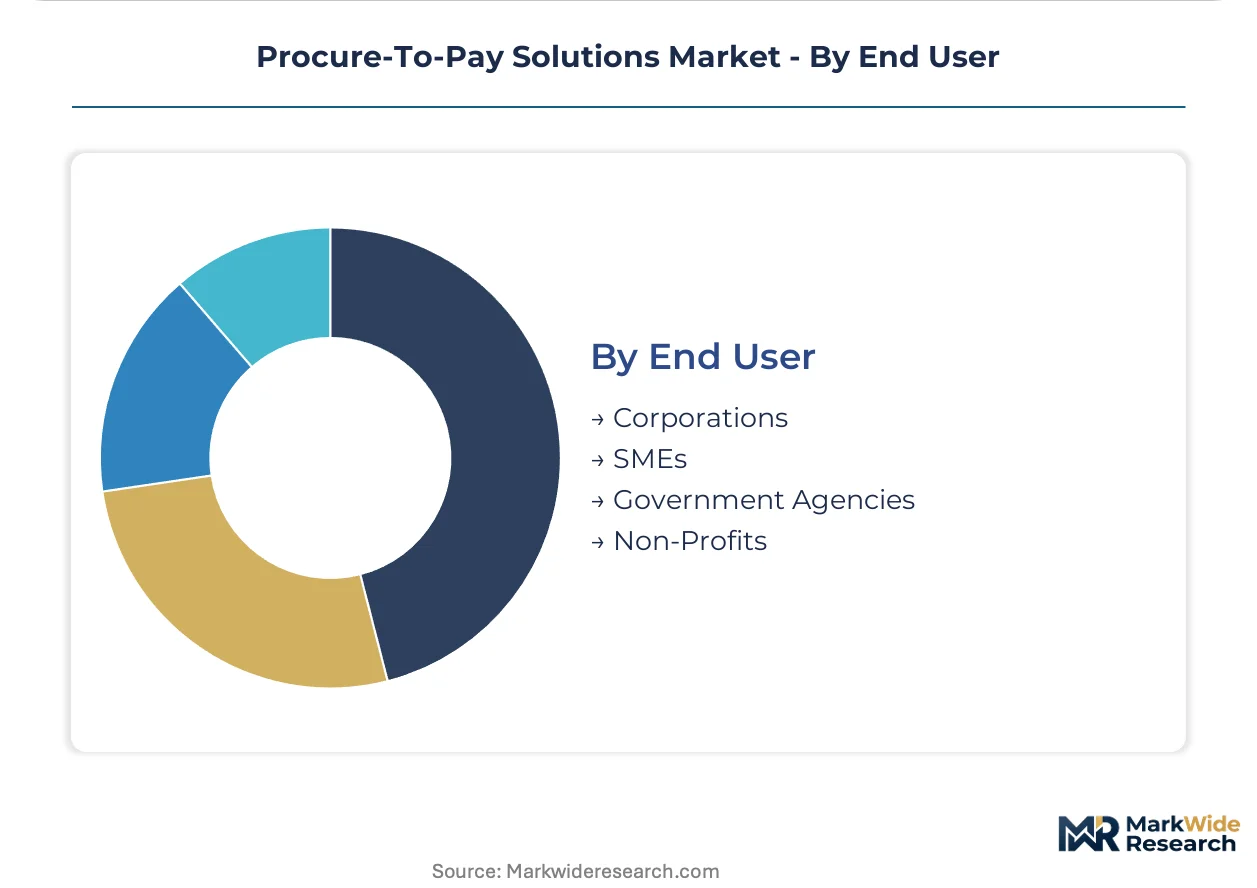
Procure-To-Pay Solutions vendors architect product roadmaps around four distinct segmentation axes. Deployment model determines compliance architecture and data residency obligations. Solution type dictates margin capture and integration complexity. Industry vertical and end-user scale shape pricing elasticity and sales cycle duration.
Solution Type:
GDPR and EU AI Act requirements fragment feature prioritization across European deployments, with audit trails and explainable AI commanding R&D investment.
- Invoice Management:Optical character recognition engines extract header-level and line-item data from unstructured documents, applying machine learning confidence scoring before three-way matching against purchase orders and receipts. German automotive suppliers and French industrial distributors prioritize this segment to satisfy real-time e-invoicing mandates from tax authorities while collapsing accounts payable cycle times.
- Supplier Management:Master data platforms unify vendor onboarding, risk scoring, and ESG credential verification through API-connected third-party databases. Demand concentrates among mid-market manufacturers in Germany seeking dual-source visibility and CSRD-aligned carbon accounting across tier-2 and tier-3 networks.
- Purchase Order Management:Workflow engines enforce approval hierarchies and budget guardrails through configurable business rules.
- Payment Processing:Treasury modules optimize settlement timing and currency exposure across multi-bank relationships.
Established volume favors Invoice Management; emerging adoption favors Supplier Management.
Deployment Model:
Cost tier differentiation separates enterprise buyers absorbing implementation complexity from mid-market purchasers demanding pre-configured connectivity.
- Cloud-Based:Multi-tenant architectures eliminate infrastructure ownership while embedding automatic compliance updates for evolving e-invoicing mandates. North American distributors with 500-5,000 employees drive displacement of on-premise ERP modules, prioritizing API-first platforms with native SAP and Oracle connectors.
- SaaS:Subscription pricing aligns vendor incentives with customer success metrics through usage-based expansion revenue. European mid-market buyers under GDPR data residency requirements select EU-sovereign instances with ISO 27001 certification, accepting premium pricing for regional data center guarantees.
- On-Premise:Single-tenant installations persist in defense-adjacent supply chains facing DFARS cybersecurity restrictions.
- Hybrid:Split architectures isolate sensitive supplier data on-premise while leveraging cloud analytics for spend intelligence.
Cloud-Based deployments dominate new bookings; On-Premise retention concentrates in regulated defense and healthcare supply chains.
Industry Vertical:
Application-specific compliance requirements reshape functional roadmaps, with manufacturing direct-material procurement demanding fundamentally different capabilities than retail indirect spend.
- Manufacturing:Direct-material sourcing platforms integrate bill-of-materials explosions, should-cost modeling, and supplier quality audits. Complex discrete manufacturers in Germany and contract electronics producers in India's Gujarat and Tamil Nadu anchor demand, driven by PLI scheme expansion and dual-source mandates.
- Healthcare:Contract lifecycle management with FDA 21 CFR Part 11 electronic signature compliance and vendor credentialing for medical device suppliers.
- Retail:High-volume indirect procurement with seasonal demand forecasting and promotional spend tracking.
- Financial Services:Regulatory procurement with SOX-compliant segregation of duties and vendor risk concentration monitoring.
Manufacturing commands the steepest expansion trajectory; Financial Services maintains the longest replacement cycles.
End User:
Customer scale determines sales motion economics, with enterprise accounts justifying field deployment teams while SME segments demand product-led growth and partner-channel fulfillment.
- Corporations:Global procurement organizations with decentralized buying centers require multi-entity consolidation, intercompany netting, and commodity hedge accounting. Demand clusters among Fortune 500 industrial conglomerates restructuring around shared services centers in Germany, France, and the United States.
- SMEs:Mid-market buyers with limited IT staff prioritize rapid deployment templates and pre-integrated supplier networks over customization depth.
- Government Agencies:Public sector procurement with open competition mandates, small business set-asides, and appropriation-year spending controls.
- Non-Profits:Grant-funded organizations with donor restriction tracking and volunteer procurement policy enforcement.
Corporations anchor absolute revenue contribution; SME segments are gaining share fastest through verticalized cloud suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform vendors concentrate engineering resources in jurisdictions with the densest procurement software adoption. Germany, the United States, the United Kingdom, India, and Brazil each anchor distinct demand patterns shaped by local regulatory and industrial conditions.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria drive demand for supplier risk visibility tools. The EU AI Act mandates algorithmic transparency for automated sourcing decisions, forcing platform upgrades. Stuttgart's automotive supplier ecosystem leads deployment of explainable AI procurement modules.
United States
Mid-market distributors with 500-5,000 employees accelerate cloud migration to retire on-premise ERP maintenance. DFARS cybersecurity restrictions constrain defense-adjacent supply chains to hybrid deployments. Chicago and Dallas industrial corridors anchor SaaS procurement suite adoption.
United Kingdom
Financial services procurement teams prioritize SOX-compliant segregation of duties and vendor risk monitoring. Post-Brexit regulatory divergence complicates EU data residency requirements for London-based shared services centers. The Midlands manufacturing belt experiments with unbundled best-of-breed procurement stacks.
India
PLI scheme incentives for electronics and pharmaceutical manufacturing spawn greenfield procurement technology deployments. Domestic contract manufacturers in Gujarat and Tamil Nadu demand cloud-native platforms with pre-built ERP connectors. BIS certification requirements shape vendor selection criteria for data sovereignty.
Brazil
Nota Fiscal Eletrônica real-time e-invoicing mandates force platform interoperability investments. São Paulo industrial distributors require native tax authority connectivity for accounts payable automation. ANVISA pharmaceutical procurement regulations add compliance layers for healthcare supply chains.
Procure-To-Pay Solutions Market Competitive Environment
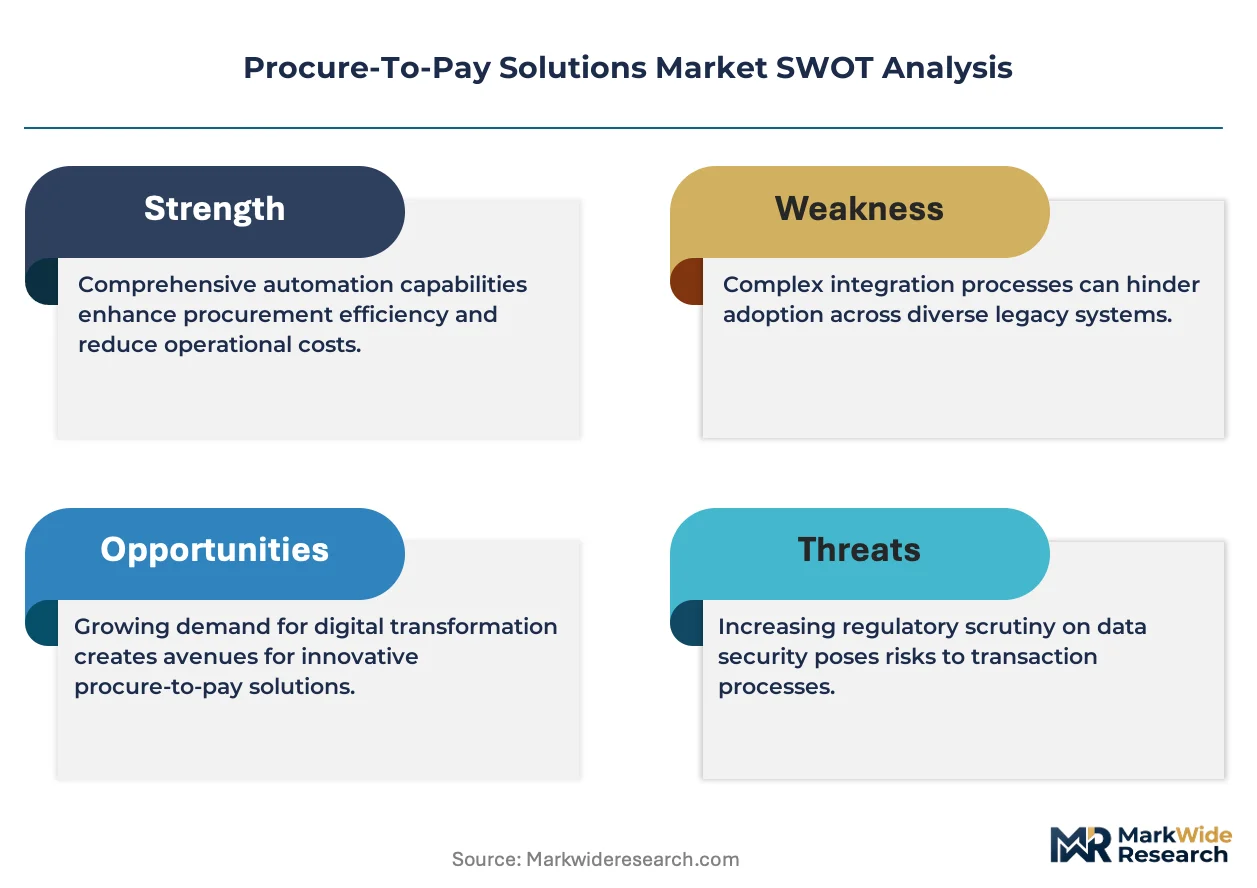
Concentration sits with enterprise suites and mid-market specialists occupying distinct tiers. The vendor base segments into three strategic archetypes: legacy ERP-integrated suites, cloud-native challengers with configurable workflow engines, and vertical specialists targeting direct-material procurement. M&A activity consolidates adjacent capabilities into unified platforms, while API-first architectures enable best-of-breed unbundling for selective buyers.
Among the enterprise-integrated tier, SAP Ariba and Oracle Procurement Cloud occupy positions anchored by ERP ecosystem lock-in. Coupa and Ivalua exemplify the cloud-native challenger archetype with mid-market penetration strategies. GEP SMART represents the vertical specialist segment focused on manufacturing direct-material complexity.
| Leading Market Players |
|---|
| Ivalua |
| JAGGAER |
| SAP Ariba |
| Medius |
| Basware |
| Coupa |
| GEP SMART |
| Procurify |
| Oracle Procurement Cloud |
| Others |
Value Chain & Pricing Dynamics
ISO 27001 certification gates both vendor qualification and price differentiation in European Procure-To-Pay deployments, forcing mid-market buyers to absorb six-figure compliance premiums for data residency guarantees while compressing margins for uncertified competitors.
Pricing Analysis
EU AI Act algorithmic transparency mandates dictate the pricing tier structure across explainable AI procurement modules. Three-tier pricing structure across premium, standard, and economy levels separates EU-sovereign cloud instances with full audit trails from basic SaaS tiers lacking GDPR-aligned data center guarantees. Cost compression in the mid-market tier is intensifying because pre-built ERP connectors are becoming table stakes. SMEs with limited IT staff exhibit the highest price sensitivity, while Fortune 500 industrial conglomerates prioritize compliance depth over subscription cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes directly impact deployment timelines for hardware-dependent hybrid installations. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning anchored in regional data centers. Platform engineering draws from specialized machine learning talent pools, API integration libraries, and compliance documentation frameworks. Single-source vulnerability sits with hyperscaler cloud dependencies for EU-sovereign instances. Distribution runs through direct enterprise sales teams for large accounts and partner-channel fulfillment for SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procure-To-Pay platform economics are reaching an inflection as API-first architectures enable best-of-breed unbundling, rewarding vendors who embed interoperability at the protocol layer rather than the feature layer.
For Market Incumbents: Consolidate adjacent capabilities into unified suites before cloud-native challengers capture mid-market workflow automation share. Acquire specialized e-sourcing or invoice automation firms to fill functional gaps. Invest in ISO 27001 certification breadth across all regional data center footprints to defend European pricing power against uncertified entrants. For New Entrants and Emerging Players: Anchor in India's PLI scheme manufacturing expansion, where greenfield contract manufacturers in Gujarat and Tamil Nadu lack legacy ERP entanglements. Target mid-market distributors with 500-5,000 employees in North America, where on-premise retirement urgency outpaces vendor consolidation. Pursue verticalized cloud suites with pre-built Oracle and SAP connectors as the primary go-to-market angle. For Investors and Strategic Acquirers: EU AI Act implementation timelines reshape the acquisition landscape toward explainable AI platforms with auditable decision trails. Position holdings for a 5-10 year window where algorithmic governance compliance becomes a durable moat. Prioritize targets with embedded carbon-accounting modules for CSRD-aligned supplier management. Monitor e-invoicing mandate expansion across Brazil, Italy, and Saudi Arabia as the signal for platform interoperability premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Absorbs e-sourcing or invoice automation capabilities into unified suite architecture. |
| Platform Integration | Embeds iPaaS connectivity layers for best-of-breed unbundling resistance. |
| Geographic Expansion | Captures PLI scheme manufacturing demand in Gujarat and Tamil Nadu contract producers. |
| Product Launch | Introduces explainable AI modules satisfying EU AI Act algorithmic transparency mandates. |
| Strategic Partnership | Secures native tax authority connectivity for Brazil Nota Fiscal Eletrônica compliance. |
Study Parameters
Desk research of SEC filings, hyperscaler capex disclosures, and EU regulatory databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across Germany, the United States, and India. Primary fieldwork with SaaS vendor product managers and ERP implementation consultants validated secondary estimates of cloud migration timelines. Bottom-up deployment counts and top-down enterprise software spending aggregates were triangulated against vendor-reported booking trends.
Variance decomposition across deployment model, organization size, vertical, and integration complexity shaped the analytical framework. CAGRs were derived from logistic adoption curves fitted to mid-market cloud migration patterns and e-invoicing mandate compliance deadlines. Modeled inputs included ERP connector availability, ISO 27001 certification penetration rates, and AI Act implementation phase schedules across member states.
Material uncertainties — regulatory enforcement intensity, hyperscaler pricing volatility, and supplier data standardization breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about compliance timeline adherence and cloud infrastructure cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Onboarding Software Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
Integrated Systems Market
Digital Solutions
Global Delivery Management Software Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Data Monetization Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Global Multichannel Campaign Management Market
Digital Solutions
Global Genealogy Products and Services Market