
 Global Service Delivery Platform Market | 2026-2036
Global Service Delivery Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Service Delivery Platform Market Foresight
Cloud-native engineering talent is rotating toward telecom-centric platform development, tightening supply for general enterprise software roles. Cisco Systems leverages its router and security installed base to embed service delivery platforms directly into carrier networks. Huawei Technologies anchors its position through integrated 5G core-to-edge stack ownership across Asian and Middle Eastern deployments. Ericsson competes on Open RAN interoperability, sustaining R&D intensity in cloud-native network functions that feed platform demand.
A service delivery platform constitutes a middleware architecture that orchestrates digital services across network, compute, and application layers through standardized APIs and policy engines, typically supporting sub-50 millisecond latency targets for real-time service instantiation. Its primary purpose is enabling telecommunications operators and enterprises to provision, monetize, and assure digital services without bespoke system integration for each offering. Cloud-based deployment leads in new implementations as carriers retire legacy operational support systems, while edge computing represents the fastest-expanding segment driven by ultra-reliable low-latency use cases in manufacturing and autonomous systems. API management captures concentrated margin pools because vendor lock-in deepens once developer ecosystems coalesce around specific gateway standards.
The Federal Communications Commission shapes US market access through spectrum allocation rules that determine where edge platforms must physically locate processing capacity, while the European Telecommunications Standards Institute governs interoperability benchmarks that vendors must satisfy for cross-border service portability. India's Telecom Regulatory Authority pushes domestic data localization mandates that force platform providers to establish in-country infrastructure, raising compliance costs but creating captive demand for local integrators. Stakeholders must monitor whether Open Gateway API standardization by the GSMA fragments into regional variants or achieves sufficient convergence to prevent platform siloing.
Market Dynamics
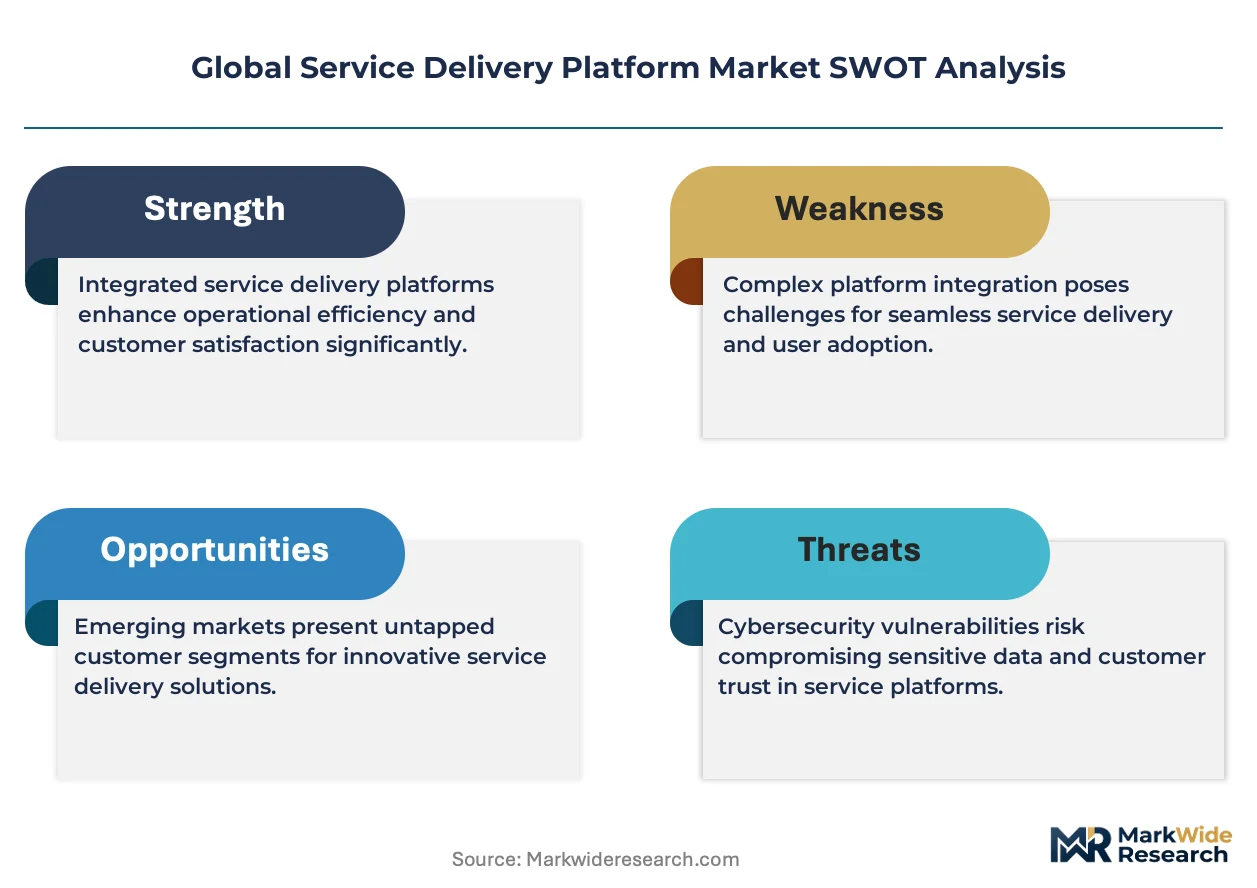
Cloud-native service orchestration is compressing deployment cycles from months to hours, forcing incumbent vendors to dismantle monolithic architectures while carriers simultaneously confront EU AI Act compliance mandates and 5G standalone core buildouts.
Growth Catalysts
- GDPR-Driven Governance Embedding:The EU AI Act and GDPR compliance requirements are compelling platform vendors to embed automated policy engines directly into service delivery stacks, creating captive upgrade cycles among European carriers.
- Edge Computing Infrastructure Buildout:Manufacturing and autonomous systems in Germany, the United States, and India are demanding sub-50 millisecond latency guarantees, pulling capital toward distributed service delivery nodes.
- API Standardization Convergence:GSMA Open Gateway initiatives are reducing integration friction between carrier networks and enterprise developers, expanding addressable use cases beyond traditional telecom boundaries.
Market Restraints
- Cloud-Native Talent Scarcity:Engineering supply for Kubernetes-native network function development remains concentrated among a handful of specialized integrators, inflating implementation costs.
- Data Localization Mandates:India's TRAI domestic infrastructure requirements force platform providers to establish captive in-country processing capacity, raising fixed cost bases without commensurate revenue scale.
- Legacy OSS Retirement Complexity:Carriers face technical debt from decades-old operational support systems that resist API-based abstraction layers, slowing migration timelines.
Strategic Opportunities
- 5G Standalone Core Deployments:United States and Indian carriers are greenfielding cloud-native cores, bypassing legacy constraints and creating first-mover advantages for platform vendors with proven interoperability.
- Network-as-a-Service Channel Expansion:Hyperscale cloud marketplaces are emerging as distribution channels for service delivery platforms, compressing enterprise sales cycles.
- AI-Assured Service Orchestration:Convergence of machine learning inference with real-time policy engines enables predictive service assurance, opening premium pricing tiers for manufacturing verticals.
Industry Challenges
- Multi-Vendor Integration Complexity:Open RAN disaggregation is fragmenting component sourcing, forcing platform vendors to certify against dozens of radio and core combinations.
- Certification Timeline Compression:ETSI interoperability benchmarks and FCC spectrum rules are evolving faster than vendor validation cycles, risking market access delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Service Delivery Platform Market |
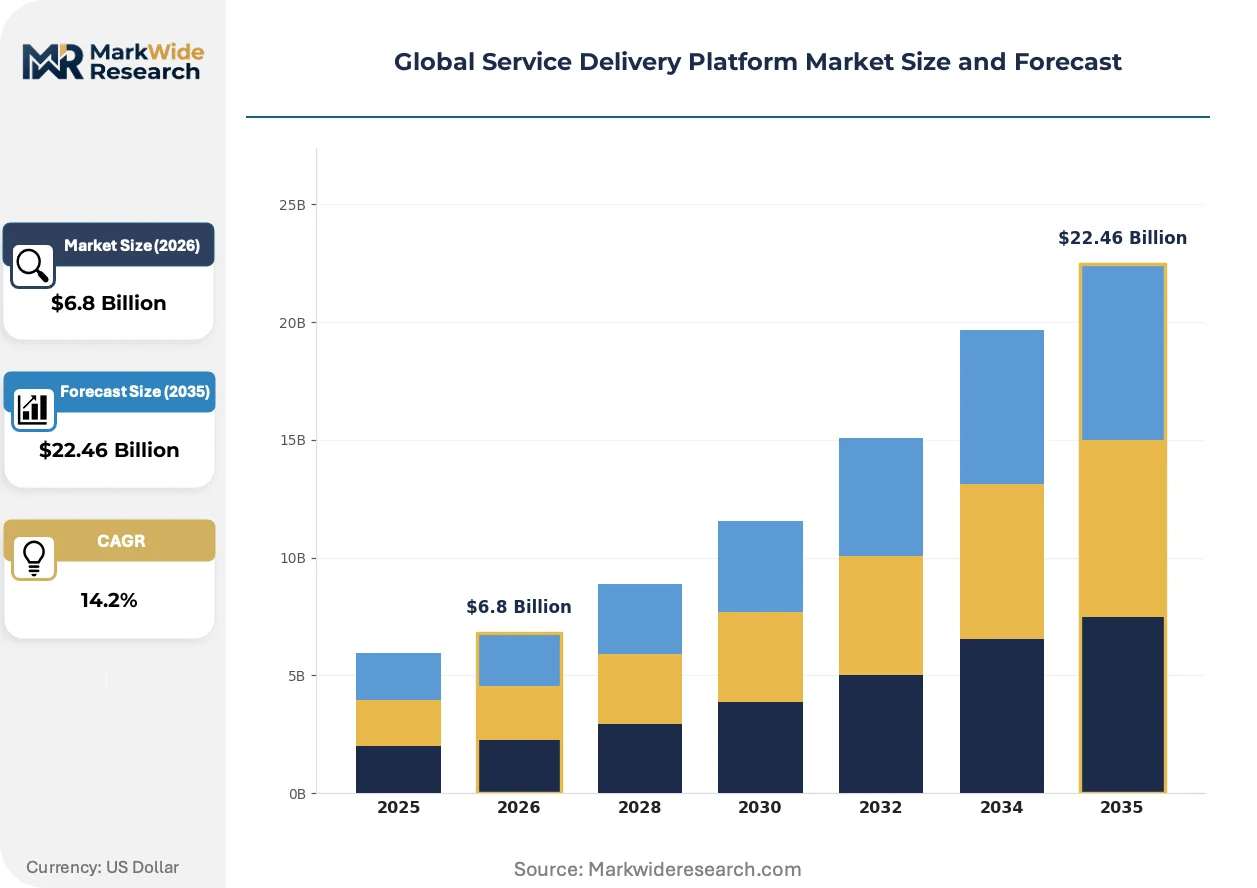
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution/Offering: API Management, Data Integration, User Interface, Analytics Engine, Security Module Application/Use Case: Telecommunications, Digital Media, Financial Services, E-Commerce, Public Sector End User/Industry Vertical: Information Technology, Insurance Firms, Consumer Electronics, Transportation Services |
| Companies Covered | Cisco Systems, Inc., HCL Technologies Ltd, Huawei Technologies Co., Ltd., Accenture PLC, Fujitsu Ltd, Nokia Corporation, Amdocs Limited, Telenity Inc., Ericsson AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Service Delivery Platform Market Shifts & Advancements
Service delivery platforms are undergoing architectural compression as edge computing, automated governance, and developer-centric procurement models simultaneously reshape technical requirements and commercial pathways.
Containerized network functions are displacing virtual machine-based deployments in carrier cores. Deutsche Telekom and Reliance Jio are accelerating rollouts of Kubernetes-orchestrated control planes. This shift is miniaturizing the operational footprint of service instantiation engines, enabling deployment on commodity hardware at cell tower bases.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated service provisioning. Vendors must now document decision pathways within policy engines. European deployments face the steepest compliance curves, with carriers pre-integrating audit trails into platform procurement specifications.
Enterprise buyers are unbundling professional services from platform licensing, preferring self-service API portals with consumption-based metering. System integrators are losing attach rates to direct developer relationships. This pattern is most pronounced in United States manufacturing verticals, where DevOps teams procure network capabilities without IT procurement intermediation.
Global Service Delivery Platform Market Segmentation
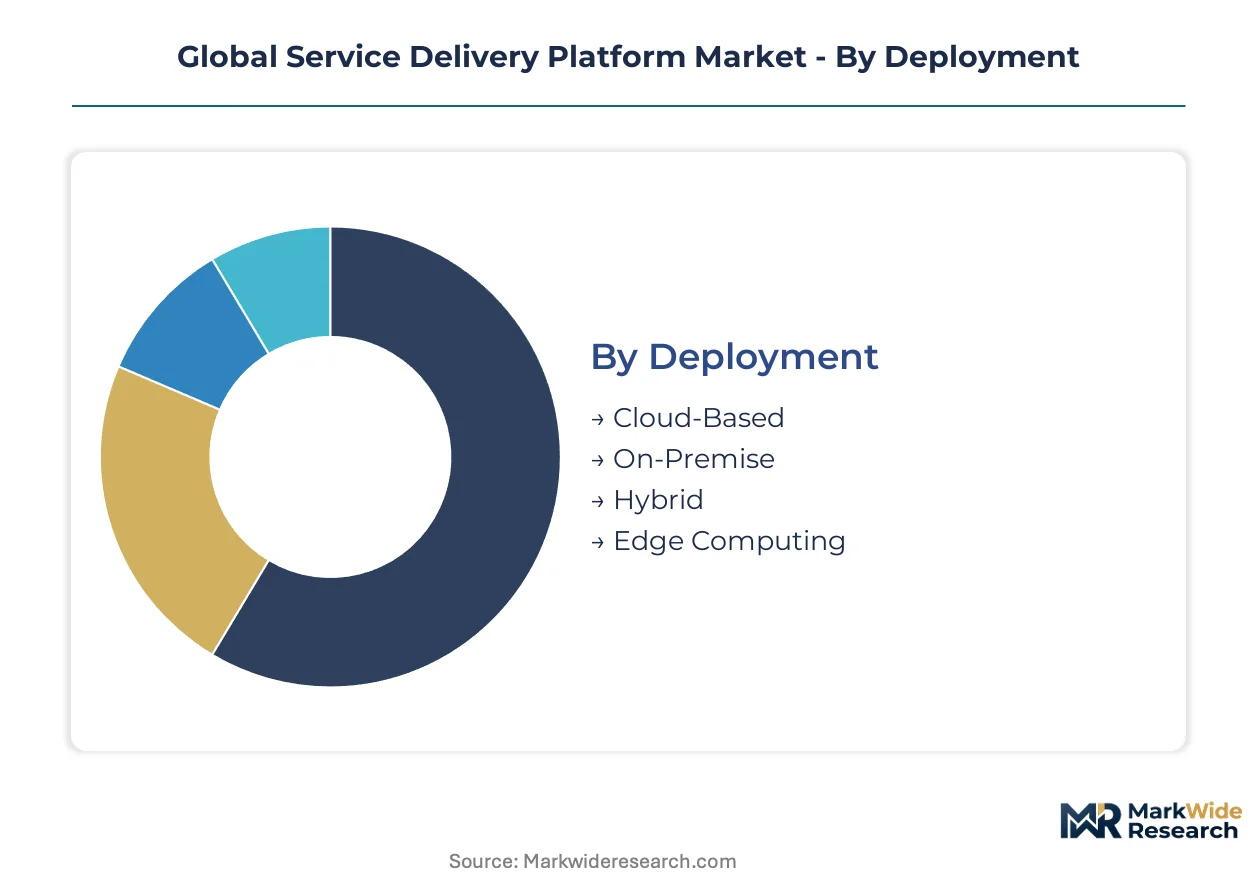
Service delivery platform procurement channels diverge sharply by deployment model and buyer sophistication. Telecom carriers favor direct vendor relationships for core infrastructure, while enterprise verticals increasingly source through hyperscale cloud marketplaces with consumption-based metering.
Deployment:
Channel economics vary dramatically by deployment architecture, with capital intensity and compliance obligations determining whether carriers buy direct, through systems integrators, or via cloud marketplaces.
- Cloud-Based:Multi-tenant architectures hosted on hyperscale infrastructure dominate new carrier implementations. Deutsche Telekom and Reliance Jio are greenfielding Kubernetes-native control planes that bypass legacy operational support systems entirely, compressing deployment cycles from months to hours.
- Edge Computing:Distributed nodes at cell tower bases and factory floors require sub-50 millisecond latency guarantees. Manufacturing and autonomous systems in Germany, the United States, and India are pulling capital toward these deployments, though certification against ETSI interoperability benchmarks slows vendor validation cycles.
- Hybrid:Split orchestration layers span private cores and public cloud bursting capacity for traffic spikes.
- On-Premise:Air-gapped installations persist in defense and critical infrastructure verticals with data sovereignty requirements.
Cloud-based deployments dominate installed base. Edge computing is where expansion concentrates.
Solution/Offering:
Margin pools concentrate where vendor lock-in deepens, with API management capturing premium pricing through developer ecosystem capture while commoditized modules face pricing pressure.
- API Management:Gateway standardization by the GSMA Open Gateway initiative is reducing integration friction between carrier networks and enterprise developers. Once developer ecosystems coalesce around specific gateway implementations, switching costs escalate dramatically, embedding vendors for multi-year cycles.
- Security Module:Automated policy engines must now document algorithmic decision pathways under the EU AI Act's risk classification framework. European carriers are pre-integrating audit trails into procurement specifications, creating captive upgrade cycles among vendors serving this geography.
- Analytics Engine:Machine learning inference convergence with real-time policy engines enables predictive service assurance.
- Data Integration:Legacy operational support system abstraction layers face technical debt resistance from decades-old carrier infrastructure.
- User Interface:Self-service portals with consumption-based metering are displacing professional services attach rates.
API management commands premium pricing tiers. Security modules are climbing the fastest as compliance mandates harden.
Application/Use Case:
Volume concentration tracks 5G standalone core buildouts, with telecommunications absorbing disproportionate platform investment while adjacent verticals adopt modular capabilities.
- Telecommunications:5G standalone core deployments in the United States and India are greenfielding cloud-native architectures without legacy constraints. Carriers confront simultaneous pressures from EU AI Act compliance mandates and FCC spectrum allocation rules that determine where edge platforms must physically locate processing capacity.
- Financial Services:Real-time payment orchestration and fraud detection require sub-50 millisecond policy engine responses.
- E-Commerce:Peak load orchestration during transaction surges drives hybrid deployment adoption.
- Digital Media:Content delivery network integration demands API standardization for cache invalidation workflows.
- Public Sector:India's TRAI domestic data localization mandates force in-country infrastructure establishment, raising fixed cost bases without commensurate revenue scale.
Telecommunications anchors volume demand. Financial services represent the steepest expansion trajectory as real-time requirements harden.
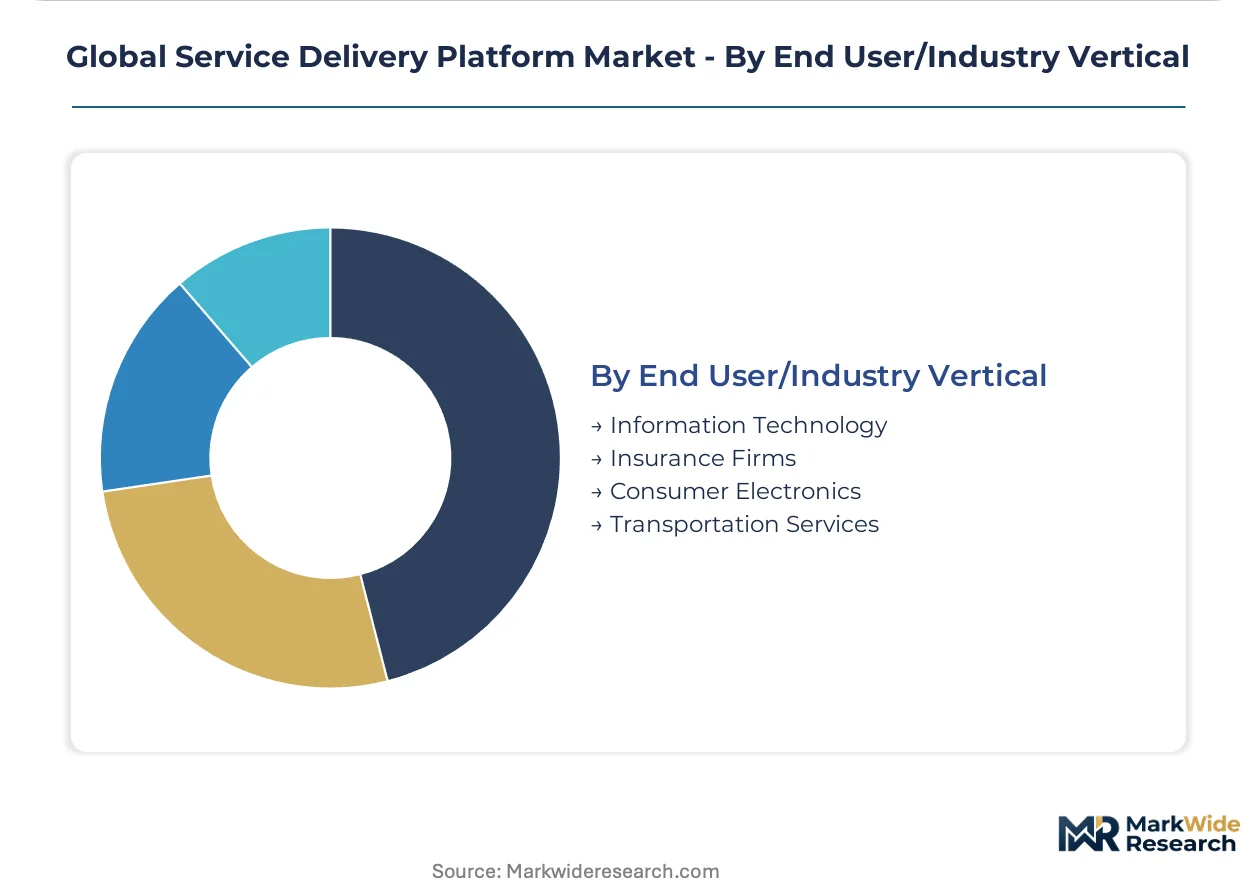
End User/Industry Vertical:
Procurement authority is shifting from central IT to DevOps teams, with developer-centric buying patterns most pronounced in manufacturing-adjacent verticals.
- Information Technology:Hyperscale cloud marketplaces are emerging as primary distribution channels, compressing enterprise sales cycles. DevOps teams procure network capabilities without traditional IT procurement intermediation, unbundling professional services from platform licensing entirely.
- Transportation Services:Autonomous systems and fleet management require ultra-reliable low-latency connectivity.
- Insurance Firms:Telematics data ingestion platforms demand edge-to-cloud orchestration pipelines.
- Consumer Electronics:Device lifecycle management and over-the-air update distribution require scalable API gateways.
Information technology verticals dominate developer-led procurement. Transportation services are where edge-native requirements concentrate most intensely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC shapes United States market access through spectrum allocation rules that determine where edge platforms must physically locate processing capacity. Carrier investments concentrate where regulatory clarity intersects with 5G standalone core buildout timelines.
United States
AT&T and Verizon are greenfielding cloud-native service delivery architectures for 5G standalone cores. The FCC's mid-band spectrum auctions force edge platform providers to co-locate processing capacity with licensed spectrum holdings. Dallas-Fort Worth and Seattle-Tacoma clusters host the densest concentrations of Kubernetes-orchestrated network function deployments.
Germany
Deutsche Telekom's manufacturing vertical contracts demand sub-50 millisecond latency guarantees for industrial automation. The EU AI Act's risk classification framework mandates algorithmic transparency in automated service provisioning. Munich and Stuttgart engineering corridors concentrate edge node deployments serving automotive and precision manufacturing clients.
India
Reliance Jio and Bharti Airtel are bypassing legacy operational support systems entirely with Kubernetes-native control planes. TRAI's domestic data localization mandates force platform providers to establish captive in-country processing infrastructure. Bengaluru and Hyderabad technology corridors absorb disproportionate engineering talent for cloud-native network function development.
China
China Mobile and China Telecom are deploying integrated 5G core-to-edge stacks across manufacturing zones. MIIT's dual carbon goals accelerate retirement of energy-intensive legacy operational support systems. Shenzhen and Hangzhou technology clusters concentrate platform development for export-oriented telecommunications equipment.
United Kingdom
BT Group and Vodafone UK are navigating Open RAN disaggregation while maintaining legacy interoperability. The UK Information Commissioner's Office enforces GDPR-aligned audit trail requirements for automated policy engines. London's financial services corridor drives demand for real-time payment orchestration platforms with sub-50 millisecond response guarantees.
Global Service Delivery Platform Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the service delivery platform market. The vendor base separates into three strategic tiers: integrated telecommunications equipment providers, cloud-native software specialists, and systems integrators with carrier relationships. Consolidation pressures intensify as carriers demand end-to-end accountability for multi-vendor deployments. Dominant competitive moves include strategic partnerships between hardware and software providers and geographic expansion through localized compliance infrastructure.
Among integrated telecommunications equipment providers, Cisco Systems, Huawei Technologies, and Ericsson anchor distinct competitive positions. Cisco leverages its router and security installed base to embed service delivery platforms directly into carrier networks. Huawei anchors its position through integrated 5G core-to-edge stack ownership across Asian and Middle Eastern deployments. Ericsson competes on Open RAN interoperability, sustaining R&D intensity in cloud-native network functions that feed platform demand.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| HCL Technologies Ltd |
| Huawei Technologies Co., Ltd. |
| Accenture PLC |
| Fujitsu Ltd |
| Nokia Corporation |
| Amdocs Limited |
| Telenity Inc. |
| Ericsson AB |
| Others |
Supply & Pricing Matrix
Containerized network functions displacing virtual machine-based deployments simultaneously redistribute supply geography toward Kubernetes-native engineering clusters and compress pricing premiums for legacy orchestration tiers as carriers retire operational support systems.
Pricing Analysis
Geographic price spreads between United States and Indian deployments exceed three-to-one for equivalent API management modules, with EU AI Act compliance embedding in European contracts adding certification-grade premiums. Pricing stratifies across cloud-native, edge-optimized, and legacy abstraction tiers, with customization for sub-50 millisecond latency guarantees commanding the widest spreads. Cost compression in standard cloud-based implementations is intensifying as hyperscale marketplaces introduce consumption-based metering. Enterprise DevOps teams in United States manufacturing verticals exhibit the lowest price sensitivity, while Indian carrier procurement offices face the highest.
Supply Chain Analysis
Inbound logistics costs for edge computing hardware face intermittent pressure from container availability constraints on Asia-Europe trade lanes serving German automotive corridor deployments. Supply concentrates in United States, Germany, and India for cloud-native control plane development, with China anchoring integrated 5G core-to-edge stack manufacturing. Component sourcing draws from Taiwanese semiconductor foundries, South Korean memory suppliers, and Japanese precision networking equipment. Single-source vulnerability around GSMA Open Gateway API standardization creates certification chokepoint risk. Distribution runs through direct vendor relationships for carrier core infrastructure and hyperscale cloud marketplaces for enterprise verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Service Delivery Platform Market is entering a cyclical recovery phase as 5G standalone core buildouts accelerate capital deployment cycles after legacy operational support system stagnation.
For Market Incumbents: Shield embedded positions by deepening API gateway ecosystem capture before GSMA Open Gateway standardization crystallizes around competitor implementations. Prioritize in-country infrastructure establishment in India ahead of TRAI enforcement timelines to preempt local integrator displacement. Vertical integration into Kubernetes-native network function development tightens control over scarce engineering talent pools. For New Entrants and Emerging Players: Differentiate on AI-assured service orchestration capabilities targeting manufacturing verticals in Germany with predictive assurance premiums. White-space concentration sits in edge computing nodes for autonomous systems where incumbent certification lag against ETSI benchmarks creates entry windows. Target financial services in the United Kingdom through real-time payment orchestration specialization. Go-to-market leverage runs through hyperscale cloud marketplaces bypassing traditional carrier procurement cycles. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native software specialists with proven Open RAN interoperability certification and captive relationships with Reliance Jio or Deutsche Telekom. Long-term viability over the next decade hinges on algorithmic transparency capabilities mandated by expanding EU AI Act risk classifications. The signal to watch is FCC spectrum allocation rule changes that would force physical relocation of edge processing capacity and trigger infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| API Gateway Ecosystem Capture | GSMA Open Gateway standardization locks developer relationships into multi-year vendor cycles. |
| Edge Node Geographic Expansion | FCC spectrum rules force co-location with licensed holdings in Dallas-Fort Worth and Seattle-Tacoma clusters. |
| AI-Assured Service Orchestration | Machine learning convergence with policy engines opens premium pricing tiers for German manufacturing clients. |
| In-Country Infrastructure Establishment | TRAI data localization mandates create captive demand for Indian domestic processing capacity. |
| Legacy OSS Abstraction Layer Development | Technical debt resistance from decades-old carrier infrastructure slows migration and extends service revenue. |
Research Methodology
The analysis maps cloud-based, edge computing, hybrid, and on-premise deployment architectures, each validated through conversations with carrier network architects, platform engineering leads, hyperscale cloud procurement officers, and systems integrators with active telecommunications accounts. Primary interview insights combined with secondary validation against SEC 10-K filings, ETSI interoperability benchmark documentation, FCC spectrum auction records, and TRAI regulatory circulars. Bottom-up deployment volume estimates triangulated against top-down carrier capital expenditure disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models deployment model, solution type, application use case, and end-user vertical segmentation dimensions. CAGRs were derived from carrier greenfield buildout timelines and hyperscale marketplace adoption curves. Industry-specific forecast inputs include 5G standalone core deployment schedules and EU AI Act compliance implementation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained carrier cloud-native migration, stable regulatory enforcement timelines, and continued Open RAN disaggregation would require recalibration. Forecasts reflect documented assumptions around engineering talent availability and certification cycle durations. Specific risk factors that could revise projections include accelerated legacy operational support system retirement failure, regional fragmentation of GSMA Open Gateway standards, or abrupt spectrum policy shifts by the FCC or national equivalents. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Work From Home Setup Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Service Lifecycle Management Application Market
Digital Solutions
Business Document Work Process Management Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Cloud Electronic Design Automation Market
Digital Solutions
Global Online Classifieds Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
Load Balancer Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market