
 Computer-To-Plate and Computer-To-Press Systems Market | 2026-2036
Computer-To-Plate and Computer-To-Press Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Computer-To-Plate and Computer-To-Press Systems Market Analysis
Modular bundling of plate-setter hardware with cloud-based color management software is restructuring buyer procurement patterns across the commercial print sector. Fujifilm Holdings Corporation leverages its hybrid ink-plate ecosystem to anchor long-term service contracts in North American packaging hubs. Heidelberger Druckmaschinen AG dominates mid-web offset installations through captive financing structures that lock in consumables volume.
Computer-To-Plate and Computer-To-Press Systems integrate digital imaging engines with lithographic or flexographic printing units, typically operating at resolutions between 1200 and 2540 dpi to transfer bitmap data directly onto photosensitive plates or blanket cylinders without intermediate film. These systems eliminate analog darkroom steps, cutting makeready time from hours to minutes while stabilizing dot gain curves across long print runs. Thermal technology leads installed base value due to its chemistry-free workflow and broad substrate compatibility, though UV-curable direct imaging is gaining traction in narrow-web label applications where instant plate hardening reduces job-change downtime. Flatbed configurations occupy the premium tier in corrugated post-print segments, while roll-to-roll architectures sustain volume share in publication gravure replacement cycles.
EPA emissions guidelines for volatile organic compounds constrain solvent-based plate processing in US commercial print facilities, pushing converters toward thermal and water-wash alternatives. REACH restrictions on chromium compounds and EU F-Gas Regulation phase-down schedules reshape equipment replacement timelines across European packaging plants. China's MEE enforcement of dual carbon targets pressures domestic printers to retire thermal oxidizer-dependent film workflows. Stakeholders must monitor how regional carbon border adjustments recalibrate total cost of ownership calculations for imported versus locally manufactured plate engines.
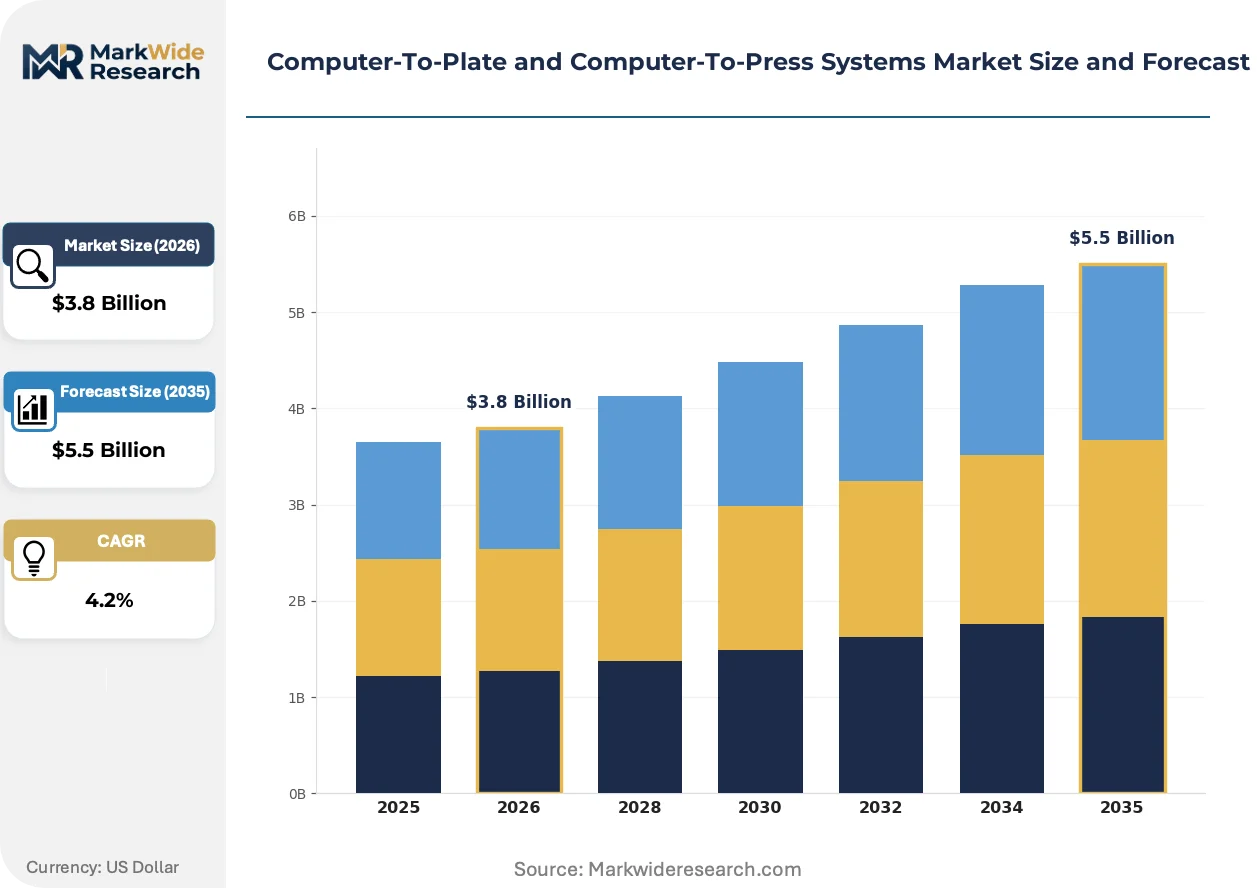
Market Dynamics
Packaging converters across Germany and the United States are consolidating direct-to-press workflows to eliminate makeready waste, compressing job-change cycles from hours to minutes while locking in chemistry-free thermal plate technologies as the default infrastructure standard.
Growth Catalysts
- REACH Phase-Down Mandates:ECHA restrictions on chromium compounds and solvent-based processing push European commercial printers toward thermal and water-wash plate alternatives, accelerating replacement cycles in Germany and France.
- Corrugated Post-Print Automation:Flatbed CTP configurations penetrate folding carton lines in the United States and China, where e-commerce packaging volumes demand instant plate imaging without film intermediates.
- Dual Carbon Enforcement:China's MEE pressures domestic printers to retire thermal oxidizer-dependent analog workflows, redirecting capital toward direct-imaging engines with lower energy intensity.
Market Restraints
- Capital Intensity Barriers:Mid-format commercial printers in Italy and Spain face compressed access to equipment financing, delaying thermal plate-setter adoption despite operational savings.
- UV-Curable Ink Substitution:Narrow-web label converters in Japan and South Korea increasingly favor UV inkjet direct-to-substrate systems, eroding addressable volume for lithographic CTP in short-run segments.
- Service Network Concentration:Dense maintenance infrastructure clusters in Germany and Japan leave peripheral European markets with extended downtime risks and higher total cost of ownership.
Strategic Opportunities
- Cloud-Native Color Management:Hybrid bundling of plate-setter hardware with SaaS-based profiling tools creates recurring revenue anchors for vendors serving North American packaging hubs.
- India Commercial Print Modernization:BIS standardization of thermal plate chemistry-free workflows opens procurement pathways for mid-tier printers in Maharashtra and Gujarat previously locked into analog film.
- F-Gas Regulation Tailwinds:EU phase-down schedules for hydrofluorocarbon-based plate conditioning systems force replacement demand toward thermal alternatives in French and Italian gravure conversion projects.
Industry Challenges
- Prepress Specialist Scarcity:German and Japanese equipment vendors struggle to deploy qualified field engineers for thermal plate calibration across fragmented commercial print bases in Eastern Europe.
- Legacy MIS Integration Friction:Direct-to-press workflows require API-level connectivity with existing job ticketing systems, creating deployment delays for mid-market converters in the United States and United Kingdom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer-To-Plate and Computer-To-Press Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal, UV, Direct, Laser Application: Packaging, Commercial Printing, Labeling, Textile Printing Product Type: Flatbed, Roll-to-Roll, Hybrid, Inline End User: Publishing, Advertising, Electronics, Food & Beverage |
| Companies Covered | Eastman Kodak Company, Agfa-Gevaert Group, Screen Holdings Co., Ltd., Fujifilm Holdings Corporation, Heidelberger Druckmaschinen AG, ECRM, Mitsubishi Imaging, Glunz & Jensen, Komori Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer-To-Plate and Computer-To-Press Systems Market Emerging Trajectories
Digital imaging engines are fusing with lithographic and flexographic units in ways that compress makeready intervals and eliminate chemistry-dependent processing steps entirely.
Thermal plate technology is converging with inline spectrophotometry for closed-loop color correction. Narrow-web label converters in Japan and Germany adopt these integrated systems to cut job approval cycles. The structural result is a collapse in make-ready labor hours and plate remakes.
EPA emissions guidelines for volatile organic compounds constrain solvent-based plate processing in United States commercial facilities. This regulatory pressure redirects capital toward water-wash and thermal alternatives. Packaging converters in California and Texas respond by accelerating thermal oxidizer retirement timelines.
Buyer procurement patterns now favor modular hardware-software bundles over standalone equipment purchases. North American packaging hubs lead this transition, replacing perpetual licenses with subscription-based color management. The shift concentrates vendor relationships around service contracts rather than transactional equipment sales.
Computer-To-Plate and Computer-To-Press Systems Market Segmentation
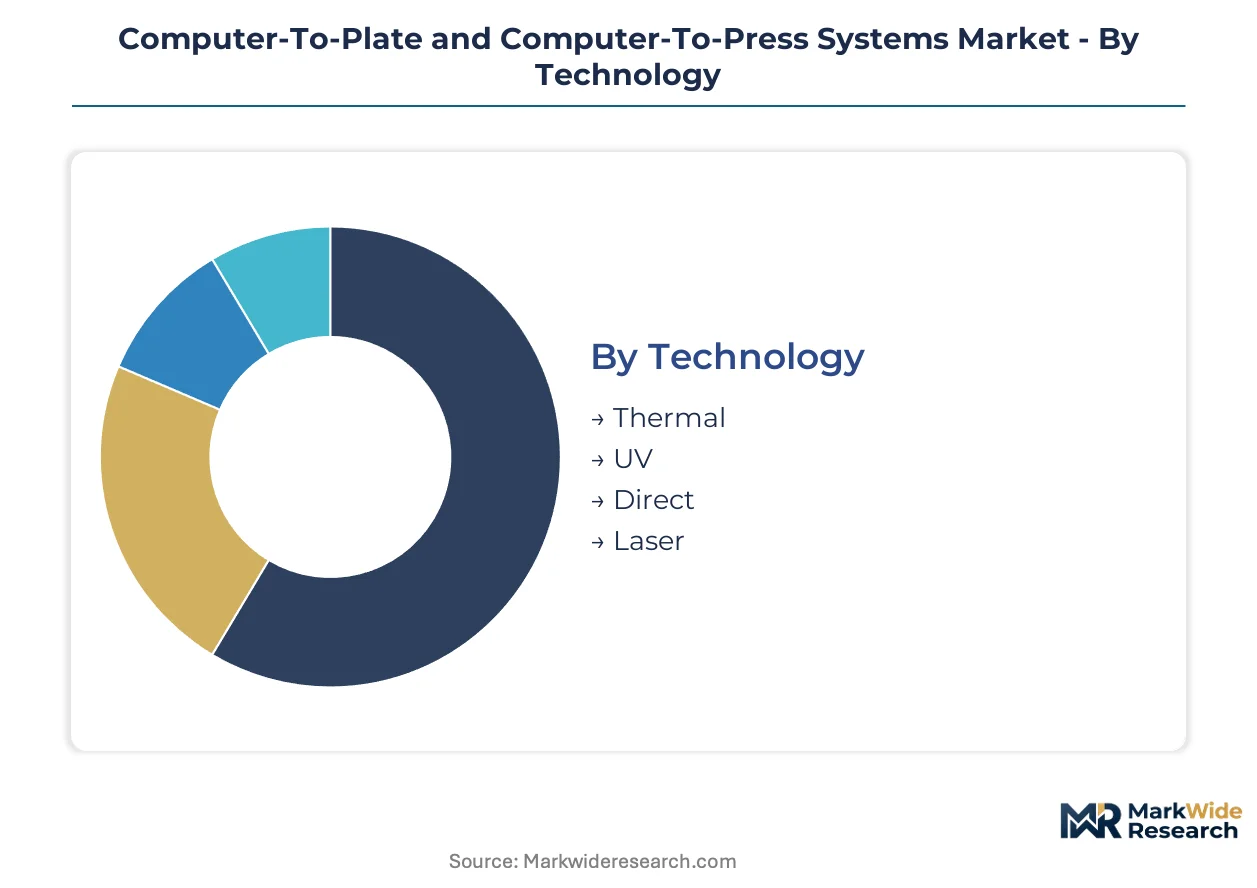
Segmentation in CTP/CTPress systems reveals how technical specifications, production formats, and end-use requirements reshape procurement decisions across print infrastructure investments. Buyers prioritize chemistry-free workflows, substrate versatility, and integration depth with existing press lines when evaluating system categories.
Technology:
Technology selection separates buyers by environmental compliance posture and chemistry handling capabilities, with thermal systems commanding premium positioning among converters facing regulatory pressure.
- Thermal:Chemistry-free imaging using infrared laser diodes to ablate photopolymer layers without wet processing steps. Packaging converters in Germany and the United States favor thermal plate-setters to satisfy ECHA REACH mandates and EPA VOC guidelines while eliminating hazardous waste streams from darkroom operations.
- UV:Direct imaging with ultraviolet exposure hardens photopolymer plates instantly without thermal development. Narrow-web label producers in Japan adopt UV-curable direct imaging to compress job-change cycles below fifteen minutes, though inkjet substitution erodes addressable volume in short-run segments.
- Direct:Laser ablation transfers bitmap data straight to blanket cylinders, bypassing plate intermediates entirely. Direct-to-press architectures suit high-volume publication gravure replacement cycles.
- Laser:Solid-state laser engines deliver 2400+ dpi resolution for fine halftone reproduction in security printing and currency applications.
Thermal systems anchor installed base value today; UV configurations are gaining share fastest in narrow-web label segments.
Application:
Application segmentation tracks how print volume concentration and job-change frequency dictate automation requirements across converter categories.
- Packaging:Folding carton and corrugated post-print lines demand flatbed CTP configurations with instant plate imaging to match e-commerce volume surges. California and Texas packaging hubs accelerate thermal oxidizer retirement to align with EPA emissions guidelines.
- Commercial Printing:Mid-format sheetfed operations in France and Italy consolidate direct-to-press workflows to compress makeready intervals from hours to minutes, though capital intensity barriers delay adoption among smaller printers.
- Labeling:Narrow-web flexographic converters prioritize inline spectrophotometry integration for closed-loop color correction.
- Textile Printing:Roll-to-roll thermal imaging penetrates digital textile transfer segments requiring repeatability across synthetic and natural fiber substrates.
Packaging commands the dominant revenue share; labeling applications demonstrate the steepest expansion trajectory among application categories.
Product Type:
Physical architecture determines substrate handling range, floor space requirements, and integration complexity with upstream prepress and downstream finishing systems.
- Flatbed:Stationary plate exposure beds accommodate oversized corrugated sheets and rigid substrates up to 2-meter widths. Post-print automation in Chinese e-commerce packaging lines drives flatbed CTP penetration for folding carton production.
- Roll-to-Roll:Continuous-feed configurations sustain volume share in publication gravure replacement and flexible packaging segments where web tension control determines print quality consistency.
- Hybrid:Convertible architectures switch between sheetfed and roll-fed modes for commercial printers serving mixed packaging and publication contracts.
- Inline:Direct integration with press units eliminates plate handling entirely, locking in chemistry-free workflows for high-throughput newspaper and insert operations.
Roll-to-roll systems retain volume leadership in publication segments; flatbed configurations climb fastest in corrugated post-print infrastructure.
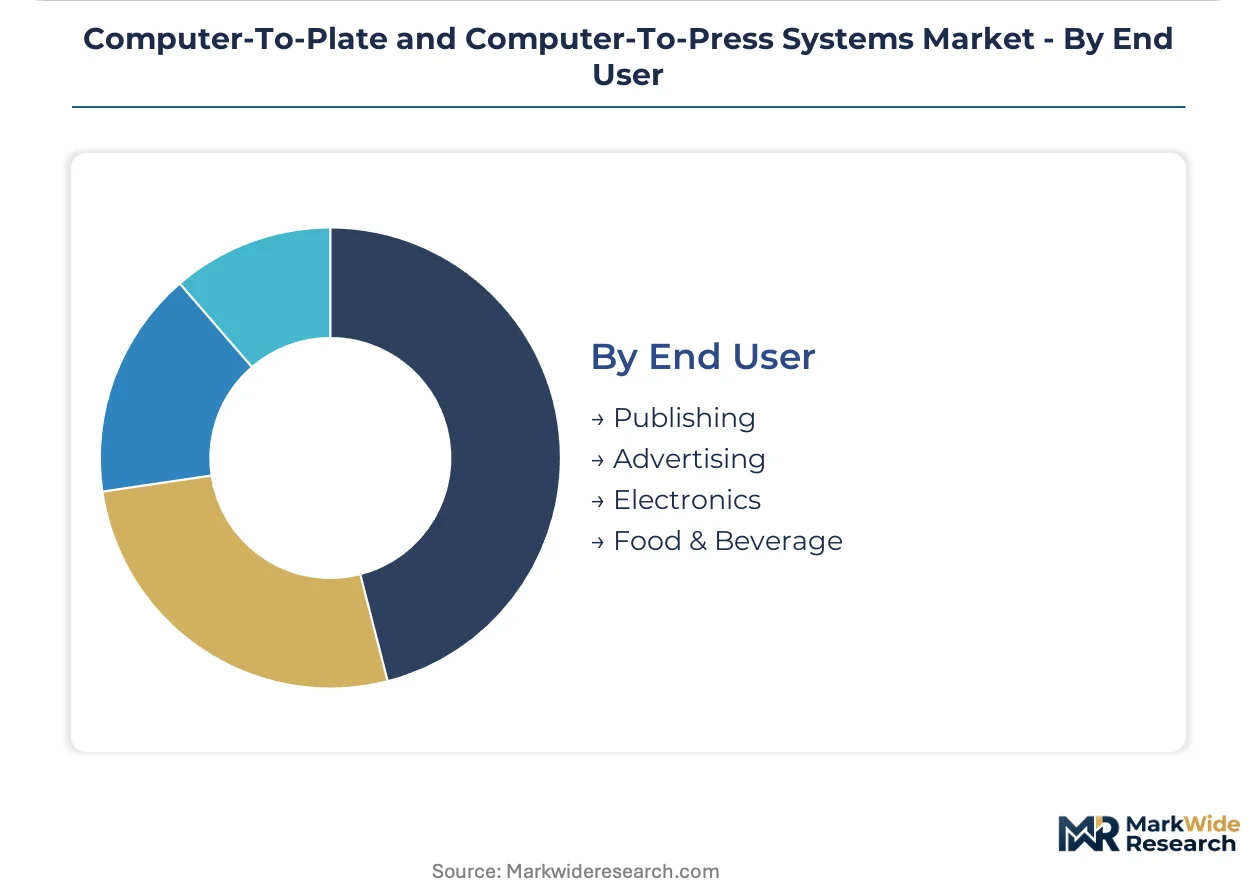
End User:
End-user segmentation exposes how regulatory exposure and brand sustainability commitments reshape procurement priorities across vertical demand pools.
- Publishing:Newspaper and magazine groups in Germany and Japan replace thermal oxidizer-dependent film workflows with direct-imaging engines to satisfy dual carbon enforcement pressures and reduce energy intensity.
- Advertising:Point-of-sale and promotional print buyers prioritize color consistency across distributed production networks, favoring cloud-native color management bundles over standalone equipment.
- Electronics:Printed circuit board and membrane switch manufacturers require sub-10-micron registration accuracy from laser-direct imaging systems.
- Food & Beverage:Brand owners mandate migration to water-wash and thermal plate technologies to eliminate solvent residues in primary packaging, accelerating replacement cycles among contract converters.
Publishing verticals dominate historical installed base; food and beverage end users are expanding most quickly as sustainability specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The computer-to-plate and computer-to-press systems industry traces its commercial origins to German precision engineering traditions, where Heidelberger Druckmaschinen AG pioneered direct-imaging workflows for mid-format commercial printers during the 1990s analog-to-digital transition.
Germany
Packaging converters in Baden-Württemberg and North Rhine-Westphalia consolidate direct-to-press installations to eliminate makeready waste. ECHA REACH phase-down mandates on chromium compounds accelerate thermal plate-setter replacement cycles among commercial printers. Dense service networks from Heidelberg and Komori in the Rhine-Main region lock in consumables volume through captive financing structures.
United States
Corrugated post-print automation in California and Texas drives flatbed CTP penetration for e-commerce packaging lines. EPA emissions guidelines for volatile organic compounds constrain solvent-based plate processing, redirecting capital toward thermal and water-wash alternatives. Midwest commercial print hubs in Illinois and Ohio face legacy MIS integration friction that delays direct-to-press workflow deployment.
China
Domestic printers in the Yangtze River Delta and Pearl River Delta retire thermal oxidizer-dependent film workflows under MEE enforcement of dual carbon targets. Folding carton lines in Guangdong province demand instant plate imaging without film intermediates to match surging e-commerce volumes. Shanghai-based packaging converters redirect capital toward direct-imaging engines with lower energy intensity.
Japan
Narrow-web label producers in the Kanto region adopt UV-curable direct imaging to compress job-change cycles below fifteen minutes. METI industrial standards support closed-loop color correction integration with inline spectrophotometry. Osaka-area flexographic converters face erosion from UV inkjet direct-to-substrate substitution in short-run segments.
India
Mid-tier printers in Maharashtra and Gujarat transition from analog film workflows under BIS standardization of thermal plate chemistry-free processing. Commercial print modernization in the Delhi-NCR corridor opens procurement pathways previously locked into darkroom operations. Western India packaging hubs accelerate thermal oxidizer retirement to align with emerging state-level emissions protocols.
Computer-To-Plate and Computer-To-Press Systems Market Vendor Landscape
Premium-margin players sit above commodity-margin players across service-contract intensity and consumables lock-in structures. The vendor base stratifies between integrated imaging-press ecosystems and standalone plate-setter specialists. Three archetypes dominate: hybrid ink-plate platform vendors, mid-web offset financing bundlers, and narrow-web UV imaging specialists. Competitive moves concentrate on cloud-native color management bundling and regional service network densification.
Within the integrated ecosystem tier, Fujifilm Holdings Corporation and Heidelberger Druckmaschinen AG exemplify platform vendors that anchor recurring revenue through hybrid hardware-software contracts. Eastman Kodak Company occupies a position among legacy imaging specialists transitioning toward chemistry-free thermal workflows. These three companies represent contrasting strategic postures across the premium-to-standard margin spectrum.
| Leading Market Players |
|---|
| Eastman Kodak Company |
| Agfa-Gevaert Group |
| Screen Holdings Co., Ltd. |
| Fujifilm Holdings Corporation |
| Heidelberger Druckmaschinen AG |
| ECRM |
| Mitsubishi Imaging |
| Glunz & Jensen |
| Komori Corporation |
| Others |
Supply Flow & Price Mechanics
Packaging converters in Germany and the United States concentrate procurement decisions around service-contract bundling rather than standalone equipment transactions, anchoring vendor pricing power in long-term consumables lock-in structures. This buyer-archetype concentration elevates subscription-based color management SaaS as the dominant revenue model, displacing perpetual licensing across North American and European commercial print hubs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates thermal plate-setter configurations with inline spectrophotometry from entry-level UV-curable systems lacking closed-loop color correction. Price differentiation rests on chemistry-free certification tier and captive financing availability, with Heidelberg and Komori commanding brand premiums through dense Rhine-Main service networks. Cost compression in mid-format commercial segments intensifies because Italian and Spanish printers face compressed equipment financing access. Smaller converters in Eastern Europe exhibit highest price sensitivity, while German packaging hubs prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Specialized field engineers for thermal plate calibration concentrate in Germany and Japan, leaving peripheral European markets with extended service response timelines and elevated downtime risk. Manufacturing draws from precision optics suppliers in Japan, laser diode fabricators in Germany, and control electronics producers in Taiwan. Single-source vulnerability runs through infrared laser engine suppliers serving thermal imaging architectures. Distribution runs through authorized dealer networks with captive consumables fulfillment, bypassing independent distributors in favor of vendor-direct service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
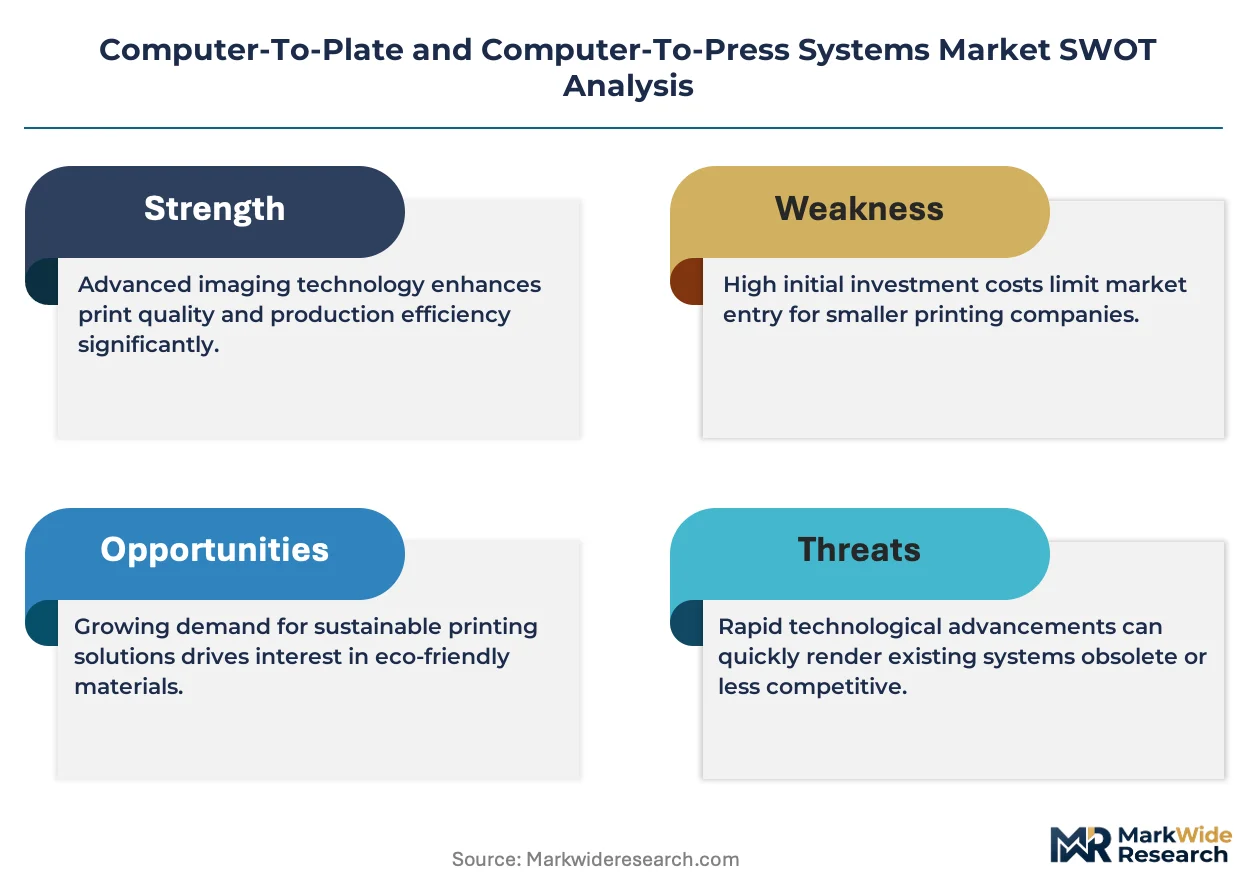
This market offers margin-expansion pathways through chemistry-free thermal workflow substitution, as REACH and EPA mandates compress addressable volume for solvent-based plate processing alternatives.
For Market Incumbents: Cement service-contract renewals by embedding cloud-native color management SaaS into thermal plate-setter hardware bundles, locking in recurring revenue streams against UV inkjet substitution threats in narrow-web label segments. Deepen backward integration into photopolymer plate chemistry to capture consumables margin compression currently leaking to third-party suppliers.
For New Entrants and Emerging Players: Direct-to-press workflow software licensing offers the most penetrable entry vector, targeting mid-tier commercial printers in Maharashtra and Gujarat where BIS standardization has opened procurement pathways previously blocked by analog film infrastructure. Lead with API-level MIS integration capabilities to resolve deployment friction that delays Heidelberg and Komori installations in Midwest United States print hubs.
For Investors and Strategic Acquirers: Hybrid ink-plate platform vendors are the most active acquirer in this space, consolidating narrow-web UV imaging specialists to complete ecosystem coverage across packaging and label segments. Target acquisition candidates with dense service networks in underpenetrated geographies and proven thermal plate chemistry-free certification. Watch for MEE enforcement intensity in China's Yangtze River Delta as the signal indicating accelerated domestic replacement cycle velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Color Management Bundling | Fujifilm anchors recurring revenue in North American packaging hubs through hybrid hardware-software contracts. |
| Thermal Chemistry-Free Certification Investment | Heidelberg satisfies ECHA REACH mandates while eliminating hazardous waste streams from European darkroom operations. |
| Regional Service Network Densification | Komori reduces downtime risk for mid-format commercial printers across Baden-Württemberg and North Rhine-Westphalia. |
| API-Level MIS Integration Development | Resolves legacy job ticketing connectivity friction delaying direct-to-press deployment in Illinois and Ohio print facilities. |
| Backward Integration into Photopolymer Chemistry | Captures consumables margin compression and secures supply continuity for thermal plate production lines. |
Methodological Framework
Coverage spans Germany, the United States, China, Japan, and India, with primary inputs from each market combining structured interviews with prepress operations directors, packaging converter procurement leads, OEM service network managers, and thermal plate chemistry suppliers. Secondary validation draws from ECHA REACH regulatory filings, EPA emissions compliance databases, SEC 10-K equipment revenue disclosures, and BIS standardization notices. Bottom-up equipment shipment tallies triangulate against top-down print industry capital expenditure surveys.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, modeling technology substitution curves between thermal, UV-curable, and direct-to-press architectures alongside application segmentation across packaging, commercial printing, labeling, and publication verticals. CAGRs derive from installed base replacement cycles, regulatory compliance deadlines, and e-commerce packaging volume elasticity. Forecast inputs incorporate MEE dual carbon enforcement timelines and F-Gas Regulation phase-down schedules.
The model assumes a particular technology adoption path; alternative pathways for UV inkjet direct-to-substrate substitution would alter the outlook for lithographic CTP addressable volume in short-run label segments. Forecasts reflect assumptions around REACH and EPA regulatory continuity, thermal plate chemistry supply stability, and service network expansion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Global Barcode Printer Market
Printing Technology
Large Character Printers Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Commercial Printing Outsourcing Market
Printing Technology
Web to Print Market
Printing Technology
Digital Paper System Market
Printing Technology
Large Format Printer Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Card Printers Market
Printing Technology
US Print on Demand Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Photo Printing Market
Printing Technology
ID Card Printers Market