
 Digital Freight Management Market | 2026-2036
Digital Freight Management Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Freight Management Market Outlook
Buyer concentration among large e-commerce and retail shippers is rebalancing negotiating leverage across digital freight platforms. C.H. Robinson Worldwide leverages its North American truckload brokerage network to sustain volume density on its Navisphere platform. SAP SE anchors enterprise demand through embedded transportation management within its broader supply chain suite. Kuehne + Nagel differentiates via ocean freight visibility tools that integrate with its controlled forwarding operations.
Digital freight management encompasses software platforms that automate freight matching, rate procurement, shipment tracking, and carrier compliance through API-connected transportation management systems processing real-time GPS, ELD, and AIS telemetry feeds. Transportation Management solutions dominate current revenue as shippers prioritize centralized control towers, while Software-as-a-Service deployments capture the fastest expansion by eliminating capital barriers for mid-sized freight buyers. Fleet Management modules concentrate margin pools in telematics hardware bundling, and Route Optimization engines extract value from fuel cost volatility.
The EU Green Deal and its delegated acts on transport emissions reporting shape platform requirements across European lanes, while the US EPA SmartWay program filters carrier eligibility for sustainability-minded shippers. India's Ministry of Road Transport and Highways mandates e-way bill integration, forcing platform providers to localize data architectures. Stakeholders must weigh cloud deployment commitments against emerging data sovereignty rules affecting cross-border freight data flows.
Market Dynamics
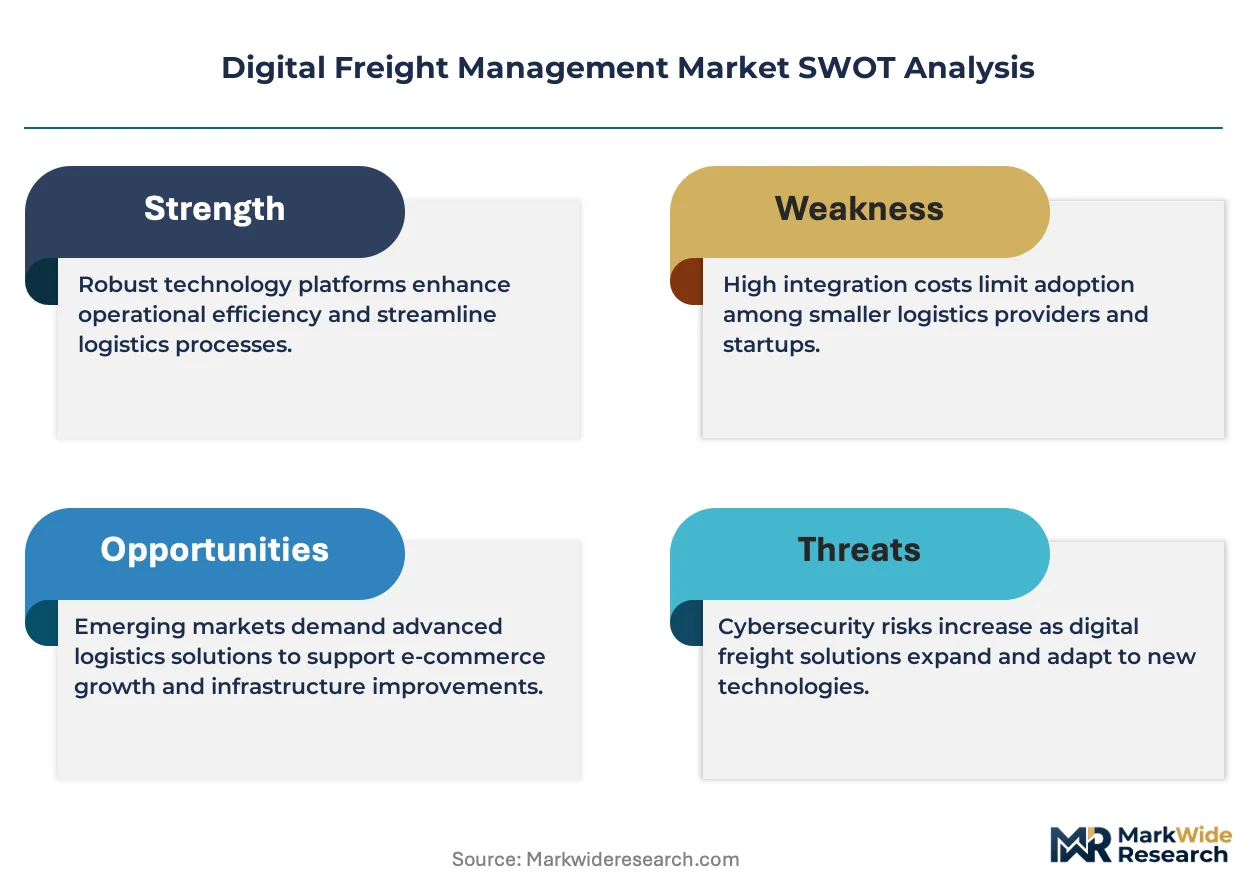
Buyer concentration among large e-commerce and retail shippers is rebalancing negotiating leverage across digital freight platforms, forcing providers to differentiate through embedded sustainability tools and API-first architectures.
Growth Catalysts
- EU Green Deal emissions reporting:Delegated acts on transport emissions reporting mandate platform upgrades for European logistics operators, accelerating investment in carbon accounting modules and carrier scoring algorithms.
- E-commerce freight matching platforms:Online retailers are expanding adoption of automated freight matching to reduce procurement cycle times and improve load consolidation across fragmented carrier networks.
- India's e-way bill integration:The Ministry of Road Transport and Highways mandates real-time data synchronization, forcing platform providers to localize cloud architectures and driving adoption among domestic freight buyers.
Market Restraints
- Telematics hardware bundling costs:Fleet Management modules require upfront capital for GPS and ELD device deployment, compressing margins for mid-sized platform providers competing against subsidized hardware offerings.
- Data sovereignty fragmentation:Cross-border freight data flows face emerging localization requirements across Germany, France, and India, complicating cloud deployment strategies and increasing compliance overhead.
- Legacy TMS substitution threat:On-premise transportation management systems retain entrenched positions in asset-heavy shipper IT stacks, slowing SaaS migration timelines among risk-averse procurement teams.
Strategic Opportunities
- Rhine-Ruhr logistics corridor concentration:Germany's dense freight node offers platform providers a testbed for multimodal optimization engines combining road, rail, and barge routing.
- Route Optimization fuel volatility play:Real-time fuel price integration creates value extraction opportunities as shippers prioritize dynamic rerouting to manage energy cost spikes.
- API-connected control tower convergence:Transportation Management solutions are unifying with supply chain visibility platforms, creating whitespace for vendors offering embedded analytics and predictive exception management.
Industry Challenges
- ELD-GPS-AIS telemetry integration complexity:Platform engineering teams face skill gaps in harmonizing disparate data streams from truck, vessel, and container tracking systems into unified visibility layers.
- Carrier compliance certification timelines:US EPA SmartWay eligibility verification and EU emissions verification protocols create onboarding friction that delays network expansion for sustainability-focused shippers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Freight Management Market |
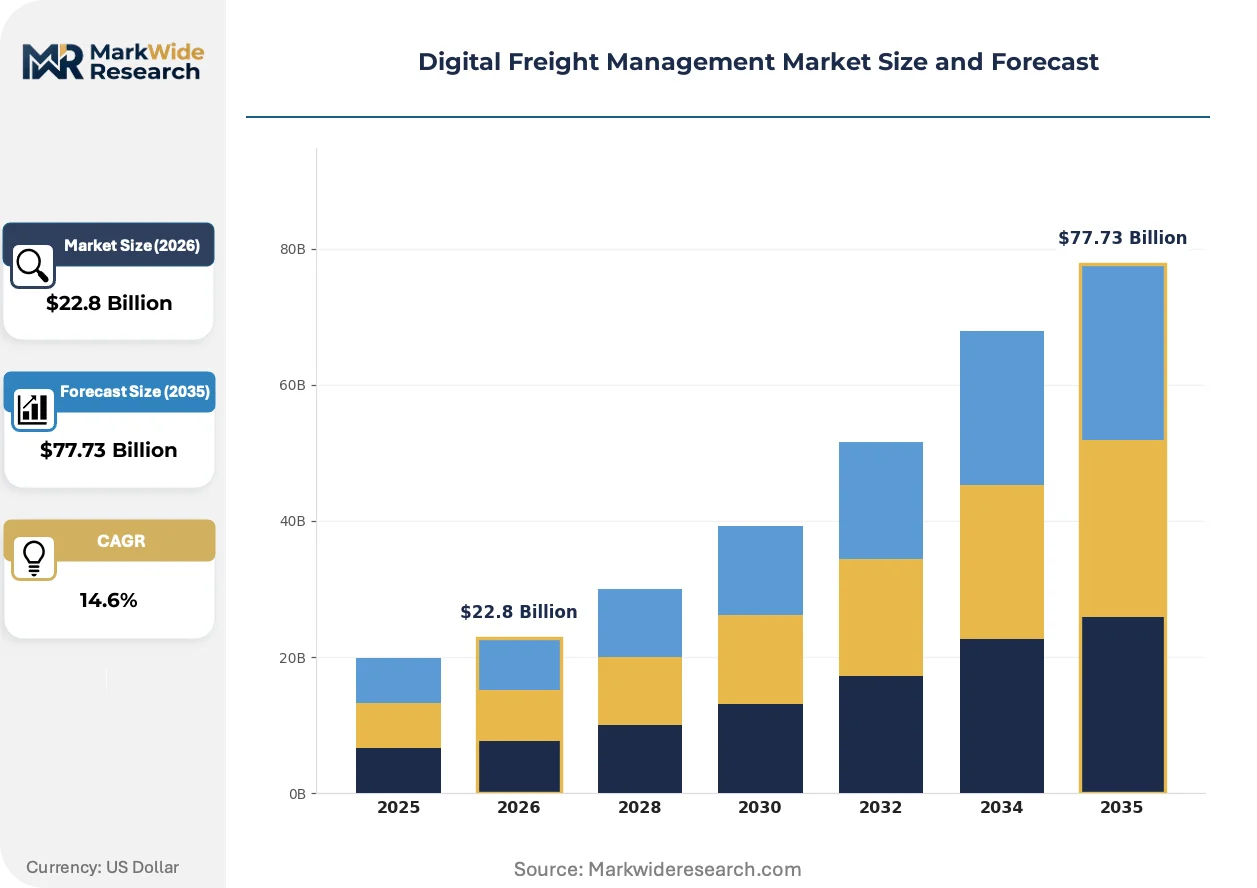
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $77.73 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Transportation Management, Software-as-a-Service, Fleet Management, Route Optimization End User: Retailers, Manufacturers, Logistics Providers, E-commerce Companies Deployment Model: Cloud-based, On-premise, Hybrid, Multi-tenant Service Type: Consulting, Integration, Support & Maintenance, Training |
| Companies Covered | Maersk, C.H. Robinson Worldwide, Kuehne + Nagel, CMA CGM, DSV, Oracle Corporation, SAP SE, Manhattan Associates, Descartes Systems Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Freight Management Market Strategic Shifts
Real-time data infrastructure is compressing decision cycles across freight procurement and execution, while regulatory pressure on emissions transparency is reshaping platform feature roadmaps.
API-connected transportation management systems are unifying previously siloed freight matching, rate procurement, and shipment tracking functions into single-pane control towers. Large retail shippers are adopting these architectures fastest, consolidating vendor relationships and compressing the addressable market for point solutions. The structural consequence is margin pressure on standalone freight matching platforms that lack embedded TMS capabilities.
The EU Green Deal's delegated acts on transport emissions reporting are mandating granular carbon accounting across European lanes. Platform providers must now integrate fuel consumption models, distance-based emission factors, and carrier-specific verification into core workflows. Ocean freight visibility tools face the steepest compliance burden, as maritime operators lag road and air in standardized emissions data collection.
Shippers are consolidating procurement authority into centralized transportation control towers, displacing distributed buying across regional distribution centers. Third-party logistics providers and large manufacturers are the primary adopters, replacing fragmented carrier relationships with platform-mediated spot and contract freight markets. This pattern is most visible in Germany and the Netherlands, where dense logistics networks enable rapid carrier onboarding and price discovery.
Digital Freight Management Market Segmentation
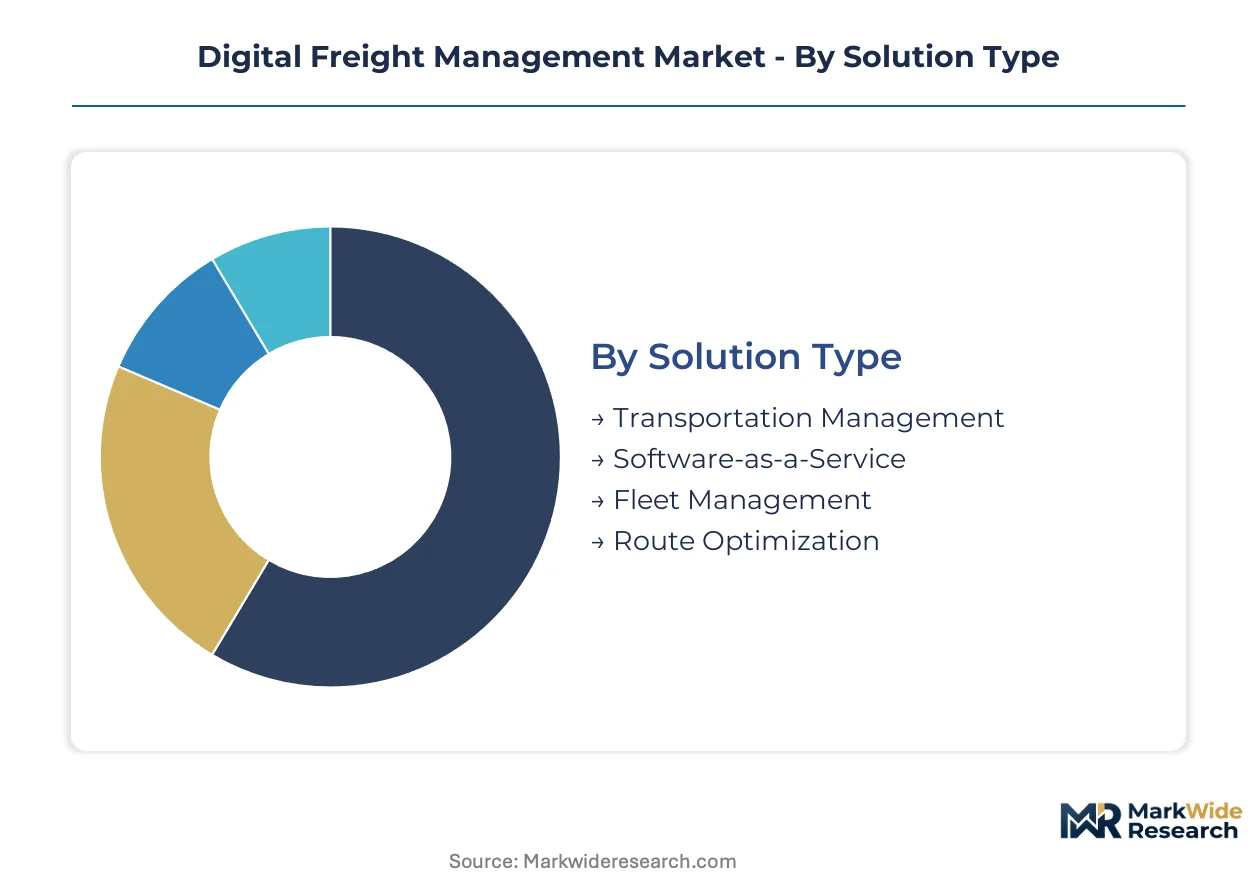
Segmentation in digital freight management reveals how certification burdens, deployment complexity, and end-user scale reshape vendor priorities. Solution architectures diverge sharply between asset-heavy shippers seeking control tower unification and mid-sized buyers eliminating capital barriers through subscription models.
Solution Type:
Transportation Management systems face EU Green Deal emissions verification protocols, while Fleet Management modules trigger telematics hardware certification under US EPA SmartWay and India's AIS-140 standards.
- Transportation Management:Centralized control towers integrate freight matching, rate procurement, and shipment tracking through API-connected architectures. Large retail shippers in Germany's Rhine-Ruhr corridor prioritize these systems to consolidate procurement authority and compress carrier onboarding cycles.
- Software-as-a-Service:Cloud-native deployments eliminate upfront capital requirements through subscription pricing models. Mid-sized freight buyers across fragmented European carrier networks adopt these fastest, driven by compressed IT procurement timelines and reduced implementation risk.
- Fleet Management:Telematics hardware bundling with GPS and ELD devices dominates margin pools.
- Route Optimization:Real-time fuel price integration enables dynamic rerouting against energy cost volatility.
Transportation Management sits at the top of the volume ranking, with Software-as-a-Service climbing the fastest.
End User:
Scale concentration determines platform customization depth, with enterprise retailers demanding embedded sustainability tools and logistics providers requiring multi-tenant architectures for shipper segregation.
- Retailers:Large e-commerce and retail shippers concentrate buying power into centralized transportation control towers, displacing distributed procurement across regional distribution centers. These buyers mandate carbon accounting modules and carrier scoring algorithms under EU emissions reporting requirements.
- E-commerce Companies:Automated freight matching adoption accelerates procurement cycle compression and load consolidation across fragmented last-mile carrier networks. India's e-way bill integration mandates drive platform localization investments for this segment.
- Manufacturers:Asset-heavy IT stacks retain entrenched on-premise TMS positions.
- Logistics Providers:Third-party operators mediate spot and contract freight markets through platform architectures.
Retailers command the largest addressable spend, while E-commerce Companies expand most quickly.
Deployment Model:
Data sovereignty rules fragment cloud strategies, with Germany's localization requirements and India's data residency mandates forcing architecture diversification.
- Cloud-based:Eliminates capital barriers and enables real-time GPS, ELD, and AIS telemetry integration through scalable infrastructure. Compliance overhead rises from emerging data sovereignty rules affecting cross-border freight data flows between European and Asian lanes.
- Hybrid:Combines on-premise control with cloud scalability for sensitive shipment data.
- On-premise:Retains entrenched positions in risk-averse procurement teams.
- Multi-tenant:Logistics providers favor this architecture for shipper data segregation.
Cloud-based deployments dominate new implementations, with Hybrid gaining share fastest among regulated industries.
Service Type:
Implementation complexity and ongoing compliance maintenance drive service attach rates, with integration services capturing premium pricing for telemetry harmonization.
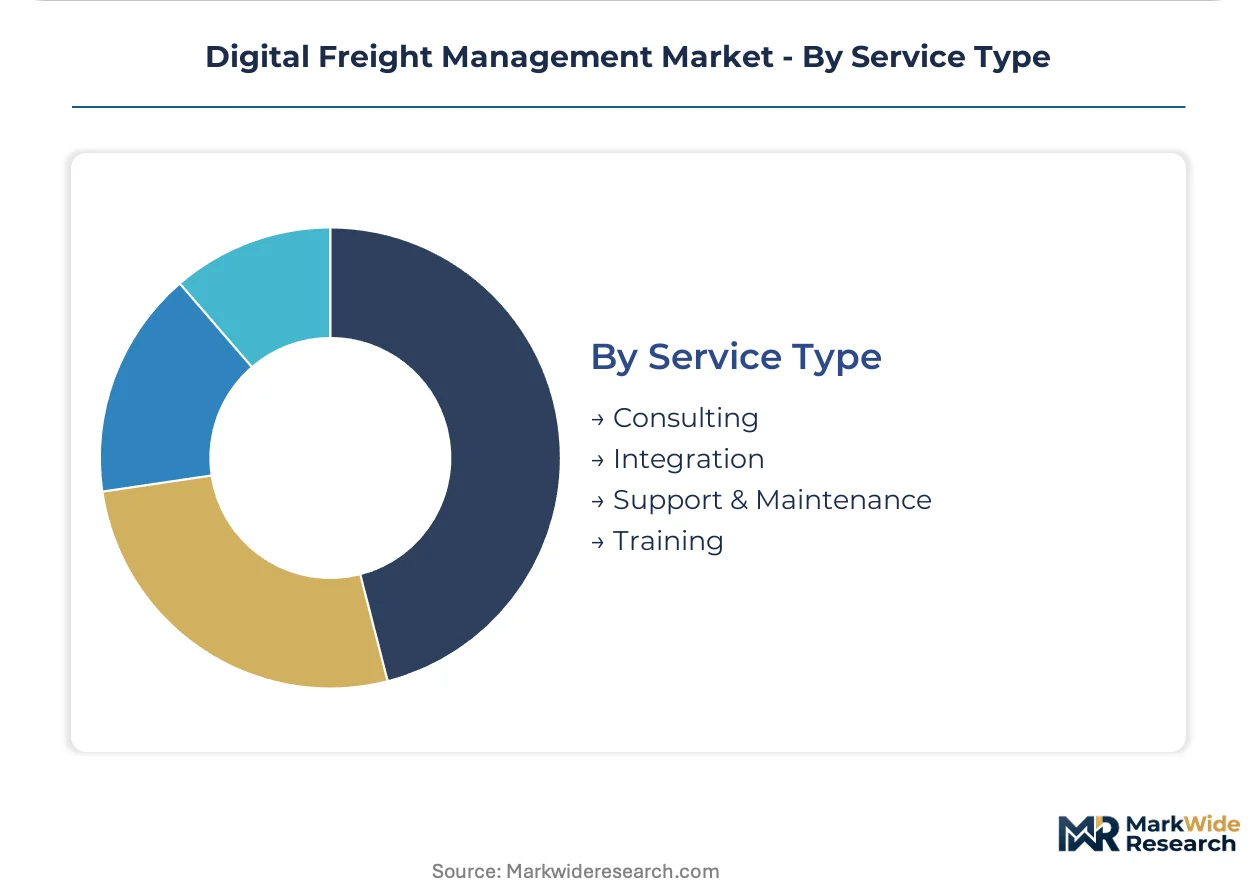
- Integration:Engineering teams face skill gaps in unifying truck ELD, vessel AIS, and container GPS streams into unified visibility layers. These services command premium pricing for API-first architecture deployment and legacy TMS migration support.
- Support & Maintenance:Carrier compliance certification timelines for US EPA SmartWay and EU emissions verification create recurring revenue pools through ongoing eligibility monitoring and platform upgrade management.
- Consulting:Advisory services guide sustainability tool selection and control tower design.
- Training:User enablement accelerates adoption curves for complex multimodal optimization engines.
Integration services generate the highest revenue per engagement, with Support & Maintenance showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr corridor generates denser freight platform adoption than India's emerging logistics hubs, yet both markets face divergent regulatory pressures shaping vendor localization strategies.
United States
Large retail shippers concentrate procurement authority into centralized transportation control towers across the Midwest and Southeast distribution belts. The US EPA SmartWay program filters carrier eligibility through emissions verification protocols that extend platform onboarding timelines. Chicago anchors the densest freight node, where API-first architectures compress spot market price discovery cycles.
Germany
The EU Green Deal's delegated acts mandate granular carbon accounting modules across multimodal freight corridors. KBA vehicle certification requirements intersect with emissions reporting standards for road freight operators. The Rhine-Ruhr logistics cluster serves as the primary testbed for road-rail-barge optimization engines combining real-time telemetry feeds.
India
E-commerce freight matching adoption accelerates among domestic retailers seeking load consolidation across fragmented last-mile carrier networks. The Ministry of Road Transport and Highways mandates e-way bill integration, forcing cloud architecture localization for platform providers. Maharashtra and Gujarat host the steepest platform investment curves as logistics parks densify around Mumbai and Ahmedabad.
China
Dual carbon goals under MEE supervision reshape freight platform feature roadmaps toward emissions transparency tools. GB standards for telematics hardware create certification friction for foreign platform vendors seeking market entry. The Yangtze River Delta concentrates demand for ocean freight visibility tools integrating with port authority data systems.
United Kingdom
Post-Brexit customs data requirements drive platform upgrades for cross-channel freight documentation automation. The UK's independent emissions reporting framework diverges from EU Green Deal protocols, complicating vendor compliance architectures. The Midlands logistics corridor sustains dense adoption of transportation management systems among third-party logistics providers.
Digital Freight Management Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the digital freight management landscape, creating a tiered structure where scale advantages concentrate in integrated logistics providers while agility resides in software-native vendors. The vendor base spans three strategic archetypes: asset-heavy forwarders embedding proprietary platforms, enterprise software vendors anchoring supply chain suites, and independent SaaS providers offering modular point solutions. Competitive moves center on API-first architecture investments and sustainability tool integration as differentiation vectors.
Within the asset-forwarder tier, Maersk and CMA CGM exemplify carriers extending control over digital customer interfaces through captive platform development. SAP SE and Oracle Corporation occupy positions as enterprise software anchors embedding transportation management within broader supply chain suites. C.H. Robinson Worldwide sits within the brokerage-led archetype, leveraging North American truckload density to sustain volume on its Navisphere platform.
| Leading Market Players |
|---|
| Maersk |
| C.H. Robinson Worldwide |
| Kuehne + Nagel |
| CMA CGM |
| DSV |
| Oracle Corporation |
| SAP SE |
| Manhattan Associates |
| Descartes Systems Group |
| Others |
Value Chain & Pricing Dynamics
Telematics hardware costs cascade through platform pricing tiers as GPS and ELD device procurement absorbs margin from mid-sized SaaS providers competing against subsidized bundled offerings from integrated logistics conglomerates.
Pricing Analysis
Capacity additions in India's cloud infrastructure are reshaping price floors for localized platform deployments. Three-tier pricing structure across premium API-first suites, standard control tower modules, and economy freight-matching subscriptions dominates. Price differentiation rests on certification depth under EU Green Deal emissions protocols and US EPA SmartWay verification tiers. Pricing pressure stems from hardware bundling subsidies at Fleet Management specialists. Mid-sized freight buyers exhibit highest price sensitivity; enterprise retailers with centralized procurement authority show lowest.
Supply Chain Analysis
India's data residency mandates and Germany's localization requirements are reshaping cloud architecture sourcing strategies for platform providers. Engineering talent concentrates in India, Germany, and the United States. Raw material dependencies include semiconductor chips for telematics devices, server infrastructure for cloud deployments, and specialized GPS-ELD-AIS sensor components. Single-source vulnerability runs through Taiwan-based chip fabrication for hardware modules. Distribution runs through direct enterprise sales teams and channel partnerships with third-party logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EU Green Deal emissions reporting requirements push shipper procurement toward premium-certified platform tiers with embedded carbon accounting capabilities.
For Market Incumbents: Anticipate margin compression from API-first SaaS challengers by deepening embedded sustainability tool suites and accelerating carrier compliance certification timelines. Prioritize backward integration into telematics hardware production to defend hardware bundling economics against subsidized entrants. Lock in enterprise retail shipper relationships through multi-year control tower contracts with emissions reporting guarantees.
For New Entrants and Emerging Players: Channel partnerships with regional third-party logistics providers offer the fastest path to shipper access without direct enterprise sales infrastructure. Target India's e-way bill integration mandate as the most penetrable regulatory entry point, where localization requirements create friction for global incumbents. Lead with modular freight-matching APIs that embed into existing TMS stacks rather than full platform displacement.
For Investors and Strategic Acquirers: Consolidation pressure builds where standalone freight-matching platforms lack embedded TMS capabilities and face displacement from retail shipper procurement consolidation. Long-term viability favors vendors with multimodal optimization engines spanning road-rail-barge corridors. Target acquisition archetypes include SaaS-native route optimization specialists with real-time fuel price integration. Watch carrier network density in Germany's Rhine-Ruhr corridor as inflection indicator for platform pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Deployment | Enables real-time ELD-GPS-AIS telemetry unification for retail shipper control towers. |
| EU Green Deal Compliance Module Development | Positions platforms for mandatory carbon accounting across European freight lanes. |
| India Cloud Localization Investment | Satisfies Ministry of Road Transport e-way bill mandates for domestic freight buyers. |
| Telematics Hardware Backward Integration | Captures margin pools compressed by subsidized Fleet Management bundling strategies. |
| Rhine-Ruhr Multimodal Optimization Engine | Combines road-rail-barge routing for densest European freight node adoption. |
Study Parameters
Bottom-up shipper procurement modeling reconciled against top-down platform provider revenue tracking forms the analytical core. Primary interviews with transportation management officers, freight procurement directors, carrier compliance managers, and third-party logistics technology leads combined with secondary validation from SEC filings of listed logistics providers, EU transport emissions delegated act documentation, and India's Ministry of Road Transport e-way bill regulatory filings. Cross-referencing bottom-up adoption curves against top-down vendor revenue disclosures ensures triangulation integrity.
Input-output matrices map platform deployment volumes through segmentation dimensions including solution architecture type, end-user scale tier, deployment model, and regional regulatory cluster. CAGRs derive from modeled adoption velocity against baseline penetration estimates. Industry-specific forecast inputs incorporate EU Green Deal implementation timelines and India's e-way bill integration compliance deadlines across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to data sovereignty rule fragmentation and carrier compliance certification timeline extensions. Forecasts reflect documented assumptions regarding regulatory implementation pacing and shipper procurement centralization trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
India Cold Chain Logistics Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United Kingdom Freight and Logistics Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
Global Connected Logistics Market