
 Receptacle Tester Market | 2026-2036
Receptacle Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Receptacle Tester Market Analytics
UL 1436 certification is unwinding competitive access for manufacturers lacking accredited testing laboratory partnerships. Fluke Corporation leverages its calibration network to sustain premium positioning across industrial channels. Klein Tools anchors its presence through deep distribution in residential and contractor supply chains. IDEAL Industries differentiates via specialized product lines targeting electrical contractor workflows.
A receptacle tester is a portable electrical safety instrument designed to verify proper wiring configuration, ground integrity, and polarity in standard AC outlets through indicator lights or digital readouts, typically operating within 90-250V ranges. These devices serve critical functions in preventing shock hazards, equipment damage, and fire risks during installation verification and routine maintenance inspections. Digital testers command attention for their precision and data-logging capabilities, while combination units that integrate GFCI and AFCI testing capture expanding margin pools from consolidated tool preferences. Smart technology segments incorporating Bluetooth connectivity and mobile app integration represent the fastest-growing configuration as field documentation requirements intensify.
NFPA 70 National Electrical Code adoption cycles, OSHA electrical safety standards, and IEC 61543 international specifications collectively shape product design mandates and market access conditions across jurisdictions. The Consumer Product Safety Commission monitors outlet-related incident patterns that indirectly steer inspection frequency and tester deployment rates. Stakeholders must track evolving arc-fault detection requirements and smart building integration standards to align R&D roadmaps with emerging compliance architectures.
Market Dynamics
UL 1436 certification requirements are compressing vendor access as accredited laboratory partnerships become mandatory for North American market entry, forcing smaller manufacturers toward private-label arrangements or exit.
Growth Catalysts
- NFPA 70 NEC Adoption Cycles:Triennial code revisions in the United States mandate replacement of non-compliant testing equipment, creating predictable refresh demand across electrical contractor inventories.
- Smart Building Integration:Bluetooth-enabled testers with mobile app documentation capabilities are capturing preference from facility managers requiring audit trail compliance for commercial property insurance.
- Metropolitan Construction Corridors:Concentrated infrastructure investment in Dallas-Fort Worth, Toronto, and Phoenix is driving localized tester procurement through regional electrical supply houses.
Market Restraints
- Semiconductor Component Volatility:Microcontroller availability constraints from Asian foundry concentration create production scheduling uncertainty for digital tester assembly.
- Laboratory Accreditation Bottlenecks:Limited UL 1436 testing capacity extends certification timelines to 14-18 months for new product introductions.
- Basic Analog Substitution:Low-cost indicator-light testers from unbranded Asian manufacturers capture price-sensitive residential maintenance segments.
Strategic Opportunities
- Canadian Market Expansion:CSA C22.2 No. 160 adoption lags US NEC alignment, creating first-mover advantage for pre-certified product lines in Vancouver and Calgary construction markets.
- Data Center Commissioning:Hyperscale facility buildouts require specialized 208V three-phase receptacle verification protocols absent from standard residential tester specifications.
- OSHA Electrical Safety Directive:Enhanced workplace inspection mandates for qualified person verification are expanding tester deployment beyond installation into ongoing maintenance protocols.
Industry Challenges
- Firmware Validation Expertise:Digital tester development requires embedded systems engineering talent scarce among legacy analog instrument manufacturers.
- Multi-Jurisdiction Certification Stacking:Simultaneous UL, CSA, and IEC 61543 compliance creates documentation burden and test protocol conflicts for unified product architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Receptacle Tester Market |
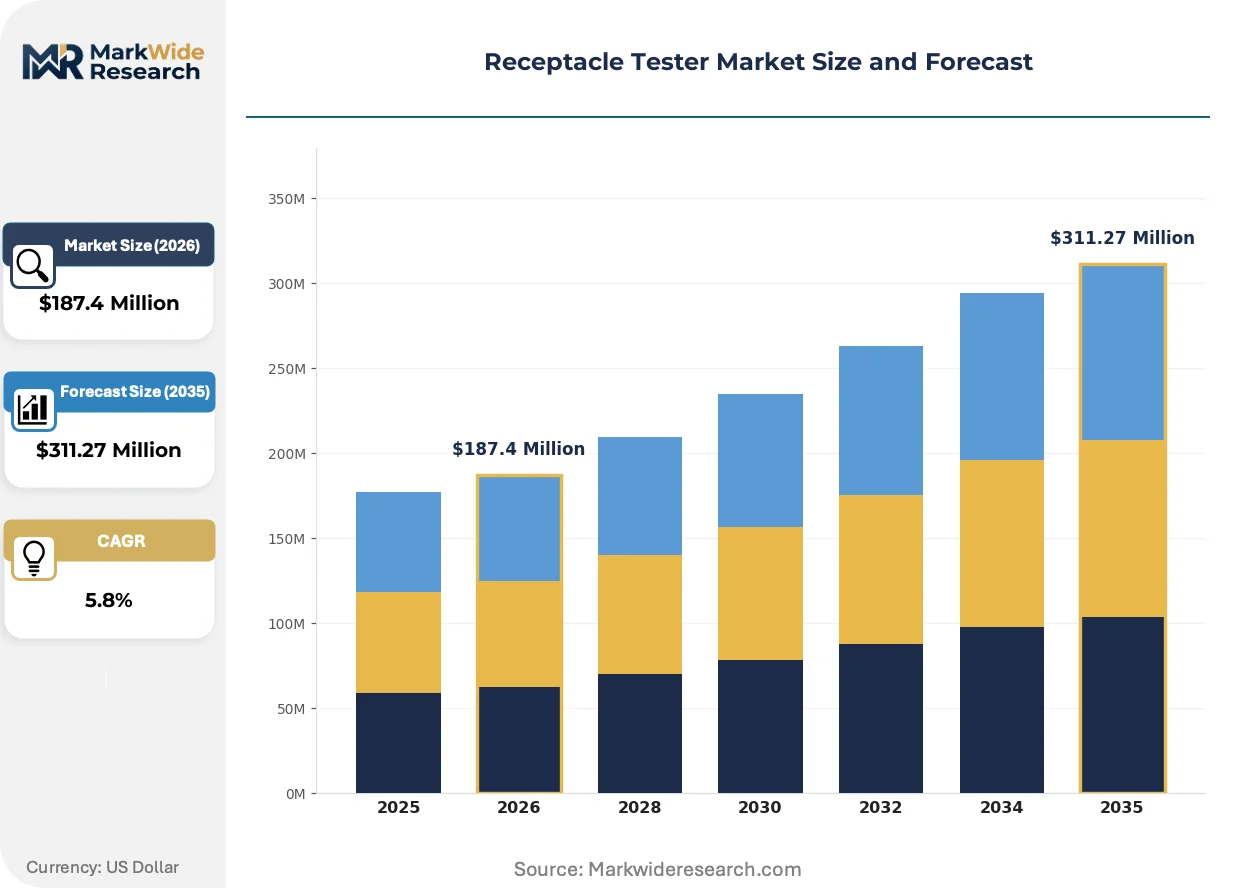
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Tester, Digital Tester, Combination Tester, Network Tester Application: Commercial Buildings, Residential, Industrial Facilities, Electrical Contractors Technology: Smart Technology, Voltage Detection, Ground Testing, Low Voltage Testing End User: Electricians, Engineers, Homeowners, Inspectors |
| Companies Covered | Fluke Corporation, Klein Tools, IDEAL Industries, Southwire Company, Megger Group Limited, Testo SE & Co. KGaA, Hubbell Incorporated, Extech Instruments, Amprobe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Receptacle Tester Market Evolving Landscape
Connectivity integration and automated documentation are displacing standalone instruments across commercial and industrial inspection workflows. Field technicians now expect seamless data export rather than manual recording.
Non-contact voltage detection fused with receptacle testing is decomposing the traditional multi-tool carry requirement for electrical contractors. Single-unit consolidation reduces belt weight and tool inventory overhead. Large commercial contractors in Texas and Florida are standardizing on combination units for efficiency gains during rough-in inspections.
OSHA's updated electrical safety standards are mandating documented verification of de-energized circuits before receptacle testing in industrial environments. This procedural layering extends inspection timeframes and increases tester utilization rates. Manufacturing facilities in Ohio and Michigan are responding with dedicated tester fleets per maintenance shift rather than shared pool arrangements.
Electrical supply house counter sales are yielding to direct contractor e-procurement with will-call fulfillment. Klein Tools and IDEAL Industries have enabled real-time inventory visibility through distributor portal integration. Independent contractors in Atlanta and Denver now specify exact model configurations online before physical pickup, compressing purchase decision cycles from days to hours.
Receptacle Tester Market Segmentation
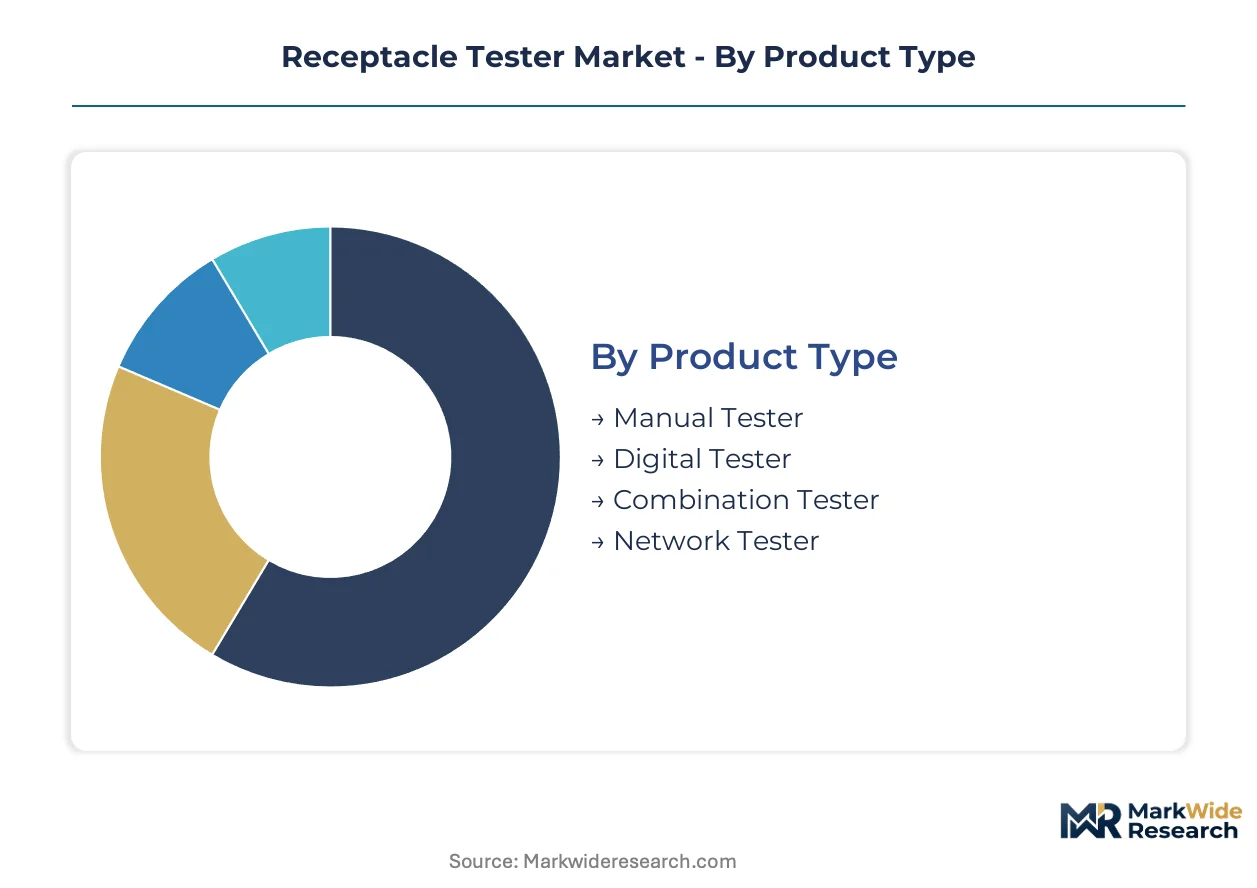
Receptacle tester segmentation reveals divergent margin architectures across product configurations and buyer profiles. Understanding where value concentrates within each dimension enables targeted portfolio positioning against distinct procurement workflows and compliance requirements.
Product Type:
Margin pools concentrate in multifunction units that consolidate multiple verification protocols into single instruments, commanding price premiums over basic configurations while reducing contractor tool inventory overhead.
- Manual Tester:Simple indicator-light devices operating through basic circuit completion detection without digital processing. Demand clusters in residential maintenance segments across price-sensitive homeowners in Phoenix and Dallas-Fort Worth metropolitan construction corridors where code compliance verification requires minimal documentation.
- Digital Tester:Microprocessor-based instruments delivering precise voltage readings, polarity confirmation, and ground impedance measurements with LCD or LED numeric displays. Electrical contractors in Toronto and Vancouver specify these units for commercial rough-in inspections where measurement accuracy supports warranty documentation and liability protection.
- Combination Tester:Integrated GFCI and AFCI testing capabilities within standard receptacle verification protocols. OSHA electrical safety directive compliance is expanding deployment in Ohio and Michigan manufacturing facilities.
- Network Tester:Specialized instruments validating structured cabling termination and Ethernet signal integrity through receptacle-mounted RJ45 connections. Data center commissioning protocols in hyperscale facility buildouts require these specifications absent from standard electrical verification tools.
Manual testers hold installed capacity across residential maintenance segments. Digital testers are rotating up the share rankings in commercial contractor inventories.
Application:
Volume concentration tracks metropolitan construction investment intensity, with procurement patterns differentiating between new installation workflows and ongoing maintenance protocols.
- Commercial Buildings:Multi-tenant office, retail, and hospitality properties requiring periodic electrical safety verification for property insurance compliance and tenant safety certification. Facility managers in Atlanta and Denver are standardizing on Bluetooth-enabled documentation capabilities for audit trail generation.
- Residential:Single-family and multi-family dwelling inspections driven by home sale transactions, renovation permitting, and homeowner safety awareness. Basic analog substitution pressure from unbranded Asian manufacturers captures price-sensitive segments in this category.
- Industrial Facilities:Manufacturing plants, warehouses, and processing operations where OSHA mandates documented verification of de-energized circuits before receptacle testing. Ohio and Michigan facilities are responding with dedicated tester fleets per maintenance shift.
- Electrical Contractors:Professional installation and service firms representing the core buyer segment where adoption strengthens through deep distribution relationships and NEC revision cycle replacement demand.
Commercial buildings anchor procurement volume through facility management standardization. Industrial facilities are expanding tester utilization rates fastest under enhanced workplace inspection mandates.
Technology:
Smart connectivity features command expanding margin premiums as field documentation requirements intensify across commercial property insurance and regulatory compliance frameworks.
- Smart Technology:Bluetooth-enabled testers with mobile app integration for automated data logging, photo documentation, and cloud-based report generation. Facility managers requiring audit trail compliance are capturing these capabilities for commercial property insurance verification in Texas and Florida markets.
- Voltage Detection:Non-contact sensing circuits fused with receptacle testing functionality, decomposing traditional multi-tool carry requirements for electrical contractors. Large commercial contractors are standardizing on these combination units for efficiency gains during rough-in inspections.
- Ground Testing:Dedicated ground impedance measurement protocols verifying earth connection integrity beyond basic continuity detection. NEC triennial revision cycles mandate replacement of non-compliant equipment in contractor inventories.
- Low Voltage Testing:Specialized verification for control circuits, doorbell transformers, and landscape lighting systems operating below standard 120V residential distribution.
Voltage detection holds installed capacity through contractor belt consolidation preferences. Smart technology is climbing the fastest as documentation automation displaces manual recording workflows.
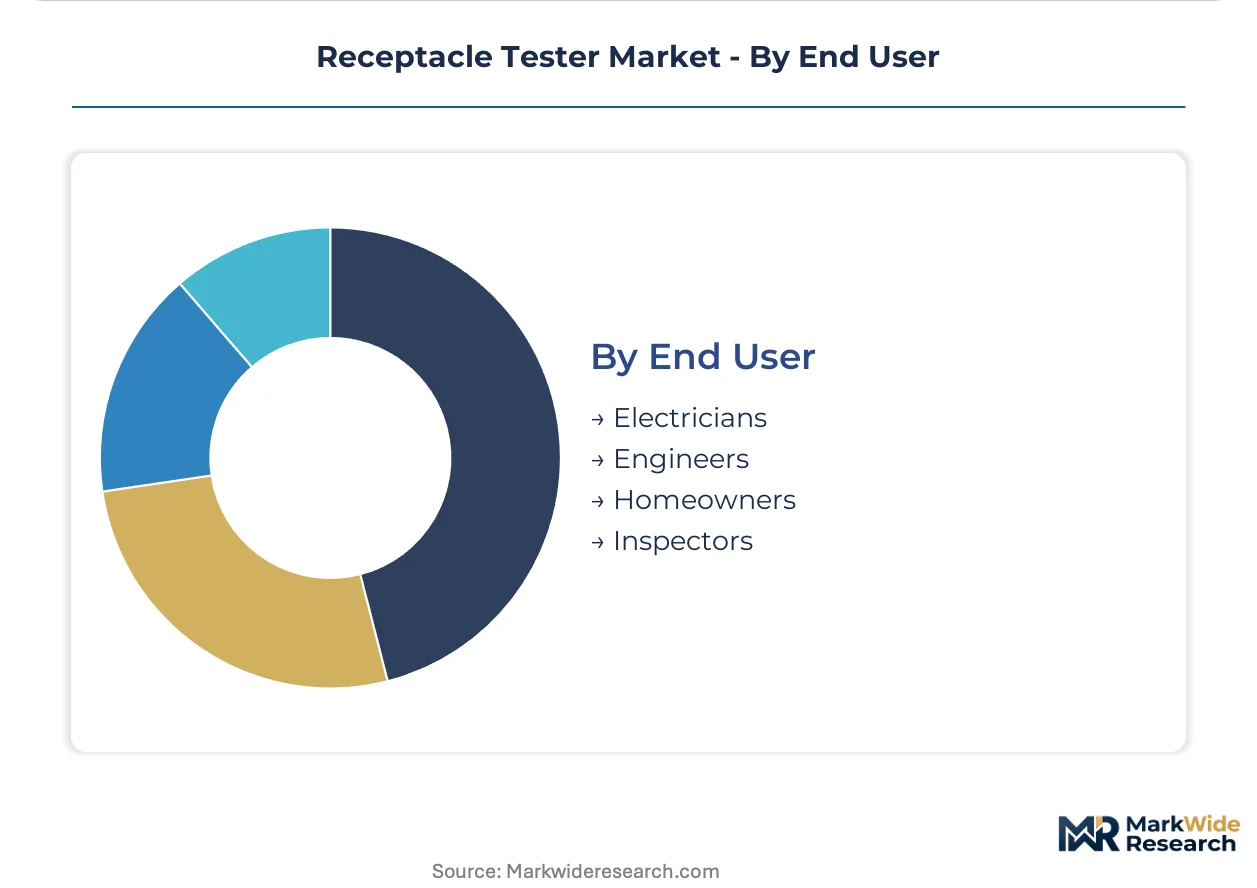
End User:
Professional versus amateur buyer differentiation shapes price architecture, feature prioritization, and channel strategy across direct procurement and retail distribution.
- Electricians:Licensed trade professionals requiring durable, accurate instruments for daily field deployment with calibration traceability and warranty support. Deep distribution through electrical supply house counter sales yields to direct e-procurement with will-call fulfillment in Atlanta and Denver markets.
- Engineers:Design and commissioning specialists specifying precision instrumentation for system validation and acceptance testing protocols. Data center commissioning requirements drive specialized 208V three-phase receptacle verification needs.
- Homeowners:Non-professional users conducting basic safety verification for DIY installations and pre-purchase home inspections. Price sensitivity favors basic analog substitution from unbranded manufacturers.
- Inspectors:Municipal and third-party compliance officials requiring documented verification for code enforcement and certificate of occupancy issuance. UL 1436 certification requirements compress vendor access for this segment.
Electricians anchor professional-grade volume through contractor supply chain relationships. Inspectors are rotating up the share rankings as code enforcement documentation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NFPA 70 NEC triennial revision cycles in the United States generate predictable equipment replacement demand, while CSA C22.2 No. 160 adoption lags create first-mover openings in Canadian metropolitan construction corridors. Germany's DIN VDE standards and Japan's JIS C 1010 specifications shape parallel compliance architectures across industrialized markets.
United States
Electrical contractors in Dallas-Fort Worth and Phoenix metropolitan construction corridors drive concentrated procurement through regional supply houses. OSHA electrical safety standards mandate documented verification protocols in Ohio and Michigan manufacturing facilities. NEC triennial code revisions force replacement of non-compliant testing equipment across contractor inventories nationwide.
Canada
CSA C22.2 No. 160 certification requirements lag US NEC alignment, creating timing advantages for pre-certified product lines. Vancouver and Calgary construction markets show accelerating demand for compliant verification instruments. Health Canada monitors electrical safety incident patterns that indirectly shape inspection frequency mandates.
Germany
DIN VDE 0701-0702 standards govern electrical equipment testing protocols across industrial maintenance workflows. Bavaria and North Rhine-Westphalia manufacturing clusters deploy specialized verification instruments for three-phase industrial distribution systems. The country's national electrical safety regulator enforces stringent calibration traceability requirements for professional-grade equipment.
Japan
METI oversees JIS C 1010 safety standards that constrain market access for non-compliant instrumentation. Kanto and Kansai industrial corridors concentrate demand from precision manufacturing facilities requiring documented ground integrity verification. The country's electrical equipment inspection regime extends tester utilization rates beyond installation into ongoing maintenance protocols.
China
GB standards administered by SAMR establish domestic certification requirements for electrical safety instrumentation. Yangtze River Delta and Pearl River Delta manufacturing hubs generate demand for export-compliant verification equipment. MIIT industrial policy directives increasingly emphasize smart building integration standards that favor connected testing devices.
Receptacle Tester Market Competitive Landscape
Listed leaders compete with private specialists across certification networks and distribution depth. The vendor base stratifies into three tiers: premium-calibration providers, contractor-channel specialists, and price-competitive volume manufacturers. Consolidation pressure concentrates among accredited laboratory partners holding UL 1436 certification authority. Dominant competitive moves include strategic partnerships with testing laboratories and geographic expansion into laggard certification markets.
Within the premium-tier vector, Fluke Corporation anchors calibration-network positioning across industrial channels. Klein Tools and IDEAL Industries exemplify contractor-channel specialists with deep electrical supply house relationships. These three entities represent divergent strategic archetypes: precision instrumentation heritage, trade-focused distribution mastery, and workflow-optimized product architecture respectively.
| Leading Market Players |
|---|
| Fluke Corporation |
| Klein Tools |
| IDEAL Industries |
| Southwire Company |
| Megger Group Limited |
| Testo SE & Co. KGaA |
| Hubbell Incorporated |
| Extech Instruments |
| Amprobe |
| Others |
Value Network & Pricing Analysis
Accredited laboratory capacity utilization at UL facilities shapes both certification timelines and manufacturer cost structures, compressing margins for smaller vendors unable to secure priority testing slots while entrenching premium positioning for incumbents with established laboratory partnerships.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with UL 1436-accredited products commanding substantial premiums over unbranded alternatives lacking accredited laboratory validation. Three-tier pricing structure across premium, standard, and economy levels reflects calibration traceability, warranty duration, and bundled service offerings. Cost compression in the economy tier is intensifying because unbranded Asian manufacturers flood residential maintenance segments with basic indicator-light substitutes. Electrical contractors demonstrate lowest price sensitivity due to liability exposure and documentation requirements, while homeowners exhibit highest sensitivity and trade accuracy for unit cost.
Supply Chain Analysis
Extended lead times for microcontroller components from Taiwanese and South Korean foundries are forcing manufacturers to hold larger strategic inventories of digital tester assemblies. Component sourcing draws from China for plastic housings and indicator LEDs, Mexico for cable assemblies, and Taiwan for microcontrollers. Single-source vulnerability concentrates in advanced microcontroller supply where foundry allocation prioritizes automotive and consumer electronics. Distribution runs through electrical supply house networks with will-call fulfillment, though direct e-procurement portals are compressing purchase decision cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through UL 1436 certification creates durable barriers against unaccredited competitors, locking in incumbent advantages through mandatory laboratory partnerships that smaller players cannot replicate.
For Market Incumbents: Consolidate laboratory accreditation relationships through exclusive testing capacity agreements or captive laboratory investments, securing priority certification slots that compress new product introduction timelines. Deepen backward integration into calibration services and firmware development capabilities, countering the emerging threat from semiconductor-constrained digital entrants by controlling critical component validation pipelines.
For New Entrants and Emerging Players: Documentation automation gaps in Canadian metropolitan construction corridors represent the most penetrable white-space opportunity, where CSA C22.2 No. 160 adoption lags create timing advantages for pre-certified product lines. Target facility management segments in Vancouver and Calgary with Bluetooth-enabled units priced below Fluke Corporation premiums but above unbranded substitutes, leveraging direct contractor e-procurement channels to bypass established supply house relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among calibration-service providers and firmware-enabled digital testers with subscription documentation platforms, suggesting durable cash flow quality in these archetypes. Acquisition candidates should display established UL laboratory partnerships and embedded contractor distribution relationships as primary defensive assets. Watch for inflection when OSHA electrical safety directive enforcement intensity crosses thresholds that mandate dedicated tester fleets per maintenance shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Accredited Laboratory Partnership | UL 1436 certification access determines North American market entry viability for new product introductions. |
| Firmware Development Investment | Embedded systems capabilities differentiate digital testers from analog substitutes in contractor workflows. |
| Bluetooth Connectivity Integration | Mobile app documentation captures facility manager preference for audit trail compliance verification. |
| Canadian Market Pre-Certification | CSA C22.2 No. 160 timing advantages create first-mover positioning in Vancouver and Calgary construction. |
| Calibration Service Expansion | Recurring revenue streams from annual calibration deepen customer lock-in beyond initial equipment sales. |
Research Methodology
Initial hypotheses were tested against primary input from electrical contractor purchasing managers, facility maintenance directors, electrical supply house counter sales representatives, and UL laboratory certification specialists and refined through secondary validation against NEC code revision documentation, OSHA electrical safety directive filings, CPSC incident pattern databases, and customs trade data on electrical instrumentation imports. Bottom-up demand modeling from metropolitan construction permit data was triangulated against top-down market sizing from accredited laboratory certification volumes.
Variance decomposition across product type, application, technology tier, and end-user archetype dimensions enabled identification of growth contribution by segment. CAGRs were derived from installed base rotation rates and replacement cycle analysis tied to NEC triennial revision timing. Industry-specific forecast inputs included semiconductor lead time indices from Asian foundry disclosures and electrical contractor inventory survey data from regional supply house networks.
Underlying assumptions cover continued NEC adoption cycle regularity and stable laboratory accreditation capacity, with deviation risk concentrated in semiconductor component availability and trade policy shifts affecting Asian manufacturing inputs. Revision becomes warranted when OSHA enforcement intensity or smart building integration standard adoption crosses thresholds that accelerate equipment replacement beyond modeled baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Shock Testing System Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Tribometer Market
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Global Reflux Testing Products Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
Global in Circuit Tester Market