
 Digital Cinema Projectors Market | 2026-2036
Digital Cinema Projectors Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Cinema Projectors Market Analysis
Modular projector-lens bundles with integrated media servers is consolidating buyer choice across premium and mid-tier cinema installations. Barco NV leverages its captive laser phosphor supply chain to sustain margin control in large-format deployments. Sony Corporation anchors its position through native 4K SXRD panels that dominate flagship auditorium retrofits in Japan and Western Europe. Christie Digital Systems competes on service density, operating the most extensive field-engineering network among North American projector vendors.
Digital cinema projectors are precision optoelectronic systems that modulate light through DLP, LCoS, or laser-phosphor engines to achieve luminance outputs exceeding 30,000 lumens for screens exceeding 20 meters in width. Their primary commercial purpose is studio-compliant theatrical exhibition meeting Digital Cinema Initiatives specifications for color gamut, resolution, and content security. DLP technology leads installed base volume due to Texas Instruments' long-standing chipset supply relationships with tier-one OEMs, while laser projection captures the fastest expansion as xenon lamp replacement cycles accelerate operating-cost comparisons. Fixed installations concentrate the majority of revenue as multiplex operators prioritize standardized ceiling-mounted configurations over portable units for permanent auditorium builds.
The Digital Cinema Initiatives specification governs image quality and encryption standards, while the EU F-Gas Regulation pressures exhibitors toward laser-based cooling systems that eliminate high-global-warming-potential refrigerants. The US FAA maintains indirect influence through certification requirements for projector transport in cargo configurations affecting international logistics. Stakeholders must monitor how regional content quota laws reshape screen deployment patterns and whether laser-illuminated retrofit demand sustains once xenon lamp inventories fully deplete.
Market Dynamics
Laser illumination is systematically displacing xenon lamp architectures across theatrical exhibition, compressing replacement cycles and rewiring procurement economics for multiplex operators worldwide.
Growth Catalysts
- Laser Phosphor Technology:Solid-state illumination eliminates lamp replacement costs and reduces cooling loads, pulling exhibitors toward retrofit decisions.
- EU F-Gas Regulation:Restrictions on high-global-warming-potential refrigerants mandate laser-based cooling systems for new auditorium builds across European Union member states.
- China Screen Expansion:Concentrated new cinema construction in tier-two and tier-three Chinese cities sustains hardware procurement volumes for premium large-format installations.
Market Restraints
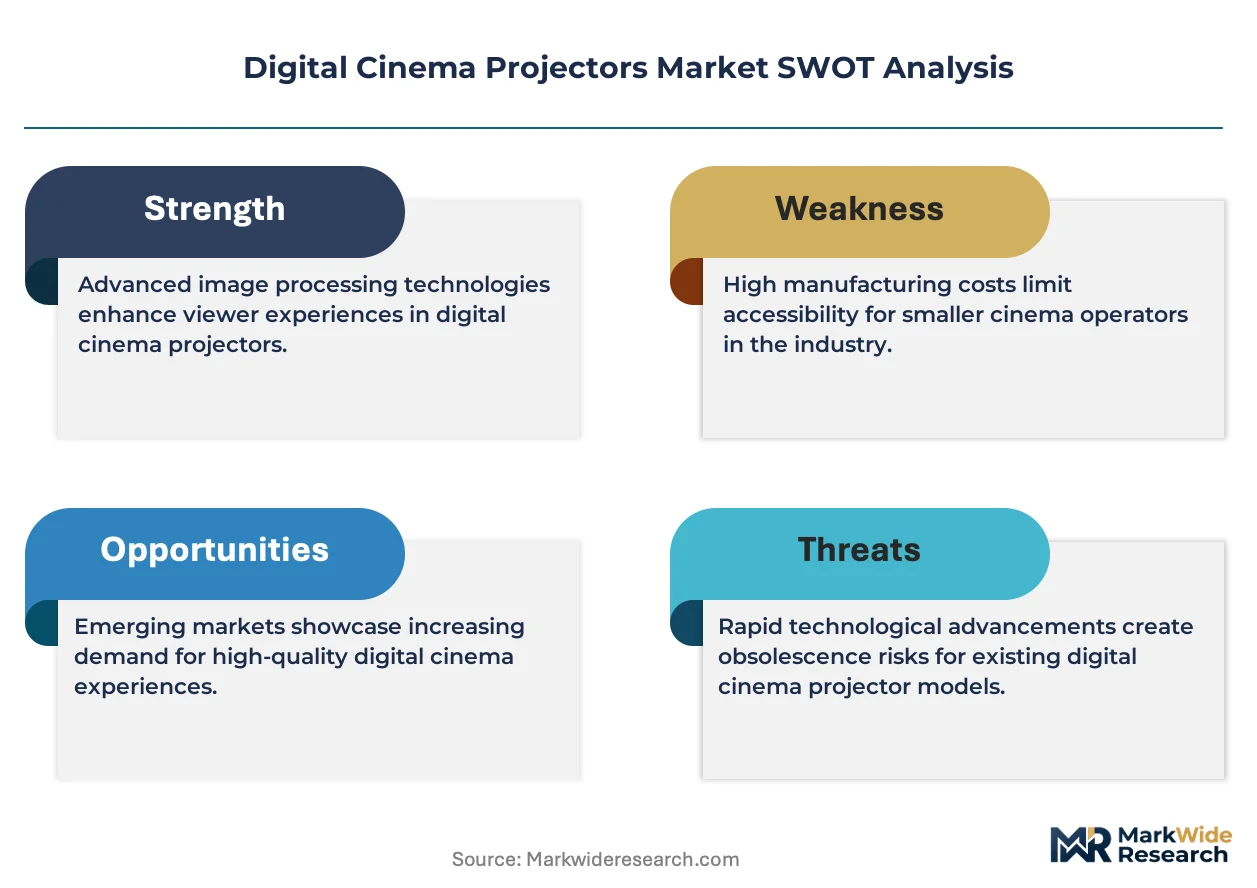
- Upfront Capex Compression:Laser projector units command substantially higher initial investment than legacy xenon systems, extending payback periods for independent exhibitors.
- Texas Instruments DLP Chipset Concentration:Single-source dependency for DLP cinema chipsets creates supply vulnerability for tier-one OEM production schedules.
- Content Pipeline Volatility:Theatrical release window compression and streaming platform competition threaten screen utilization rates and replacement demand timing.
Strategic Opportunities
- India Multiplex Modernization:Underpenetrated premium screen formats in Indian metro markets present retrofit potential as PVR-Inox and Cinepolis expand large-format footprints.
- Integrated Media Server Convergence:Bundled projector-server-lens packages reduce installation complexity and open mid-tier auditorium standardization opportunities.
- Digital Cinema Initiatives Compliance Mandates:Studio tightening of DCI specification enforcement creates forced-upgrade cycles for non-compliant legacy installations.
Industry Challenges
- Field Engineering Talent Scarcity:Specialized laser calibration and optical alignment skills remain concentrated among veteran technicians, constraining service network expansion.
- Legacy Xenon Infrastructure Stranding:Existing lamp-based projector fleets carry sunk costs that complicate ROI calculations for laser migration decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Cinema Projectors Market |
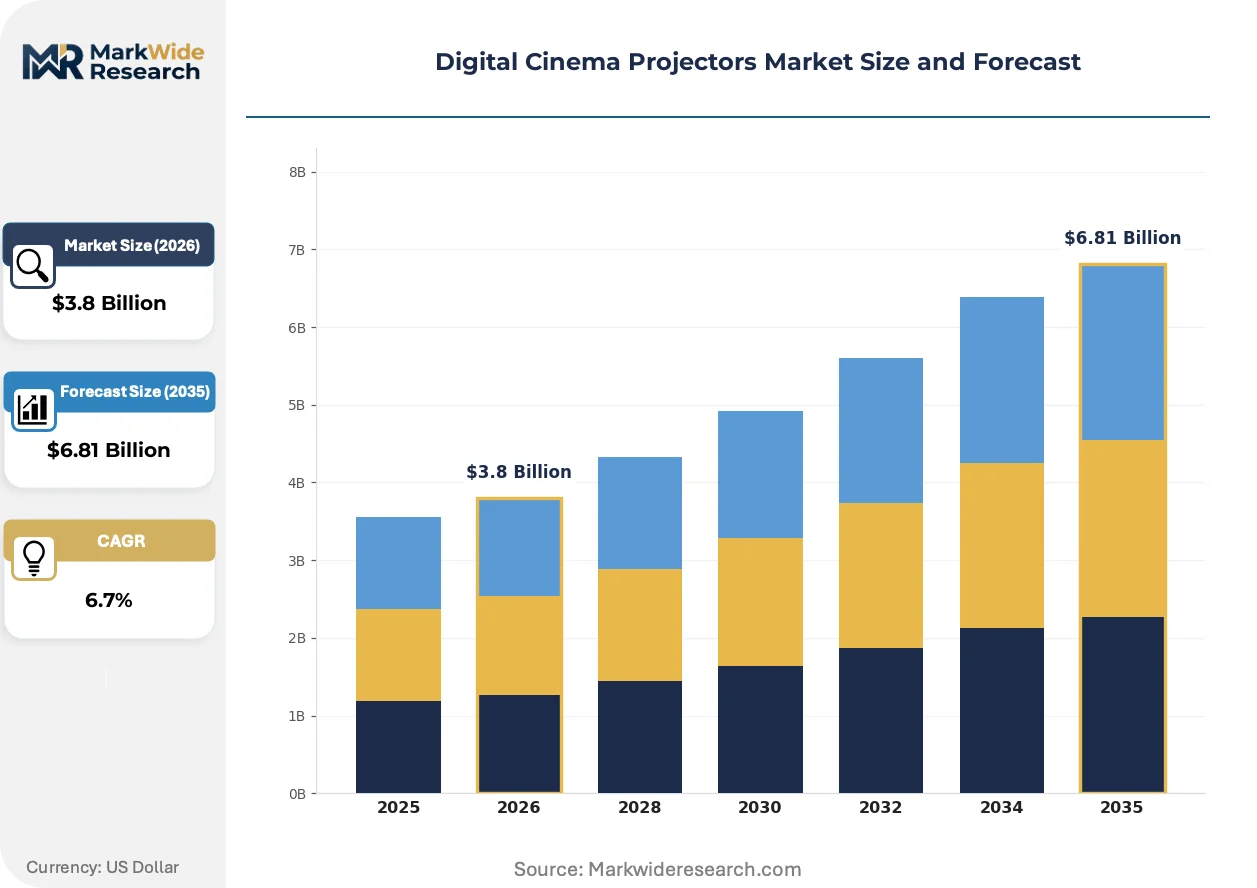
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DLP, LCoS, LED, 4K Technology: Digital Projection, Laser Projection, Hybrid, Cathode Ray End User: Cinemas, Film Festivals, Home Theaters, Event Venues Installation: Fixed, Portable, Ceiling-Mounted, Floor-Mounted |
| Companies Covered | Panasonic Corporation, Canon Inc., Sony Corporation, NEC Display Solutions, Delta Electronics, Barco NV, Seiko Epson Corporation, JVCKenwood Corporation, Christie Digital Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Cinema Projectors Market Emerging Trajectories
Three intersecting developments are restructuring how theatrical exhibition hardware is specified, procured, and maintained across developed and emerging cinema markets simultaneously.
RGB pure laser architecture is electrifying high-luminance projection for premium large-format screens exceeding 25 meters in width. Major exhibition chains in Japan and South Korea are prioritizing RGB systems for flagship auditorium renovations. This technology is electrifying competitive differentiation strategies as exhibitors seek to justify ticket premiums through measurable brightness and color gamut superiority.
The EU F-Gas Regulation is accelerating refrigerant-phaseout timelines that directly impact xenon projector cooling system compliance. European exhibitors face mandated equipment replacement or costly cooling retrofits for existing lamp-based installations. Germany and France are witnessing the fastest compliance-driven laser upgrade cycles as national environmental agencies tighten enforcement protocols.
Service contract unbundling is fragmenting traditional procurement relationships between exhibitors and OEMs. North American multiplex operators are separating hardware acquisition from maintenance agreements, engaging third-party field service networks for laser phosphor calibration and optical engine replacement. This pattern is most pronounced in Texas and California exhibition clusters where independent service providers have achieved critical mass.
Digital Cinema Projectors Market Segmentation
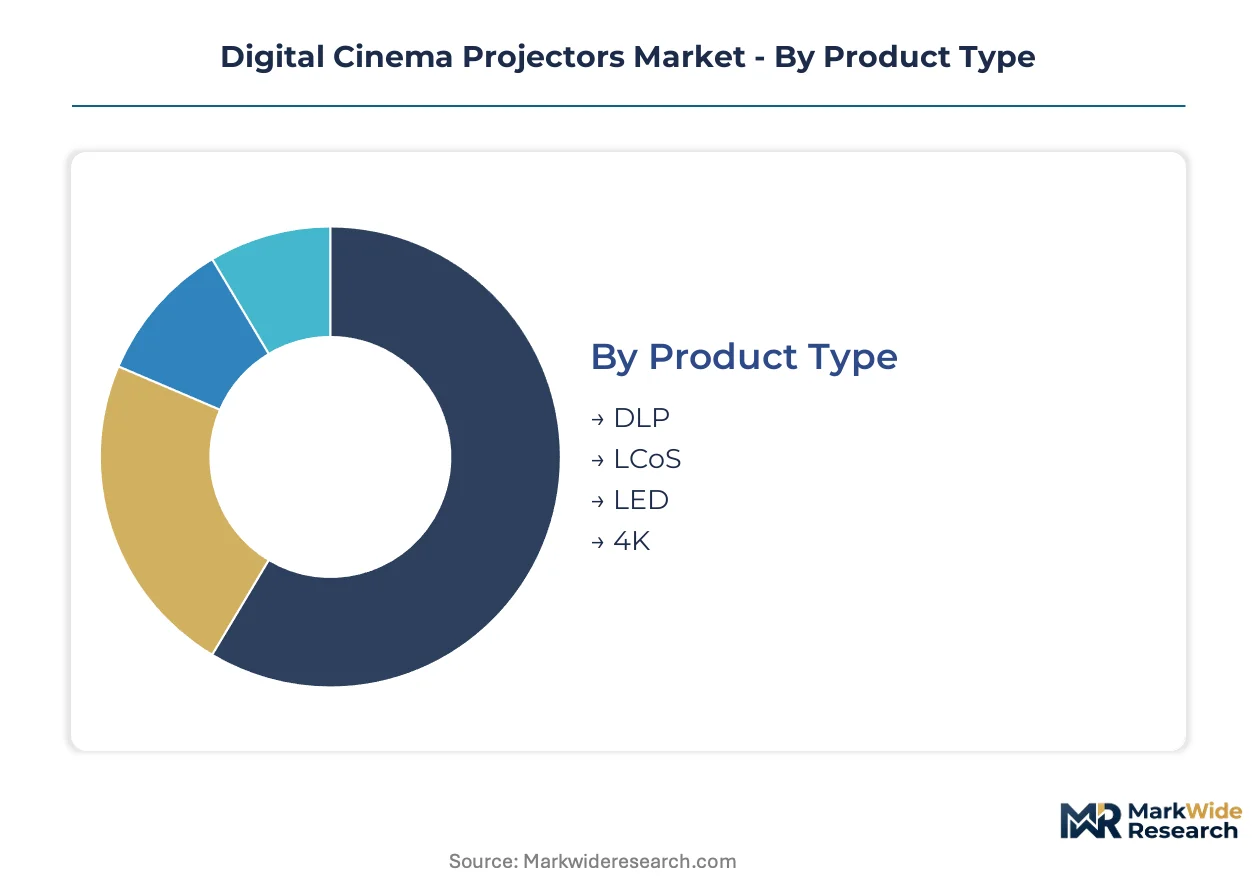
Digital cinema projector procurement splits sharply between standardized multiplex deployments and specialized configurations for premium venues. Understanding these fault lines illuminates where hardware margins concentrate and which technology transitions reshape replacement cycles.
Product Type:
Resolution and light-engine architecture create a customization spectrum from commodity DLP chassis to precision-engineered 4K panels requiring optical bench calibration.
- DLP:Texas Instruments micromirror chipsets dominate multiplex volume through proven reliability and streamlined supply chains. Cinema chains across India and China specify DLP for tier-two city rollouts where unit cost sensitivity overrides premium specifications.
- 4K:Native 4096×2160 resolution panels command flagship auditorium retrofits in Japan and Western Europe where DCI specification compliance and color gamut precision justify hardware premiums. Sony SXRD and LCoS architectures anchor this tier.
- LCoS:Liquid crystal on silicon technology delivers high-fill-factor imagery for mid-tier premium screens.
- LED:Direct-emission diode arrays serve specialized micro-cinema and screening room applications.
Leading the category by volume: DLP. Expanding most quickly: 4K.
Technology:
Illumination source selection determines operating economics, with laser systems compressing total cost of ownership despite substantial upfront differentials.
- Laser Projection:Solid-state phosphor and RGB pure laser architectures eliminate lamp replacement cycles and reduce cooling loads. German and French exhibitors accelerate compliance-driven adoption under EU F-Gas refrigerant restrictions.
- Digital Projection:Broad category encompassing DLP and LCoS engines with xenon or laser illumination, representing transitional installed base.
- Hybrid:Dual-source systems blending laser and conventional illumination for specialized large-format applications.
- Cathode Ray:Legacy technology confined to archival preservation and specialty restoration screening facilities.
Dominant installed base: Digital Projection. Steepest expansion trajectory: Laser Projection.
End User:
Venue type dictates specification rigor, with commercial cinemas enforcing DCI compliance while non-theatrical applications tolerate broader performance variance.
- Cinemas:Multiplex operators and independent exhibitors drive standardized procurement through studio-mandated DCI specification adherence. PVR-Inox in India and major chains across China concentrate new screen hardware demand.
- Film Festivals:Temporary and semi-permanent installations require rapid deployment calibration and transportable chassis configurations.
- Home Theaters:Ultra-high-net-worth residential specifications approach commercial-grade luminance and resolution.
- Event Venues:Convention centers and performing arts spaces deploy convertible projection for cinema-format programming.
Concentrating procurement volume: Cinemas. Fastest-growing specification tier: Film Festivals.
Installation:
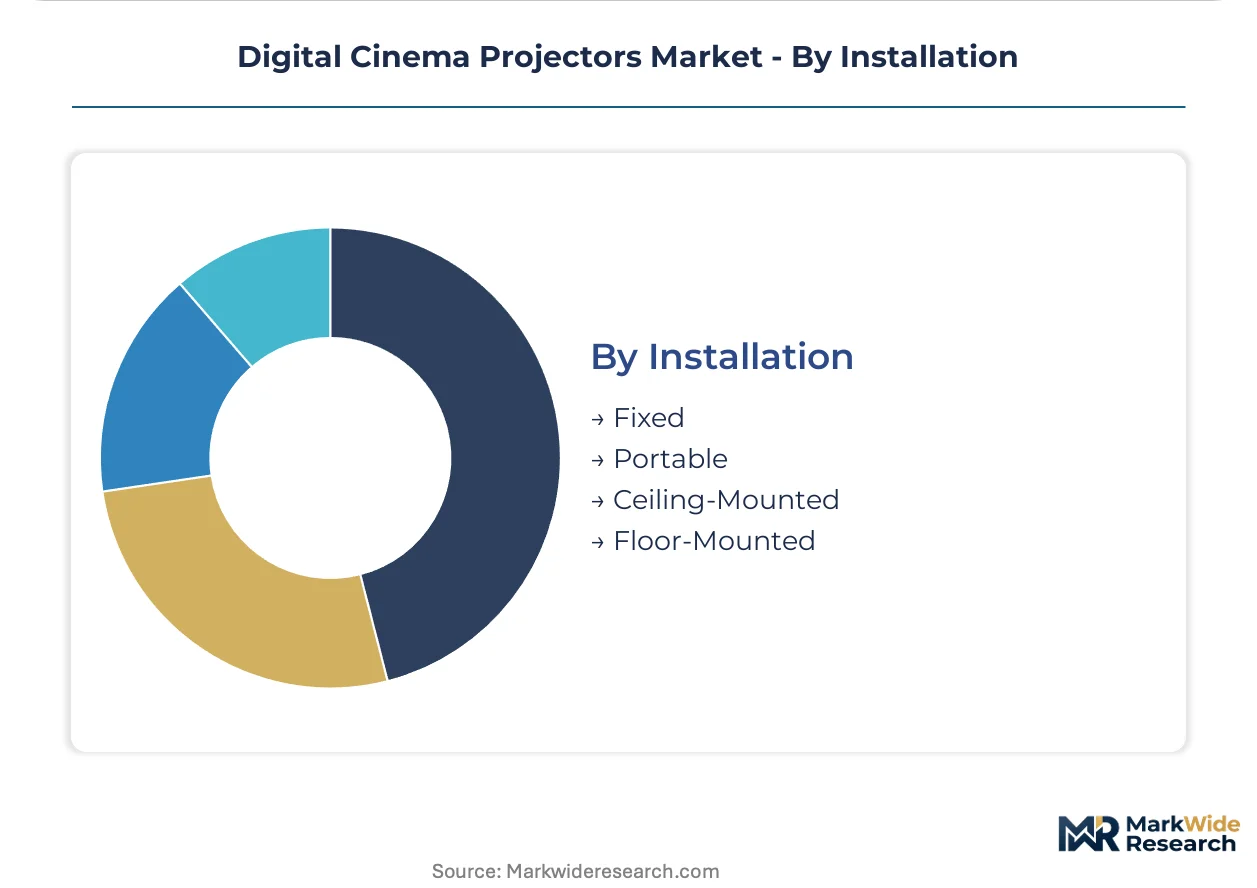
Mounting configuration reflects venue permanence and acoustic design constraints, with fixed ceiling systems dominating purpose-built auditorium construction.
- Fixed:Permanent ceiling-mounted configurations standardize multiplex construction and minimize per-screen calibration variance. Southeast Asian chains prioritize fixed installations for new-build premium large-format auditoriums.
- Ceiling-Mounted:Suspended chassis with integrated ventilation and cable management dominate retrofit scenarios.
- Portable:Mobile chassis serve pop-up cinemas, outdoor screenings, and festival circuits requiring rapid relocation.
- Floor-Mounted:Elevated booth and rear-projection configurations address architectural constraints in heritage venue conversions.
Commanding revenue share: Fixed. Gaining share fastest: Ceiling-Mounted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian electronics clusters while consumption tilts toward multiplex construction in emerging markets. China and India drive screen installation volumes. European retrofit cycles accelerate under environmental compliance mandates.
China
Tier-two and tier-three cities sustain premium large-format screen construction as Wanda Cinema and CGV expand footprints. The Ministry of Ecology and Environment enforces dual carbon goals that pressure exhibitors toward laser cooling systems. Shenzhen and Guangzhou manufacturing hubs supply DLP chassis and laser phosphor engines to domestic chains.
United States
Texas and California exhibition clusters drive service contract unbundling as operators separate hardware procurement from maintenance agreements. The FAA maintains cargo transport certification requirements affecting international projector logistics. Dallas-Fort Worth and Los Angeles metro areas concentrate third-party field service network density for laser calibration.
India
PVR-Inox and Cinepolis expand large-format footprints in underpenetrated metro markets. The Bureau of Indian Standards mandates electrical safety certifications for imported projection equipment. Mumbai and Delhi-NCR concentrate multiplex modernization spending toward DCI-compliant retrofits.
Germany
Flagship auditorium renovations prioritize RGB pure laser systems for screens exceeding 25 meters. The EU F-Gas Regulation accelerates refrigerant-phaseout timelines for xenon cooling systems. Berlin and Munich exhibition clusters face the fastest compliance-driven upgrade cycles as environmental agencies tighten enforcement protocols.
Japan
Native 4K SXRD panels dominate flagship retrofits where color gamut precision justifies hardware premiums. METI standards govern optoelectronic equipment efficiency benchmarks. Tokyo and Osaka anchor demand concentration for precision-engineered projection systems in premium cinema deployments.
Digital Cinema Projectors Market Vendor Landscape
The competitive structure tilts toward integrated optoelectronic conglomerates with captive display technology. Three tiers separate laser phosphor specialists, DLP chipset licensors, and precision LCoS fabricators. Market concentration reflects long-standing supply relationships between Texas Instruments and tier-one OEMs. Dominant competitive moves include backward integration into laser diode supply and geographic expansion through field service network density.
Among Japanese precision electronics groups, Sony Corporation and Panasonic Corporation exemplify the premium-tier vector through native 4K panel architectures. Barco NV occupies a position within the laser phosphor specialist archetype, leveraging European manufacturing proximity for EU F-Gas compliance-driven demand. These three anchors represent distinct competitive postures: semiconductor-backed resolution leadership, diversified electronics scale, and illumination-engine specialization.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Canon Inc. |
| Sony Corporation |
| NEC Display Solutions |
| Delta Electronics |
| Barco NV |
| Seiko Epson Corporation |
| JVCKenwood Corporation |
| Christie Digital Systems |
| Others |
Supply Flow & Price Mechanics
Laser diode arrays and phosphor wheel assemblies flow from Japanese and Taiwanese component foundries through tier-one OEM assembly in Belgium and China, with DCI certification tiers stratifying final pricing across premium RGB, standard laser phosphor, and legacy xenon replacement brackets.
Pricing Analysis
Margin tightening in mid-tier laser phosphor brackets reflects Texas Instruments DLP chipset allocation constraints and captive laser engine supply from Barco's European manufacturing. Three-tier pricing structure across premium RGB, standard laser phosphor, and economy xenon-replacement tiers separates exhibitors by screen width and DCI compliance stringency. Cost-down pressure on standard-tier bundles accelerates because Chinese multiplex chains negotiate volume procurement through Shenzhen manufacturing proximity. Independent exhibitors in India exhibit highest price sensitivity, while Japanese flagship retrofits show lowest elasticity for native 4K SXRD premiums.
Supply Chain Analysis
Single-source vulnerability sits with Texas Instruments for DLP cinema chipsets and Japanese laser diode manufacturers for RGB pure laser engines. Manufacturing concentrates in China for DLP chassis assembly, Belgium for laser phosphor integration, and Japan for LCoS panel fabrication. Raw material dependencies include rare-earth phosphors, precision optical glass, and aluminum heat-dissipation substrates. Tariff exposure on Chinese-assembled chassis threatens North American exhibitor procurement economics. Distribution runs through direct OEM sales teams for multiplex chains and regional AV integrators for independent venues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a compliance moat that rewards laser-ready OEMs while stranding xenon-dependent service networks, elevating certified-field-engineering density as a sustainable competitive advantage.
For Market Incumbents: Deploy backward integration into laser diode supply to secure phosphor engine margin control against emerging Chinese LED array competitors. Consolidate field engineering talent pools in Germany and California where compliance-driven retrofit cycles concentrate service demand. Deepen DCI certification investment to accelerate forced-upgrade capture from non-compliant legacy installations. For New Entrants and Emerging Players: Third-party service networks in Texas and California offer partnership pathways for laser calibration capabilities without captive manufacturing. White-space opportunity concentrates in Indian tier-two city multiplex modernization where PVR-Inox expansion outpaces OEM direct coverage. Target film festival temporary-installation segments with portable RGB chassis and rapid-deployment calibration protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor European laser phosphor specialists with EU F-Gas compliance-ready product lines and stranded xenon service assets trading below replacement cost. Long-term viability hinges on laser illumination share sustaining past xenon lamp inventory depletion. Monitor China screen installation permit approvals as inflection signal for hardware procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Engine Backward Integration | Captive phosphor supply secures margin control against Texas Instruments chipset concentration. |
| Field Service Network Expansion | Density in Germany and California captures EU F-Gas compliance-driven retrofit cycles. |
| DCI Certification Fast-Track | Accelerated compliance timelines force-upgrade non-compliant legacy auditorium installations. |
| India Distribution Partnership | PVR-Inox and Cinepolis volume procurement in tier-two cities outpaces direct OEM reach. |
| Festival Circuit Portable Systems | RGB chassis with rapid calibration protocols address film festival temporary-installation demand. |
Methodological Framework
SEC 10-K filings, EU F-Gas regulatory submissions, and China Ministry of Ecology permitting records formed the secondary backbone, cross-referenced against primary interviews with multiplex procurement directors, laser calibration field engineers, and DCI compliance auditors. Bottom-up screen installation counts from China Film Administration and India CBFC data were triangulated against top-down OEM revenue disclosures.
Historical trendline analysis across installed base transitions from xenon to laser illumination informed projection modeling throughout the forecast period. Segmentation dimensions included resolution tier, light-engine architecture, illumination source, venue type, and mounting configuration. CAGRs were derived from replacement cycle compression rates and new screen construction permits. Industry-specific inputs incorporated Texas Instruments DLP chipset allocation schedules and EU refrigerant phaseout enforcement timelines.
Caveats apply where theatrical release window compression or streaming platform subscriber growth could materially shift screen utilization assumptions and replacement timing. Forecasts reflect documented assumptions about laser diode cost curves and DCI specification enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Cinema Camera Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Film Dubbing Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
Drive-In Movie Theater Market
Film and Cinema
Movie Tickets Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Camera Jib Market
Film and Cinema
Global Advanced Cinema Projector Market