
 Cinema Lenses Market | 2026-2036
Cinema Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Cinema Lenses Market Intelligence
Full-frame T1.5 specification tiers are redrawing competitive boundaries in premium cinema optics. ARRI AG leverages its Munich engineering base to sustain dominance in large-format rental channels. Canon Inc anchors volume through EF and RF mount ecosystems that span prosumer and professional tiers. ZEISS Group differentiates via Supreme Prime radiance and controlled global distribution.
Cinema lenses are precision-engineered optical assemblies with fixed or variable focal lengths, calibrated T-stops, and matched color science for sequential imaging on digital cinema cameras. Manufacturers grind aspherical and low-dispersion elements to sub-micron tolerances, then house them in all-metal barrels with unified gear positions for follow-focus and matte-box compatibility. Prime lenses occupy the margin-rich tier for feature films, while zoom configurations gain share in documentary and commercial workflows where schedule pressure favors flexibility. Anamorphic formats lead prestige productions, though spherical designs dominate unit economics across rental houses serving episodic television.
FCC equipment authorization shapes wireless lens control integration in the United States, while CE marking and EU RoHS compliance govern European import eligibility for electronics-embedded cine optics. ISO 517 and SMPTE standards define flange depth and metadata protocols that manufacturers must satisfy for interoperability. Stakeholders should monitor sensor format fragmentation and mount standard consolidation as the decisive variables for R&D allocation and inventory risk.
Market Dynamics
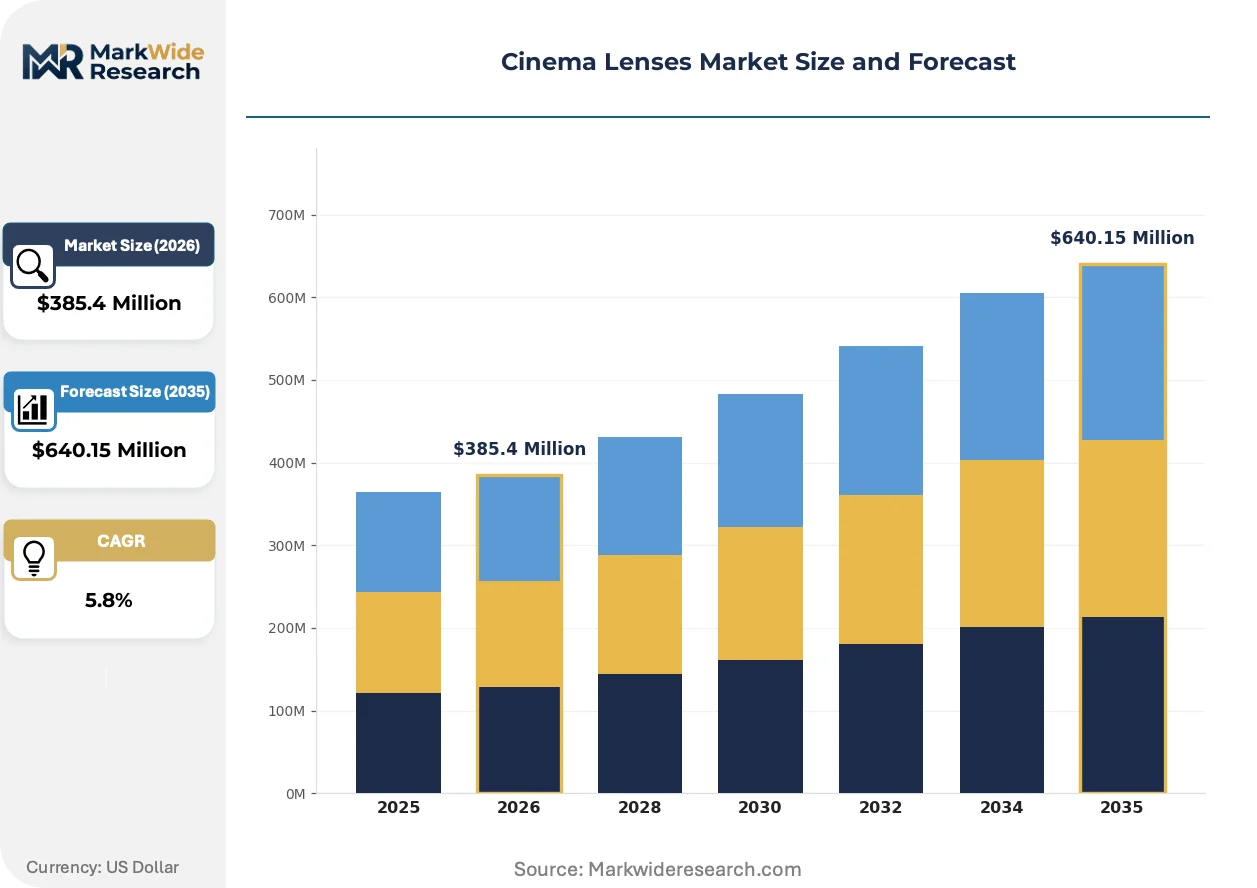
Full-frame sensor proliferation is compressing the addressable market for legacy Super 35 optics while simultaneously expanding rental house inventory requirements for large-format coverage. This format migration forces manufacturers to retool coating chambers and recalibrate flange depth specifications across entire product families.
Growth Catalysts
- Streaming Originals Pipeline:Netflix, Amazon Prime Video, and Disney+ commission feature-length productions requiring cinema-grade glass, expanding addressable demand beyond traditional theatrical distributors.
- CE Marking Harmonization:EU RoHS and electromagnetic compatibility standards now cover wireless lens control modules, enabling cross-border equipment circulation across German, French, and Italian rental markets.
- Large-Format Acquisition:ARRI Alexa 35 and RED V-Raptor cameras with full-frame sensors are supplanting Super 35 bodies on prestige productions, forcing lens refresh cycles.
Market Restraints
- Optical Glass Concentration:Schott AG and Ohara Corporation control specialized low-dispersion substrate supply, exposing manufacturers to germanium and lanthanum price volatility.
- Mount Fragmentation:Sony E-mount, Canon RF-mount, and LPL mount incompatibility forces rental houses to triple inventory carrying costs for multi-camera productions.
- FCC Equipment Authorization:Wireless follow-focus and iris control modules embedded in cinema lenses face 6-12 month certification timelines, delaying product launches in the United States.
Strategic Opportunities
- India Production Expansion:Mumbai and Hyderabad studio complexes are commissioning international co-productions requiring PL-mount cinema glass, opening new rental demand outside traditional Western markets.
- Virtual Production Volumes:LED wall stages in London, Atlanta, and Sydney require lenses optimized for moiré suppression and chromatic consistency under sustained illumination.
- PLI Scheme Incentives:India's Production Linked Incentive scheme for electronics manufacturing could localize lens assembly and reduce import duties on precision-machined barrels.
Industry Challenges
- Coating Technician Scarcity:Multi-layer nano-coating deposition requires operators trained on ion-beam sputtering equipment, with fewer than 200 qualified specialists globally.
- ISO 517 Calibration Backlogs:Flange depth verification and T-stop certification at accredited laboratories extend lead times by 8-14 weeks for new lens introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cinema Lenses Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lens Type: Prime, Zoom, Anamorphic, Wide-Angle Mount Type: PL, EF, E-Mount, MFT Application: Feature Films, Documentaries, Commercials, Music Videos Target Market: Independent Filmmakers, Production Companies, Rental Houses, Educational Institutions |
| Companies Covered | ARRI AG, FUJIFILM Corporation, Canon Inc, Angénieux, Sigma Corporation, ZEISS Group, Sony Corporation, Leica Camera AG, Cooke Optics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cinema Lenses Market Strategic Shifts & Innovations
Computational optics and real-time aberration correction are merging with traditional mechanical designs, compressing the performance gap between mid-tier and premium glass. This convergence is reshaping R&D allocation across Munich, Tokyo, and Rochester engineering centers.
Electromechanical iris units with stepless T-stop control are supplanting traditional mechanical aperture rings in documentary and commercial workflows. Owner-operators shooting run-and-gun content favor this technology for exposure automation during unscripted sequences. The shift compresses demand for purely mechanical cinema primes while expanding the addressable market for hybrid stills-cinema crossover lenses.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing manufacturers to reformulate anti-reflective coating chemistries and cleaning solvents. German and Italian optical houses now face compliance costs for legacy deposition processes. The regulation most affects anamorphic lens production, where fluoropolymer surface treatments traditionally ensured flare control.
Rental houses are consolidating procurement through direct manufacturer partnerships, bypassing traditional distributor markups on high-volume zoom lens purchases. This channel compression concentrates purchasing power with Panavision, ARRI Rental, and Keslow Camera in Los Angeles, London, and Sydney. The pattern is most visible in episodic television, where production volume justifies captive inventory over spot rental arrangements.
Cinema Lenses Market Segmentation
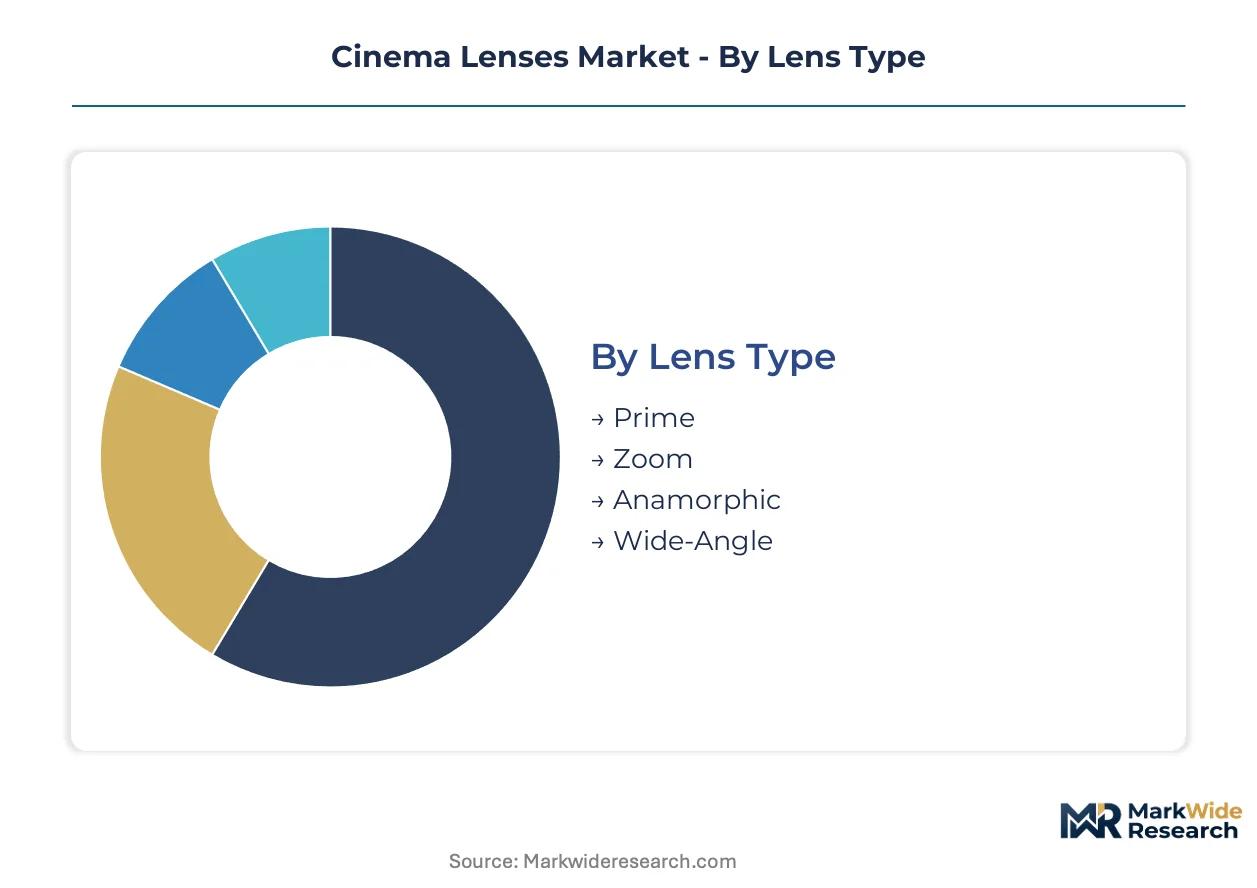
Format migration and mount fragmentation force distinct inventory strategies across each segmentation dimension. Rental houses, manufacturers, and owner-operators face divergent cost structures depending on which lens category, mount standard, and application tier they target.
Lens Type:
Regulatory differentiation centers on CE marking and EU F-Gas Regulation compliance for coating chemistries, with anamorphic production facing the strictest reformulation requirements.
- Prime:Fixed focal length optical assemblies with calibrated T-stops and matched color science dominate prestige feature production. Los Angeles and Atlanta rental houses concentrate inventory here for episodic television and theatrical releases.
- Zoom:Variable focal length configurations with parfocal design enable rapid reframing during documentary and commercial shoots. Demand concentrates in owner-operator segments where schedule pressure and crew minimization override absolute optical performance.
- Anamorphic:Squeeze-factor optics requiring specialized flare control and oval bokeh rendering face EU F-Gas Regulation coating reformulation costs.
- Wide-Angle:Sub-24mm focal lengths with rectilinear correction serve LED volume virtual production stages in London and Atlanta.
Prime lenses handle the majority of rental throughput; wide-angle configurations are expanding most quickly on share as virtual production volumes proliferate.
Mount Type:
Cost tier stratification separates professional PL-mount ecosystems from prosumer EF and E-mount alternatives, with inventory carrying costs tripling for multi-camera productions.
- PL:Positive lock mount with standardized flange depth per ISO 517 dominates rental house inventory and ARRI Alexa 35 deployments. Mumbai and Hyderabad studio complexes are expanding PL-mount procurement for international co-productions.
- EF:Canon's legacy bayonet mount spans prosumer DSLRs and professional cinema cameras, anchoring volume through backward compatibility.
- E-Mount:Sony's short flange distance enables compact full-frame designs but fragments inventory against PL and LPL standards.
- MFT:Micro Four Thirds mount serves documentary and educational workflows where sensor size and weight reduction override full-frame coverage requirements.
PL mount handles the majority of professional throughput; E-mount is gaining share fastest as Sony Venice and FX series cameras displace legacy Super 35 bodies.
Application:
Volume concentration in streaming originals versus theatrical distribution creates divergent durability and specification requirements across production tiers.
- Feature Films:Theatrical and streaming original productions requiring matched lens sets for consistent intercutting. Netflix, Amazon Prime Video, and Disney+ commissioning patterns now exceed traditional studio volume.
- Documentaries:Run-and-gun workflows favoring zoom configurations and electromechanical iris control for unscripted exposure management.
- Commercials:High-day-rate productions with compressed schedules where rental flexibility outweighs long-term ownership economics.
- Music Videos:Visual-effects-heavy content with anamorphic preference for stylized flare and aspect ratio differentiation.
Feature films handle the majority of rental revenue; documentaries are climbing the fastest as streaming platforms expand non-fiction slates.
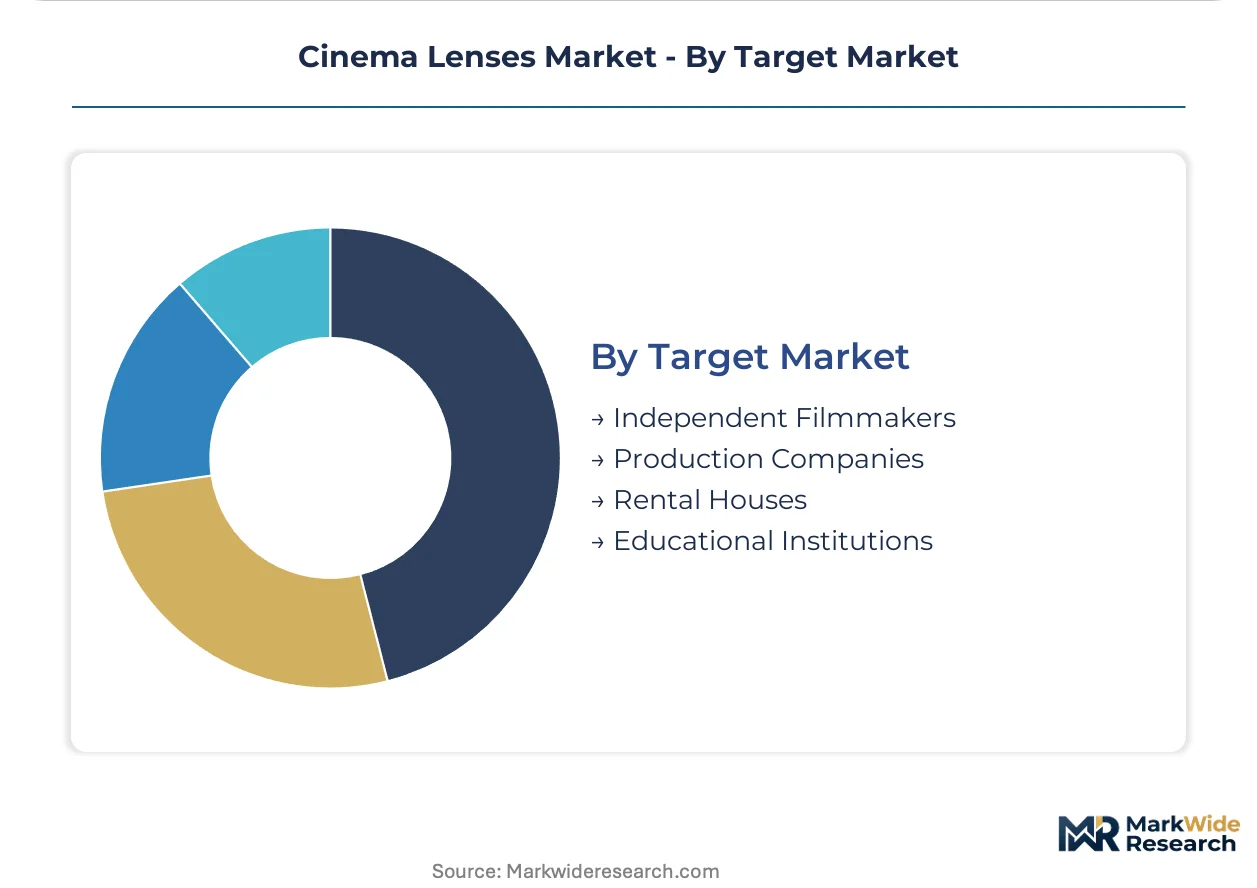
Target Market:
Customer type determines procurement channel—direct manufacturer partnerships versus distributor networks—and influences warranty, service, and upgrade terms.
- Independent Filmmakers:Owner-operators purchasing hybrid stills-cinema crossover glass with autofocus compatibility for commercial and documentary work.
- Production Companies:Studio and streaming-funded entities with captive lens inventories or long-term rental arrangements.
- Rental Houses:Panavision, ARRI Rental, and Keslow Camera in Los Angeles, London, and Sydney consolidating procurement through direct manufacturer partnerships.
- Educational Institutions:Film schools and university programs with MFT-mount preference for curriculum standardization and student equipment access.
Rental houses handle the majority of professional throughput; independent filmmakers are expanding most quickly on share as owner-operator economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in precision cinema optics favor German and Japanese manufacturers supplying rental houses in the United States and United Kingdom. Trade flows concentrate on PL-mount and LPL-mount glass where ISO 517 flange depth compliance enables cross-border equipment circulation. Currency volatility and specialized optical substrate sourcing expose margins on transatlantic shipments.
United States
Los Angeles and Atlanta anchor production volume for streaming originals and theatrical releases. FCC equipment authorization governs wireless lens control modules, creating six-to-twelve month certification delays for new product introductions. Panavision and Keslow Camera consolidate procurement through direct manufacturer partnerships, bypassing traditional distributor networks.
Germany
Munich engineering centers sustain dominance in large-format rental channels through precision grinding capabilities. EU F-Gas Regulation restricts fluorinated greenhouse gases in anti-reflective coating chemistries, forcing reformulation of legacy deposition processes. ARRI AG leverages its Bavaria base to supply PL-mount glass across European rental markets.
United Kingdom
London LED volume stages drive demand for wide-angle lenses optimized for moiré suppression under sustained illumination. CE marking and RoHS compliance enable cross-border equipment circulation with German and Italian rental markets. Soho post-production facilities require matched lens sets for consistent intercutting on prestige productions.
India
Mumbai and Hyderabad studio complexes commission international co-productions requiring PL-mount cinema glass. The Production Linked Incentive scheme for electronics manufacturing could localize lens assembly and reduce import duties on precision-machined barrels. BIS standards govern equipment eligibility for government-funded productions.
Japan
Tokyo and Osaka optical houses control specialized low-dispersion substrate supply through relationships with Ohara Corporation. JIS standards and METI industrial policy support domestic coating chamber infrastructure. Sigma Corporation and FUJIFILM Corporation anchor volume through mount ecosystems spanning prosumer and professional tiers.
Cinema Lenses Market Key Industry Players
Concentration sits with German precision-engineering specialists and Japanese volume-scale manufacturers. The vendor base stratifies across three tiers: Munich-based large-format specialists, Tokyo-Osaka mount-ecosystem anchors, and French-British optical heritage houses. Competitive moves center on direct rental house partnerships eliminating distributor markups, and coating chemistry reformulation responding to EU F-Gas Regulation compliance costs.
Within the precision-engineering tier, ARRI AG exemplifies large-format rental channel dominance through its Munich engineering base. ZEISS Group occupies a position in controlled global distribution of Supreme Prime radiance tiers. Canon Inc anchors volume-scale positioning through EF and RF mount ecosystems that span prosumer and professional segments. These three represent distinct competitive archetypes: engineering-led rental specialization, premium distribution control, and mount-ecosystem scale.
| Leading Market Players |
|---|
| ARRI AG |
| FUJIFILM Corporation |
| Canon Inc |
| Angénieux |
| Sigma Corporation |
| ZEISS Group |
| Sony Corporation |
| Leica Camera AG |
| Cooke Optics Ltd |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Munich engineering houses and Los Angeles rental chains lock in multi-year supply access for PL-mount prime sets while fixing price visibility against optical glass volatility. This contract structure insulates ARRI Rental and Keslow Camera from germanium and lanthanum price swings that otherwise compress margins on spot-procured anamorphic glass.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in cinema lens procurement. Premium tiers command substantial markups for T1.5 full-frame primes with matched color science, while economy tiers serve educational institutions and documentary owner-operators through MFT-mount configurations. Pricing pressure stems from rental house consolidation bypassing distributor markups on high-volume zoom purchases. Owner-operators exhibit highest price sensitivity due to hybrid stills-cinema crossover alternatives, whereas prestige feature productions demonstrate lowest sensitivity given schedule-driven rental economics.
Supply Chain Analysis
Inventory lead times for ISO 517 flange depth certification extend procurement cycles by 8-14 weeks, forcing rental houses to pre-position glass ahead of production greenlights. Geographic supply concentrates in Germany, Japan, and the United States, with Munich grinding centers and Tokyo coating chambers feeding global distribution. Raw material dependencies rest on Schott AG and Ohara Corporation for low-dispersion optical substrates, plus precision-machined aluminum barrels from Bavarian metalworking suppliers. Single-source vulnerability in ion-beam sputtering equipment exposes coating capacity constraints. Distribution runs through direct manufacturer partnerships with Panavision, ARRI Rental, and Keslow Camera consolidating procurement power in Los Angeles, London, and Sydney.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of qualified ion-beam sputtering technicians—fewer than 200 globally—constrains coating capacity expansion and concentrates margin capture with incumbent precision-engineering houses. This capability gap limits new entrant scale-up and reinforces incumbent pricing power in premium tiers.
For Market Incumbents: Consolidate coating technician training pipelines through partnerships with Munich and Tokyo technical institutes to secure deposition capacity against competitor hiring. Deepen backward integration into low-dispersion optical substrate supply through long-term offtake with Schott AG and Ohara Corporation, reducing exposure to germanium price volatility that threatens margin compression in anamorphic production. For New Entrants and Emerging Players: Anchor in Hyderabad and Mumbai studio complexes where PL-mount demand from international co-productions outpaces established rental house inventory depth. Target documentary and commercial workflows with electromechanical iris zoom configurations, a segment where schedule pressure overrides absolute optical performance and incumbent prime lens dominance weakens. Pursue direct procurement partnerships with LED volume stage operators in Atlanta and London requiring moiré-suppressed wide-angle glass. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale optical houses with captive coating chambers and established CE marking pathways, positioned for acquisition by mount-ecosystem anchors seeking vertical integration. Long-term viability hinges on full-frame sensor compatibility and wireless lens control module certification. Monitor FCC equipment authorization timelines as the decisive signal—compression from 12-month to 6-month cycles would indicate regulatory streamlining enabling faster product refresh and inventory turnover.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation | EU F-Gas Regulation compliance enables continued anamorphic lens production for German and Italian optical houses. |
| Direct Rental House Partnership | Panavision and Keslow Camera consolidation bypasses distributor markups on high-volume zoom lens procurement. |
| Wireless Lens Control Certification | FCC equipment authorization unlocks US market entry for electromechanical iris modules with stepless T-stop control. |
| Virtual Production Optimization | LED volume stages in London and Atlanta demand lenses calibrated for moiré suppression under sustained illumination. |
| Production Linked Incentive Localization | India's PLI scheme for electronics manufacturing could reduce import duties on precision-machined lens barrels. |
Research Approach
Initial hypotheses were tested against primary input from rental house procurement directors, optical engineering leads at Munich and Tokyo manufacturers, streaming platform production executives, and LED volume stage technical supervisors, then refined through secondary validation. Primary fieldwork encompassed structured interviews across Los Angeles, London, Munich, and Mumbai production clusters. Secondary sources included SEC filings from publicly traded camera manufacturers, SMPTE standards documentation, EU F-Gas Regulation compliance filings, and Indian BIS equipment eligibility records. Bottom-up lens shipment estimates triangulated against top-down streaming production spend allocations.
Variance decomposition across the projection horizon isolates format migration, mount standard consolidation, and coating capacity constraints as the three primary drivers of forecast uncertainty. Segmentation modeling spans lens type, mount standard, application tier, and target customer archetype, with cross-elasticities estimated between prime and zoom configurations. CAGRs derive from production volume trends in streaming originals, theatrical releases, and virtual production stages, calibrated against sensor format adoption curves from Sony, Canon, and ARRI camera release schedules.
Decision-makers should treat outputs as directional under assumptions of sustained streaming platform commissioning, stable optical glass supply from Schott AG and Ohara Corporation, and no disruptive consolidation in PL-mount standards; material deviation in any would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
Camera Jib Market
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
Cinema Camera Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Movie Tickets Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
North America 3D Cinema Screen Market