
 Japan Animation, VFX and Post Production Market | 2026-2036
Japan Animation, VFX and Post Production Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Animation, VFX and Post Production Market Insights
Modular service packaging is decoupling animation production from traditional studio-bound workflows, enabling buyers to license specific pipeline stages rather than full-project contracts. Toei Animation Co. leverages its in-house production capacity to sustain vertical control over long-running franchises. Production I.G differentiates through technology leadership in digital compositing and virtual production workflows. Graphinica anchors specialized VFX subcontracting for both domestic theatrical releases and international streaming co-productions.
Japan Animation, VFX and Post Production encompasses the creation, manipulation, and finishing of moving-image content through frame-by-frame animation techniques, computer-generated imagery, and digital intermediate processing at resolutions up to 4K HDR with Rec. 2020 color space mastering. Its primary commercial purpose is to supply finished entertainment assets to theatrical exhibitors, streaming platforms, and broadcasters. Service type segmentation shows animation and VFX commanding the largest revenue pools due to labor-intensive keyframe work and simulation complexity. Distribution channel segmentation reveals streaming services as the fastest-expanding outlet, while theatrical release retains premium pricing power for franchise properties. Production stage segmentation indicates post-production and color grading concentrate margin capture through specialized technical talent scarcity.
METI's Cool Japan policy framework and the Agency for Cultural Affairs' content export subsidies shape production incentives toward internationally distributable formats. JIS standards for digital cinema packaging and PMDA-adjacent content classification protocols influence market access thresholds for age-targeted segments. Stakeholders must monitor how generative AI tools alter labor allocation across in-between animation and background art roles without eroding the handcrafted aesthetic that defines Japanese output.
Market Dynamics
Generative AI tools are redistributing labor across Japan's animation pipeline, compressing in-betweening and background art roles while preserving the handcrafted keyframe aesthetic that defines domestic output. This force is reshaping cost structures and talent deployment across the Tokyo-Osaka production corridor.
Growth Catalysts
- Cool Japan export subsidies:The Agency for Cultural Affairs' content export incentives direct production investment toward internationally distributable formats with multi-language packaging requirements.
- Streaming platform content budgets:Global streaming services are expanding dedicated anime commissioning teams and minimum-guarantee licensing structures for original series production.
- Virtual production workflows:Real-time rendering engines and LED volume stages are compressing post-production timelines for hybrid animation-live action projects.
Market Restraints
- Key animator labor scarcity:The pool of experienced keyframe artists capable of sustaining franchise-grade quality is concentrated among aging practitioners with limited succession pipelines.
- Subcontractor network fragility:Production reliance on dispersed in-betweening studios across East and Southeast Asia creates coordination overhead and quality variance risks.
- JIS digital cinema compliance costs:Packaging standards for theatrical distribution impose certification and technical validation expenses that burden mid-tier productions.
Strategic Opportunities
- Osaka-Kyoto production cluster expansion:Lower operational costs and emerging technical institutes are attracting secondary studio facilities outside saturated Tokyo precincts.
- Immersive format adaptation:Volumetric capture and spatial audio pipelines enable anime IP extension into location-based entertainment and metaverse environments.
- METI SME digitalization grants:Small and mid-size animation houses can access subsidized cloud rendering infrastructure and asset management system upgrades.
Industry Challenges
- Digital compositing talent pipeline gaps:Training programs for HDR color grading and ACES workflow management are not scaling with production volume demands.
- Generative AI copyright ambiguity:Unclear training data licensing frameworks create legal exposure for studios deploying machine learning tools in commercial pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Animation, VFX and Post Production Market |
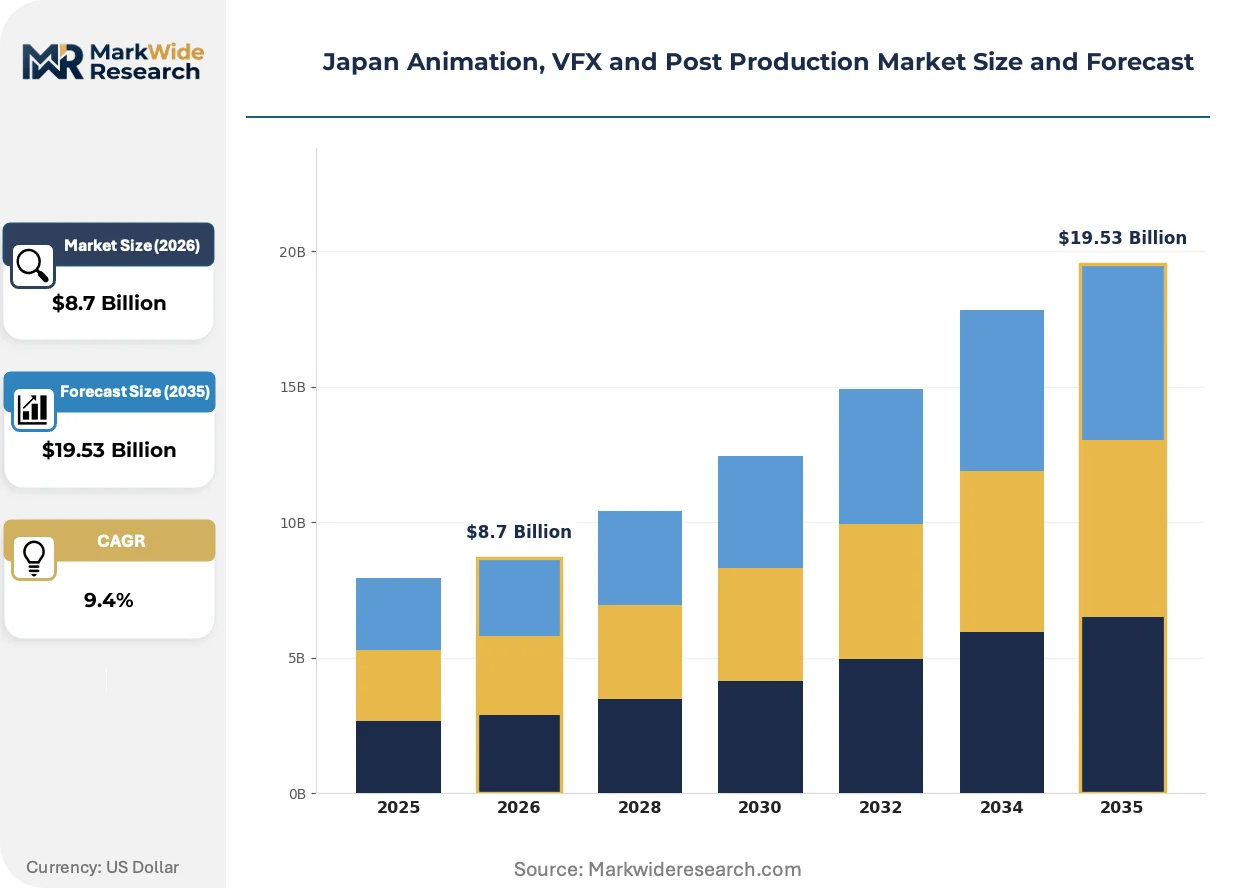
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Animation, Visual Effects, Editing, Color Grading Production Stage: Pre-Production, Production, Post-Production, Distribution Distribution Channel: Theatrical Release, Streaming Services, Television Broadcast, DVD/Blu-ray Target Audience: Children, Teens, Adults, Families |
| Companies Covered | Toei Animation Co., BONUS.CO.JP, Sony Pictures Animation, DLE, Inc., Studio Ghibli, Production I.G, Imagica Lab, Graphinica, Tokyo Laboratory Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Animation, VFX and Post Production Market Trends and Innovations
Cloud-based rendering and modular service packaging are dissolving traditional studio boundaries, enabling buyers to license discrete pipeline stages rather than complete project contracts. This shift is reconfiguring competitive advantage toward specialized technical capabilities and scalable infrastructure access.
Real-time game engines are decentralizing previsualization and final-pixel rendering workflows across Japan's animation sector. Mid-size studios in Osaka and Fukuoka are adopting Unreal Engine and Unity pipelines for virtual cinematography at accelerating rates. This technology is decentralizing production authority away from centralized Tokyo facilities and enabling geographically distributed teams to collaborate on shared virtual stages with reduced physical asset requirements.
METI's revised Cool Japan funding criteria now mandate demonstrable export revenue targets and multi-platform distribution strategies for subsidy eligibility. Production committees must document international licensing commitments before accessing public co-financing. Feature film and premium series segments are responding by front-loading global streaming platform negotiations and embedding localization requirements into greenlight decisions.
Buyers are unbundling post-production services from traditional full-project contracts and sourcing color grading, compositing, and mastering from specialized subcontractors. Streaming platforms with dedicated anime divisions are driving this fragmentation through modular procurement templates that separate creative supervision from technical execution. This pattern is most visible in Tokyo's Suginami and Nerima wards, where boutique grading houses and VFX studios are capturing margin previously retained by integrated production committees.
Japan Animation, VFX and Post Production Market Segmentation
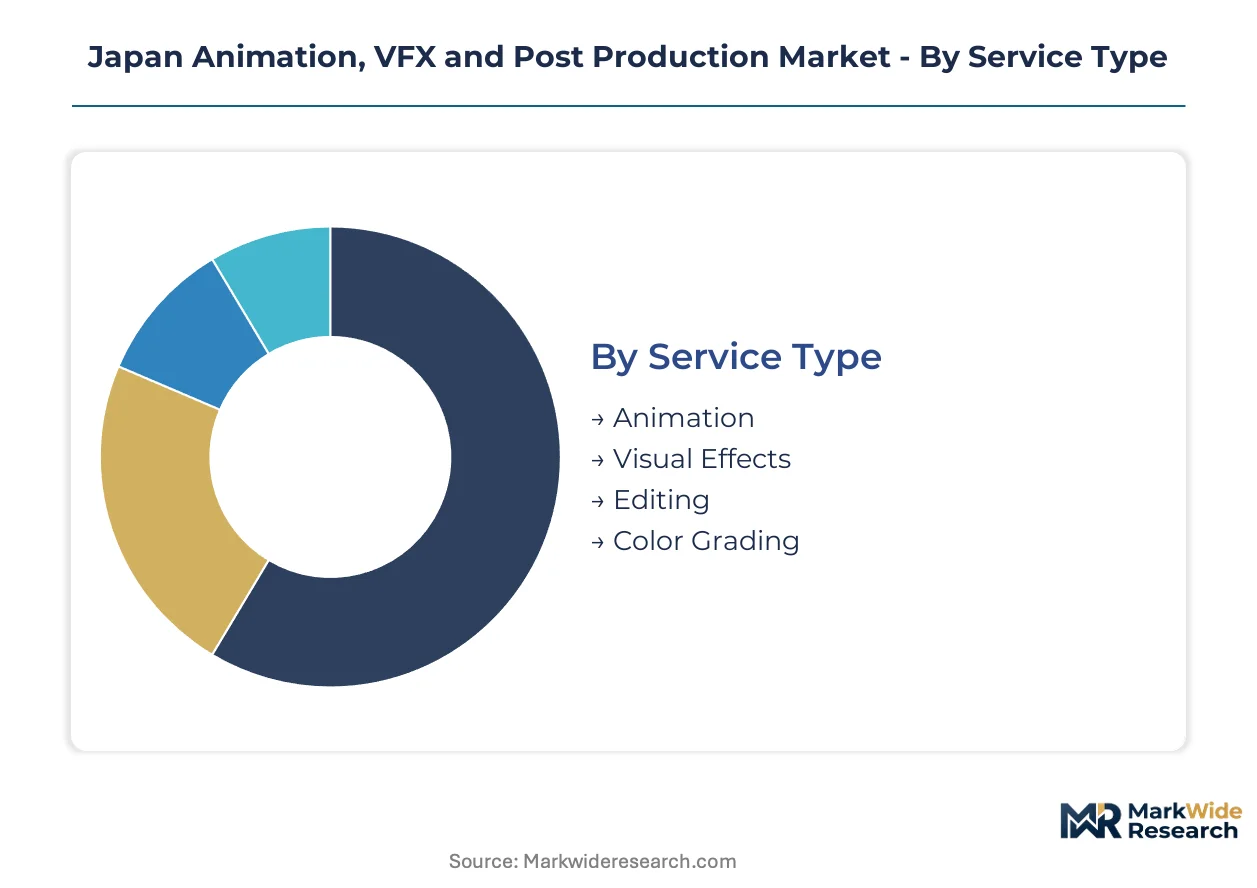
Segmentation in Japan's animation and post-production market reveals how capital allocation and technical specialization concentrate across distinct service layers. Production committees and streaming buyers use these boundaries to unbundle contracts and source modular capabilities.
Service Type:
Capital intensity varies sharply across this dimension, with infrastructure-heavy segments demanding specialized hardware and software licensing commitments.
- Animation:Frame-by-frame production encompasses keyframe artistry, in-betweening, and digital ink-and-paint processing. Labor concentration in Tokyo's Suginami and Nerima wards drives cost premiums, while generative AI tools compress background art timelines. METI SME digitalization grants subsidize cloud rendering infrastructure for mid-tier houses seeking capacity expansion.
- Visual Effects:CGI simulation, particle systems, and digital environment construction require HPC clusters and perpetual software licenses from Autodesk and Foundry. Osaka-based Graphinica anchors specialized subcontracting for theatrical releases and international streaming co-productions, capturing margin through technical scarcity.
- Editing:Non-linear assembly and narrative sequencing operate at lower capital thresholds with workstation-based Avid and Adobe pipelines.
- Color Grading:HDR mastering and Rec. 2020 color space finishing demand calibrated reference monitors and controlled environment suites.
Animation absorbs the bulk of installed capacity; Visual Effects is expanding most quickly.
Production Stage:
Margin capture concentrates at opposite ends of this spectrum, with concept development and final finishing commanding premium pricing over commoditized middle stages.
- Pre-Production:Script development, storyboarding, and character design establish creative direction and IP ownership terms. Production committees front-load international licensing negotiations here to satisfy METI's revised Cool Japan export revenue mandates.
- Production:Asset creation and shot execution span the labor-intensive core where key animator scarcity constrains output volume.
- Post-Production:Compositing, sound design, and digital intermediate processing concentrate technical talent scarcity. Boutique grading houses in Tokyo's western wards capture margin previously retained by integrated committees through modular procurement templates.
- Distribution:Mastering and platform packaging require JIS digital cinema compliance certification for theatrical release.
Post-Production commands the steepest margin expansion; Distribution is gaining share fastest as streaming platforms multiply output windows.
Distribution Channel:
Revenue stability diverges across channels, with long-term licensing structures displacing volatile theatrical performance for portfolio planning.
- Theatrical Release:Premium exhibition retains pricing power for franchise properties and event-scale premieres. JIS packaging standards impose certification costs that burden mid-tier productions seeking theatrical windows.
- Streaming Services:Global platforms expand dedicated anime commissioning teams with minimum-guarantee structures. This channel decentralizes production authority away from Tokyo facilities through distributed virtual production workflows.
- Television Broadcast:Traditional broadcaster slots sustain volume production for long-running series with established sponsorship models.
- DVD/Blu-ray:Physical media persists for collector editions and otaku demographic retention despite secular decline.
Streaming Services now absorb the majority of greenlight decisions; Theatrical Release maintains the highest per-unit revenue capture.
Target Audience:
Content investment intensity tracks age demographic sophistication, with adult-oriented production commanding higher per-minute budgets and complex narrative packaging.
- Adults:Mature-themed series and feature films drive international licensing premiums and festival circuit positioning. PMDA-adjacent content classification protocols shape market access thresholds for age-targeted distribution.
- Teens:Shonen and shojo franchise properties sustain multi-decade merchandising ecosystems and cross-media expansion.
- Children:Educational and entertainment programming maintains broadcaster commissioning volume with lower per-episode production values.
- Families:Cross-generational theatrical releases balance accessibility with franchise universe maintenance.
Adults-oriented content captures the highest international licensing multiples; Teens programming maintains the largest cumulative episode volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's animation output dominates global supply while domestic consumption absorbs only a fraction of finished inventory. This production-consumption asymmetry shapes regional strategy across the archipelago's studio clusters.
Kanto/Tokyo
Suginami and Nerima wards concentrate keyframe artistry and post-production grading houses. METI's Cool Japan export subsidies flow through production committees headquartered here. The Tokyo-Osaka production corridor anchors talent migration patterns and subcontractor coordination networks.
Kansai/Osaka
Lower operational costs and emerging technical institutes attract secondary studio facilities outside saturated Tokyo precincts. Graphinica anchors specialized VFX subcontracting for theatrical releases and international streaming co-productions. The Osaka-Kyoto cluster expands capacity through METI SME digitalization grants for cloud rendering infrastructure.
Chubu/Nagoya
Industrial automation expertise from Toyota's supply chain feeds motion capture and virtual production workflow adoption. Regional technical colleges partner with studios on real-time engine training pipelines. Nagoya-based facilities capture overflow work from Tokyo production committees.
Kyushu
Fukuoka studios adopt Unreal Engine and Unity pipelines for virtual cinematography at accelerating rates. Government regional revitalization funds subsidize facility construction outside the Tokyo-Osaka axis. Distributed teams here collaborate on shared virtual stages with reduced physical asset requirements.
Hokkaido
Cold climate data centers offer competitive cloud rendering infrastructure for Tokyo production committees. Sapporo technical institutes train digital compositing talent for HDR color grading workflows. Regional content funds support co-productions targeting winter tourism and location-based entertainment tie-ins.
Japan Animation, VFX and Post Production Market Competitive Landscape
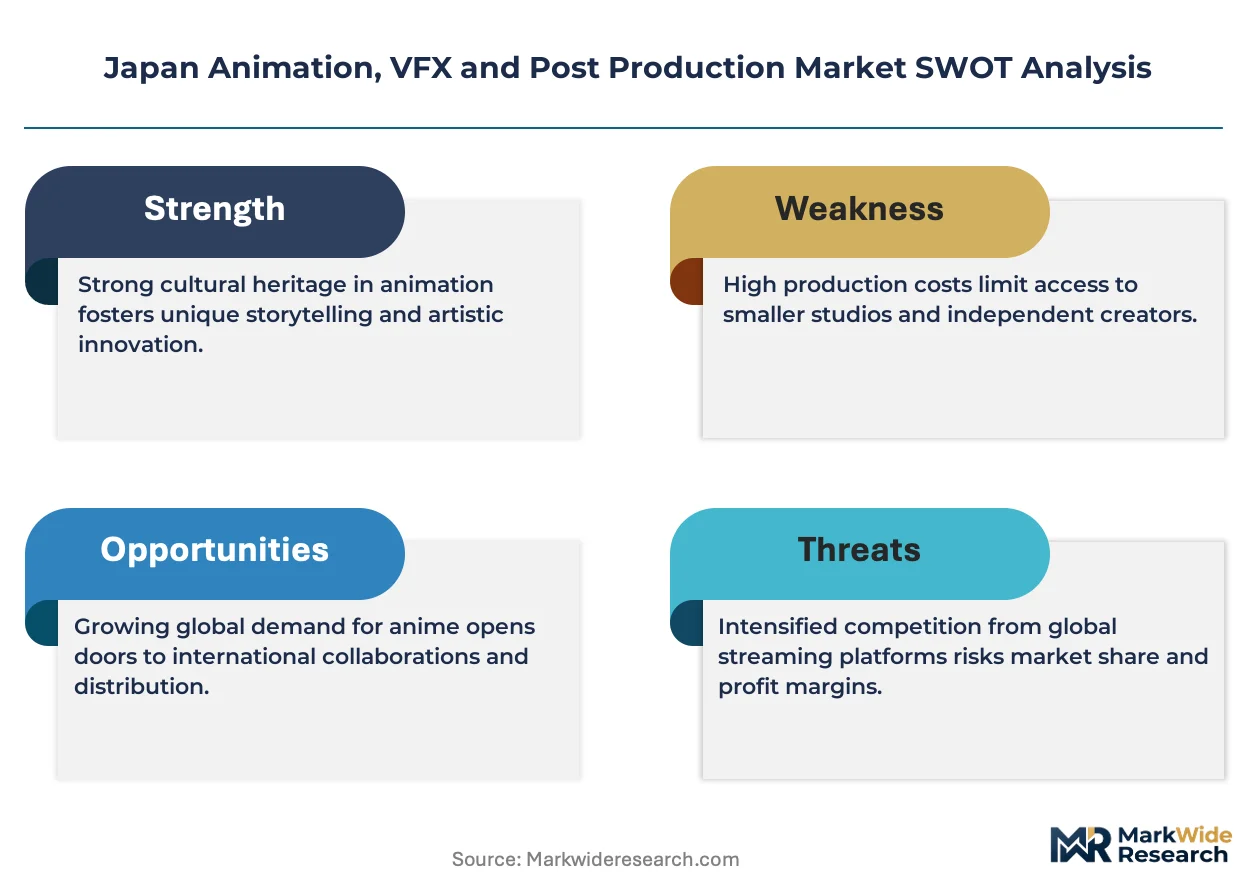
Diversified conglomerates compete with focused pure-play specialists across Japan's animation value chain. The market structure tilts toward tiered specialization rather than horizontal consolidation. Three archetypes dominate: vertically integrated franchise stewards, technology-forward digital production houses, and modular subcontracting specialists. Competitive moves concentrate on talent retention through working condition reforms and infrastructure expansion into lower-cost regional clusters.
Among legacy franchise holders, Toei Animation Co. exemplifies vertical control through in-house production capacity sustaining long-running properties. Production I.G occupies a position emphasizing technology leadership in digital compositing and virtual production workflows. Graphinica anchors specialized VFX subcontracting, capturing margin through technical scarcity in theatrical and streaming co-production pipelines. These three represent distinct strategic postures rather than direct segment overlap.
| Leading Market Players |
|---|
| Toei Animation Co. |
| BONUS.CO.JP |
| Sony Pictures Animation |
| DLE, Inc. |
| Studio Ghibli |
| Production I.G |
| Imagica Lab |
| Graphinica |
| Tokyo Laboratory Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Keyframe animator concentration in Tokyo's Suginami and Nerima wards drives labor-cost premiums that widen pricing spreads between premium franchise-grade productions and economy-tier subcontractor output. Cost differentials between these talent pools force production committees to tier commissioning structures based on quality certification and export-market compliance requirements.
Pricing Analysis
Margin tightening in mid-tier theatrical productions traces to JIS digital cinema compliance certification costs that burden productions seeking premium distribution windows. Project-based pricing stratifies across premium franchise properties, standard series commissions, and economy-tier subcontractor packages, with differentiation hinging on key animator pedigree and HDR mastering capabilities. Cost-down pressure on in-betweening services accelerates as generative AI tools compress background art timelines. Streaming platforms exhibit lowest price sensitivity due to minimum-guarantee licensing structures, while independent theatrical distributors face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Chinese cloud rendering infrastructure providers serving Tokyo production committees during peak capacity windows. Raw material dependencies encompass perpetual software licenses from Autodesk and Foundry, HPC cluster access, and specialized Wacom digitizing tablets. Supply chain risk centers on tariff exposure for hardware components crossing regional trade boundaries. Distribution runs through modular procurement templates that unbundle post-production services from integrated production committee contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
JIS digital cinema compliance creates a cost-of-compliance moat that rewards certified players with theatrical distribution access while excluding uncertified competitors from premium revenue tiers.
For Market Incumbents: Cement franchise-grade quality premiums by securing exclusive key animator retainers in Tokyo's western wards before talent scarcity worsens. Expand cloud rendering capacity through METI SME digitalization grants to reduce reliance on South Korean infrastructure providers. Defend against modular procurement fragmentation by integrating color grading and HDR mastering capabilities in-house. For New Entrants and Emerging Players: The price-point gap between premium theatrical releases and economy-tier streaming commissions creates white-space for mid-budget productions targeting international co-production treaties. Enter through Osaka-Kyoto cluster facilities with lower operational costs than Tokyo precincts. Pursue virtual production workflow specialization using Unreal Engine pipelines to bypass traditional key animator bottlenecks. For Investors and Strategic Acquirers: Re-rating potential sits with specialized VFX subcontracting houses given streaming platform content budget expansion and technical talent scarcity in digital compositing. Long-term viability favors asset-light technical specialists over fixed-capacity traditional studios. Watch for inflection when METI revises Cool Japan subsidy criteria to favor demonstrable export revenue performance over production volume metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Rendering Infrastructure Expansion | METI grants enable mid-tier houses to compete with Tokyo's integrated studios on capacity. |
| Virtual Production Workflow Adoption | Unreal Engine pipelines decentralize production authority away from Suginami and Nerima wards. |
| Key Animator Retention Programs | Working condition reforms secure scarce talent before generative AI displaces in-betweening roles. |
| Osaka-Kyoto Cluster Facility Buildout | Lower operational costs attract secondary studios outside saturated Tokyo production corridors. |
| JIS Compliance Certification Investment | Theatrical distribution access requires technical validation that mid-tier productions struggle to fund. |
Research Methodology
Agency for Cultural Affairs export subsidy filings, METI Cool Japan program disclosures, and JIS standards documentation formed the secondary backbone for production volume and policy incentive quantification. Primary interviews with production committee executives, streaming platform commissioning leads, post-production facility technical directors, and key animator guild representatives validated cost structures and talent deployment patterns. Bottom-up project pipeline tracking and top-down industry association membership analysis enabled triangulation across data sources.
Historical trendline analysis examined production committee formation rates, streaming licensing deal announcements, and theatrical release counts across the analysis window. Segmentation modeling incorporated service type, production stage, distribution channel, and target audience dimensions with regional cluster overlays. CAGRs derived from production volume trajectories and per-project budget surveys across Tokyo-Osaka corridor facilities. Forecast inputs included streaming platform content budget disclosures and METI SME digitalization grant uptake rates.
Underlying measurement precision varies by segment; streaming commissioning data carries tighter precision than theatrical box office attribution. Forecasts reflect assumptions about Cool Japan policy continuity, generative AI adoption curves, and key animator succession pipeline viability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
Drive-In Movie Theater Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Movie Tickets Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Camera Jib Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
North America 3D Cinema Screen Market