
 Film Dubbing Market | 2026-2036
Film Dubbing Market Size, Share, and Industry Trends Forecast 2026-2036
Film Dubbing Market Foresight
India is fragmenting as new dubbing clusters emerge in Mumbai, Hyderabad, and Chennai to serve streaming demand. BTI Studios leverages its European network to sustain multi-language capacity across theatrical and OTT releases. Keywords Studios anchors high-end game-to-film adaptation work through specialized voice direction pipelines. Iyuno-SDI Group competes on scale, operating localized facilities in over thirty territories to reduce turnaround times for platform clients.
Film dubbing is the post-production process of replacing original dialogue tracks with translated voice performances, synchronized to lip movements through automated dialogue replacement and time-stretching algorithms at 48 kHz sample rates. Its commercial purpose is to eliminate language barriers and expand addressable audiences for audiovisual content across territories. Voice-over and re-recording services dominate current revenue pools as theatrical releases and serialized content require full-cast replacement, while AI voice synthesis represents the fastest-growing technology segment as studios pilot neural voice cloning for secondary-language distribution. Streaming platforms and film studios anchor end-user demand, with direct sales channels capturing premium project margins.
India's Central Board of Film Certification and the Bureau of Indian Standards shape content approval timelines and technical quality benchmarks for theatrical releases. The EU's Audiovisual Media Services Directive mandates accessibility quotas that expand subtitling and audio description requirements across member states. Stakeholders must monitor regulatory divergence between territorial content codes and emerging AI-generated voice disclosure rules as automation scales.
Market Dynamics
Neural voice synthesis is collapsing traditional dubbing timelines as streaming platforms demand same-day multilingual releases, forcing facilities to reconfigure talent pools and technical infrastructure around hybrid human-AI workflows.
Growth Catalysts
- EU Audiovisual Media Services Directive:Accessibility quotas mandate expanded audio description and multilingual tracks across member states, creating baseline demand for dubbing services.
- Streaming platform localization:Netflix, Disney+, and regional OTT operators commission 20-40 language versions per original production, multiplying project volumes.
- 48 kHz time-stretching algorithms:Automated dialogue replacement tools reduce lip-sync adjustment labor, compressing post-production schedules.
Market Restraints
- Voice actor guild minimums:SAG-AFTRA and European union rate cards elevate labor costs above AI-only alternatives, constraining margin expansion.
- Facility concentration in Mumbai-Chennai-Hyderabad:India's dubbing cluster dominance creates bottlenecks during peak release windows.
- Original performance licensing:Studio contracts often restrict voice cloning rights, blocking neural synthesis deployment on A-list titles.
Strategic Opportunities
- Indonesia-Philippines-Vietnam streaming penetration:Southeast Asian language dubbing remains underserved relative to subscriber growth.
- Game-to-film adaptation pipelines:Interactive entertainment IP requires specialized voice direction for cinematic releases.
- AI voice disclosure rules:Emerging transparency mandates favor established facilities with compliance infrastructure over pure-synthetic entrants.
Industry Challenges
- Lip-sync precision engineering:Automated systems still require manual frame-level correction for emotional dialogue sequences.
- Cross-border talent mobility:Visa processing delays for specialized voice directors disrupt multinational project staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Film Dubbing Market |
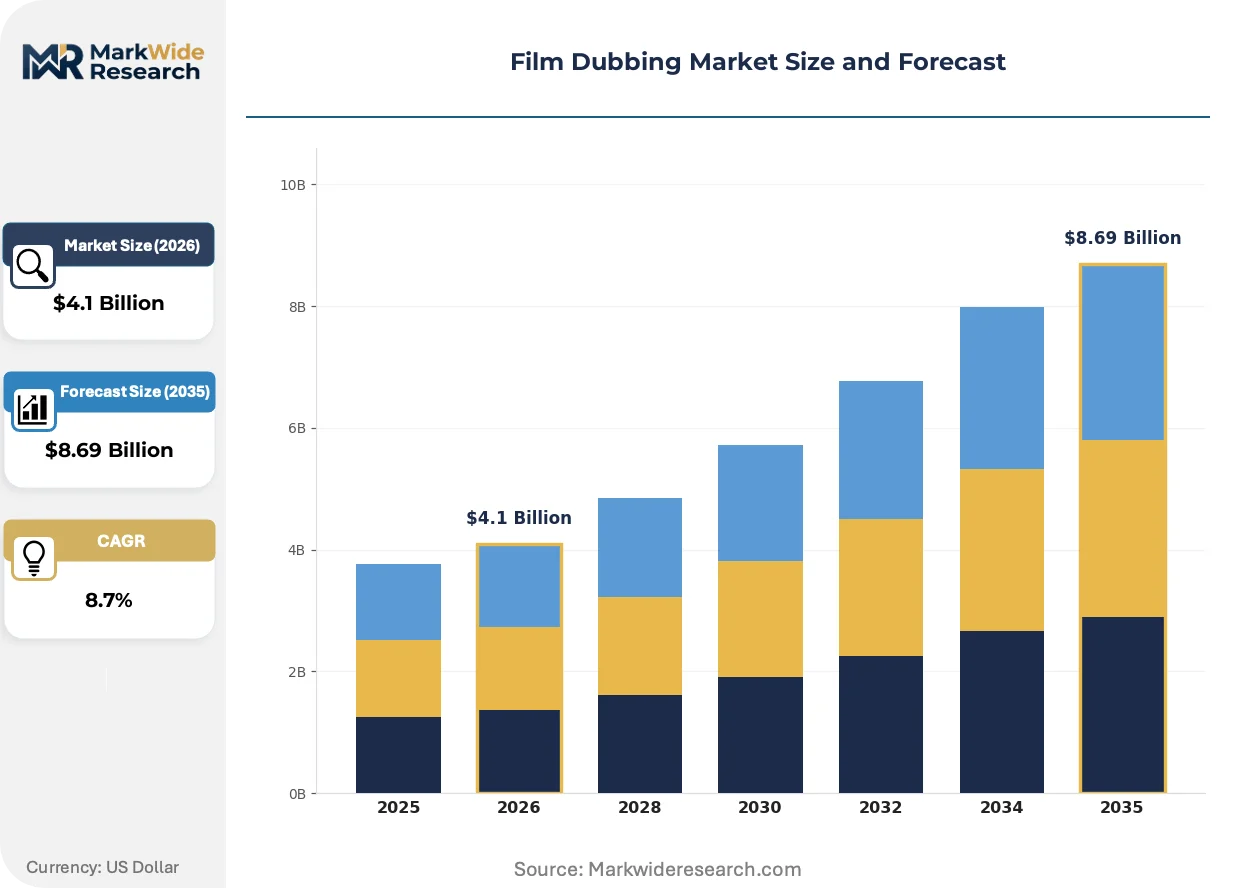
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice-over, Subtitling, Re-Recording, Casting Technology: Digital Audio Workstation, Cloud-based Solutions, AI Voice Synthesis, Hybrid Systems End User: Film Studios, Streaming Platforms, TV Networks, Independent Filmmakers Distribution Channel: Direct Sales, Online Platforms, Partnerships, Distributors |
| Companies Covered | ABC Dubbing and Subtitles Studios, BTI Studios, Iyuno-SDI Group, Mafilm Audio, Groupe Auditorium Artistique, Keywords Studios, AudioMaster, VSI (Voice & Script International), Sukudo Studios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Film Dubbing Market Shifts & Advancements
Three distinct vectors are reconfiguring how dubbed content reaches audiences: synthetic voice pipelines, territorial compliance frameworks, and platform-driven procurement models. Each trend carries specific implications for facility investment and competitive positioning.
Neural voice cloning systems are collapsing the cost structure for secondary-language distribution. These platforms generate synthetic performances from limited source recordings. Mid-tier streaming catalog titles now deploy hybrid workflows where AI handles background characters and human actors anchor lead roles. The technology is collapsing price floors for standardized dubbing, forcing traditional facilities to differentiate through directorial quality.
India's Central Board of Film Certification maintains theatrical approval timelines that extend post-production schedules by 15-30 days. The Bureau of Indian Standards enforces technical quality benchmarks for cinema releases that exceed streaming specifications. Domestic theatrical distributors absorb these delays as a cost of accessing India's 9,000+ screen market, while platform-first producers route content through faster OTT certification pathways.
Platform procurement teams now contract directly with dubbing facilities, bypassing traditional studio intermediaries. Netflix's preferred vendor programs establish volume commitments and fixed rate cards across 30+ languages. This disintermediation concentrates purchasing power with streaming operators, compressing margins for facilities outside preferred supplier tiers. The shift is most visible in European markets where platform originals now exceed licensed acquisitions.
Film Dubbing Market Segmentation
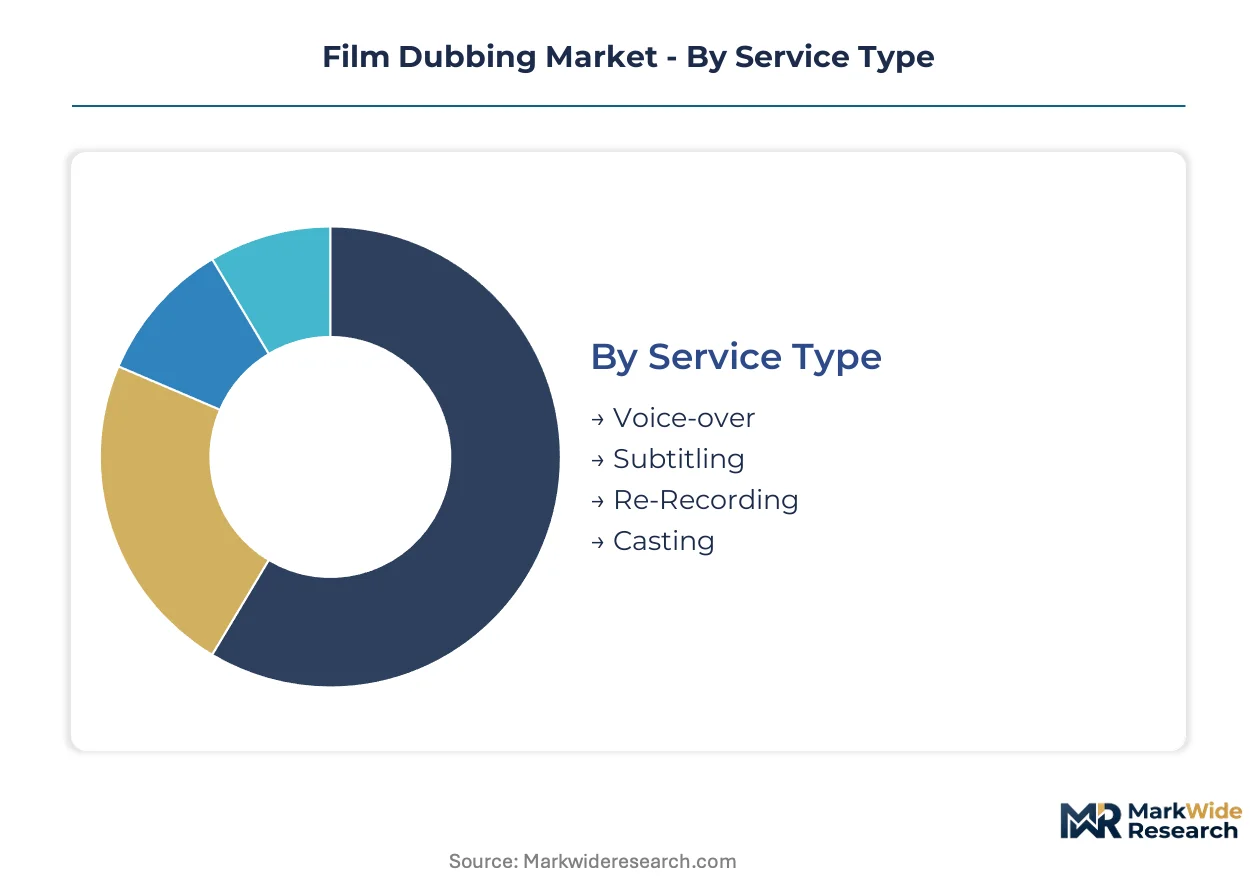
Film dubbing market segmentation reveals how service providers allocate capital across divergent technical and commercial requirements. Distinct procurement patterns emerge between theatrical distributors demanding broadcast-grade mastering and streaming operators optimizing for volume velocity.
Service Type:
Mature theatrical workflows coexist with emerging platform-native formats as demand fragments across release windows.
- Voice-over:Narration-driven replacement where original dialogue remains partially audible beneath translated tracks. Documentary and reality content in Indonesia and Vietnam drives volume as unscripted programming expands regional platform catalogs.
- Re-Recording:Full-cast automated dialogue replacement synchronized to 48 kHz broadcast specifications. Mumbai and Chennai facilities handle peak theatrical loads for Bollywood and regional cinema exports.
- Subtitling:Text-based translation paired with original audio preservation. European accessibility mandates under the EU Audiovisual Media Services Directive expand baseline procurement.
- Casting:Talent identification and contract negotiation for multi-language voice ensembles. Hyderabad's emerging cluster competes with established Mumbai agencies for streaming platform contracts.
Re-recording handles the majority of throughput; AI-assisted voice-over is gaining share fastest as platforms pilot synthetic narration for catalog content.
Technology:
Cost tier stratification separates premium facilities investing in proprietary pipelines from operators deploying standardized cloud infrastructure.
- AI Voice Synthesis:Neural cloning systems generating performances from limited source recordings. Disney+ and Netflix pilot hybrid workflows where synthetic voices cover background characters while human actors anchor leads.
- Digital Audio Workstation:Pro Tools and Nuendo-based editing suites with frame-level lip-sync precision. Established European facilities anchor high-end theatrical releases requiring manual correction protocols.
- Cloud-based Solutions:Distributed rendering and collaborative review platforms reducing facility capital requirements. Independent filmmakers in the Philippines and Vietnam access tier-one technical capacity without physical infrastructure investment.
- Hybrid Systems:Human-AI workflows combining automated dialogue replacement with director oversight. SAG-AFTRA contract minimums constrain full automation on A-list theatrical titles.
Digital Audio Workstation deployments dominate current infrastructure investment; AI Voice Synthesis shows the steepest expansion trajectory as platforms mandate same-day multilingual release windows.
End User:
Customer type determines pricing power and technical specification stringency across the procurement landscape.
- Streaming Platforms:Netflix, Disney+, and regional OTT operators commissioning 20-40 language versions per original production. Direct vendor programs disintermediate traditional studio intermediaries and compress rate cards.
- Film Studios:Theatrical distributors requiring CBFC certification and BIS technical compliance for India's 9,000+ screen market. Original performance licensing restrictions block neural synthesis deployment on star-driven titles.
- TV Networks:Broadcasters with fixed seasonal schedules and established union relationships. Linear programming maintains traditional re-recording workflows despite platform competition.
- Independent Filmmakers:Budget-constrained producers leveraging cloud-based solutions and AI-assisted workflows. Southeast Asian festival circuits drive demand for rapid-turnaround localization.
Streaming Platforms concentrate procurement volume; Independent Filmmakers are expanding most quickly as production tools democratize.
Distribution Channel:
Supply concentration in direct sales relationships reshapes margin capture across the value chain.
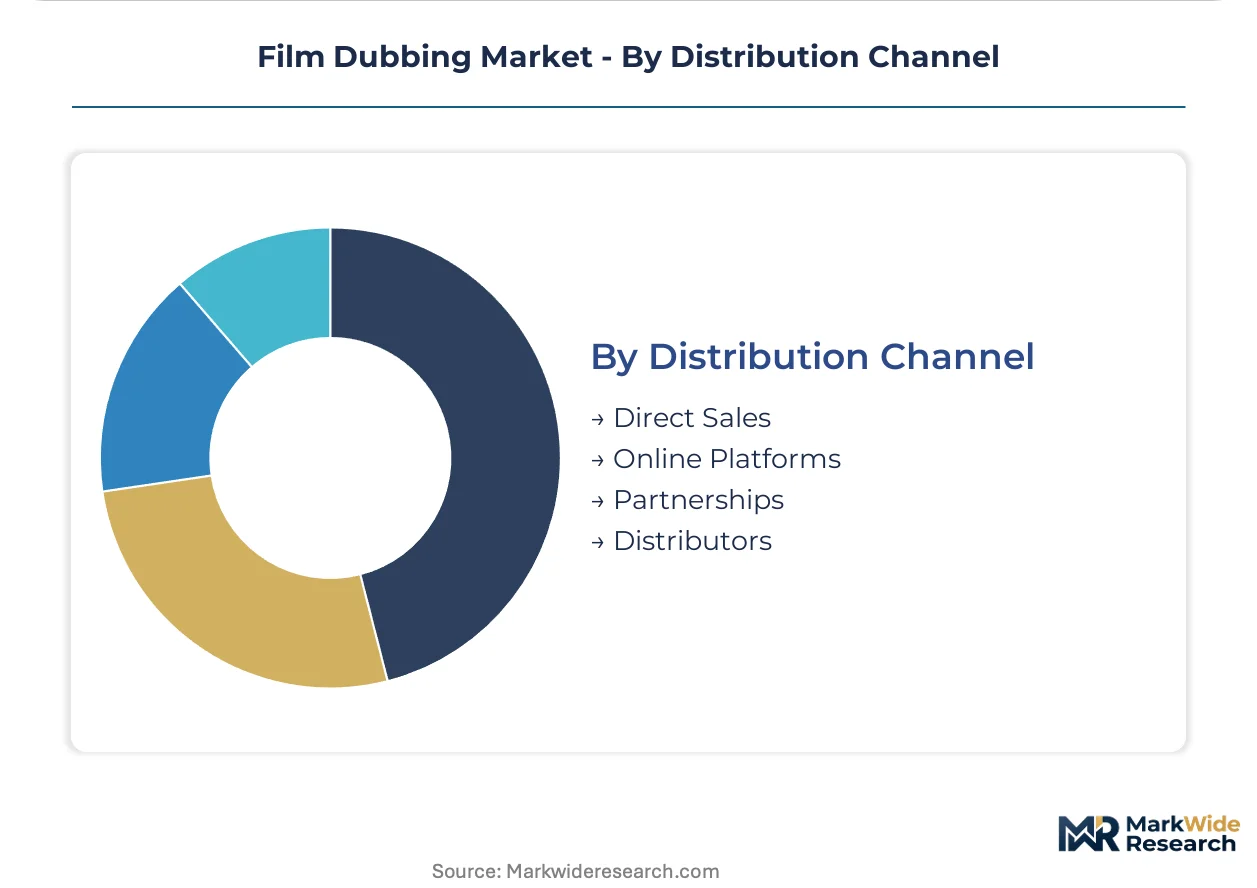
- Direct Sales:Facility-to-platform contracts establishing volume commitments and fixed rate cards. Netflix's preferred vendor tiers concentrate purchasing power with three to five approved suppliers per language pair.
- Partnerships:Co-production arrangements splitting localization costs across territorial distributors. European theatrical networks deploy this structure for mid-budget co-ventures.
- Online Platforms:Self-service portals for independent producers and short-form content creators. Automated quotation engines reduce sales overhead for standardized project scopes.
- Distributors:Traditional intermediaries aggregating theatrical and home entertainment localization. Margin compression from platform disintermediation forces consolidation among legacy aggregator networks.
Direct Sales captures the dominant share of high-value project flow; Online Platforms are climbing the fastest as self-service tools penetrate the independent segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Central Board of Film Certification and Bureau of Indian Standards anchor theatrical localization protocols. Streaming operators in Southeast Asia accelerate multilingual commissioning. European accessibility mandates expand baseline service demand.
India
Netflix and Disney+ commission 20-40 language versions per original production, multiplying project volumes for Mumbai facilities. The Central Board of Film Certification extends post-production schedules by 15-30 days for theatrical releases. The Mumbai-Chennai-Hyderabad cluster concentrates capacity as Bollywood and regional cinema expand international distribution.
United States
SAG-AFTRA rate cards elevate labor costs above AI-only alternatives, constraining margin expansion on A-list titles. The Federal Communications Commission maintains broadcast accessibility requirements that expand audio description procurement. Los Angeles facilities anchor high-end theatrical releases requiring manual lip-sync correction protocols.
Germany
The EU Audiovisual Media Services Directive mandates accessibility quotas that expand multilingual tracks across member states. ECHA chemical safety protocols indirectly shape studio facility compliance for voice recording environments. Berlin and Munich facilities serve theatrical distributors requiring broadcast-grade 48 kHz mastering specifications.
France
ANSM content oversight and CNIL data protection frameworks shape AI voice cloning disclosure requirements for synthetic performances. The Toubon Law mandates French-language dubbing for theatrical releases, preserving baseline demand for traditional workflows. Paris facilities specialize in high-end game-to-film adaptation voice direction.
Indonesia
Streaming penetration in Jakarta and Surabaya outpaces localized content supply, creating capacity bottlenecks for Bahasa Indonesia dubbing. The national film censorship board maintains theatrical approval timelines that compress post-production windows. Bandung and Yogyakarta emerging clusters compete for platform vendor program contracts.
Film Dubbing Market Competitive Landscape
Scale-driven networks and specialized boutiques split the market into distinct procurement tiers. Facility concentration in India and Europe creates regional bottlenecks during peak release windows. Strategic archetypes include multi-territory volume operators, premium theatrical specialists, and cloud-native independents. M&A activity concentrates purchasing power with platform-preferred vendors while technology licensing agreements accelerate AI workflow adoption.
Among European-based volume operators, BTI Studios and Iyuno-SDI Group exemplify the multi-territory archetype with localized facilities spanning over thirty territories. Keywords Studios occupies a position within the premium specialization tier, anchoring high-end game-to-film adaptation work through dedicated voice direction infrastructure. These three entities represent how scale, geographic reach, and technical specialization define competitive positioning as streaming platforms consolidate vendor relationships.
| Leading Market Players |
|---|
| ABC Dubbing and Subtitles Studios |
| BTI Studios |
| Iyuno-SDI Group |
| Mafilm Audio |
| Groupe Auditorium Artistique |
| Keywords Studios |
| AudioMaster |
| VSI (Voice & Script International) |
| Sukudo Studios |
| Others |
Supply & Pricing Matrix
Mumbai's dubbing cluster concentration shapes downstream pricing power as streaming platforms consolidate vendor relationships around preferred supplier tiers. The Central Board of Film Certification extends theatrical post-production timelines, forcing facilities to absorb carrying costs that compress margins on CBFC-compliant projects.
Pricing Analysis
Rate spreads between Mumbai theatrical facilities and Jakarta cloud-native operators span 3-5x for equivalent language pairs. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-grade 48 kHz mastering from AI-assisted voice-over and synthetic narration tiers. Cost compression in the standard tier intensifies because Netflix and Disney+ fixed rate cards cap per-language project fees. Independent filmmakers in Southeast Asia exhibit highest price sensitivity; theatrical distributors requiring BIS certification demonstrate lowest.
Supply Chain Analysis
Visa processing delays between India and European Union member states dominate supply chain risk for multinational voice director staffing. Geographic supply concentration centers on India, Germany, and France as anchor territories for theatrical and streaming localization. Raw material dependencies encompass Pro Tools/Nuendo licensing, acoustic studio construction, and SAG-AFTRA-compliant talent pools. Single-source vulnerability sits with cloud rendering infrastructure concentrated among three hyperscaler providers. Distribution runs through direct facility-to-platform contracts that disintermediate legacy aggregator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neural voice synthesis disruption is reshaping competitive positioning as same-day multilingual release windows become standard procurement requirements. The EU Audiovisual Media Services Directive accessibility mandates create baseline demand expansion that favors established compliance infrastructure.
For Market Incumbents: Harden directorial quality differentiation against AI-only entrants by investing in hybrid human-AI workflow certification and expanding Hyderabad-Chennai capacity to relieve Mumbai bottlenecks. Secure voice cloning rights through renegotiated original performance licensing terms before SAG-AFTRA disclosure rules formalize.
For New Entrants and Emerging Players: Build out Indonesia-Philippines-Vietnam language capacity as platform subscriber growth outpaces localized content supply. Target Bahasa Indonesia and Vietnamese dubbing as most penetrable segments. Pursue cloud-native infrastructure partnerships to bypass capital-intensive studio construction.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-dependency play because vendor consolidation around Netflix-Disney+ preferred tiers will concentrate purchasing power with three to five approved suppliers per language pair. Target mid-scale facilities with established CBFC-BIS relationships and existing AI workflow pilots. Watch for SAG-AFTRA disclosure rule finalization as inflection signal for synthetic voice deployment permissions.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Hybrid Workflow Certification | Establishes compliance infrastructure ahead of EU AI Act disclosure requirements for synthetic performances. |
| Multi-Territory Facility Expansion | Reduces turnaround times for platform clients demanding 20-40 language versions per original production. |
| Voice Cloning Rights Acquisition | Unlocks neural synthesis deployment on catalog content currently blocked by original performance licensing restrictions. |
| Cloud Rendering Infrastructure Partnership | Democratizes tier-one technical capacity for independent filmmakers in Philippines and Vietnam. |
| Preferred Vendor Program Enrollment | Captures volume commitments and fixed rate cards from Netflix and Disney+ procurement teams. |
Research Methodology
The analysis maps voice-over, re-recording, subtitling, and casting service verticals, each validated through voice directors, platform localization executives, facility technical leads, and talent agency contract specialists. Primary interviews with streaming procurement officers and theatrical distributors combined with secondary validation against CBFC certification databases, BIS technical standards, EU Audiovisual Media Services Directive filings, and SAG-AFTRA contract documentation. Bottom-up project volume estimates and top-down platform content spend analysis provide triangulation.
Assumptions held fixed include current CBFC approval timelines, SAG-AFTRA rate card structures, and neural synthesis accuracy thresholds; variables tested encompass streaming subscriber growth trajectories in Southeast Asia and AI disclosure rule implementation timing. Segmentation dimensions modeled cover service type, technology tier, end-user category, and distribution channel across the projection horizon. CAGRs derive from weighted average of historical project volume expansion and platform localization budget growth. Industry-specific inputs include 48 kHz broadcast specification adoption rates and hybrid workflow penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-synthetic entrants or regulatory acceleration on AI disclosure would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Movie Tickets Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Drive-In Movie Theater Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Camera Jib Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
Global Advanced Cinema Projector Market