
 United Kingdom Animation, VFX and Post Production Market | 2026-2036
United Kingdom Animation, VFX and Post Production Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Animation, VFX and Post Production Market Insights
The UK's Screen Sustainability Charter is rebalancing production workflows toward carbon-accounted VFX pipelines. Framestore Limited leverages its London facility network to anchor high-end feature film work. DNEG sustains competitive capacity across multiple UK sites. MPC specializes in episodic streaming content, differentiating its service portfolio from theatrical-heavy rivals.
Animation, VFX and Post Production encompasses digital content creation services spanning 2D animation, 3D animation, visual effects compositing, and editorial finishing, delivered through render farm infrastructure, motion capture stages, and color-grading suites to produce broadcast-ready masters. The primary commercial purpose is transforming raw footage or concept art into finished moving-image content for distribution across theatrical, streaming, and broadcast channels. 3D animation and visual effects command premium pricing due to compute-intensive pipeline requirements and scarce artist specialization. Post production services represent a mature margin pool where facility utilization rates determine profitability. Streaming services distribution channels are expanding fastest as platform-exclusive commissioning reshapes client type demand toward studios with volume-series mandates.
Ofcom's broadcasting codes and the British Film Institute's certification standards shape content eligibility for Creative Industries Tax Relief, directly conditioning which productions access fiscal incentives. BSI standards for media asset management and the UK's implementation of GDPR through the Information Commissioner's Office impose data governance requirements on cloud-based collaborative workflows. Stakeholders must monitor how forthcoming revisions to the Audio-Visual Media Services Directive through UK statutory instruments alter platform content obligations and consequently VFX procurement patterns.
Market Dynamics
The UK's Creative Industries Tax Relief is restructuring commissioning patterns by conditioning fiscal access on British Film Institute certification standards, concentrating investment in qualifying domestic productions while streaming platforms escalate volume mandates for episodic content.
Growth Catalysts
- Creative Industries Tax Relief:The British Film Institute's certification framework incentivizes qualifying productions to route post-production spend through UK facilities, expanding facility utilization rates across London and Manchester.
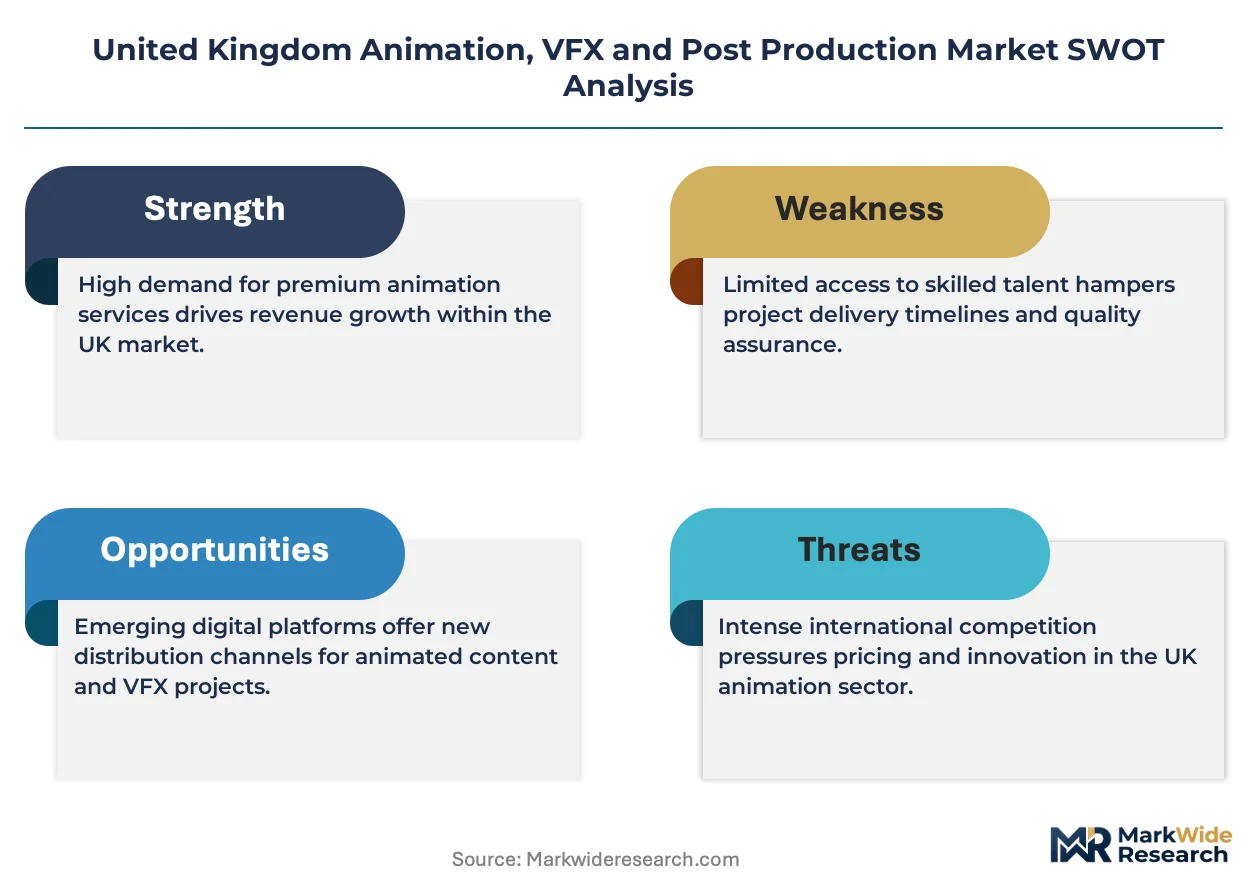
- Streaming platform commissioning:Platform-exclusive volume mandates from Netflix, Amazon Prime Video, and Disney+ are pulling capacity toward episodic series pipelines with compressed delivery schedules.
- Carbon-accounted VFX pipelines:The UK's Screen Sustainability Charter is mandating emissions reporting across post-production workflows, differentiating certified facilities in competitive tenders.
Market Restraints
- Compute infrastructure concentration:Render farm capacity concentrates in London's Soho cluster, creating geographic single-point-of-failure risk for time-critical delivery pipelines.
- Artist specialization scarcity:Advanced simulation and creature effects expertise remains structurally limited, constraining throughput for high-end feature film work regardless of facility capital investment.
- GDPR-imposed workflow friction:The Information Commissioner's Office enforcement of cloud-based collaborative data governance adds compliance overhead to international co-production pipelines.
Strategic Opportunities
- Manchester media hub expansion:Lower facility costs and regional tax incentives are pulling post-production capacity northward from London, creating geographic diversification for volume-series producers.
- Virtual production convergence:LED volume stages integrated with real-time game engines are collapsing pre-production and post-production boundaries, enabling new service bundling models.
- Audio-Visual Media Services Directive revisions:Forthcoming UK statutory instruments altering platform content obligations will reshape VFX procurement patterns toward domestic quota-compliant productions.
Industry Challenges
- Real-time pipeline skill gaps:Virtual production workflows demand Unreal Engine and LED volume technical artists that traditional VFX training pipelines have not scaled to produce.
- Legacy asset management integration:Cloud-native collaborative tools must interface with decades of facility-specific archive formats, creating data migration bottlenecks for established houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Animation, VFX and Post Production Market |
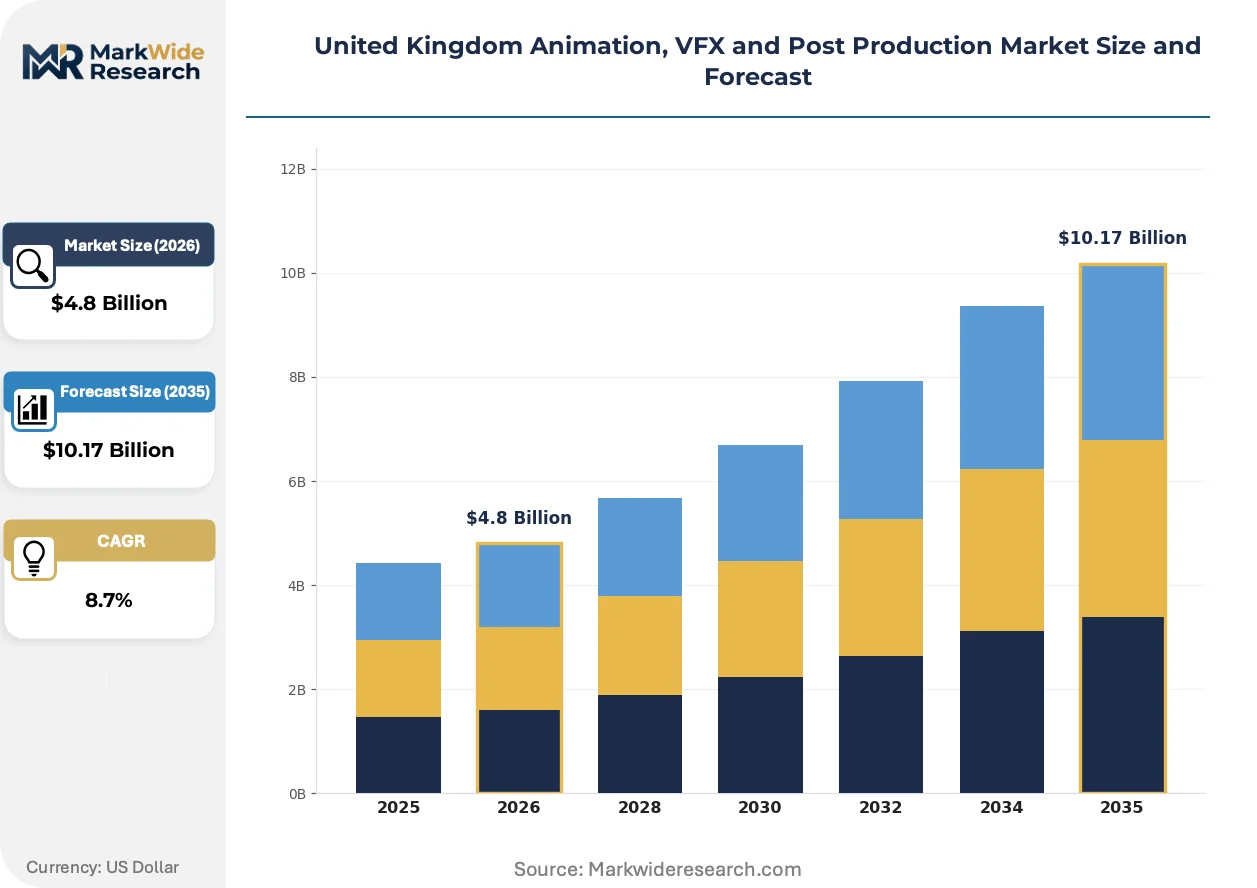
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 2D Animation, 3D Animation, Visual Effects, Post Production Application: Film, Television, Video Games, Advertising Client Type: Studios, Independent Filmmakers, Corporations, Agencies Distribution Channel: Theatrical, Streaming Services, Television Networks, Online Platforms |
| Companies Covered | Framestore Limited, Aardman Animations Ltd, Jellyfish Pictures, Blue Zoo Animation Studio, Cinesite, The Mill, DNEG, Outpost VFX, MPC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Animation, VFX and Post Production Market Trends and Innovations
Generative artificial intelligence is penetrating editorial and compositing workflows, compressing iteration cycles while forcing recalibration of artist role definitions across British post-production facilities.
Real-time rendering engines are rewriting production economics by collapsing the separation between principal photography and final pixel delivery. Virtual art departments at Pinewood Studios and Shepperton are deploying Unreal Engine 5 for in-camera VFX, enabling directors to lock final imagery on set. This convergence is compressing post-production schedules from months to weeks for qualifying productions.
The British Film Institute's evolving certification standards are tightening eligibility criteria for Creative Industries Tax Relief, redirecting investment toward productions meeting cultural content thresholds. Facilities are restructuring service portfolios to capture qualifying spend, while non-qualifying international work migrates toward competing European hubs. Manchester and Belfast facilities are positioning to absorb displaced volume through regional incentive stacking.
Platform-exclusive commissioning is consolidating buyer power among streaming services with multi-year volume mandates. Netflix and Amazon are requiring integrated post-production partnerships spanning dailies through final delivery, displacing the traditional fragmented vendor model. This concentration is most visible in London's Soho district, where facilities are restructuring as platform-embedded service units with dedicated pipeline investments.
United Kingdom Animation, VFX and Post Production Market Segmentation
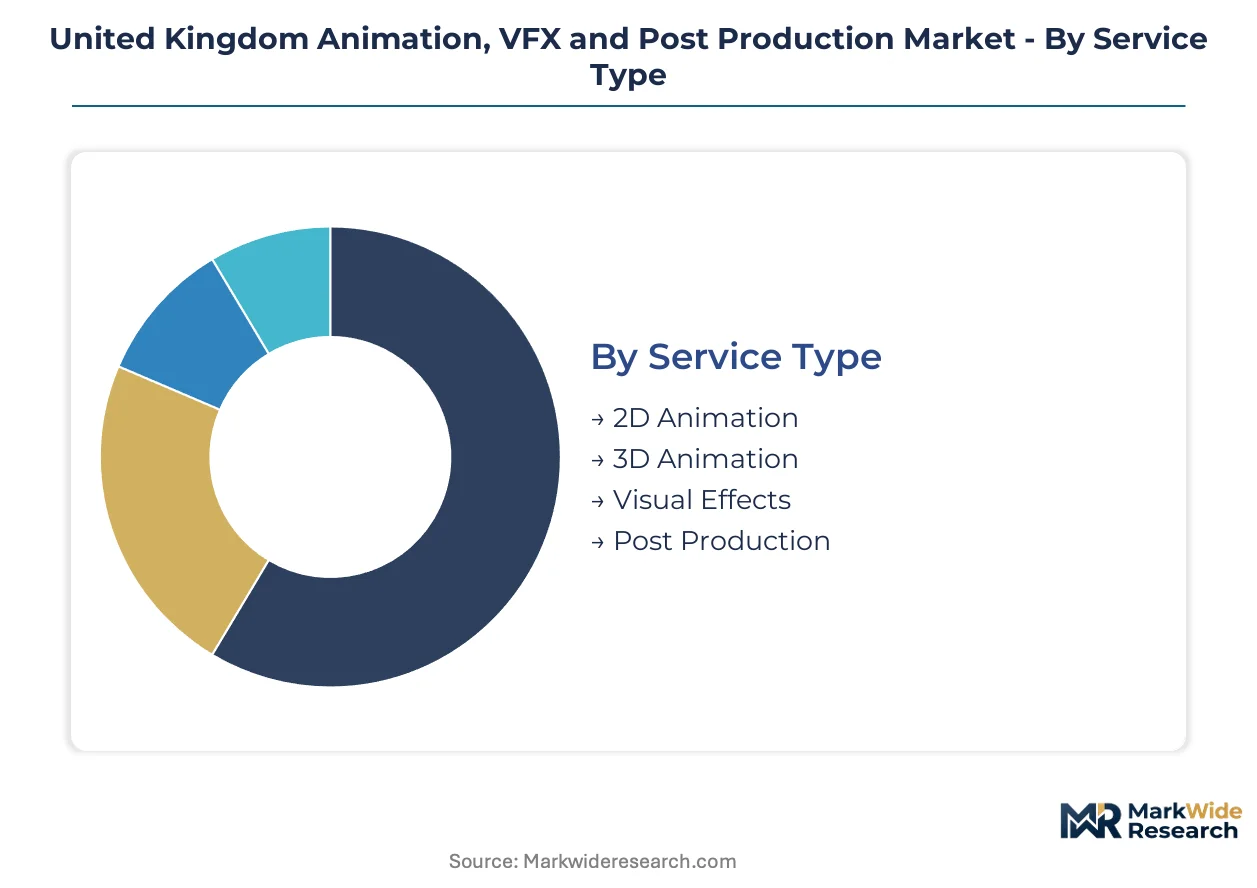
Service differentiation across animation, VFX and post production determines facility capital allocation and artist specialization pipelines. Buyer procurement patterns diverge sharply between theatrical tentpoles demanding creature effects mastery and streaming volume series prioritizing turnaround velocity.
Service Type:
Production budget tier dictates service selection, with premium features commanding compute-intensive pipelines and episodic content optimizing for throughput economics.
- 3D Animation:Compute-intensive pipelines require render farm infrastructure and specialized rigging artists. Demand concentrates in theatrical feature production from Pinewood and Shepperton facilities, constrained by scarce simulation expertise and compressed delivery windows from streamer volume mandates.
- Visual Effects:Compositing, simulation and creature effects work demands advanced artist specialization and motion capture stages. London's Soho cluster anchors high-end feature film work, though carbon-accounted pipeline certification is differentiating facilities in competitive tenders.
- 2D Animation:Traditional cel and digital 2D techniques serve episodic series and advertising content with lower infrastructure thresholds.
- Post Production:Editorial finishing, color grading and sound design represent mature margin pools where facility utilization rates determine profitability.
Volume sits with Post Production; growth tilts toward Visual Effects.
Application:
End-use format shapes technical specifications, delivery protocols and certification requirements for tax relief eligibility.
- Television:Episodic series production with compressed schedules and volume mandates from platform-exclusive commissioning. Manchester's emerging media hub is absorbing displaced volume through regional incentive stacking, while London facilities restructure as platform-embedded service units.
- Film:Theatrical features demanding highest-fidelity creature effects and simulation work. British Film Institute certification standards condition Creative Industries Tax Relief access, concentrating investment in qualifying domestic productions.
- Video Games:Real-time asset creation for interactive entertainment, converging with virtual production pipelines.
- Advertising:Commercial content with rapid turnaround requirements and brand-direct client relationships.
Revenue concentrates in Film; expansion accelerates fastest in Television.
Client Type:
Procurement scale and contract structure vary dramatically between volume-series streamers and project-based independents.
- Studios:Major production entities with multi-year volume mandates requiring integrated partnerships spanning dailies through final delivery. Netflix and Amazon are consolidating vendor relationships, displacing fragmented procurement models.
- Agencies:Creative services firms managing brand advertising content with rapid iteration cycles.
- Independent Filmmakers:Project-based producers accessing tax relief through British Film Institute certification frameworks.
- Corporations:Enterprise clients commissioning internal and promotional video content.
Contract value sits with Studios; pipeline diversification tilts toward Agencies.
Distribution Channel:
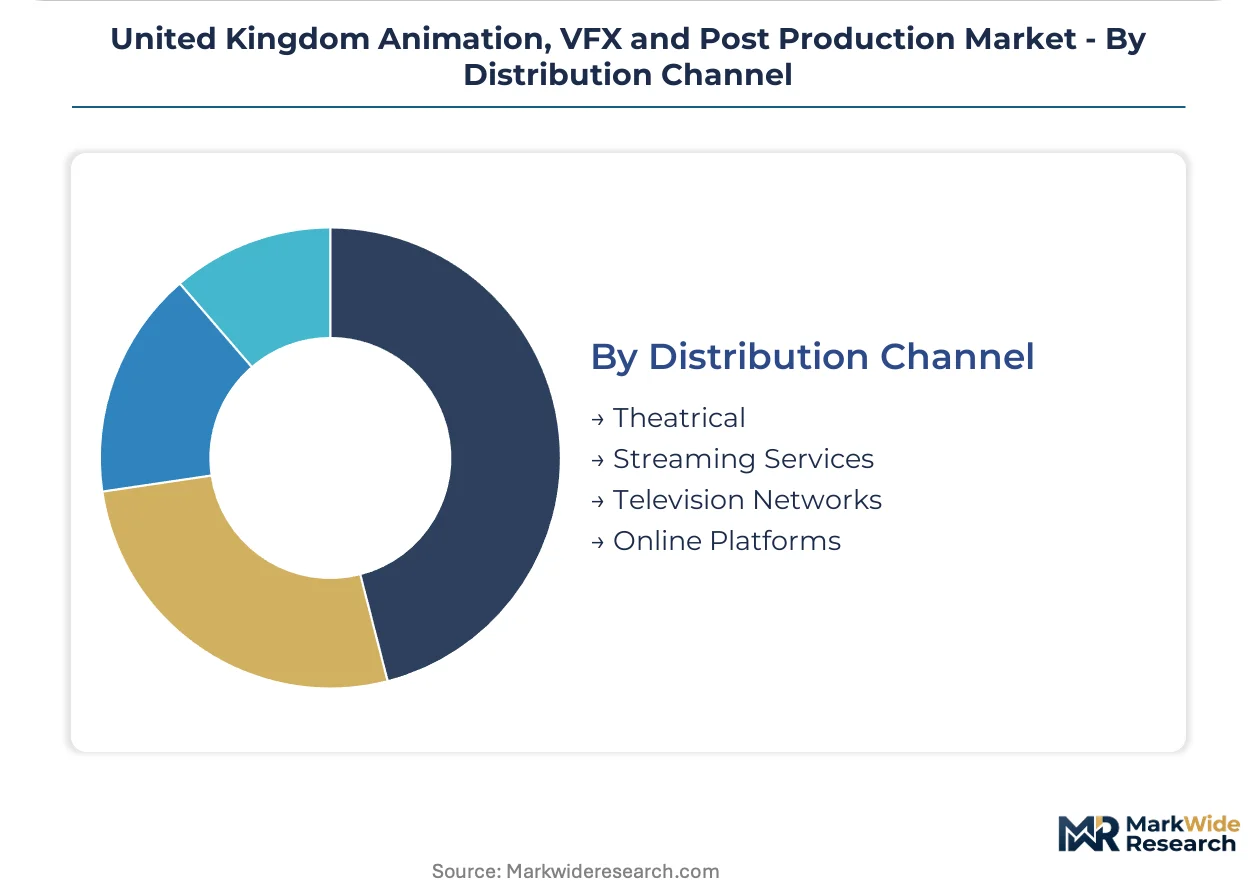
Platform content obligations under forthcoming Audio-Visual Media Services Directive revisions are reshaping commissioning patterns and facility service portfolios.
- Streaming Services:Platform-exclusive distribution with volume mandates and compressed delivery schedules. Domestic quota compliance requirements are redirecting investment toward qualifying productions.
- Theatrical:Cinema release windows demanding highest technical specifications and extended post-production timelines.
- Television Networks:Traditional broadcast distribution with established technical standards and regulatory compliance frameworks.
- Online Platforms:User-generated and short-form content distribution with lower production value thresholds.
Facility utilization sits with Streaming Services; regulatory-driven reconfiguration favors Television Networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's Soho cluster anchors the United Kingdom's animation, VFX and post-production infrastructure, housing the densest concentration of render farms and color-grading suites in Europe. Manchester's emerging media hub and Belfast's production facilities are absorbing displaced volume through regional incentive stacking.
London and the Southeast
Platform-exclusive commissioning from Netflix and Amazon is restructuring Soho facilities as embedded service units with dedicated pipelines. The British Film Institute's certification standards condition Creative Industries Tax Relief access, concentrating qualifying spend in capital-based houses. Pinewood Studios and Shepperton's virtual art departments deploy Unreal Engine 5 for in-camera VFX, collapsing post-production timelines.
North England
Manchester's MediaCityUK complex is pulling episodic series production northward through lower facility costs and regional tax incentives. The Greater Manchester Combined Authority's sector development programs support LED volume stage investments. Jellyfish Pictures and other facilities are expanding real-time pipeline capacity to capture streaming platform volume mandates.
Scotland
Edinburgh and Glasgow post-production houses are accessing Screen Scotland production funds for high-end television qualification. The Scottish Government's screen strategy targets VFX service expansion through skills pipeline investments. Outpost VFX maintains Glasgow operations to serve international co-productions with GDPR-compliant data governance.
Northern Ireland
Belfast facilities leverage UK-wide Creative Industries Tax Relief alongside Northern Ireland Screen incentives for competitive rate stacking. Titanic Quarter studios are positioning for virtual production convergence with LED volume infrastructure. DNEG and other houses utilize Belfast capacity for volume-series work with compressed delivery schedules.
Wales
Cardiff's post-production sector serves Welsh-language broadcast content and English-language streaming series through Creative Wales funding mechanisms. The Welsh Government's screen sector plan targets VFX capacity expansion beyond traditional broadcast post work. Wolf Studios Wales provides stage infrastructure integrated with Cardiff-based finishing facilities.
United Kingdom Animation, VFX and Post Production Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specialization depth and pipeline certification tiers. The vendor base organizes around theatrical feature houses with creature effects mastery, episodic specialists optimizing for turnaround velocity, and platform-embedded units with dedicated infrastructure. Three strategic archetypes dominate: integrated full-service studios spanning animation through final delivery, VFX boutiques with narrow simulation expertise, and virtual production convergents collapsing pre- and post-production boundaries. Competitive dynamics center on M&A consolidation for volume-series capacity and geographic expansion toward regional incentive stacks.
Among London-anchored full-service studios, Framestore Limited and DNEG exemplify the premium-tier archetype through multi-site UK capacity and high-end feature film positioning. MPC occupies a distinct position within the episodic streaming specialist tier, differentiating through volume-series mandates from platform-exclusive commissioning. Aardman Animations Ltd represents the animation-native archetype with proprietary production methodologies distinct from VFX-convergent competitors.
| Leading Market Players |
|---|
| Framestore Limited |
| Aardman Animations Ltd |
| Jellyfish Pictures |
| Blue Zoo Animation Studio |
| Cinesite |
| The Mill |
| DNEG |
| Outpost VFX |
| MPC |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between BFI-qualifying and non-qualifying productions splits UK animation, VFX and post-production pricing into parallel tracks, with tax-relief-eligible work commanding facility premiums while standard-rate projects face cost compression. This bifurcation concentrates high-margin pipeline investment in London's Soho cluster and Manchester's MediaCityUK, leaving commodity post work to compete on turnaround velocity rather than technical differentiation.
Pricing Analysis
Value-based pricing anchors on Creative Industries Tax Relief certification throughput, with facilities charging premium rates for BFI-compliant productions that secure fiscal incentives. Three-tier pricing stratifies across theatrical creature effects, episodic streaming volume, and advertising turnaround tiers. Cost compression in advertising post-production intensifies as cloud-native tools democratize color grading and editorial finishing. Studios with multi-year platform mandates exhibit lowest price sensitivity; independent filmmakers accessing tax relief face highest budget elasticity.
Supply Chain Analysis
Artist specialization scarcity in UK metropolitan centers constrains pipeline throughput regardless of render farm capacity expansion. Compute infrastructure draws from London, Manchester and Belfast facilities, while motion capture stages and LED volumes rest on Pinewood and Shepperton integration. Single-source vulnerability concentrates in London's Soho render farm cluster for time-critical theatrical delivery. Distribution runs through platform-embedded service partnerships displacing fragmented vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced simulation and creature effects expertise operates as the binding capacity constraint across UK VFX pipelines, sustaining pricing power for certified facilities despite cloud-enabled cost compression in commoditized post tiers.
For Market Incumbents: Deepen vertical integration into real-time pipeline infrastructure at Pinewood and Shepperton virtual art departments to defend against LED volume stage entrants. Capture Manchester and Belfast capacity through regional incentive stacking before competitor facility commitments solidify. For New Entrants and Emerging Players: Launch via carbon-accounted pipeline certification targeting streaming platform sustainability procurement mandates. Manchester's MediaCityUK offers the most penetrable geography given lower facility costs and Greater Manchester Combined Authority development support. For Investors and Strategic Acquirers: Re-rating potential sits with episodic streaming specialists given platform-exclusive volume mandate consolidation. Long-term viability favors facilities with integrated real-time and traditional post-production capabilities. Watch Audio-Visual Media Services Directive statutory instrument revisions as inflection triggers for domestic quota-compliant production investment.| Strategic Initiative | Industry Significance |
|---|---|
| LED Volume Stage Integration | Unreal Engine 5 deployment at Pinewood collapses pre- and post-production boundaries for qualifying features. |
| Carbon Pipeline Certification | Screen Sustainability Charter compliance differentiates facilities in Netflix and Amazon competitive tenders. |
| Regional Capacity Expansion | Manchester and Belfast facility investments capture displaced volume from London cost escalation. |
| Platform-Embedded Partnership | Multi-year integrated service agreements with Disney+ and Amazon secure dedicated pipeline utilization. |
| Real-Time Technical Artist Scaling | Unreal Engine and LED volume training programs address structural skill gaps constraining virtual production throughput. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this UK animation, VFX and post-production market analysis. Primary interviews with VFX facility executives, post-production house operations directors, streaming platform content procurement leads, and British Film Institute certification officers combined with British Film Institute expenditure reports, Ofcom broadcasting code filings, and Screen Scotland production fund disclosures. Bottom-up facility utilization modeling and top-down sector expenditure triangulation validated volume estimates.
Granularity-level modeling tracked service type, application format, client procurement scale, and distribution channel across the projection horizon. Segmentation dimensions included 3D animation compute intensity, visual effects specialization depth, episodic versus theatrical delivery protocols, and platform-exclusive versus independent financing structures. CAGRs derived from facility capacity expansion timelines, streaming commissioning pipeline visibility, and tax relief policy continuity assumptions. Real-time pipeline adoption curves and carbon-accounted workflow penetration served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for generative artificial intelligence in editorial and compositing would alter the outlook. Forecasts reflect assumptions regarding Creative Industries Tax Relief continuity, platform volume mandate stability, and LED volume stage cost curves. Material deviation in streaming subscriber growth, BFI certification criteria tightening, or GDPR enforcement intensity on cloud workflows warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
Camera Jib Market
Film and Cinema
Cinema Camera Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Drive-In Movie Theater Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
Movie Tickets Market