
 North America 3D Cinema Screen Market | 2026-2036
North America 3D Cinema Screen Market Size, Share, and Industry Trends Forecast 2026-2036
North America 3D Cinema Screen Market Insights
The United States is tilting toward laser-based screen infrastructure as exhibitors modernize aging multiplex footprints. IMAX Corporation leverages its proprietary dual-projector architecture to sustain premium positioning in major metropolitan venues. Harkness Screens anchors supply continuity through its North American coating and finishing facilities. RealD Inc. competes via lightweight screen metallization that reduces installation complexity for retrofits.
North America 3D cinema screens are specialized optical surfaces engineered with precision-gain coatings and polarization-preserving substrates to deliver stereoscopic depth perception at high ambient-light rejection ratios. These screens integrate with active-shutter or passive-polarized projection systems to render dual-image streams for immersive theatrical exhibition. Digital product-type installations dominate current revenue contribution due to widespread DCI-compliant projector compatibility, while Laser technology segments are capturing accelerated replacement demand as exhibitors retire mercury-arc lamp inventories. Theater end-user applications concentrate margin pools in premium large-format venues, whereas Theme Park installations are expanding fastest through destination entertainment complexes seeking differentiated guest experiences.
FCC equipment authorization requirements govern wireless active-shutter eyewear emissions, while EPA hazardous substance rules constrain mercury-containing lamp disposal and drive laser-transition timelines. State-level energy codes in California and New York impose efficiency thresholds on projection system power density that filter procurement specifications. Stakeholders must monitor regulatory pacing on laser safety classifications and emerging state building codes for auditorium illumination standards.
Market Dynamics
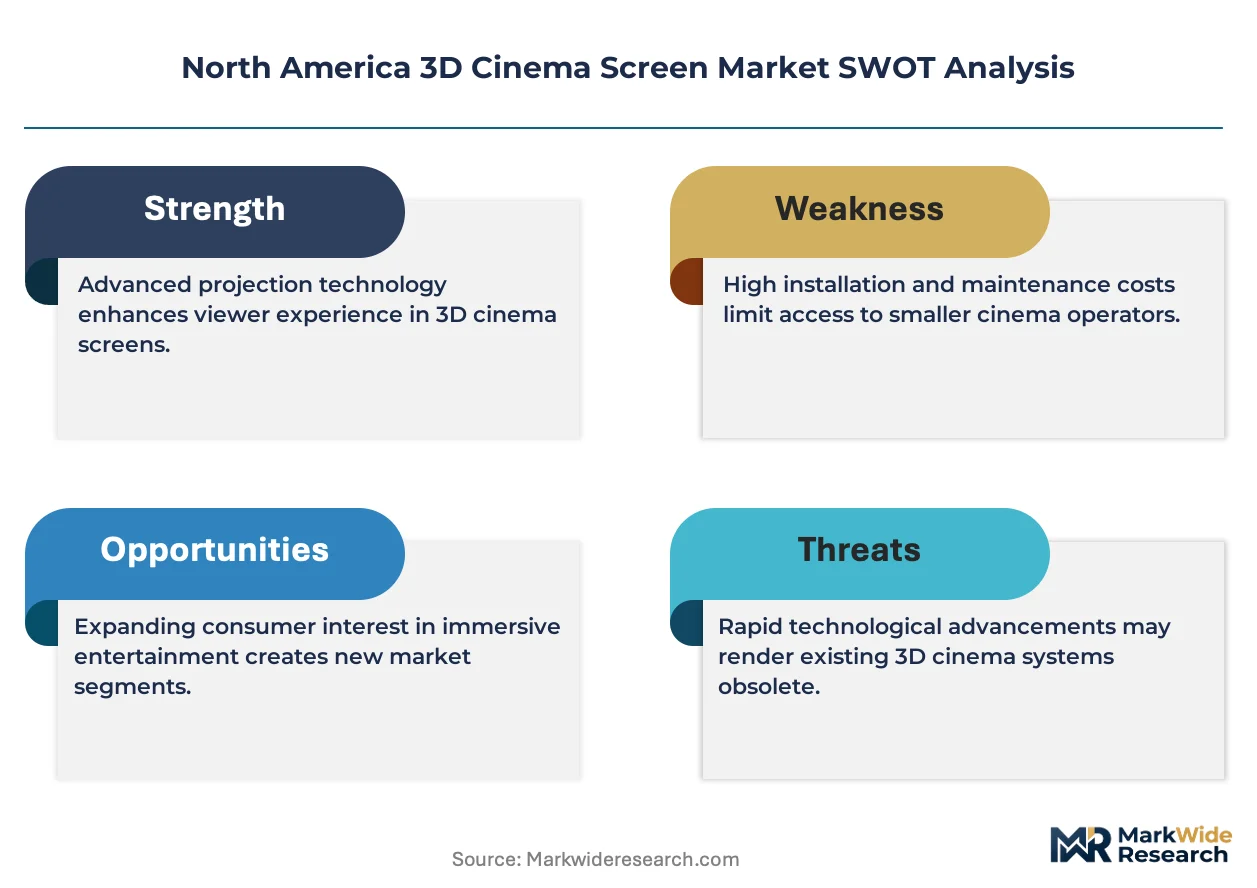
Laser projection retrofits are compressing replacement cycles across aging multiplex footprints as EPA mercury-disposal rules and California Title 24 energy codes force hardware turnover. Theater operators face simultaneous pressure to upgrade optical infrastructure while containing capital deployment per screen.
Growth Catalysts
- California Title 24 Efficiency Mandates:The state's building energy codes now impose strict power-density thresholds on projection systems, forcing exhibitors toward laser-based 3D screen installations that meet compliance windows.
- Theme Park Destination Complexes:Integrated entertainment venues in Florida and California are deploying premium large-format 3D screens as differentiated guest-experience anchors, expanding addressable demand beyond traditional theatrical.
- Mercury Lamp Phase-Out Schedules:EPA hazardous substance disposal regulations are accelerating retirement timelines for legacy xenon-arc projection inventories, creating forced-upgrade demand across regional theater circuits.
Market Restraints
- Silver-Coated Substrate Concentration:Precision metallized screen manufacturing concentrates among a limited supplier base in the Northeast and Midwest, creating single-source vulnerability for large-format deployments.
- Laser Safety Classification Friction:FDA and OSHA laser safety protocols impose extended certification timelines for high-output projection installations, stretching deployment schedules for premium venues.
- Home Streaming Substitution:Advanced consumer display technologies and spatial audio systems are compressing theatrical exclusivity windows, reducing urgency for mid-tier screen upgrades.
Strategic Opportunities
- Texas Metro Corridor Expansion:Dallas-Fort Worth and Houston multiplex renovation cycles lag coastal markets, creating underpenetrated demand for laser-3D retrofits as regional chains consolidate.
- Canadian Provincial Incentive Programs:Federal and provincial energy-efficiency rebates in Ontario and British Columbia are offsetting capex burdens for independent theater operators adopting compliant screen technologies.
- Active-Passive Polarization Convergence:Hybrid projection architectures that bridge RealD's lightweight metallization with dual-laser brightness are enabling single-inventory screen solutions across mixed-format venues.
Industry Challenges
- Optical Coating Technician Scarcity:Precision gain-coating application requires specialized skill sets concentrated among aging workforces in legacy manufacturing regions, constraining production scaling.
- DCI Compliance Integration Complexity:New screen deployments must synchronize with existing digital cinema server infrastructure, creating interoperability testing burdens that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America 3D Cinema Screen Market |
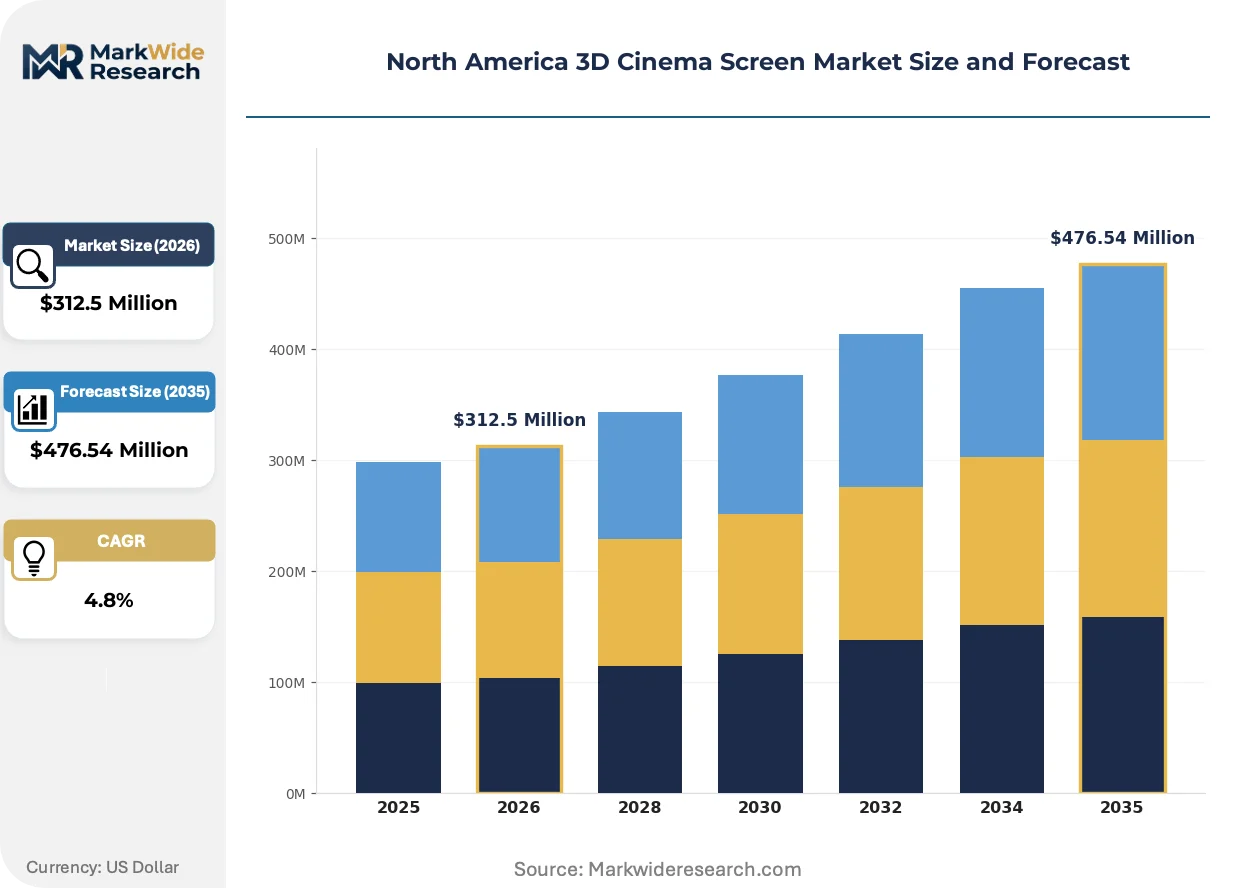
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stereoscopic, Anaglyph, Digital, IMAX Technology: DLP, LCD, LCoS, Laser End User: Theaters, Home Cinemas, Theme Parks, Museums Installation: Fixed, Mobile, Semi-permanent, Portable |
| Companies Covered | IMAX Corporation, Harkness Screens, Severtson Screens, Christie Digital Systems, Barco, Dolby Laboratories, Sony Corporation, Samsung Electronics, RealD Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America 3D Cinema Screen Market Trends and Innovations
Optical surface engineering and projection source technology are converging to redefine screen performance benchmarks. Three developments are compressing legacy upgrade timelines and reshaping procurement specifications.
Laser phosphor and RGB pure-laser illumination systems are migrating from xenon-arc lamp housings as exhibitors confront disposal liability and energy-code compliance. Major theater circuits in California and New York are prioritizing laser-3D bundles that reduce lamp-replacement labor and hazardous-material handling. The technology is migrating from premium large-format niches into mainstream multiplex renovations, collapsing the historical tiering between flagship and standard auditorium experiences.
EPA hazardous waste rules and state-level extended producer responsibility frameworks are tightening mercury-containing equipment retirement schedules. These regulations are forcing capital allocation toward laser projection and compatible high-gain screens earlier than typical depreciation cycles would dictate. Regional circuits in Texas and the Midwest are responding through phased retrofit programs that cluster compliance-driven upgrades with concession renovations to minimize downtime.
Exhibitor procurement is consolidating around turnkey screen-projection-eyewear packages rather than component sourcing. National theater chains are negotiating master service agreements with integrated suppliers, displacing the previous model of separate screen, projector, and glasses procurement. This pattern is most visible in California and Florida where destination-entertainment complexes demand single-accountability vendor relationships for large-format deployments.
North America 3D Cinema Screen Market Segmentation
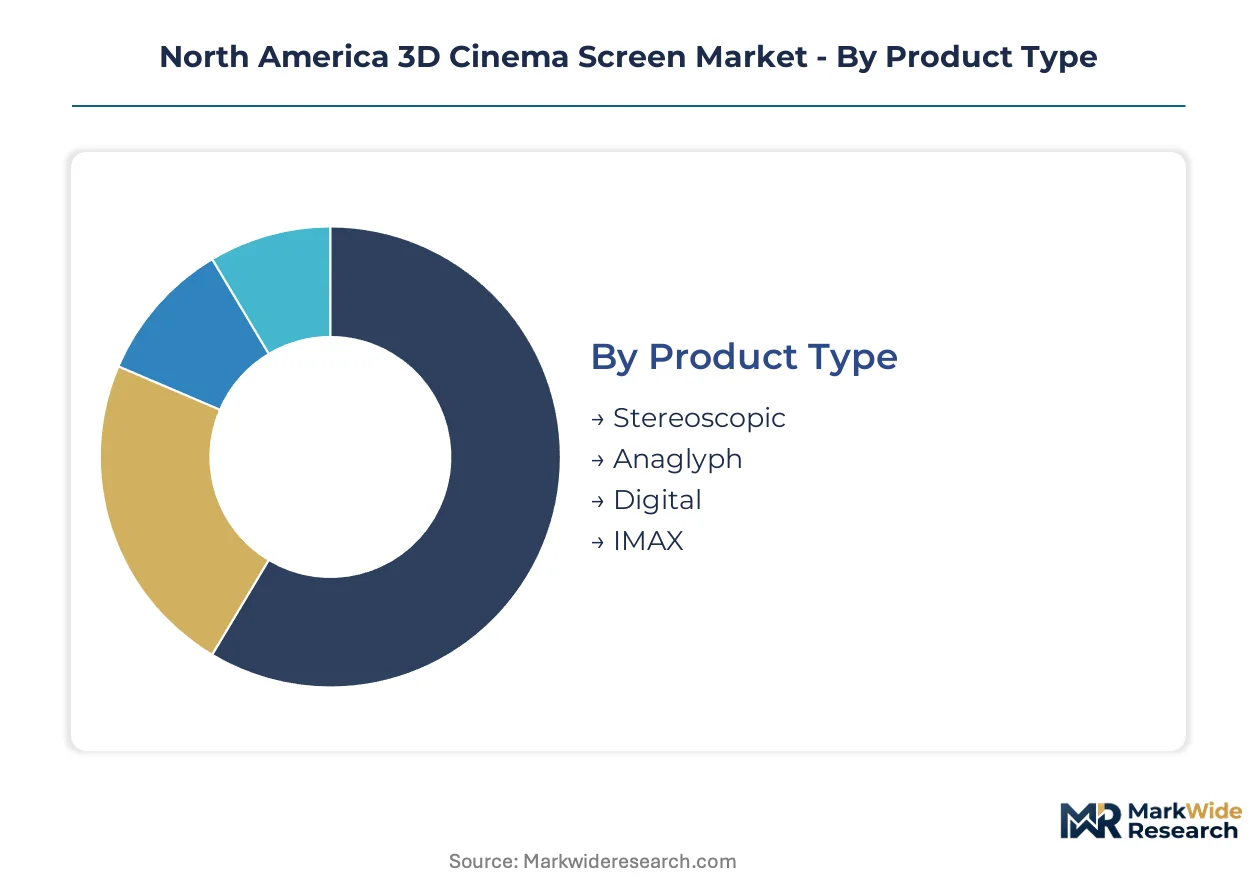
Segmentation in the North America 3D cinema screen market reveals divergent service intensity patterns across product tiers. Theater operators demand rapid-response coating restoration for premium large-format installations, while theme park deployments prioritize seasonal calibration contracts over emergency repair coverage.
Product Type:
After-sales service intensity varies sharply across optical architectures, with precision-gain coatings requiring specialized technician dispatch versus standardized digital surfaces.
- Stereoscopic:Dual-image polarization-preserving substrates engineered for active-shutter synchronization demand frequent optical alignment recalibration. California and Texas multiplex operators contract annual coating inspection protocols to maintain gain uniformity across aging installations.
- Digital:DCI-compliant surfaces dominate current procurement volumes through broad projector interoperability and streamlined commissioning workflows. Theater circuits in New York metro corridors prioritize digital bundles for rapid retrofit deployment under compressed Title 24 compliance windows.
- Anaglyph:Color-filtered legacy architecture persists in budget-conscious educational and museum installations requiring minimal technical support.
- IMAX:Proprietary large-format specifications tie operators to manufacturer-exclusive service agreements with limited third-party maintenance options.
By volume, Digital leads. By growth pace, Stereoscopic is climbing the fastest as exhibitors retrofit polarization infrastructure for laser brightness compatibility.
Technology:
Cost tier stratification separates premium laser illumination from legacy lamp-based projection, with capital intensity dictating service contract structures and replacement part availability.
- Laser:RGB pure-laser and phosphor-illuminated systems command premium installation costs but eliminate lamp-replacement labor and hazardous-material handling liabilities. EPA mercury-disposal regulations and California energy codes are compressing adoption timelines across regional theater circuits.
- DLP:Texas Instruments micromirror architecture anchors mainstream multiplex deployments through proven reliability and extensive technician certification networks. Canadian provincial rebate programs in Ontario and British Columbia are offsetting capex burdens for independent operators selecting DLP-laser bundles.
- LCD:Liquid-crystal polarization modulation serves secondary auditorium tiers and mobile screening applications with lower optical throughput requirements.
- LCoS:Liquid crystal on silicon technology occupies niche positioning for ultra-high-resolution scientific visualization and specialized museum deployments.
By installed base, DLP holds the largest share. By expansion trajectory, Laser is gaining share fastest as regulatory deadlines force hardware turnover.
End User:
Application-specific performance thresholds create divergent procurement specifications, with commercial theatrical demanding sustained brightness uniformity versus destination entertainment prioritizing rapid format switching.
- Theaters:Commercial exhibition circuits in California, Texas, and New York metro corridors drive replacement demand through multiplex renovation cycles and energy-code compliance mandates. Premium large-format venues specify high-gain silver-coated substrates for maximum light efficiency in 3D presentation modes.
- Theme Parks:Integrated destination complexes in Florida and California deploy specialized large-format screens as differentiated guest-experience anchors with accelerated depreciation schedules. Seasonal operating patterns demand modular installation architectures enabling rapid winterization and recommissioning.
- Museums:Cultural institutions prioritize archival-grade color accuracy and extended operational longevity over peak brightness metrics.
- Home Cinemas:Residential installations represent marginal volume concentrated in ultra-high-net-worth segments with dedicated screening room infrastructure.
By revenue concentration, Theaters dominate. By expansion velocity, Theme Parks are expanding most quickly through destination entertainment complex development.
Installation:
Volume and mobility requirements segment procurement between permanent auditorium infrastructure and flexible deployment architectures serving non-traditional venues.
- Fixed:Permanent wall-mounted and truss-suspended installations anchor commercial theatrical infrastructure with precision-engineered tensioning systems for optical surface stability. Texas and Midwest regional circuits are clustering fixed-screen upgrades with concession renovations to minimize multiplex downtime.
- Semi-permanent:Modular framing systems enable seasonal deployment in theme park entertainment complexes and outdoor festival circuits requiring weather-resistant enclosure integration.
- Mobile:Rapid-deployment packages serve pop-up cinema circuits and corporate event programming with trade-offs in optical gain consistency.
- Portable:Collapsible front-projection surfaces address educational and community screening applications with minimal installation labor requirements.
By deployment count, Fixed installations lead. By flexibility premium, Semi-permanent is seeing the steepest demand climb as entertainment venues seek format adaptability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA hazardous substance rules and California Title 24 energy codes are compressing replacement cycles across the continent. Theater circuits from Vancouver to Mexico City face synchronized compliance windows that favor laser-3D bundles over legacy lamp infrastructure.
United States
California multiplex operators confront Title 24 power-density thresholds that disqualify xenon-arc projection from new installations. Texas metro corridors including Dallas-Fort Worth and Houston lag coastal renovation cycles, creating underpenetrated demand for laser retrofits as regional chains consolidate. Florida destination-entertainment complexes in Orlando and Miami deploy premium large-format screens as differentiated guest-experience anchors.
Canada
Ontario and British Columbia provincial rebate programs offset capex burdens for independent theater operators adopting DCI-compliant laser bundles. Toronto's exhibition density concentrates procurement volumes for precision-gain screen coatings. Montreal's cultural venue infrastructure sustains demand for archival-grade polarization-preserving substrates in museum and institutional applications.
Mexico
Mexico City metro corridor multiplex renovation accelerates as national chains modernize aging auditoriums for competitive positioning against streaming platforms. Federal energy-efficiency guidelines for commercial buildings filter procurement specifications toward lower power-density projection systems. Guadalajara's emerging middle-class entertainment consumption supports new-build cinema complexes specifying turnkey laser-3D packages.
North America 3D Cinema Screen Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base separates between proprietary large-format specialists with locked-in service agreements and broad-line projection integrators serving mainstream multiplex renovation cycles. Two strategic archetypes dominate: dual-projector architecture providers sustaining premium positioning through exclusive screen specifications, and lightweight metallization specialists reducing installation complexity for retrofit applications. Competitive moves center on master service agreement consolidation with national theater chains and laser-illumination bundle packaging that collapses component procurement into single-accountability relationships.
Within the premium large-format tier, IMAX Corporation exemplifies proprietary ecosystem control through integrated projection-screen-venue specifications that limit third-party maintenance options. Harkness Screens anchors supply continuity for precision-gain coatings through its North American manufacturing footprint. RealD Inc. occupies a position in lightweight screen metallization that reduces field installation labor for polarization-based 3D retrofits.
| Leading Market Players |
|---|
| IMAX Corporation |
| Harkness Screens |
| Severtson Screens |
| Christie Digital Systems |
| Barco |
| Dolby Laboratories |
| Sony Corporation |
| Samsung Electronics |
| RealD Inc. |
| Others |
Pricing and Supply Chain Analysis
Los Angeles-Long Beach port congestion surcharges ripple through precision-gain screen substrate shipments, amplifying cost spreads between Northeast coating facilities and Texas multiplex operators while compressing margins for mid-tier metallization suppliers serving retrofit markets.
Pricing Analysis
Coastal-to-interior price spreads exceed fifteen percent for silver-coated substrates as California Title 24 compliance premiums concentrate procurement power among Pacific theater circuits. Three-tier pricing structure across premium large-format, standard multiplex, and economy educational tiers separates IMAX-exclusive bundles from RealD retrofit packages and basic digital surfaces. Cost compression in mid-tier metallization is intensifying because EPA mercury-disposal liability shifts capex toward laser-compatible screens faster than depreciation cycles allow. Regional chains in Texas and the Midwest exhibit highest price sensitivity; premium venue operators in Florida and California show least.
Supply Chain Analysis
Contract manufacturing for precision-gain coatings concentrates among Harkness Screens' Maryland finishing facilities and Severtson Screens' Arizona production plants, with limited qualified secondary capacity. Geographic supply concentration centers on United States, Canada, and Mexico for North American theater demand, though specialty silver substrates draw from European refiners. Raw material dependencies rest on silver bullion contracts, PET substrate films, and polarization-preserving adhesive formulations. Single-source vulnerability pervades large-format coating application equipment. Distribution runs through manufacturer-direct channels for national chains and regional AV integrators for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as national theater chains negotiate master service agreements, displacing fragmented component procurement and squeezing standalone screen suppliers.
For Market Incumbents: Harden exclusive service agreement penetration with premium large-format venues before laser-illumination bundles commoditize screen differentiation. Deepen backward integration into silver substrate refining to offset precious metal volatility. Secure EPA-compliant coating technician certification pipelines to constrain competitor scaling. For New Entrants and Emerging Players: Pursue semi-permanent modular screen architectures for Florida and California theme park seasonal cycles, where format flexibility commands premium pricing. Target Texas metro corridor retrofits as regional chains consolidate and lag coastal compliance timelines. Lead with turnkey installation labor reduction as the primary go-to-market angle. For Investors and Strategic Acquirers: Optical coating specialists with captive North American manufacturing footprints present acquisition profiles insulated from freight cost volatility and tariff exposure. Long-term viability hinges on laser-illumination transition completion across the analysis window. Watch EPA enforcement intensity on mercury lamp disposal as the inflection signal for forced-upgrade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Projection Bundle Packaging | Turnkey procurement collapses component sourcing friction for Title 24 compliance deadlines. |
| Coating Technician Certification Pipeline | Skill scarcity constrains competitor production scaling across precision-gain applications. |
| Theme Park Seasonal Service Contracts | Modular maintenance agreements capture Florida and California destination-entertainment expansion. |
| Silver Substrate Backward Integration | Captive refining hedges precious metal cost volatility for large-format deployments. |
| Master Service Agreement Consolidation | Single-accountability relationships displace fragmented procurement among national chains. |
Research Methodology
Desk research of SEC filings from exhibition circuits, EPA hazardous waste enforcement records, and California Energy Commission compliance databases preceded structured interviews with theater operations executives, projection technology procurement managers, and optical coating manufacturing engineers. Primary fieldwork encompassed multiplex renovation site assessments and theme park AV integration project reviews. Secondary validation drew from DCI specification documents, state building code filings, and industry trade association technical standards. Bottom-up screen deployment counts triangulated against top-down market value estimates.
Assumptions held laser-illumination transition timelines and EPA enforcement intensity constant across the projection horizon, while varying multiplex renovation cycle pacing and theme park development velocity. Segmentation modeling spanned product type, technology, end user, and installation mobility dimensions alongside regional regulatory cluster differentiation. CAGRs derived from regression analysis of historical replacement cycles adjusted for compliance-driven compression. Forecast inputs incorporated silver price volatility bands and coating technician workforce aging curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by projection manufacturers would shift outcomes toward bundled pricing erosion. Quarterly review of EPA mercury-disposal enforcement actions and California Title 24 amendment proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Drive-In Movie Theater Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Movie Tickets Market
Film and Cinema
Camera Jib Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
Cinema Camera Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Digital Cinema Projectors Market