
 Movie Tickets Market | 2026-2036
Movie Tickets Market Size, Share, and Industry Trends Forecast 2026-2036
Movie Tickets Market Analysis
Premium-format screen upgrades are rotating the Movie Tickets Market toward higher-margin transactions. AMC Theatres leverages its scale to anchor IMAX and Dolby Cinema deployments across North American metro clusters. PVR INOX dominates multiplex expansion in India through aggressive screen additions in underserved urban corridors. Cinemark Holdings Inc competes on regional density, sustaining operational efficiency in mid-size US markets where competitors have retrenched.
A movie ticket constitutes a time-bound admission credential granting access to a theatrical screening, typically encoded with seat assignment, showtime, and pricing tier data for inventory control and revenue recognition. The primary commercial purpose centers on yield management for fixed-capacity auditorium assets, where perishable inventory demands dynamic pricing and demand forecasting precision. Online and mobile app purchase channels now lead transaction volume, capturing structural margin pools previously absorbed by box-office staffing and physical infrastructure. IMAX and 3D ticket types command premium pricing multiples, while standard-format matinee showings represent mature, volume-dependent segments with thinner per-unit economics.
The US Federal Trade Commission monitors online ticketing platform consolidation and fee transparency, while India's Ministry of Information and Broadcasting oversees cinema pricing guidelines under state-level entertainment tax frameworks. China's National Radio and Television Administration regulates foreign film import quotas and release windows, directly shaping theatrical demand cycles. Stakeholders must monitor how streaming window compression and regulatory adjustments to revenue-sharing models reshape investment thresholds for new screen construction.
Market Dynamics
Streaming window compression is forcing theatrical exhibitors to collapse release cycles and front-load marketing spend, transforming how distributors monetize fixed-capacity auditorium inventory before digital availability erodes exclusivity premiums.
Growth Catalysts
- PLI scheme incentives:India's Production Linked Incentive scheme subsidizes domestic content production, expanding theatrical release slates and driving ticket volume in tier-two urban corridors.
- 4DX motion seating:Immersive motion and environmental effects technology commands 40-60% ticket premiums, attracting experiential-seeking demographics back to physical venues.
- Mobile wallet penetration:Unified Payments Interface infrastructure in India and Alipay/WeChat Pay ecosystems in China eliminate friction from discovery-to-purchase journeys, accelerating conversion rates.
Market Restraints
- Real estate cost escalation:Prime urban retail space rents in Mumbai, Shanghai, and New York compress multiplex operating margins and deter greenfield screen additions.
- Single-supplier projector dependency:Laser projection technology concentrates with limited certified vendors, creating procurement bottlenecks for premium-format auditorium upgrades.
- Import quota rigidities:China's National Radio and Television Administration foreign film release caps constrain programming diversity and revenue predictability for theatrical operators.
Strategic Opportunities
- Subscription membership models:AMC Stubs A-List and comparable programs lock in recurring revenue streams and flatten demand cyclicality across release calendars.
- Event cinema programming:Live opera, sports, and gaming tournament broadcasts repurpose underutilized weekday matinee slots with higher per-seat yields than standard releases.
- Dynamic pricing algorithms:Yield management software adoption enables real-time demand-responsive seat pricing, capturing consumer surplus previously left unrealized.
Industry Challenges
- Projectionist technician scarcity:Laser and LED system maintenance requires specialized certification programs that vocational pipelines have not scaled to match deployment timelines.
- Legacy point-of-sale fragmentation:Ticketing platform consolidation creates integration complexity for regional chains operating heterogeneous software estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Movie Tickets Market |
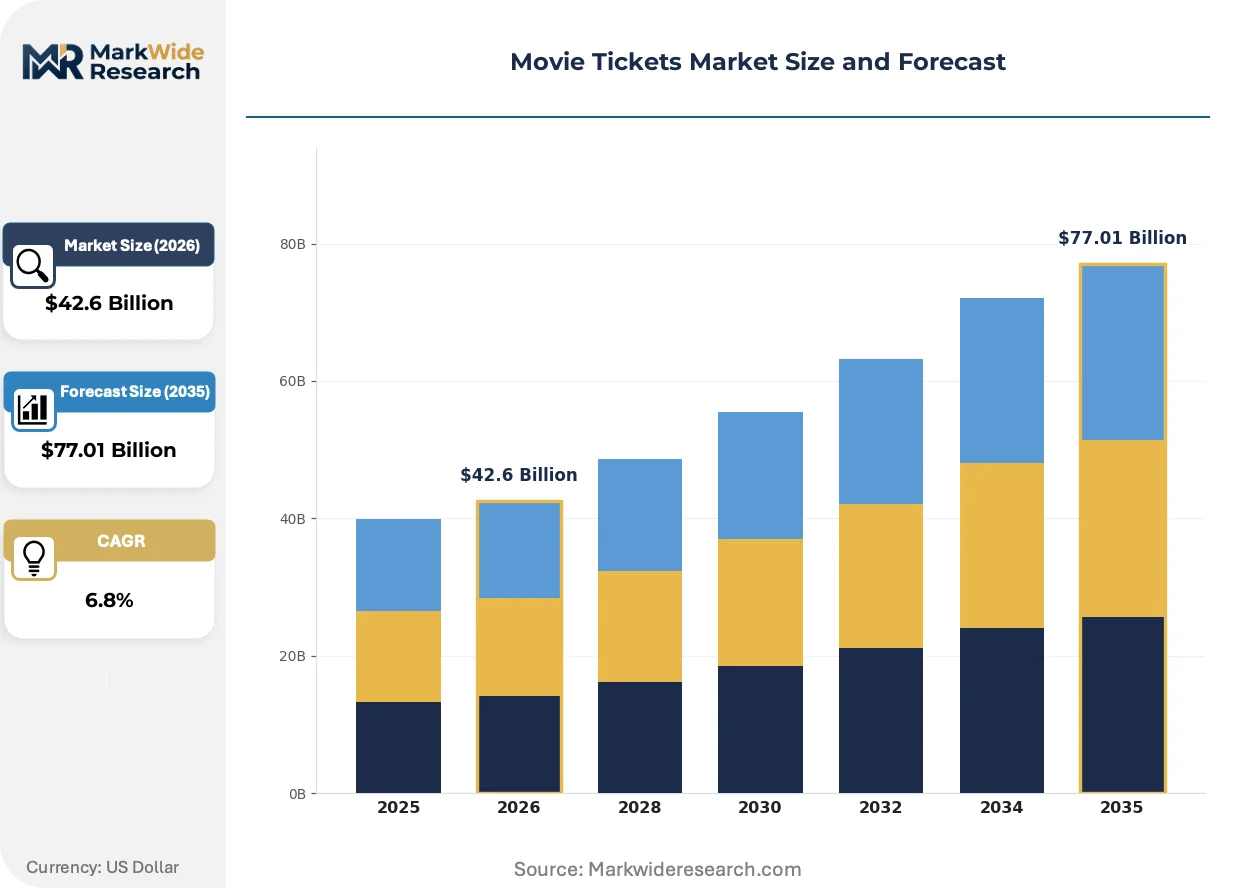
| Market Size in 2026 | $42.6 Billion |
| Market Size in 2035 | $77.01 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Purchase Channel: Online, Mobile App, Kiosk, Box Office Ticket Type: Standard, VIP, 3D, IMAX Audience Segment: Families, Couples, Groups, Singles Show Timing: Matinee, Evening, Late Night, Weekends |
| Companies Covered | Cineplex Inc, VOX Cinemas, Fandango, PVR INOX, INOX Leisure, AMC Theatres, BookMyShow, Regal Cinemas, Cinemark Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Movie Tickets Market Emerging Trajectories
Digital ticketing infrastructure is collapsing the distance between content marketing and transaction completion, while premium format differentiation and regulatory pressure on fee transparency reshape competitive positioning.
RFID-enabled smart wristbands are miniaturizing access control and concession payment into wearable form factors. Younger demographics in South Korea and the UAE adopt these devices at accelerated rates, compressing queue times and enabling behavioral data capture that feeds personalized retargeting campaigns.
India's Ministry of Information and Broadcasting periodically revises entertainment tax ceilings and service charge disclosure mandates. These adjustments force ticketing platforms to unbundle fee structures in consumer-facing interfaces, pressuring revenue models that relied on opaque add-on pricing.
Social discovery platforms now originate a growing share of purchase intent, with TikTok and Instagram Reels displacing traditional trailer placement as primary awareness drivers. Studios redirect promotional spend toward influencer seeding and algorithmic content distribution, particularly for genre releases targeting 18-34 demographics in Brazil and Southeast Asia.
Movie Tickets Market Segmentation
Segmentation in the Movie Tickets Market determines yield management precision and capital allocation across fixed-capacity auditorium assets. Purchase channel preferences and ticket type premiums directly shape revenue per seat and operational infrastructure requirements.
Purchase Channel:
Mobile and online platforms face intensifying substitute pressure from streaming services that eliminate physical venue dependency entirely.
- Online:Web-based booking portals aggregate showtime data across multiplex networks, enabling comparison shopping. Demand concentrates in tier-two Indian cities where desktop access precedes mobile wallet adoption, though conversion friction from payment gateway redirects erodes completion rates.
- Mobile App:Native applications embed loyalty programs and push notifications for flash pricing. PVR INOX and AMC Stubs capture the highest engagement in India and North American metro clusters respectively, where unified payment interfaces compress discovery-to-purchase latency.
- Kiosk:Self-service terminals reduce box-office staffing costs for regional US chains. Demand persists in suburban markets where older demographics resist app downloads.
- Box Office:Counter transactions retain relevance for impulse purchases and cash-preferred segments. Operational overhead limits deployment in premium urban locations.
Mobile App retains volume leadership; Online holds the steepest expansion trajectory.
Ticket Type:
Cost tier stratification separates capital-intensive premium deployments from volume-dependent standard operations.
- IMAX:Large-format laser projection systems deliver expanded aspect ratios and enhanced luminosity. Demand concentrates in Shanghai, Mumbai, and Dubai where experiential-seeking demographics absorb 40-60% ticket premiums.
- 3D:Polarized and active-shutter systems add depth perception to blockbuster releases. China maintains the densest screen base, though audience fatigue in mature markets compresses utilization rates.
- VIP:Reclining seating, in-auditorium dining, and reserved parking command elevated pricing. PVR INOX and Cinemark deploy these configurations in affluent suburban corridors.
- Standard:Conventional digital projection serves price-sensitive volume segments. Matinee pricing and promotional bundles sustain occupancy during off-peak windows.
Standard retains volume leadership; IMAX holds the steepest expansion curve.
Audience Segment:
Application-based clustering determines marketing spend allocation and programming mix across release calendars.
- Families:Multi-generational outings concentrate on animated features and franchise installments. Weekend matinee slots in Indian multiplexes capture this demand.
- Couples:Date-night occasions prioritize evening showings in premium formats. Valentine's Day and year-end holiday windows concentrate revenue.
- Groups:Corporate bookings and celebration events repurpose underutilized weekday slots. Event cinema programming targets this segment.
- Singles:Solo attendance patterns favor late-night and niche programming. Streaming substitution pressure weighs heaviest here.
Families retain volume leadership; Singles are gaining share fastest.
Show Timing:
Volume distribution across temporal slots shapes staffing models and concession throughput planning.
- Evening:Post-work showings capture peak demand density. Premium pricing and full concession attachment sustain margin contribution.
- Weekends:Friday-through-Sunday windows absorb franchise release concentration. Auditorium turnover limits capture capacity.
- Matinee:Discounted daytime pricing targets price-sensitive and retired demographics. Lower concession spend per cap pressures profitability.
- Late Night:Post-10pm screenings serve young adult and niche audiences. Regulatory curfews in Indian states constrain operational flexibility.
Evening retains volume leadership; Late Night holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for theatrical content and exhibition technology flow asymmetrically across major economies, with equipment and intellectual property moving from developed markets toward emerging multiplex corridors while local-language production capabilities strengthen in recipient regions.
United States
Subscription membership models and premium-format screen deployments sustain per-capita spending leadership. The FTC monitors online ticketing platform consolidation and fee transparency mandates. Los Angeles anchors studio distribution headquarters while AMC Theatres concentrates IMAX and Dolby Cinema deployments across metro clusters.
China
Mobile wallet ecosystems and tier-two city multiplex penetration drive volume expansion despite import quota constraints. The National Radio and Television Administration regulates foreign film release windows and import caps. Shanghai hosts the densest IMAX screen base globally with experiential-seeking demographics absorbing substantial ticket premiums.
India
Production Linked Incentive scheme subsidies expand domestic content slates while UPI infrastructure eliminates purchase friction. The Ministry of Information and Broadcasting oversees entertainment tax ceilings and service charge disclosure mandates. Mumbai and Delhi-NCR corridors concentrate PVR INOX multiplex expansion in underserved urban pockets.
South Korea
RFID-enabled smart wristbands and immersive format adoption accelerate among younger demographics seeking experiential differentiation. The country's national broadcasting regulator maintains content classification frameworks. Seoul anchors technology pilot programs that compress queue times and enable behavioral data capture for personalized retargeting.
United Arab Emirates
Luxury VIP configurations and event cinema programming target affluent expatriate and tourist segments with elevated per-seat yields. The national media council oversees content licensing and theatrical release frameworks. Dubai concentrates VOX Cinemas premium deployments across retail-integrated entertainment destinations.
Movie Tickets Market Vendor Landscape
Listed leaders compete with private specialists across capital access and operational agility dimensions, producing a tiered structure where scale-driven multiplex operators coexist with regional chains and pure-play ticketing platforms. Publicly traded exhibitors leverage balance sheet capacity for premium-format capex cycles while private specialists optimize yield management software and local programming relationships. Three archetypes dominate: integrated exhibition circuits, pure-play ticketing intermediaries, and hybrid entertainment-retail operators. Competitive intensity centers on auditorium upgrade cycles and dynamic pricing algorithm deployment.
Within the integrated exhibition tier, AMC Theatres and Cinemark Holdings Inc represent scale-driven archetypes with North American density advantages, while PVR INOX anchors emerging-market multiplex expansion. Among ticketing intermediaries, BookMyShow occupies a position exemplifying mobile-first platform specialization, and Fandango sits within the studio-affiliated aggregator archetype. These named entities illustrate strategic positioning without exhausting the competitive set.
| Leading Market Players |
|---|
| Cineplex Inc |
| VOX Cinemas |
| Fandango |
| PVR INOX |
| INOX Leisure |
| AMC Theatres |
| BookMyShow |
| Regal Cinemas |
| Cinemark Holdings Inc |
| Others |
Supply Flow & Price Mechanics
Laser projection technology substitution for legacy xenon systems simultaneously concentrates supplier power in the United States and Germany while compressing upgrade economics for exhibitors negotiating auditorium refresh cycles.
Pricing Analysis
Industrial OEM buyers anchor transactional per-ticket pricing stratified across premium, standard, and economy tiers. Price differentiation hinges on format certification tier—IMAX and Dolby Cinema deployments command substantial premiums over standard digital projection—and geographic venue clustering in affluent suburban corridors. Cost compression in standard-format matinee slots intensifies because streaming window compression erodes exclusivity premiums for non-event releases. Family segments demonstrate highest price sensitivity, while experiential-seeking demographics in Dubai and Shanghai absorb premium multiples with minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of projection equipment and spare parts dominates inventory posture given single-source vendor concentration and extended lead times for laser system certification. Supply concentrates in the United States, Germany, and Japan for precision optical components and laser light source modules. Raw material dependencies include rare-earth phosphors, specialized glass substrates, and precision-machined heat dissipation housings. Tariff exposure on Chinese-manufactured electronic subassemblies creates procurement vulnerability for North American exhibitors. Distribution runs through manufacturer-direct channels for premium-format deployments and regional integrators for standard auditorium refreshes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Streaming service substitution threatens theatrical exclusivity windows, forcing incumbents to collapse release cycles and front-load experiential differentiation before digital availability erodes ticket premiums.
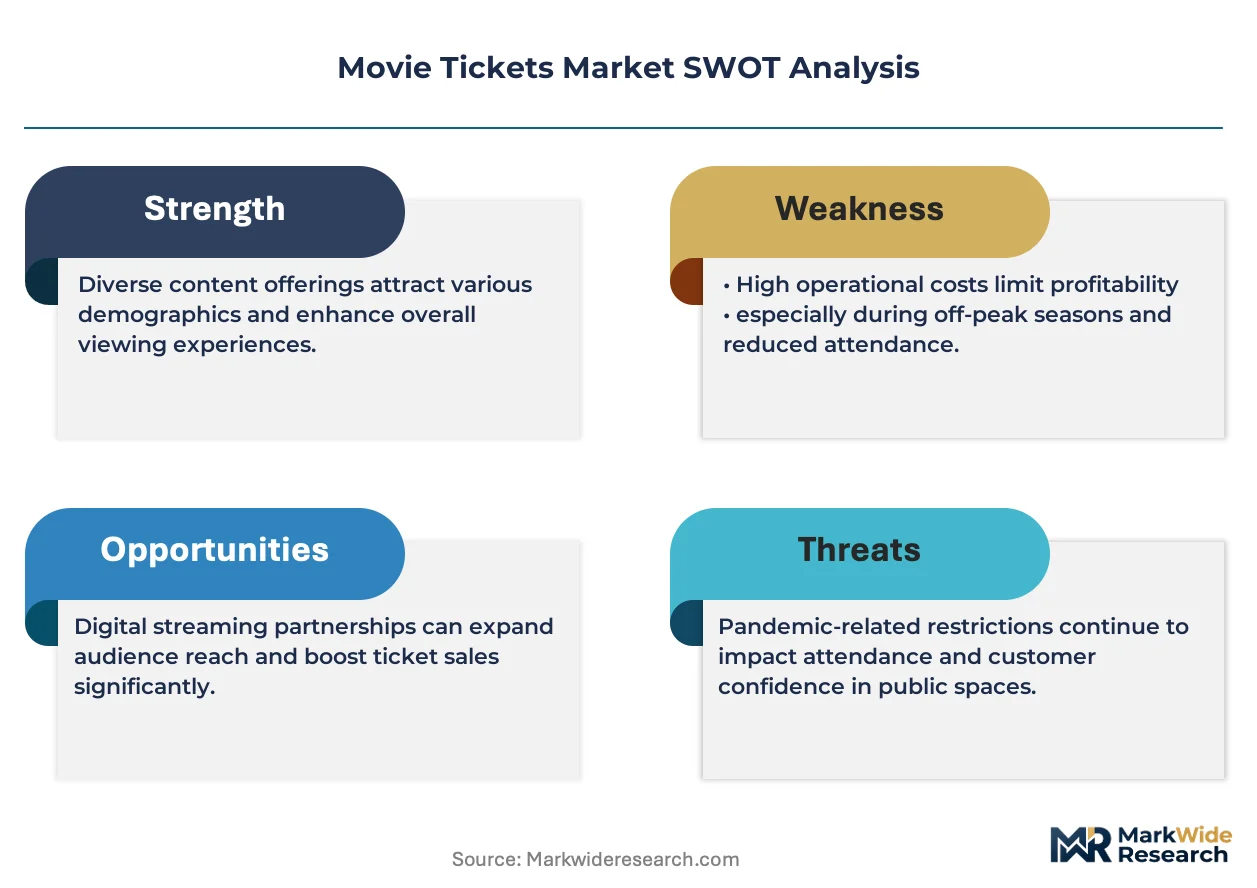
For Market Incumbents: Secure premium-format screen deployments in tier-two Indian and Chinese urban corridors where multiplex penetration deepens against limited streaming infrastructure. Lock in subscription membership recurring revenue through AMC Stubs A-List and comparable programs that flatten demand cyclicality. Vertical integration into dynamic pricing algorithm development captures consumer surplus previously left unrealized. For New Entrants and Emerging Players: Event cinema programming gaps in weekday matinee slots offer white-space capture for live opera, sports, and gaming tournament broadcasts with higher per-seat yields than standard releases. Target corporate group bookings and celebration events in underserved Middle Eastern and Southeast Asian markets. Deploy RFID-enabled smart wristband pilots in South Korea and UAE to compress queue times and enable behavioral data capture for personalized retargeting. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional chains operating heterogeneous software estates that face consolidation pressure from ticketing platform integration complexity. Long-term viability hinges on yield management software adoption and premium-format capex discipline. Watch for inflection when regulatory fee transparency mandates force unbundling of previously opaque add-on pricing structures.| Strategic Initiative | Industry Significance |
|---|---|
| Premium Format Deployment | IMAX and Dolby Cinema installations in tier-two Indian cities capture experiential-seeking demographics with elevated ticket yields. |
| Subscription Membership Launch | AMC Stubs A-List and comparable programs lock recurring revenue streams and flatten demand cyclicality across release calendars. |
| Dynamic Pricing Algorithm Adoption | Real-time demand-responsive seat pricing captures consumer surplus previously left unrealized in fixed-capacity auditoriums. |
| Event Cinema Programming Expansion | Live opera and sports broadcasts repurpose underutilized weekday slots with higher per-seat yields than standard releases. |
| Mobile Wallet Integration | UPI infrastructure in India and Alipay ecosystems in China eliminate friction from discovery-to-purchase journeys. |
Methodological Framework
A standing panel of multiplex operations directors, ticketing platform product managers, studio distribution executives, and cinema equipment procurement leads provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings of listed exhibitors, National Association of Theatre Owners industry statistics, China's National Radio and Television Administration release window disclosures, and India's Ministry of Information and Broadcasting entertainment tax circulars. Bottom-up venue count and yield data triangulated against top-down box office revenue aggregates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include purchase channel, ticket type, audience segment, and show timing, with additional granularity on premium-format penetration rates and subscription membership adoption curves. CAGRs were derived from trend extrapolation of historical transaction volumes adjusted for regulatory window adjustments and technology substitution patterns. Forecast inputs incorporated mobile wallet penetration trajectories and tier-two city multiplex construction pipelines.
Underlying assumptions cover theatrical window exclusivity duration, laser projection upgrade adoption curves, and streaming service pricing aggression, with deviation risk concentrated in regulatory import quota adjustments and real estate cost escalation in prime urban retail corridors. Revision becomes warranted when streaming window compression accelerates beyond modeled thresholds or when entertainment tax ceiling adjustments materially alter net ticket economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
Camera Jib Market
Film and Cinema
Cinema Camera Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
Film Dubbing Market