
 Camera Jib Market | 2026-2036
Camera Jib Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Jib Market Insights
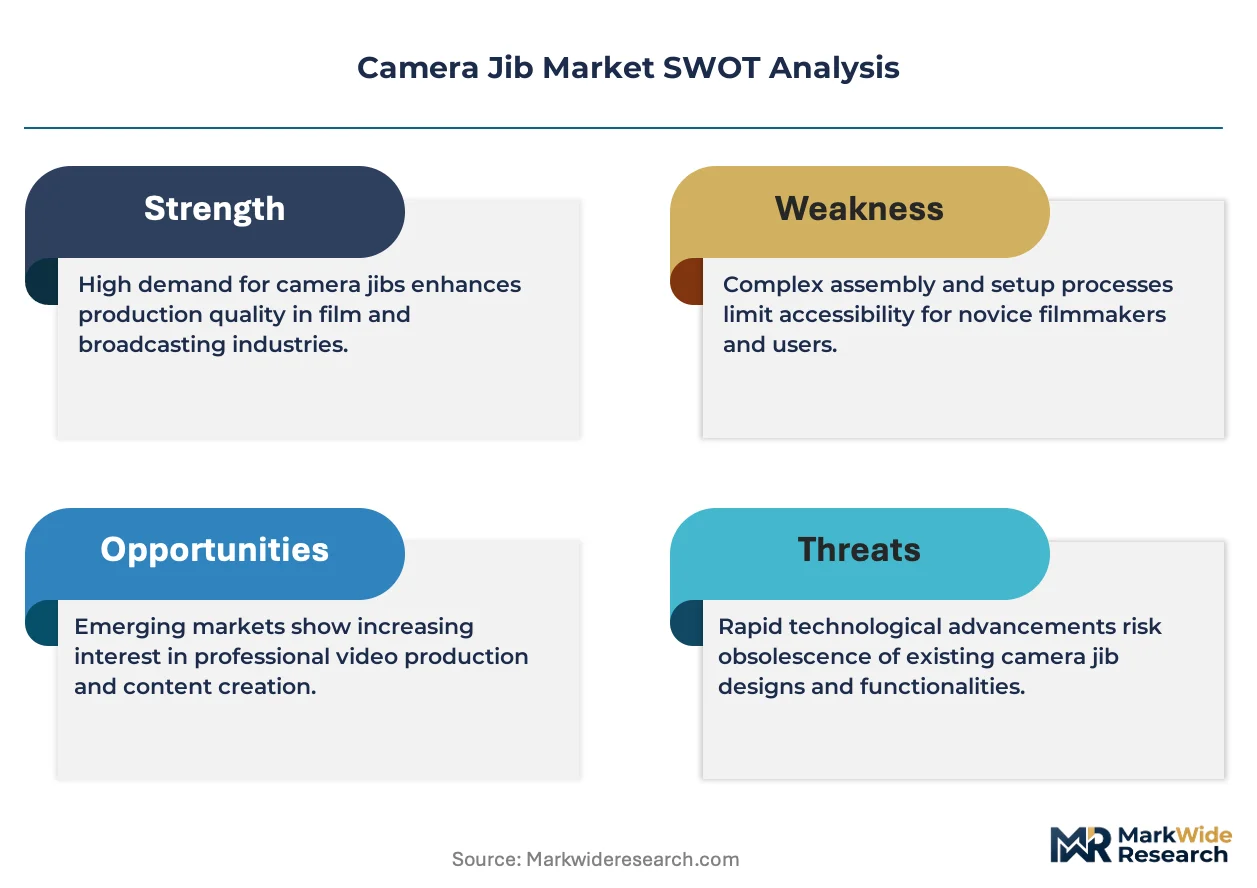
The camera jib equipment market is decoupling into two distinct tiers: precision-engineered carbon fiber systems commanding premium positioning versus aluminum commodity arms serving budget-conscious operators. Kessler Crane leverages its vertically integrated manufacturing in Indiana to control quality across payload categories from 10 lbs to over 50 lbs. Jimmy Jib anchors its position through specialized engineering for broadcast television networks requiring repeatable, high-cycle performance. Edelkrone competes by miniaturizing motorized motion control into compact jib architectures for solo operators and small crews.
A camera jib is a cantilevered support arm mounted on a tripod or dolly base, typically constructed from aluminum extrusions, steel reinforcement nodes, or carbon fiber composite tubes, engineered to sweep cameras through extended radial arcs while maintaining parabolic stability for fluid cinematic motion. Standard jibs and heavy-duty jibs occupy the mature revenue core, though carbon fiber material adoption is expanding fastest as operators prioritize reduced setup weight without sacrificing 25-50 lbs payload integrity. Film production and sports broadcasting applications concentrate margin pools where rental houses and broadcast networks specify certified load ratings and repeatable tracking precision.
FCC equipment authorization requirements govern wireless motorized jib systems deployed in U.S. broadcast environments, while OSHA fall-protection standards influence operator platform and counterweight configurations on location sets. The EU Machinery Directive and CE marking framework shape export compliance for American and Asian manufacturers accessing European rental markets. Stakeholders must monitor evolving payload certification protocols and regional content production subsidies that redirect capital expenditure toward jib-enabled live streaming infrastructure.
Market Dynamics
Carbon fiber material substitution is compressing aluminum's historic dominance in mid-reach jib segments, forcing incumbent fabricators to reconfigure extrusion-to-composite conversion lines or cede 15-25 foot reach categories to specialized composite houses.
Growth Catalysts
- Live streaming infrastructure mandates:FCC equipment authorization protocols for wireless motorized systems are accelerating broadcast network refresh cycles across U.S. metropolitan production clusters.
- Carbon fiber tube manufacturing:Pultrusion process refinements from aerospace suppliers are reducing arm deflection tolerances below 2mm over 30-foot spans.
- OSHA fall-protection compliance:Counterweight platform specifications for location sets are standardizing rental fleet configurations and extending replacement demand.
Market Restraints
- Prepreg carbon fiber supply concentration:Toray and Hexcel control 60%+ of aerospace-grade tow supply, exposing jib fabricators to allocation risk during defense contract surges.
- CE marking friction:EU Machinery Directive conformity assessment timelines for motorized jib systems extend 8-14 months, freezing European rental market entry.
- Stabilized gimbal substitution:DJI Ronin and Freefly MōVI systems below 20 lbs payload are capturing solo-operator budgets previously allocated to compact jibs.
Strategic Opportunities
- Saudi content production subsidies:NEOM and Riyadh production zone incentives are redirecting Middle Eastern capital expenditure toward broadcast infrastructure including jib-enabled live streaming rigs.
- AI-assisted motion programming:Convergence of machine learning trajectory prediction with motorized head control is enabling single-operator jib deployment previously requiring three-person crews.
- India rental market formalization:PLI scheme benefits for audiovisual equipment manufacturing are attracting domestic assembly operations to service Bollywood and regional language production expansion.
Industry Challenges
- Certified rigger skill scarcity:OSHA-qualified personnel for 50+ lbs payload assembly command 40% wage premiums in Los Angeles and New York production clusters, constraining fleet utilization rates.
- Wireless frequency coordination complexity:FCC Part 15 unlicensed device congestion in dense urban broadcast environments requires dedicated spectrum engineering for motorized head systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Jib Market |
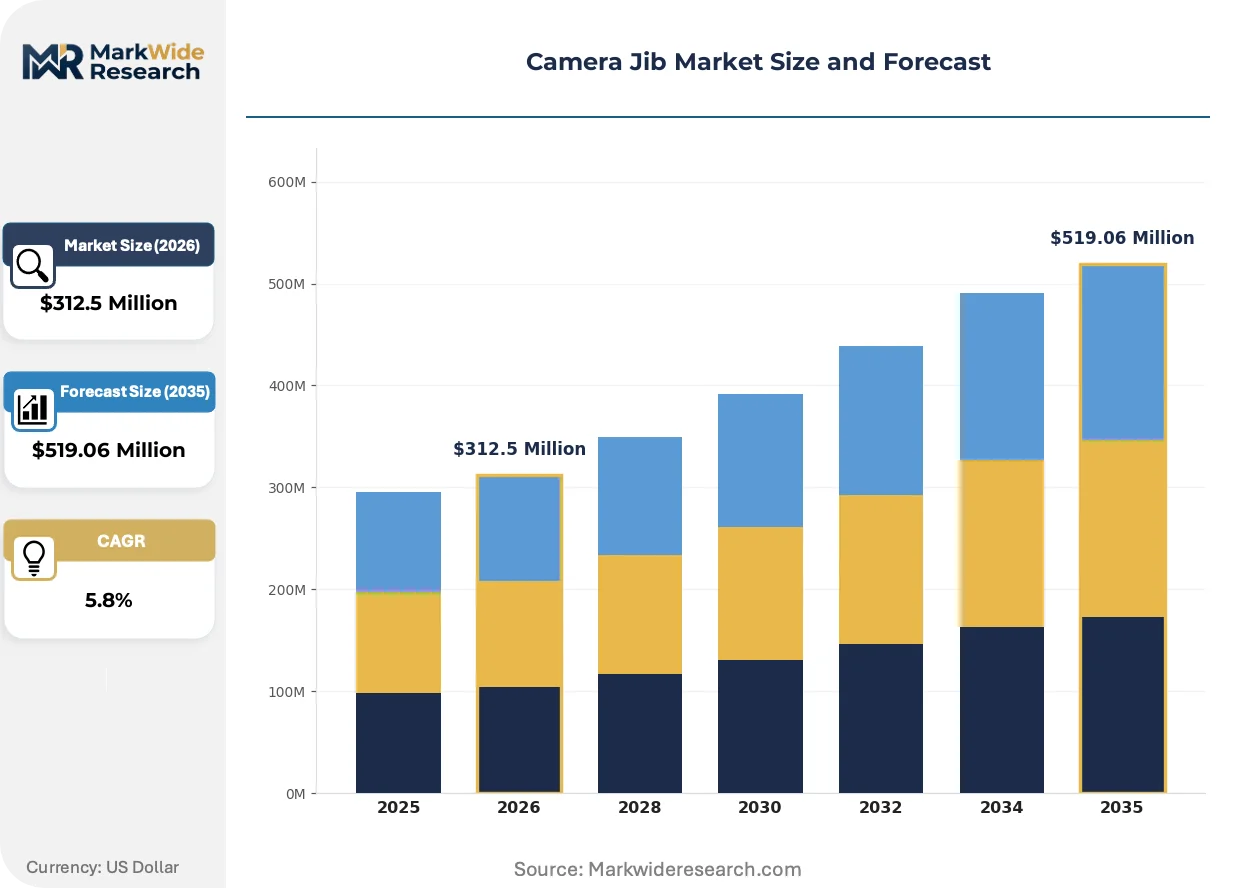
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standard Jibs, Mini Jibs, Heavy-Duty Jibs, Crane Jibs Material: Aluminium, Steel, Carbon Fiber, Plastic Application: Film Production, Live Events, Sports Broadcasting, Commercial Photography Payload Capacity: Up to 10 lbs, 10-25 lbs, 25-50 lbs, Over 50 lbs |
| Companies Covered | ProAm USA, Kessler Crane, Jimmy Jib, Libec, Hague Camera Supports, Edelkrone, Varavon, Rhino Camera Gear, CamMate Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Jib Market Trends and Innovations
Automated motion control architectures are migrating from broadcast-exclusive configurations into rental house inventories serving documentary and corporate verticals, compressing the feature gap between premium and mid-tier jib systems.
Carbon fiber composite construction is absorbing aluminum's position in 20-35 foot reach categories where weight reduction directly translates to reduced crew size and faster location setup. Sports broadcast networks operating rapid-strike mobile units are adopting these systems at replacement rates exceeding traditional aluminum by a factor of two. The technology is absorbing setup labor costs that previously consumed 15-20% of location production budgets.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate hydrofluorocarbon-based damping fluids in telescoping jib designs. Equipment suppliers are reformulating hydraulic systems with synthetic ester alternatives or migrating to electromechanical stabilization. Broadcast rental houses in Germany and France are prioritizing F-Gas-compliant inventory to preempt 2027 service restrictions.
Rental-first procurement patterns among independent production companies are displacing direct equipment ownership across sub-$50,000 project budgets. Specialty rental houses in Atlanta and London are consolidating maintenance, insurance, and operator certification into packaged daily rates. This shift concentrates fleet purchasing decisions among four to six national rental chains with certified load-rating documentation.
Camera Jib Market Segmentation
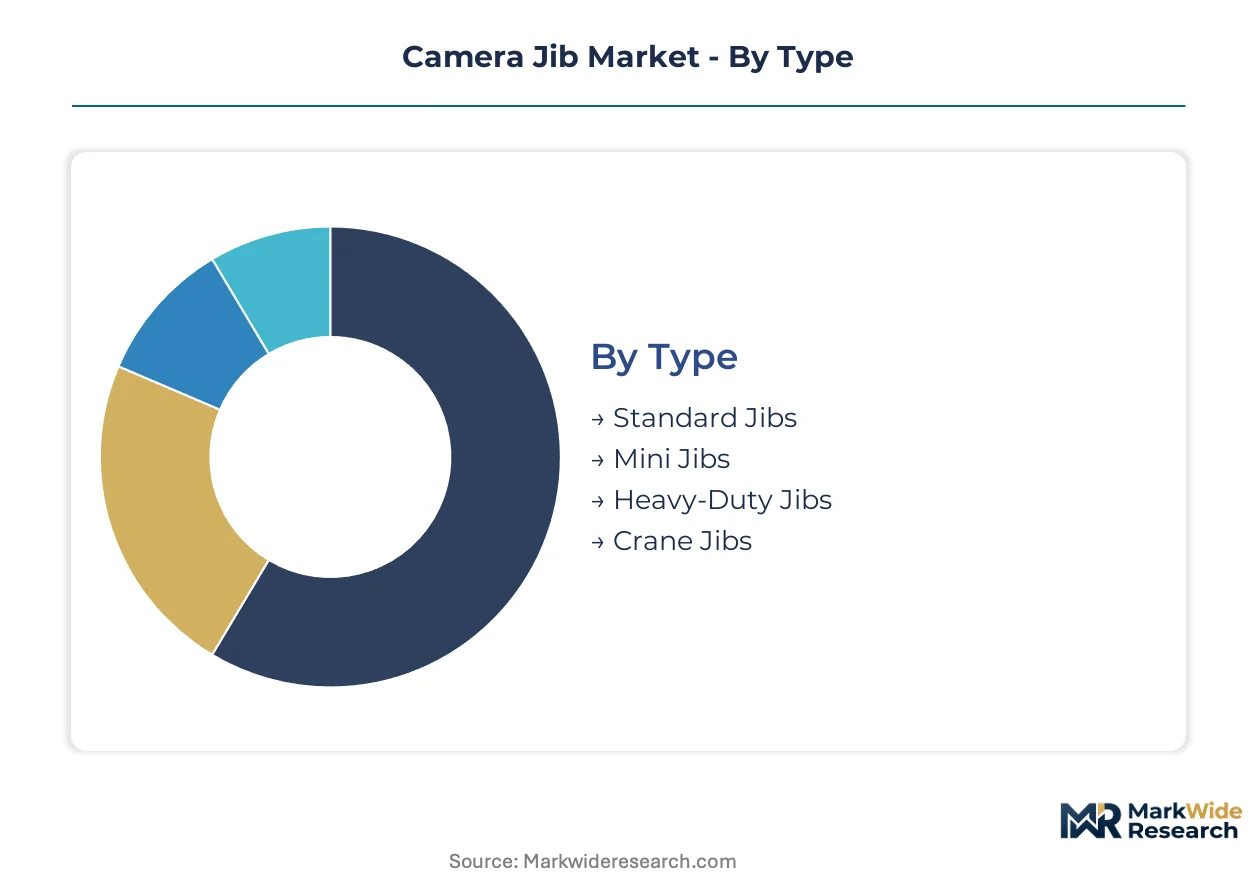
Camera jib procurement decisions pivot on payload requirements, reach specifications, and crew mobility constraints. Production houses segment their fleets across material grades and application verticals to optimize rental yields and operator deployment efficiency.
Type:
Production scale and crew size differentiate buyers across jib architectures, from solo-operated compact systems to multi-person broadcast cranes.
- Standard Jibs:Aluminum or carbon fiber arms spanning 8-20 feet dominate rental house inventories. Film production companies in Los Angeles and New York production clusters specify these for narrative features requiring repeatable parabolic tracking.
- Mini Jibs:Compact 3-6 foot architectures integrate with motorized heads for documentary and corporate verticals. Solo operators in Atlanta and London rental markets favor these for rapid location setup without certified rigger requirements.
- Heavy-Duty Jibs:Reinforced steel-node construction supports 50+ lbs cinema camera packages. Sports broadcast networks deploy these for stadium coverage requiring extended reach with broadcast-grade payload integrity.
- Crane Jibs:Telescoping 30-50 foot systems command specialized transport and assembly crews. Regional broadcast infrastructure projects in Saudi Arabia specify these for NEOM production zone live streaming mandates.
Standard Jibs leads volumes today; Mini Jibs is gaining share fastest.
Material:
Weight-to-stiffness ratios and supply chain access shape material selection, with aerospace-grade composites displacing legacy metals in premium tiers.
- Aluminium:Extruded 6061-T6 and 7075 alloys retain cost advantage in budget rental fleets. Indian domestic assembly operations under PLI scheme benefits favor aluminum for Bollywood production cost structures.
- Steel:Reinforcement nodes and base structures provide ballast stability for heavy-duty configurations. OSHA fall-protection compliance requirements standardize steel counterweight specifications across U.S. location sets.
- Carbon Fiber:Pultruded aerospace-grade tubes reduce 30-foot arm deflection below 2mm. Sports broadcast mobile units in Germany and France prioritize F-Gas-compliant carbon systems for rapid-strike deployment.
- Plastic:Glass-reinforced polymer components serve disposable protective housings and cable management channels. Solo-operator compact jibs integrate these for cost-sensitive entry-level procurement.
Aluminium leads volumes today; Carbon Fiber is climbing the fastest.
Application:
Content monetization models and production timelines create divergent specification requirements across end-use verticals.
- Film Production:Narrative features demand repeatable precision for multiple takes and VFX plate integration. Certified load ratings and parabolic stability specifications concentrate margin pools in this vertical.
- Live Events:Concert and corporate staging requires rapid assembly and wireless motorized head integration. FCC equipment authorization protocols govern wireless system deployment in U.S. metropolitan venues.
- Sports Broadcasting:Rapid-strike mobile units prioritize carbon fiber weight reduction for same-day multi-venue coverage. Replacement cycles in this vertical exceed traditional aluminum systems by a factor of two.
- Commercial Photography:Product and automotive campaigns specify compact jibs for controlled studio environments. Solo operators and small crews drive demand for miniaturized motorized motion control architectures.
Film Production leads volumes today; Live Events is expanding most quickly.
Payload Capacity:
Camera package weight and lens configuration dictate structural requirements, with certification thresholds segmenting procurement tiers.
- Up to 10 lbs:Mirrorless and compact cinema camera compatibility serves documentary and vlogger segments. DJI Ronin and Freefly MōVI stabilized gimbals capture budgets previously allocated to this jib category.
- 10-25 lbs:Mid-tier cinema cameras with cinema zoom lenses represent the rental house revenue core. Carbon fiber substitution is compressing aluminum's historic dominance in this bracket.
- 25-50 lbs:Full-feature cinema cameras with anamorphic lens packages require reinforced arm construction. Los Angeles and New York production clusters specify certified load ratings in this range for commercial and episodic work.
- Over 50 lbs:IMAX and specialized large-format systems demand heavy-duty engineering with OSHA-qualified rigging. Certified rigger skill scarcity commands 40% wage premiums, constraining fleet utilization rates.
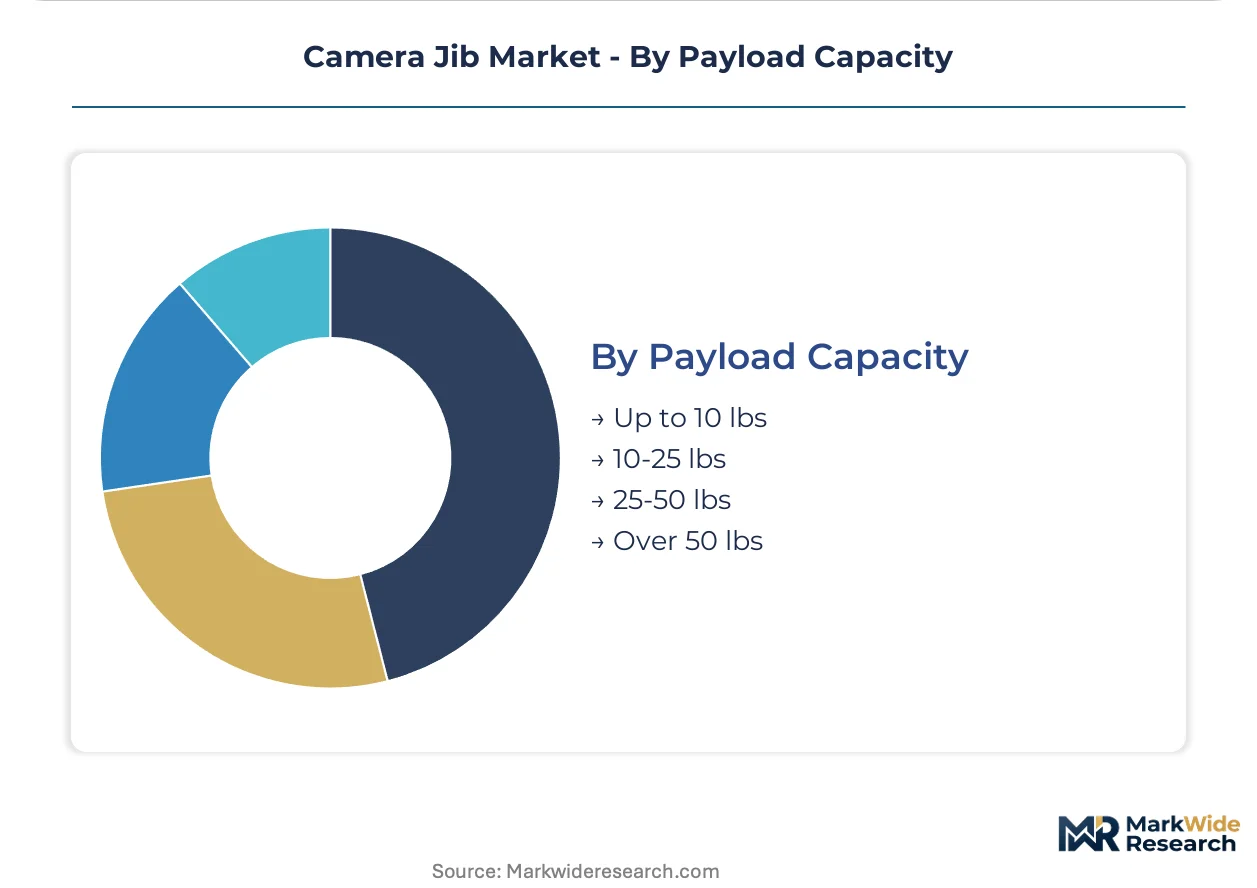
10-25 lbs leads volumes today; 25-50 lbs is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified riggers and broadcast technicians concentrate in Los Angeles and New York production clusters, anchoring North American demand for heavy-duty payload systems. These talent pools command wage premiums that reshape fleet economics across rental house networks.
United States
FCC equipment authorization mandates for wireless motorized jib systems accelerate broadcast network refresh cycles in metropolitan production zones. OSHA fall-protection standards govern counterweight platform specifications on location sets nationwide. Los Angeles and New York production clusters specify certified load ratings for commercial and episodic work, concentrating rental house purchasing decisions among four to six national chains.
Germany
EU F-Gas Regulation phase-down schedules pressure manufacturers to eliminate hydrofluorocarbon-based damping fluids in telescoping designs by 2027. CE marking conformity assessment timelines under the EU Machinery Directive extend equipment certification periods. Broadcast rental houses in Munich and Hamburg prioritize F-Gas-compliant carbon fiber inventory to preempt service restrictions.
United Kingdom
Live event production companies in London upgrade broadcast infrastructure to capture streaming revenue from concert and corporate staging verticals. The country's national broadcasting regulator enforces wireless frequency coordination protocols in dense urban venues. Specialty rental houses in Greater London consolidate maintenance, insurance, and operator certification into packaged daily rates.
India
PLI scheme benefits for audiovisual equipment manufacturing attract domestic assembly operations to service Bollywood and regional language production expansion. The country's national standards body certifies load ratings for rental fleet procurement. Mumbai and Chennai production hubs specify aluminum jib configurations optimized for local cost structures.
Saudi Arabia
NEOM and Riyadh production zone incentives redirect Middle Eastern capital expenditure toward jib-enabled live streaming infrastructure. The national media regulator mandates broadcast-grade equipment certification for content production subsidies. Crane jib systems with 30-50 foot reach specifications concentrate in northwestern development corridors.
Camera Jib Market Competitive Landscape
Top-tier vendors anchor precision-engineered carbon fiber systems, while commodity aluminum fabricators serve budget-conscious rental operators. The vendor base splits between vertically integrated manufacturers controlling quality across payload categories and specialized engineering houses serving broadcast television networks. Two strategic archetypes dominate: composite specialists leveraging aerospace supply chains, and motion control integrators miniaturizing motorized architectures. Competitive moves concentrate on material substitution and AI-assisted trajectory programming.
Among North American fabricators, Kessler Crane represents vertically integrated manufacturing archetypes, while Jimmy Jib exemplifies broadcast-specialized engineering positions. Edelkrone occupies a compact motion control tier serving solo operators and small crews. These three anchors illustrate how geographic concentration in Indiana production facilities, broadcast network relationships, and miniaturization R&D respectively shape competitive differentiation.
| Leading Market Players |
|---|
| ProAm USA |
| Kessler Crane |
| Jimmy Jib |
| Libec |
| Hague Camera Supports |
| Edelkrone |
| Varavon |
| Rhino Camera Gear |
| CamMate Systems |
| Others |
Pricing and Supply Chain Analysis
Rental-first procurement patterns among independent production companies are compressing direct equipment ownership economics and forcing manufacturers to reconfigure pricing around bundled service offerings rather than standalone hardware transactions.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the camera jib market. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber precision systems from aluminum commodity arms and entry-level plastic configurations. Price differentiation rests on certification grade and after-sales service bundling, with FCC-authorized motorized systems commanding substantial premiums over manual alternatives. Pricing pressure stems from stabilized gimbal substitution in sub-20 lbs payload brackets, where DJI Ronin systems capture solo-operator budgets. Independent production companies exhibit highest price sensitivity, while broadcast networks prioritize certified load ratings over unit cost.
Supply Chain Analysis
Warehouse-distribution layer concentration in Los Angeles, New York, and London rental hubs shapes downstream availability patterns. Manufacturing draws from aerospace-grade carbon fiber suppliers in the United States and Japan, aluminum extrusion facilities in China and India, and precision machining operations in Germany and Italy. Raw material dependencies include Toray and Hexcel prepreg tow, 6061-T6 aluminum billet, and synthetic ester hydraulic fluids. Single-source vulnerability in aerospace-grade carbon fiber allocation exposes fabricators to defense contract surge disruptions. Distribution runs through national rental chains consolidating fleet purchasing decisions with certified documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The camera jib market reads as a late-cycle quality story where carbon fiber precision systems capture disproportionate margin expansion as broadcast networks and sports mobile units prioritize reduced setup weight and repeatable tracking accuracy.
For Market Incumbents: Lock in aerospace carbon fiber supply agreements before defense contract surges constrain Toray and Hexcel allocation availability. Deepen backward integration into pultrusion processes to control arm deflection tolerances below 2mm specifications. Prioritize AI-assisted motion programming R&D to compress crew requirements from three-person to single-operator deployment. Defend against stabilized gimbal substitution by emphasizing 25-50 lbs payload integrity that gimbal architectures cannot match. For New Entrants and Emerging Players: Capture formalizing rental markets in India where PLI scheme benefits attract domestic assembly operations underserved by established Western brands. Target mini jib segments for documentary and corporate verticals where solo operators prioritize rapid location setup without certified rigger requirements. Leverage compact motorized motion control architectures to differentiate from legacy manual systems. Pursue direct-to-rental-house distribution bypassing traditional dealer networks. For Investors and Strategic Acquirers: Asymmetric upside sits with composite specialists controlling aerospace supply chain relationships and miniaturization R&D capabilities for AI-integrated motion control. Five-to-ten year viability favors manufacturers with vertically integrated Indiana or German production facilities capable of CE marking and FCC authorization compliance. Watch carbon fiber substitution rates in 20-35 foot reach categories as the inflection indicator for aluminum commoditization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Pultrusion | Captures arm deflection tolerance control from aerospace suppliers Toray and Hexcel. |
| AI-Assisted Motion Programming Development | Enables single-operator deployment previously requiring three-person crews with certified riggers. |
| FCC Equipment Authorization Investment | Unlocks wireless motorized system deployment in U.S. metropolitan broadcast production zones. |
| Rental House Consolidation Partnership | Concentrates fleet purchasing decisions among four to six national chains with certified documentation. |
| CE Marking Conformity Acceleration | Compresses 8-14 month EU Machinery Directive timelines to preempt F-Gas Regulation service restrictions. |
Research Methodology
Bottom-up film production and sports broadcasting modeling reconciled against top-down carbon fiber and aluminum supply tracking forms the analytical core of this study. Primary interviews with rental house fleet managers, broadcast network technical directors, certified riggers, and equipment manufacturing executives combined with secondary validation from FCC equipment authorization databases, EU Machinery Directive conformity assessments, OSHA fall-protection standard filings, and PLI scheme beneficiary disclosures. Trade customs data from U.S. Census Bureau and DGFT India provided import-export triangulation for supply-side calibration.
Input-output matrices mapped payload capacity requirements against material substitution trajectories and application vertical growth rates across the projection horizon. Segmentation dimensions modeled include jib type, material grade, application vertical, payload capacity tier, and geographic production cluster. CAGRs derived from regression analysis of replacement cycle acceleration in sports broadcast mobile units and rental fleet refresh patterns in Los Angeles and New York production clusters. Forecast inputs incorporated carbon fiber tube manufacturing yield improvements and certified rigger wage premium dynamics.
Underlying measurement precision varies by segment; carbon fiber material adoption and live events application growth carry tighter precision than heavy-duty jib demand and plastic component substitution. Forecasts reflect documented assumptions regarding aerospace supply allocation stability and regulatory timeline adherence. Decision-makers should treat outputs as directional within the stated assumption set, acknowledging that defense contract surges, CE marking delays, or accelerated gimbal technology advancement could materially revise trajectory projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Film Dubbing Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
Movie Tickets Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Cinema Camera Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
Drive-In Movie Theater Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
China Animation, VFX and Post Production Market