
 North America Animation, VFX and Post Production Market | 2026-2036
North America Animation, VFX and Post Production Market Size, Share, and Industry Trends Forecast 2026-2036
North America Animation, VFX and Post Production Market Insights
Real-time engine licensing is reshaping margin distribution between traditional offline rendering and interactive production pipelines. Industrial Light & Magic leverages proprietary virtual production stages to anchor high-budget franchise work. Pixar Animation Studios sustains leadership through RenderMan software licensing and in-house production integration. Sony Pictures Imageworks competes across both feature film and streaming series workloads, extending its facility footprint from Culver City to Vancouver.
Animation, VFX and post production encompasses the creation, manipulation, and finishing of moving image content through digital or hybrid analog-digital processes, typically involving frame rates of 24–120 fps, color depths of 10–16 bit, and delivery resolutions from 2K through 8K. Its primary purpose is to generate finished audiovisual assets for theatrical exhibition, broadcast transmission, or digital distribution. Visual effects and 3D animation services capture the largest share of production spending as franchise content demands escalate. Streaming platforms represent the fastest-growing end-user channel, displacing traditional television network commissioning volumes. Rendering engines and animation software form the technology core where vendor consolidation is concentrating tool procurement decisions.
The FCC governs broadcast technical standards affecting delivery specifications, while Canadian Heritage administers federal and provincial tax credits that structure production location decisions across the Canada–US border. OSHA workplace guidelines and SAG-AFTRA contractual frameworks shape labor cost structures and on-set production protocols in both countries. Stakeholders must monitor how generative AI training data regulations emerging from Washington and Ottawa will redefine intellectual property boundaries for derivative visual content.
Market Dynamics
Streaming platform commissioning cycles are compressing traditional production timelines while AI-assisted rendering pipelines redistribute labor allocation across California and British Columbia facilities.
Growth Catalysts
- Canadian Federal Tax Credits:The Canadian Heritage federal and provincial incentive framework attracts franchise productions to Vancouver's production corridor, redistributing volume from Los Angeles Basin facilities.
- Real-time Engine Technology:Virtual production stages using game engine licensing reduce location shooting requirements and compress post-production schedules for high-budget series.
- Streaming Original Content Budgets:United States and Canada-based platforms commission exclusive animated and VFX-heavy series, displacing traditional network television volume.
Market Restraints
- Render Farm Energy Costs:GPU-intensive processing requirements expose facilities to electricity price volatility in California's deregulated power markets.
- Cross-Border Talent Competition:British Columbia's provincial incentives and California's production density create bidding wars for specialized compositing and rigging specialists.
- SAG-AFTRA Contractual Frameworks:Union-mandated minimum staffing ratios and residual structures inflate fixed production costs for union-signatory projects.
Strategic Opportunities
- Generative AI Training Data Regulation:Emerging Washington and Ottawa frameworks around derivative visual content intellectual property create first-mover advantage for studios with clean training datasets.
- Texas Production Corridor:Austin's emerging post-production cluster offers lower operating costs than Los Angeles Basin or Vancouver for mid-budget streaming series.
- Virtual Production Stage Convergence:Integration of LED volume stages with real-time rendering engines enables same-day final-pixel output for episodic television.
Industry Challenges
- Pipeline Standardization Delays:Absence of unified file format standards between Autodesk Maya, Foundry Nuke, and Epic Unreal Engine workflows forces custom integration scripts per facility.
- Specialized Talent Pipeline Gaps:Technical artist programs at Sheridan College and California Institute of the Arts graduate insufficient simulation and machine learning operations specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Animation, VFX and Post Production Market |
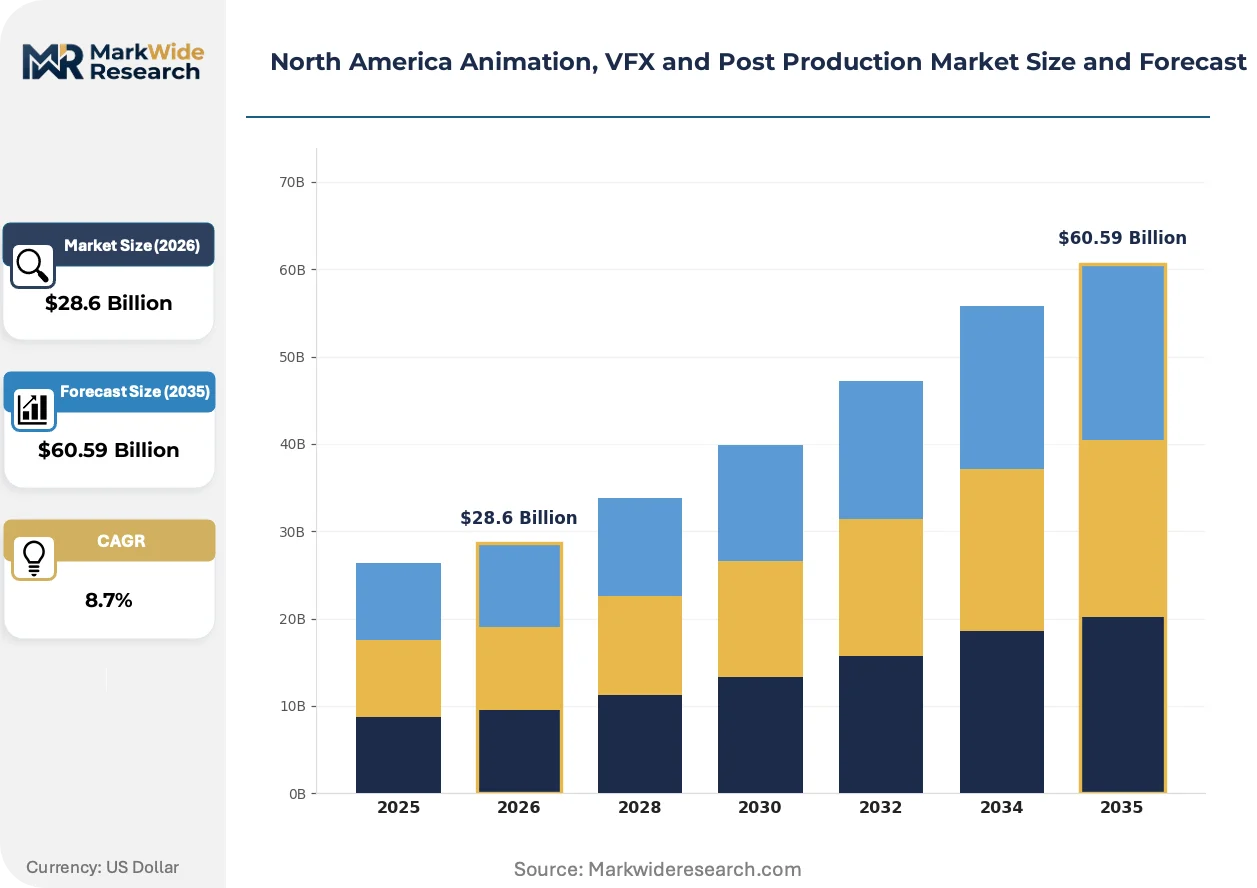
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 3D Animation, Visual Effects, Motion Graphics, Compositing End User: Film Studios, Advertising Agencies, Television Networks, Streaming Platforms Technology: Animation Software, Rendering Engines, Editing Tools, Virtual Reality Application: Feature Films, Commercials, Video Games, Documentaries |
| Companies Covered | Industrial Light & Magic (ILM), DNEG, Walt Disney Animation Studios, Wētā FX, Framestore, Pixar Animation Studios, Sony Pictures Imageworks, Rodeo FX, DreamWorks Animation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Animation, VFX and Post Production Market Trends and Innovations
Production technology is collapsing the boundary between principal photography and post-production, with real-time rendering engines enabling iterative visual development during live-action shoots rather than after wrap.
Unreal Engine and Unity render pipelines are hybridizing traditional offline ray-tracing with game-engine interactivity. Major streaming series productions in Los Angeles and Vancouver adopt these tools for virtual location scouting and in-camera VFX. This compression of the production cycle is eliminating weeks from traditional post schedules while demanding new skill sets from cinematographers and editors.
The FCC maintains broadcast technical standards governing 4K and 8K delivery specifications, while OSHA workplace guidelines for LED volume stage operations introduce new safety certification requirements. Studios must now integrate electromagnetic exposure monitoring and thermal management protocols into virtual production facility designs. California-based facilities face the strictest compliance timelines as Los Angeles Basin construction permits incorporate these standards.
Commissioning patterns among streaming platforms favor volume-based output agreements over per-project contracts. Netflix, Amazon Prime Video, and Disney+ negotiate multi-series commitments with Sony Pictures Imageworks and Industrial Light & Magic, consolidating supplier relationships. This concentration is most pronounced in Culver City and Vancouver, where anchor tenants secure preferred capacity allocation through long-term facility leases.
North America Animation, VFX and Post Production Market Segmentation
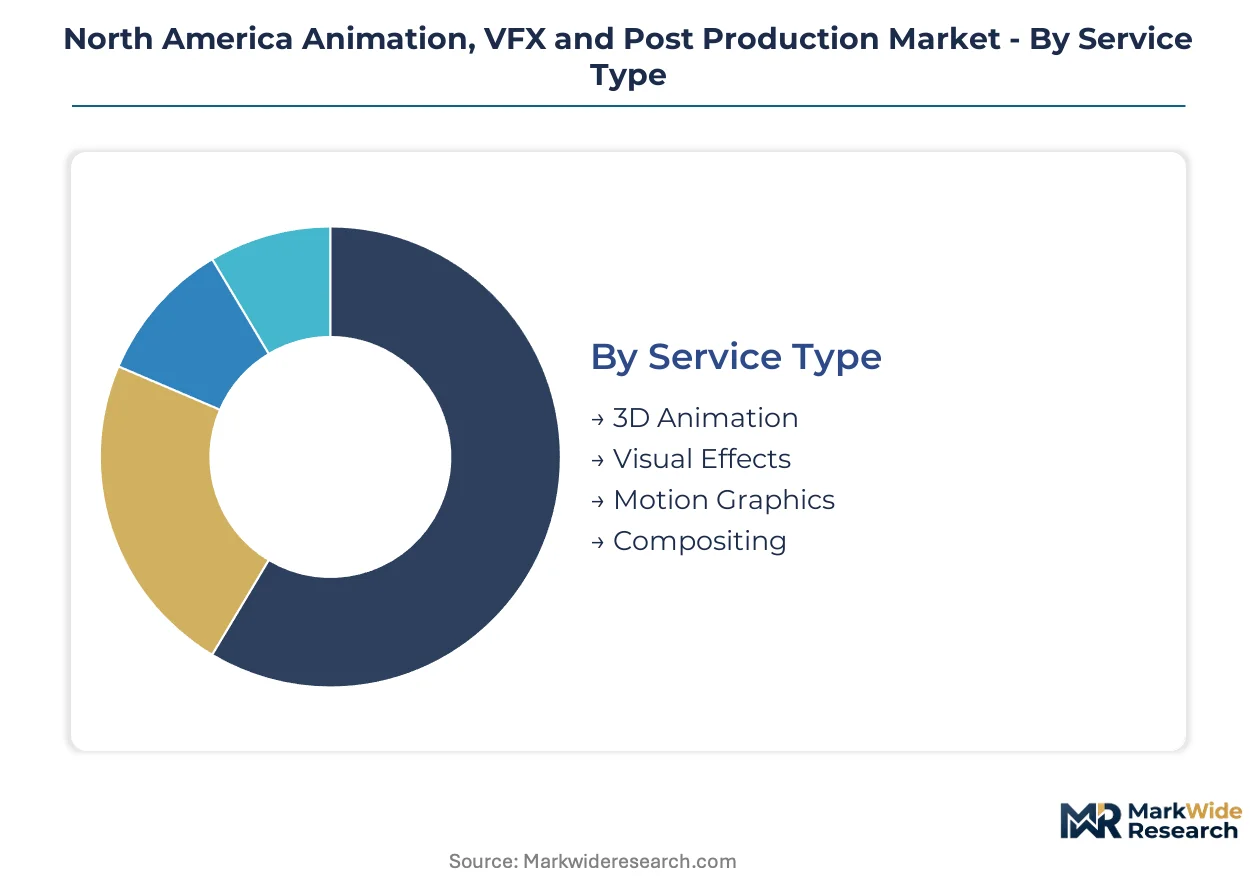
Segmentation in the North America Animation, VFX and Post Production Market reveals how service specialization, technology deployment, and end-user procurement patterns create distinct competitive arenas. Each dimension carries different margin profiles and capital intensity requirements that shape vendor positioning across Los Angeles Basin and Vancouver facilities.
Service Type:
After-sales service intensity varies sharply across service categories, with ongoing software support and retainer-based compositing work creating recurring revenue streams distinct from project-based animation delivery.
- 3D Animation:Character rigging, environmental modeling, and procedural animation workflows demand specialized technical artist teams. Los Angeles Basin facilities capture franchise feature work, while Vancouver corridors handle episodic streaming series volumes driven by Canadian federal tax credit structures.
- Visual Effects:Particle simulation, digital doubles, and destruction sequences require GPU-intensive render farm infrastructure. British Columbia's provincial incentives attract high-complexity VFX shots, redistributing project flow from California facilities facing OSHA-mandated LED volume stage compliance costs.
- Motion Graphics:Title sequences, broadcast packaging, and branded content occupy mid-budget production tiers. Austin's emerging post-production cluster targets this segment with lower operating cost structures than coastal facilities.
- Compositing:Layer integration, color matching, and final image assembly represent the labor-intensive pipeline terminus. Culver City and Vancouver facilities compete directly for streaming platform volume through multi-series output agreements.
By volume, Visual Effects leads. By expansion trajectory, 3D Animation is climbing the fastest.
End User:
Cost tier differentiation separates premium theatrical commissioning from high-volume episodic production, with residual structures and union signatory requirements creating distinct procurement economics.
- Film Studios:Theatrical franchise releases command premium per-shot VFX budgets and extended post-production timelines. California facilities anchor this tier through proximity to studio decision-makers and SAG-AFTRA contractual frameworks.
- Streaming Platforms:Volume-based commissioning favors integrated production pipelines and rapid turnaround cycles. Netflix, Amazon Prime Video, and Disney+ negotiate multi-series commitments consolidating supplier relationships in Vancouver and Culver City.
- Advertising Agencies:Campaign-driven production cycles emphasize motion graphics and rapid compositing turnaround. This segment concentrates in Los Angeles Basin facilities with established commercial production infrastructure.
- Television Networks:Traditional broadcast commissioning faces displacement from streaming volume, though FCC technical standards for 4K and 8K delivery maintain infrastructure requirements.
Streaming Platforms now dominate commissioning volume, while Film Studios retain the highest per-project value concentration.
Technology:
Application intensity determines procurement patterns, with real-time engine adoption compressing traditional offline rendering timelines and reshaping facility capital allocation.
- Animation Software:Autodesk Maya and proprietary tools anchor character and environmental workflows. Pipeline standardization gaps between platforms force custom integration scripts per facility.
- Rendering Engines:GPU-intensive processing requirements expose facilities to electricity price volatility in California's deregulated power markets. RenderMan licensing and Unreal Engine adoption concentrate in high-budget production tiers.
- Editing Tools:Non-linear editing systems integrate with color finishing and sound design workflows. Foundry Nuke and Adobe Premiere dominate facility procurement decisions.
- Virtual Reality:Immersive previsualization and 360-degree content creation represent emerging capability investments. OSHA workplace guidelines for electromagnetic exposure monitoring shape facility design requirements.
Rendering Engines command the largest capital expenditure share, while Virtual Reality is gaining adoption fastest among frontier production techniques.
Application:
Maturity curves separate established theatrical formats from expanding interactive and documentary segments, with delivery specifications varying across FCC-regulated broadcast and platform-native streaming standards.
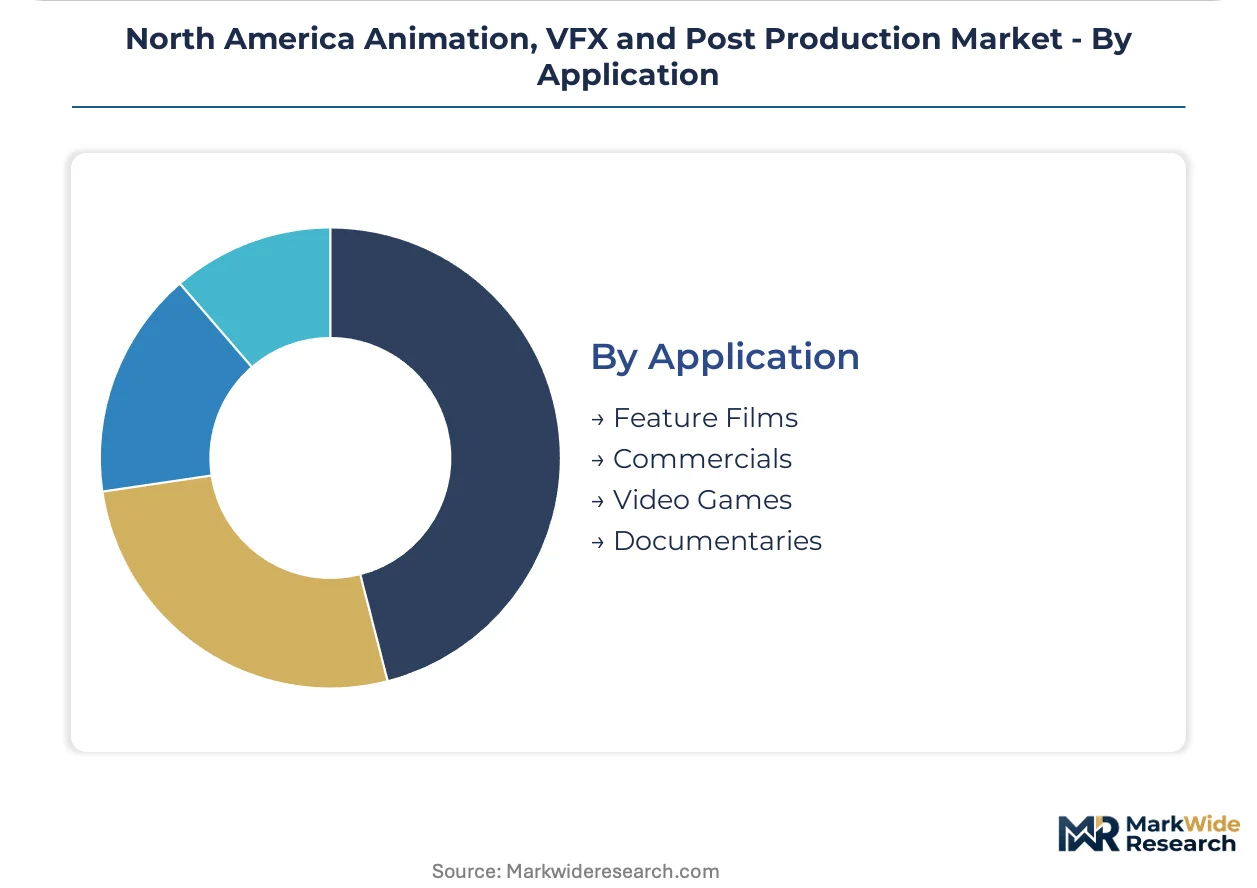
- Feature Films:Theatrical exhibition demands 4K through 8K delivery with HDR color pipelines. Franchise content concentration drives VFX spending toward Los Angeles Basin and Vancouver anchor facilities.
- Commercials:Campaign-driven production favors motion graphics and rapid turnaround workflows. Austin's lower-cost production corridor targets this application tier specifically.
- Video Games:Real-time engine convergence enables asset reuse between cinematic and interactive production. Epic Unreal Engine licensing bridges post-production and game development pipelines.
- Documentaries:Archive restoration and factual content finishing occupy specialized facility niches. Canadian Heritage funding structures support documentary post-production in Vancouver.
Feature Films maintain the highest production value per minute, though Video Games are expanding most quickly through engine technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Streaming platforms exhibit the sharpest demand elasticity, compressing timelines and squeezing margins for mid-tier facilities, while theatrical franchise work retains price-inelastic commissioning patterns anchored to Los Angeles Basin premium tiers.
United States
California's Los Angeles Basin concentrates theatrical franchise VFX and premium animation through proximity to studio decision-makers and SAG-AFTRA contractual frameworks. OSHA workplace guidelines for LED volume stage operations impose strict electromagnetic exposure monitoring and thermal management protocols on facility designs. Industrial Light & Magic anchors high-budget production through proprietary virtual production stages in Culver City.
Canada
British Columbia's provincial incentives and Canadian Heritage federal tax credits attract high-complexity VFX shots and episodic streaming volumes from US-based platforms. Competition between Vancouver's production corridor and Los Angeles facilities intensifies bidding wars for specialized compositing and rigging specialists. Sony Pictures Imageworks extends its facility footprint from Culver City to Vancouver to capture these incentive-driven flows.
Mexico
Emerging post-production clusters in Mexico City Metro and Guadalajara target motion graphics and mid-budget streaming series with labor cost advantages over US and Canadian facilities. The Secretariat of Economy's film and audiovisual sector promotion programs support infrastructure development. Baja California's proximity to Los Angeles enables nearshore servicing of commercial and documentary finishing work.
North America Animation, VFX and Post Production Market Competitive Landscape
Integrated production houses and specialized VFX boutiques split the market between franchise-scale volume commitments and agile episodic servicing. The vendor base concentrates around anchor tenants securing preferred capacity allocation through long-term facility leases in Culver City and Vancouver. Three archetypes dominate: technology-licensing studios with proprietary render pipelines, scale-driven multi-facility operators, and niche specialists in simulation or creature work. Competitive moves center on geographic expansion to capture tax incentive arbitrage and technology licensing partnerships with real-time engine providers.
Within the technology-licensing tier, Pixar Animation Studios and Industrial Light & Magic exemplify studios leveraging proprietary software and virtual production infrastructure to anchor premium-tier work. Sony Pictures Imageworks occupies a position spanning both feature film and streaming series workloads, representing the scale-driven archetype with multi-city facility footprints. Among specialized operators, DNEG and Framestore sit within the high-complexity VFX tier serving franchise theatrical releases.
| Leading Market Players |
|---|
| Industrial Light & Magic (ILM) |
| DNEG |
| Walt Disney Animation Studios |
| Wētā FX |
| Framestore |
| Pixar Animation Studios |
| Sony Pictures Imageworks |
| Rodeo FX |
| DreamWorks Animation |
| Others |
Pricing and Supply Chain Analysis
GPU render farm concentration in California's Los Angeles Basin and Vancouver's production corridor concentrates margin capture among facilities with captive infrastructure, while electricity price volatility in deregulated markets redistributes pricing power toward British Columbia's hydro-powered facilities.
Pricing Analysis
After-sales service intensity through multi-series output agreements drives lifetime value for anchor tenants in Culver City and Vancouver. Three-tier pricing structure across premium franchise theatrical, standard streaming episodic, and economy motion graphics tiers reflects project complexity and turnaround compression. Pricing pressure stems from streaming platform volume commitments squeezing per-shot margins for mid-tier facilities. Advertising agencies exhibit highest price sensitivity due to campaign-driven procurement cycles, while film studios retain lowest sensitivity through franchise-locked supplier relationships.
Supply Chain Analysis
Export-control regimes limiting high-performance GPU and rendering software flows to certain jurisdictions constrain hardware procurement flexibility for facilities in contested technology markets. Supply concentrates in Taiwan for advanced semiconductor fabrication, South Korea for memory components, and the United States for specialized software licensing. Raw material dependencies span rare earth elements for LED volume stages, copper for thermal management infrastructure, and specialized optical substrates for camera systems. Single-source vulnerability around NVIDIA GPU allocation creates bottleneck risk for California render farms. Distribution runs through direct vendor relationships with streaming platforms and studio procurement offices, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as streaming platform commissioning normalizes following post-pandemic budget retrenchment, with original content budgets expanding across Netflix, Amazon Prime Video, and Disney+.
For Market Incumbents: Insulate core franchise relationships through proprietary virtual production stage investments and multi-year facility leases in tax-advantaged jurisdictions. Anchor tenant status in Culver City or Vancouver production corridors provides defensive positioning against emerging Texas and Mexico clusters. Backward integration into real-time engine licensing and in-house render pipeline development reduces third-party dependency for high-budget theatrical work.
For New Entrants and Emerging Players: Establish a beachhead in Austin's emerging post-production corridor or Mexico City's motion graphics cluster where incumbent density remains lowest. Target mid-budget streaming series and commercial finishing work where price-sensitive buyers accept newer facility relationships. Go-to-market positioning around rapid turnaround cycles and lower overhead structures penetrates advertising agency procurement committees most effectively.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across virtual production stage infrastructure as LED volume technology becomes table stakes for premium-tier work. Long-term viability favors facilities with integrated real-time rendering pipelines and multi-city footprints spanning tax incentive jurisdictions. Acquisition targets should demonstrate clean training datasets for generative AI workflows and established relationships with at least two major streaming platforms. Watch for inflection when Canadian Heritage or California tax credit structures shift materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Production Stage Buildout | LED volume infrastructure anchors multi-series commitments from Netflix and Disney+ in Culver City. |
| Real-Time Engine Licensing Partnership | Unreal Engine integration compresses post-production timelines for episodic streaming workloads. |
| Multi-Facility Geographic Expansion | Vancouver tax credits attract high-complexity VFX shots from Los Angeles Basin anchor tenants. |
| Proprietary Render Pipeline Development | In-house software reduces third-party dependency and captures margin from RenderMan licensing. |
| Clean Training Dataset Curation | Generative AI regulatory frameworks from Washington and Ottawa reward first-mover IP compliance. |
Research Methodology
The analysis maps 3D animation, visual effects, compositing, and motion graphics sub-sectors, each validated through VFX supervisors, streaming platform content executives, post-production facility operators, and Canadian Heritage tax credit administrators. Primary interviews combined with secondary validation from FCC broadcast technical standards filings, OSHA workplace guideline updates, SEC filings from major studio parents, and provincial incentive program disclosures. Bottom-up project pipeline tracking triangulates against top-down streaming content budget analysis.
Assumption-sets held Canadian federal and provincial tax credit structures constant while varying streaming platform commissioning velocity and AI-assisted rendering adoption curves across the projection horizon. Segmentation dimensions modeled include service type, end-user procurement tier, technology deployment intensity, and application format maturity. CAGRs derive from facility capacity utilization rates, content budget trajectories, and labor cost differential analysis between Los Angeles Basin and Vancouver corridors. Forecast inputs incorporate render farm energy cost volatility and SAG-AFTRA contractual framework evolution.
Sensitivities concentrate around generative AI training data regulatory shifts, tax incentive competition between British Columbia and California, and streaming platform volume commitment durability. Forecasts reflect assumptions documented in stakeholder interviews and secondary source triangulation. Material shifts in FCC broadcast technical standards or OSHA LED volume stage compliance timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
Camera Jib Market
Film and Cinema
Drive-In Movie Theater Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Movie Tickets Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Cinema Camera Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Movies and Entertainment Market