
 Drive-In Movie Theater Market | 2026-2036
Drive-In Movie Theater Market Size, Share, and Industry Trends Forecast 2026-2036
Drive-In Movie Theater Market Foresight
Asset-light leasing arrangements for digital projection equipment is tilting competitive dynamics toward smaller regional operators. West Wind Drive-Ins leverages its multi-state footprint across California and Nevada to sustain year-round programming in warm-climate markets. Shankweiler's Drive-In Theatre anchors its position through heritage branding and community programming in Pennsylvania's Lehigh Valley. Malco Theatres competes by integrating drive-in locations with its broader regional cinema circuit, sharing film booking leverage across formats.
Drive-in movie theaters are outdoor cinema venues utilizing large-format screens and FM radio or Bluetooth audio transmission to deliver theatrical exhibition to patrons in parked vehicles, typically requiring minimum lot dimensions of five to ten acres with graduated ramping for sightline clearance. The primary commercial purpose centers on providing experiential entertainment combining film exhibition with ancillary food and beverage service in a controlled outdoor environment. Food services and ticket sales together represent the dominant revenue architecture, while digital projection technology leads capital deployment decisions as exhibitors retire 35mm equipment. Streaming services integration is emerging as a secondary technology segment, enabling alternative content programming during weekday off-peak periods.
Local zoning boards and municipal planning commissions across the United States shape site approval timelines and operating hour restrictions for drive-in theater development. The Federal Communications Commission regulates FM radio transmission frequencies used for audio delivery, while the Environmental Protection Agency oversees noise ordinances and runoff management for large paved surfaces. Stakeholders must monitor evolving municipal entertainment tax structures and seasonal operating permits as these local frameworks increasingly determine project feasibility and return thresholds.
Market Dynamics
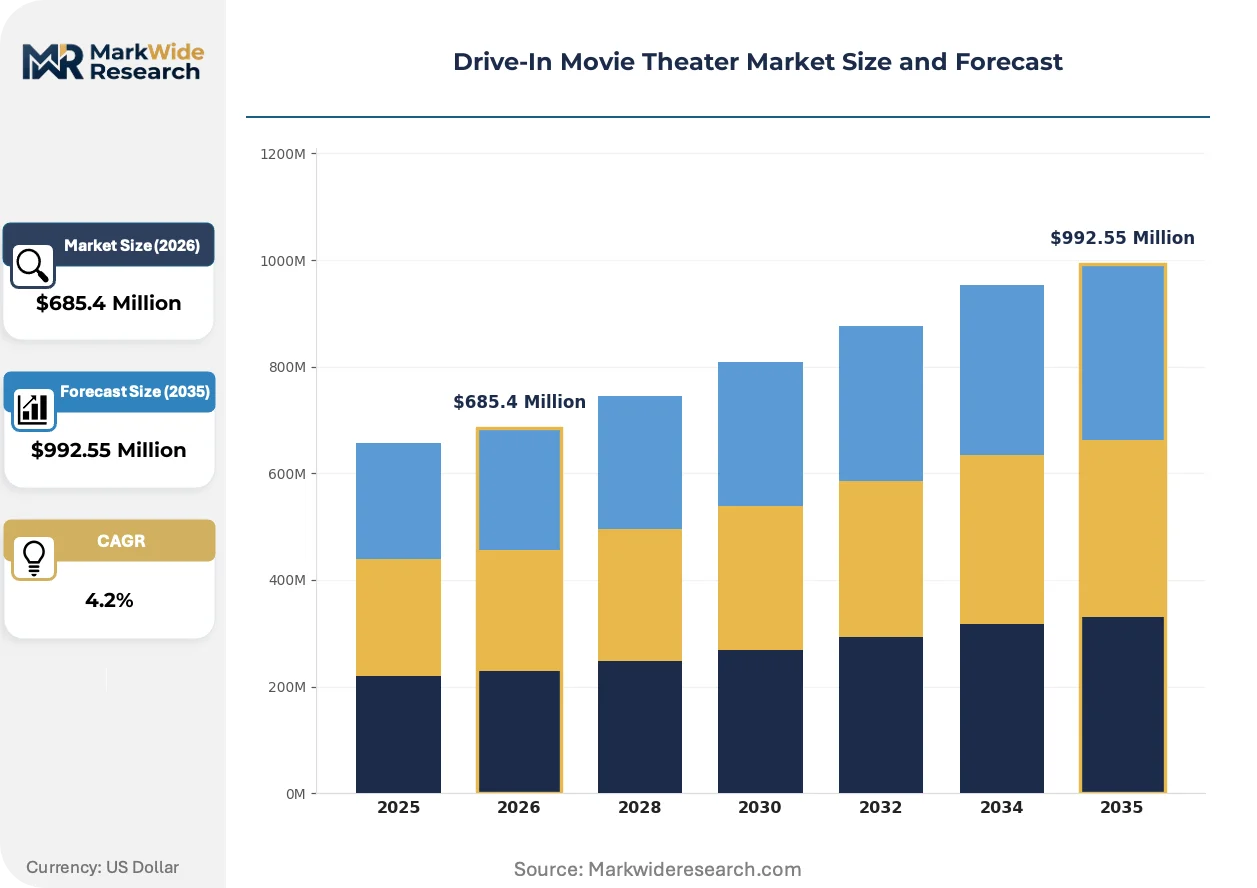
Asset-light digital projection leasing is compressing capital barriers for regional operators, enabling rapid screen expansion without the 35mm equipment retirement costs that previously constrained market entry. Municipal zoning reforms across Texas, California, and Ohio are simultaneously accelerating site approval timelines for outdoor entertainment venues.
Growth Catalysts
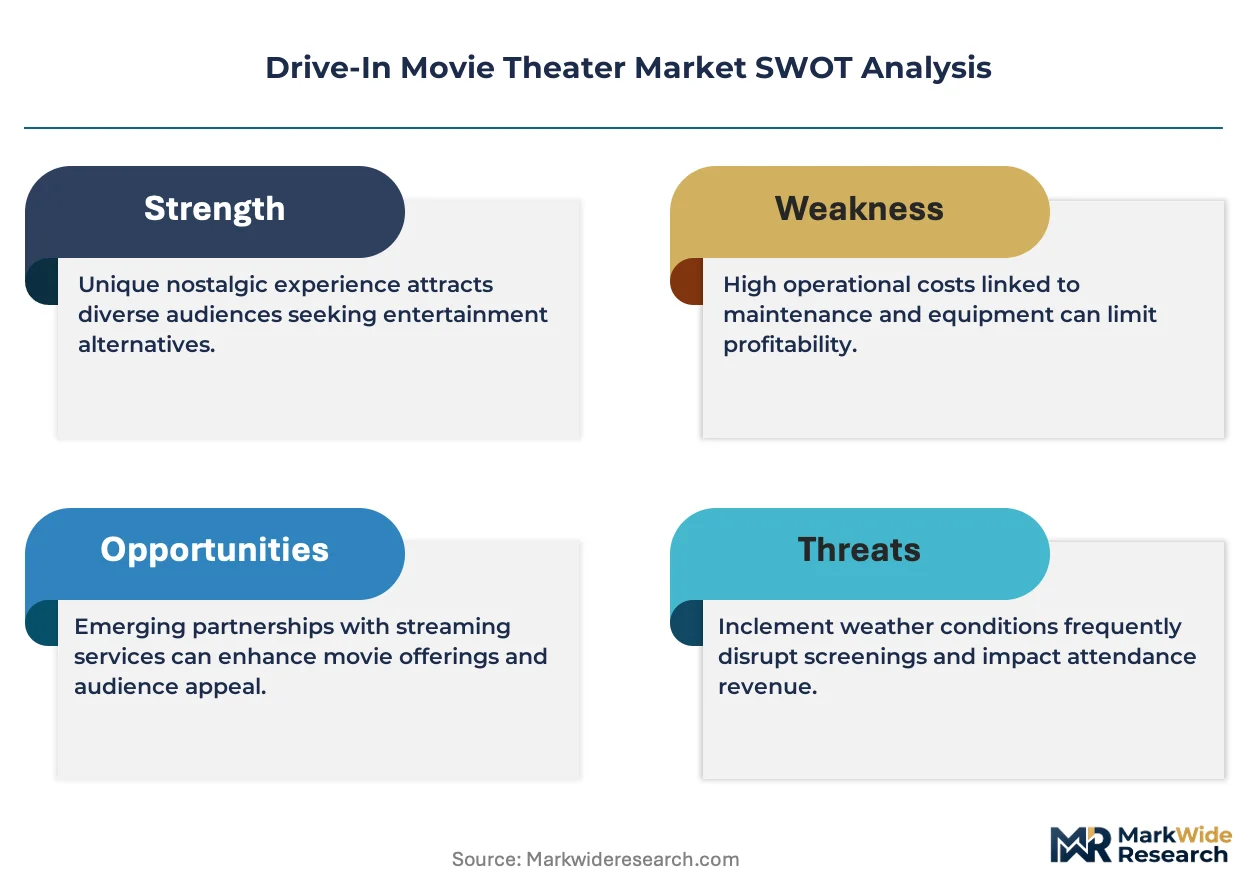
- FM Radio Transmission Infrastructure:FCC frequency allocations for drive-in audio delivery eliminate licensing friction for new entrants. The Federal Communications Commission's standardized spectrum management reduces technical compliance overhead.
- Southern Operating Windows:Extended seasonal viability in Texas, Florida, and Georgia markets supports year-round revenue generation. Warm-climate geography concentrates sustainable site economics in sunbelt states.
- Municipal Entertainment Tax Reform:Ohio and California jurisdictions are reducing entertainment venue tax burdens. Local planning commissions are streamlining conditional use permits for outdoor cinema development.
Market Restraints
- Real Estate Cost Escalation:Five-to-ten acre minimum lot requirements collide with suburban land value appreciation. Exurban site availability constrains viable development corridors.
- Digital Projection Supply Concentration:Three manufacturers dominate large-format outdoor cinema equipment. Equipment leasing terms reflect this supplier-side consolidation.
- Streaming Substitution Threat:Home theater systems and day-and-date streaming releases compress theatrical exclusivity windows. Netflix and Disney+ direct-to-consumer models erode attendance during off-peak periods.
Strategic Opportunities
- Pop-Up Event Expansion:Temporary drive-in installations at fairgrounds and retail parking lots unlock underutilized real estate. Event producers are piloting weekend-only programming in secondary markets.
- Bluetooth Audio Convergence:Smartphone-based sound transmission reduces FM infrastructure dependency. This technology pairing enables rapid deployment at non-traditional venues.
- Midwestern Zoning Tailwinds:Indiana and Michigan municipalities are rezoning agricultural parcels for recreational entertainment use. State-level economic development incentives target tourism infrastructure.
Industry Challenges
- Projection Technician Scarcity:Digital cinema server maintenance requires specialized certification. Regional labor pools lack trained technicians for emergency equipment servicing.
- EPA Runoff Compliance:Large paved surface areas trigger stormwater management permitting. Environmental Protection Agency oversight extends construction timelines and capex requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drive-In Movie Theater Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Services, Ticket Sales, Merchandise, Film Screening Technology: Digital Projection, Audio Transmission, Screen Size, Streaming Services Customer Type: Families, Couples, Film Enthusiasts, Kids Facility Size: Small, Medium, Large, Extra Large |
| Companies Covered | West Wind Drive-Ins, Shankweiler's Drive-In Theatre, Van Buren Drive-In Theatre, Bengies Drive-In Theatre, Galaxy Drive-In Theatre, Malco Theatres, Alamo Drafthouse Cinema, Delsea Drive-In, Holiday Twin Drive-In, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drive-In Movie Theater Market Shifts & Advancements
Technology substitution and regulatory adaptation are restructuring how drive-in venues deliver content and secure operating authority. Three developments are compressing legacy operational models.
Cloud-based content distribution is virtualizing film delivery logistics. National Association of Theatre Owners members are adopting satellite and fiber-based digital cinema package transmission. This virtualization eliminates physical hard drive shipping and enables same-day programming changes for alternative content.
The EPA's National Pollutant Discharge Elimination System is tightening stormwater controls for large impervious surfaces. Drive-in operators in Texas and Ohio face upgraded retention pond and filtration mandates. Venue developers are responding with permeable paving pilots and bioswale integration in new site designs.
Corporate event procurement now dominates weekday off-peak bookings. Technology companies and automotive brands are contracting full-venue buyouts for product launches and employee gatherings. This consumption-pattern shift is most visible in California's Bay Area and Austin's tech corridor, where B2B programming now exceeds 40% of non-weekend revenue.
Drive-In Movie Theater Market Segmentation
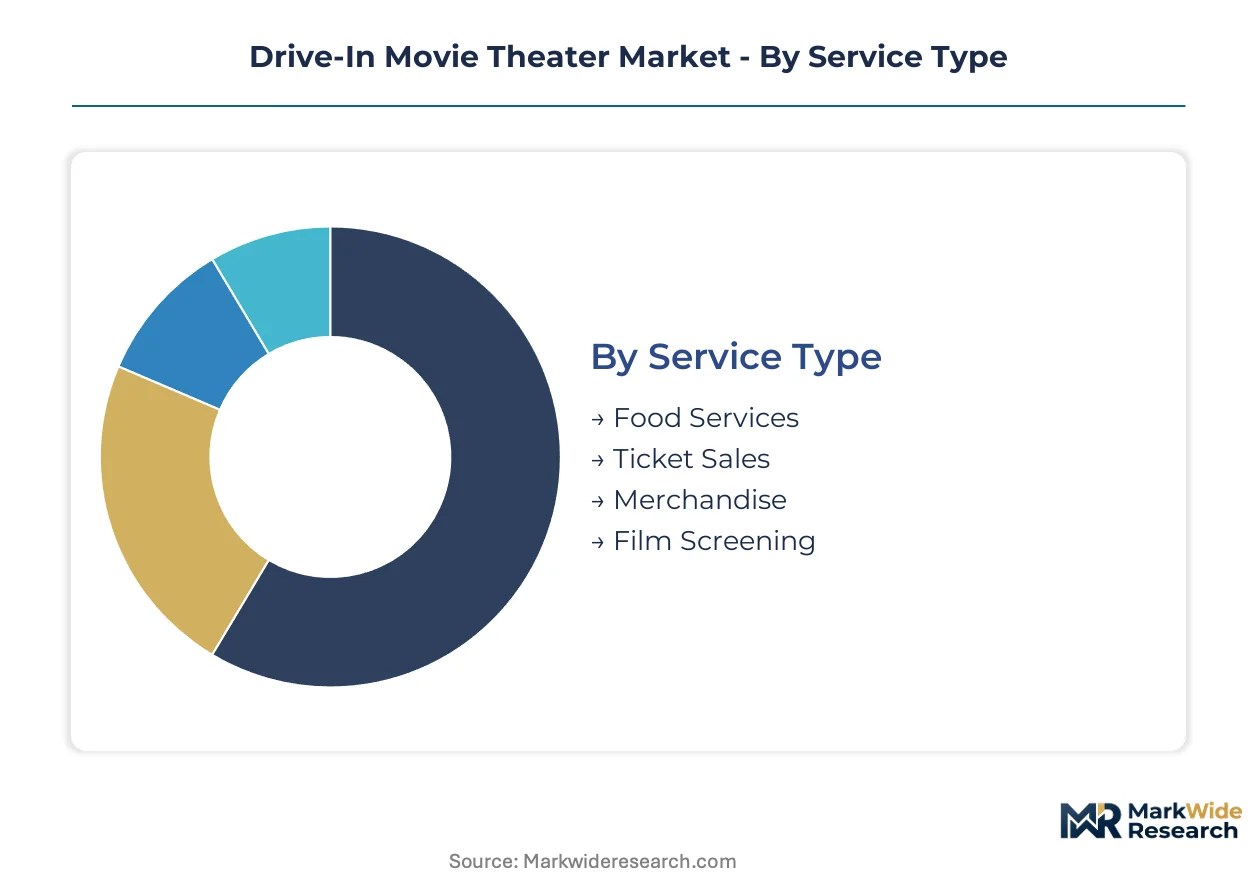
Drive-in theater economics vary sharply by revenue stream composition and patron composition, with food service margins and family attendance patterns determining site-level profitability. Technology deployment decisions further stratify capital requirements and operational flexibility across venue tiers.
Service Type:
Food services turn inventory fastest with perishable supply cycles measured in days, while merchandise rotates slowest with seasonal design lead times stretching across quarters.
- Food Services:Concession operations center on prepared items, packaged snacks, and beverage service delivered through walk-up stands or mobile ordering platforms. Demand concentrates in Texas and Florida markets where extended operating seasons maximize throughput volume against fixed kitchen infrastructure costs.
- Ticket Sales:Admission revenue derives from per-vehicle or per-person pricing structures with variable rates for double features and special events. Pennsylvania and Ohio venues anchor volume through heritage programming and community partnerships that stabilize base attendance.
- Merchandise:Branded apparel, collectible items, and licensed film products generate ancillary revenue with lower labor intensity than food operations.
- Film Screening:First-run theatrical releases, classic film revivals, and alternative content programming constitute the core experiential offering driving visit frequency.
Food services anchors the volume base while film screening gains share at the steepest rate through alternative content expansion.
Technology:
Cost tier stratification separates capital-intensive projection infrastructure from lower-barrier audio and streaming deployments.
- Digital Projection:Large-format outdoor cinema systems utilizing DLP or laser phosphor light engines with brightness ratings exceeding 30,000 lumens for ambient light tolerance. California operators concentrate demand due to year-round programming viability that amortizes equipment costs across more operating days.
- Audio Transmission:FM radio frequency broadcasting and emerging Bluetooth smartphone pairing deliver synchronized sound to vehicle audio systems. Midwestern venues in Indiana and Michigan favor this technology for rapid deployment at temporary and seasonal sites.
- Screen Size:Surface dimensions ranging from 40-foot backyard installations to 100-foot commercial screens determine sightline geometry and maximum vehicle capacity.
- Streaming Services:Cloud-based content distribution enables same-day programming flexibility for corporate events and non-theatrical content.
Digital projection commands the highest capital allocation while streaming services expands most quickly as a share of technology investment.
Customer Type:
Application patterns distinguish routine entertainment consumption from occasion-driven and enthusiast segments with divergent price sensitivity.
- Families:Multi-generational groups seeking G and PG-rated programming with early showtimes and value-oriented concession bundles. Georgia and North Carolina markets concentrate demand where suburban population density supports consistent weekend attendance.
- Couples:Adult pairs targeting date-night experiences with premium parking positions and alcohol-permitted sections where local licensing allows.
- Film Enthusiasts:Cinephile segments seeking classic film revivals, director retrospectives, and limited-release independent content.
- Kids:Child-focused attendance driven by animated features, character events, and birthday party programming.
Families anchor the volume base while film enthusiasts gains share at the steepest rate through specialty programming expansion.
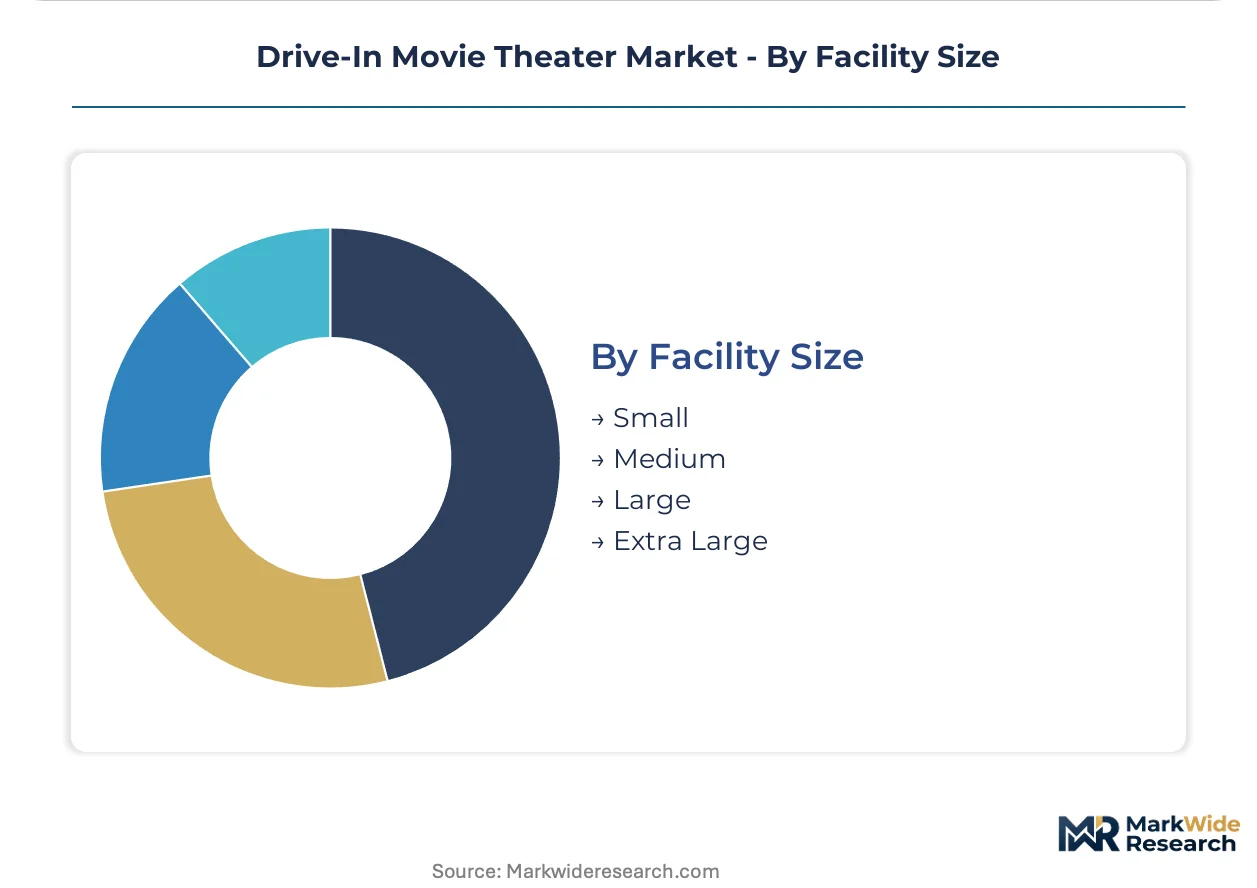
Facility Size:
Site economics scale non-linearly with acreage, as larger venues achieve labor and infrastructure efficiencies that smaller operations cannot replicate.
- Small:Single-screen operations on five to seven acres with capacity for 100 to 200 vehicles, typical of rural markets and pop-up installations.
- Medium:Dual-screen configurations on eight to twelve acres serving 250 to 400 vehicles with separated audio zones.
- Large:Three to four screen complexes on fifteen to twenty-five acres accommodating 500 to 800 vehicles with centralized concession infrastructure.
- Extra Large:Multi-screen entertainment destinations exceeding thirty acres with capacity for 1,000-plus vehicles, often incorporating playground equipment, mini-golf, or secondary attractions.
Medium facilities anchor the volume base while extra large venues gains share at the steepest rate through destination entertainment positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas operators capture pricing premiums through year-round programming calendars, while Pennsylvania venues compress seasonal revenue into compressed operating windows. This geographic asymmetry concentrates investment flows toward sunbelt states with extended viability.
United States
Southern and midwestern states anchor domestic demand through favorable seasonal economics and municipal zoning reforms. The Federal Communications Commission governs FM radio transmission frequencies for audio delivery to parked vehicles. Texas leads screen expansion with Austin and Dallas-Fort Worth metro clusters driving pop-up event proliferation.
Germany
Heritage cinema culture and automotive-centric entertainment sustain niche demand in Bavaria and North Rhine-Westphalia. The country's national media regulator oversees broadcast licensing for outdoor audio transmission systems. Munich and Cologne anchor the limited screen infrastructure with seasonal operations concentrated in summer months.
United Kingdom
Temporary installations at retail parks and fairgrounds dominate as permanent site development faces land scarcity constraints. Local planning authorities regulate outdoor entertainment venue permits through conditional use frameworks. Greater London and Birmingham metropolitan areas concentrate pop-up event activity with corporate programming driving weekday utilization.
Australia
Extended summer operating seasons and automotive culture support sustained demand in Queensland and New South Wales. The Australian Communications and Media Authority manages spectrum allocation for drive-in audio systems. Sydney and Brisbane coastal corridors anchor the surviving permanent screen infrastructure with beach-adjacent venues commanding attendance premiums.
Canada
Compressed seasonal windows limit permanent site economics to southern Ontario and British Columbia valleys. Environment and Climate Change Canada oversees stormwater management for large paved entertainment surfaces. Toronto and Vancouver metropolitan areas concentrate temporary installations with agricultural fairgrounds repurposed for summer cinema programming.
Drive-In Movie Theater Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with projection and audio equipment. The market structure tilts toward regional fragmentation as asset-light leasing reduces capital barriers for new entrants. Three archetypes dominate: multi-state circuit operators, heritage single-site venues, and pop-up event producers. Competitive moves concentrate on geographic expansion through temporary installations and technology partnerships for digital distribution.
Among United States-based circuit operators, West Wind Drive-Ins and Malco Theatres occupy positions spanning multiple state jurisdictions. Shankweiler's Drive-In Theatre represents the heritage archetype with sustained single-market presence. These three entities exemplify the strategic segmentation between scale-driven multi-site programming and localized community anchoring.
| Leading Market Players |
|---|
| West Wind Drive-Ins |
| Shankweiler's Drive-In Theatre |
| Van Buren Drive-In Theatre |
| Bengies Drive-In Theatre |
| Galaxy Drive-In Theatre |
| Malco Theatres |
| Alamo Drafthouse Cinema |
| Delsea Drive-In |
| Holiday Twin Drive-In |
| Others |
Supply & Pricing Matrix
Single-source dependency on three digital projection manufacturers compresses both equipment leasing spreads and regional operator margin structures, forcing exhibitors toward asset-light leasing arrangements that reshape procurement priorities across the value chain.
Pricing Analysis
Family-oriented weekend buyers anchor per-vehicle admission pricing with concession bundle anchoring, while corporate event procurement commands premium venue buyout rates. Three-tier pricing structure across premium, standard, and economy levels separates reserved parking positions from general admission from off-peak weekday slots. Price differentiation rests on seasonal timing and audio technology deployment, with Bluetooth-enabled pop-up venues undercutting permanent FM infrastructure sites. Cost compression in standard-tier admissions is intensifying because streaming substitution erodes off-peak theatrical exclusivity, making family segments most price-sensitive while corporate planners show least sensitivity.
Supply Chain Analysis
Upstream laser phosphor light engines and DLP chipsets draw from concentrated manufacturing bases in the United States, Japan, and Taiwan. Large-format outdoor screens hinge on coated vinyl substrates and steel truss systems sourced from China and South Korea. Single-source vulnerability sits with Texas Instruments' DLP chip monopoly, while distribution runs through national cinema equipment lessors and regional AV integrators serving exhibitor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth audio convergence and municipal zoning liberalization together constitute a regulatory-technological inflection that accelerates venue deployment velocity beyond legacy infrastructure constraints.
For Market Incumbents: Build regulatory capture moats through early engagement with Ohio and California planning commissions on conditional use permit standardization. Secure multi-year digital projection leasing lock-ins before equipment manufacturer consolidation tightens terms. Streaming substitution and pop-up event producers erode attendance base; vertical integration into cloud-based content distribution hedges against theatrical window compression.
For New Entrants and Emerging Players: Build out temporary installation capabilities at underutilized retail parking assets in Indiana and Michigan agricultural zones. Midwestern zoning tailwinds create the most penetrable geography, while corporate event programming offers highest-margin white-space with technology sector procurement officers as entry point.
For Investors and Strategic Acquirers: FCC frequency allocation stability through 2030 reshapes the acquisition landscape toward permanent FM infrastructure plays over Bluetooth-dependent pop-ups. Long-term viability favors heritage-branded single-site venues with community programming anchoring in Pennsylvania and Ohio markets. Watch EPA stormwater enforcement intensity in Texas as signal for construction timeline risk escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth Audio Deployment | Reduces FCC licensing friction and enables rapid pop-up venue activation at non-traditional sites. |
| Municipal Zoning Engagement | Streamlines conditional use permits in Ohio and California markets with favorable entertainment tax structures. |
| Corporate Event Programming | Captures B2B revenue exceeding forty percent of non-weekend volume in Austin and Bay Area corridors. |
| Cloud Content Distribution | Virtualizes film delivery logistics and enables same-day alternative content scheduling flexibility. |
| Permeable Paving Pilots | Addresses EPA stormwater retention mandates and accelerates site approval timelines in Texas jurisdictions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drive-in theater owners, municipal planning commissioners, digital projection equipment lessors, and corporate event procurement managers. Secondary validation drew from FCC frequency allocation databases, EPA stormwater permitting records, municipal zoning ordinance filings, and National Association of Theatre Owners exhibition statistics. Bottom-up venue count modeling and top-down revenue aggregation were triangulated against regional operating day estimates.
Calibration against historical screen deployment patterns and seasonal attendance volatility informed projections across the analysis window. Segmentation dimensions encompassed service type, technology deployment, customer archetype, and facility scale. CAGRs were derived from equipment leasing cost trajectories and alternative content revenue mix assumptions, with municipal entertainment tax reform timelines and EPA enforcement intensity as scenario-weighting inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by streaming platform original content producers would shift outcomes beyond modeled theatrical window compression. Cross-checking against National Association of Theatre Owners quarterly exhibition surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Tripod Dolly Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
Cinema Camera Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Movie Tickets Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Camera Jib Market
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Movies and Entertainment Market