
 Cinema Camera Market | 2026-2036
Cinema Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Cinema Camera Market Analysis
Japanese sensor fabrication capacity is expanding to meet the specialized image sensor requirements of cinema camera manufacturers. ARRI leverages its Munich engineering base to sustain dominance in large-format digital cinematography for premium theatrical releases. Sony Group Corporation anchors supply of CMOS image sensors to multiple camera brands while competing directly through its own cinema line. Canon Inc. differentiates through dual-pixel autofocus technology and controls a significant share of broadcast-cinema crossover applications.
A cinema camera is a professional motion picture acquisition device engineered to capture high-resolution video with wide dynamic range, typically recording RAW or log-encoded footage at 4K resolution or higher for post-production color grading flexibility. These systems employ Super 35mm or full-frame sensors with specialized color science to serve theatrical exhibition, streaming original content, and commercial production workflows. Mirrorless cinema cameras represent the fastest-growing product type as independent filmmakers and content creators prioritize compact form factors without sacrificing image quality. 8K technology adoption remains concentrated among studio productions and high-end commercial work where future-proofing acquisition masters justifies premium hardware investment. Wireless connectivity features are reshaping on-set workflows by enabling remote monitoring and camera control across multi-unit productions.
The Federal Communications Commission governs wireless transmission frequencies used in on-camera video assist systems, while the EPA oversees hazardous substance restrictions in battery and electronic component manufacturing. Compliance with ISO 9001 quality management and IEC 62368-1 safety standards shapes product certification requirements for international market access. Stakeholders must monitor the divergence between regional content quota regulations and sensor export control frameworks as both will influence production equipment procurement patterns and manufacturing location decisions.
Market Dynamics
The transition from HD to 4K and 8K acquisition standards is compressing equipment refresh cycles across production houses and forcing capital redeployment toward sensor-forward platforms with extended color latitude.
Growth Catalysts
- Streaming Original Production:Netflix, Amazon Prime Video, and Disney+ have expanded proprietary content budgets, driving procurement of professional camera systems capable of theatrical-grade capture for simultaneous platform and cinema release.
- EU Green Deal:The European Commission's circular electronics mandates are accelerating rental-house fleet modernization as older HD equipment faces accelerated depreciation against sustainability reporting requirements.
- Computational Imaging:Machine learning-based noise reduction and real-time debayering are extending usable ISO ranges, enabling location shooting under constrained lighting without supplemental grip equipment.
Market Restraints
- Specialized CMOS Sensor Concentration:Japanese foundry capacity for large-format cinema sensors remains concentrated among three primary suppliers, creating allocation risk during semiconductor demand spikes.
- RoHS Compliance Costs:The EU's restriction of hazardous substances in electronics manufacturing forces redesign of battery management systems and solder compositions, adding certification overhead to product development cycles.
- Smartphone Computational Video:Apple's ProRes Log output and Samsung's 8K mobile capture are displacing entry-level cinema camera volume in independent documentary and commercial segments.
Strategic Opportunities
- India Production Incentives:The Indian government's audiovisual co-production treaties and 30% cash rebate schemes for foreign shoots are expanding rental demand in Mumbai and Hyderabad production corridors.
- Virtual Production Volumes:LED wall-based in-camera visual effects are creating demand for genlock-synchronized camera arrays and specialized lens metadata protocols for real-time compositing.
- Remote Telemetry Integration:Wireless camera control and cloud-based dailies review are enabling multi-unit production models that reduce on-set headcount and accelerate post-production handoff.
Industry Challenges
- Digital Imaging Technician Shortage:The specialized skill set combining color science, LUT management, and on-set data wrangling faces supply constraints as production volume outpaces training program throughput.
- Multi-Standard Certification:Simultaneous compliance with FCC Part 15 for wireless video transmission, IEC 62368-1 for safety, and regional content quota frameworks extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cinema Camera Market |
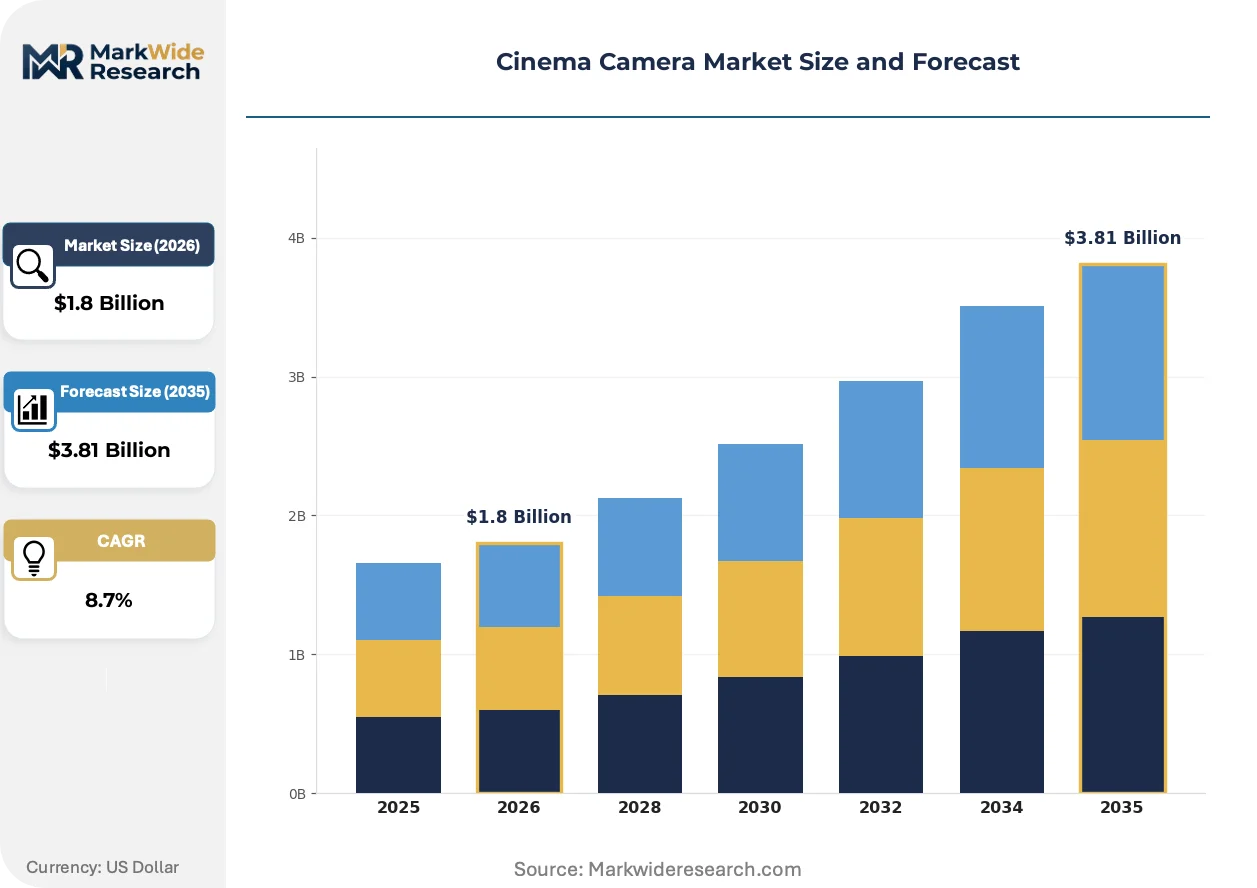
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DSLR, Mirrorless, Camcorder, Action Camera Technology: 4K, 8K, HDR, Low-Light End User: Independent Filmmakers, Studios, Broadcasters, Content Creators Feature: Wireless Connectivity, Image Stabilization, High Frame Rate, Modular Design |
| Companies Covered | ARRI, Sony Group Corporation, Canon Inc., RED Digital Cinema, Blackmagic Design, Panasonic Corporation, Nikon Corporation, JVC, Kinefinity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cinema Camera Market Emerging Trajectories
Sensor architecture and on-set connectivity protocols are converging to compress the distance between acquisition and post-production, eliminating traditional dailies bottlenecks.
Global Shutter CMOS technology is integrating into high-end cinema bodies to eliminate rolling shutter artifacts during rapid camera movement and strobe lighting conditions. Action unit cinematographers on commercial and music video shoots are adopting these sensors for whip pans and vehicle-mounted sequences. The technology is integrating with stabilized gimbal systems to reduce post-stabilization requirements and preserve full resolution.
The EU's Corporate Sustainability Reporting Directive now mandates supply chain disclosure for electronics manufacturers selling into member states. Camera OEMs must document carbon intensity across sensor fabrication, magnesium chassis machining, and lithium battery cell sourcing. European rental houses are responding by prioritizing fleet purchases from vendors with verified lifecycle assessments and modular repair architectures.
Production companies are consolidating equipment procurement through subscription-based fleet management services rather than capital purchase or traditional rental. This model transfers sensor obsolescence risk to lessors and enables rapid format migration from 4K to 8K acquisition. The shift is most pronounced among mid-tier commercial producers in Los Angeles and London who face irregular project pipelines and prefer operational expenditure classification.
Cinema Camera Market Segmentation
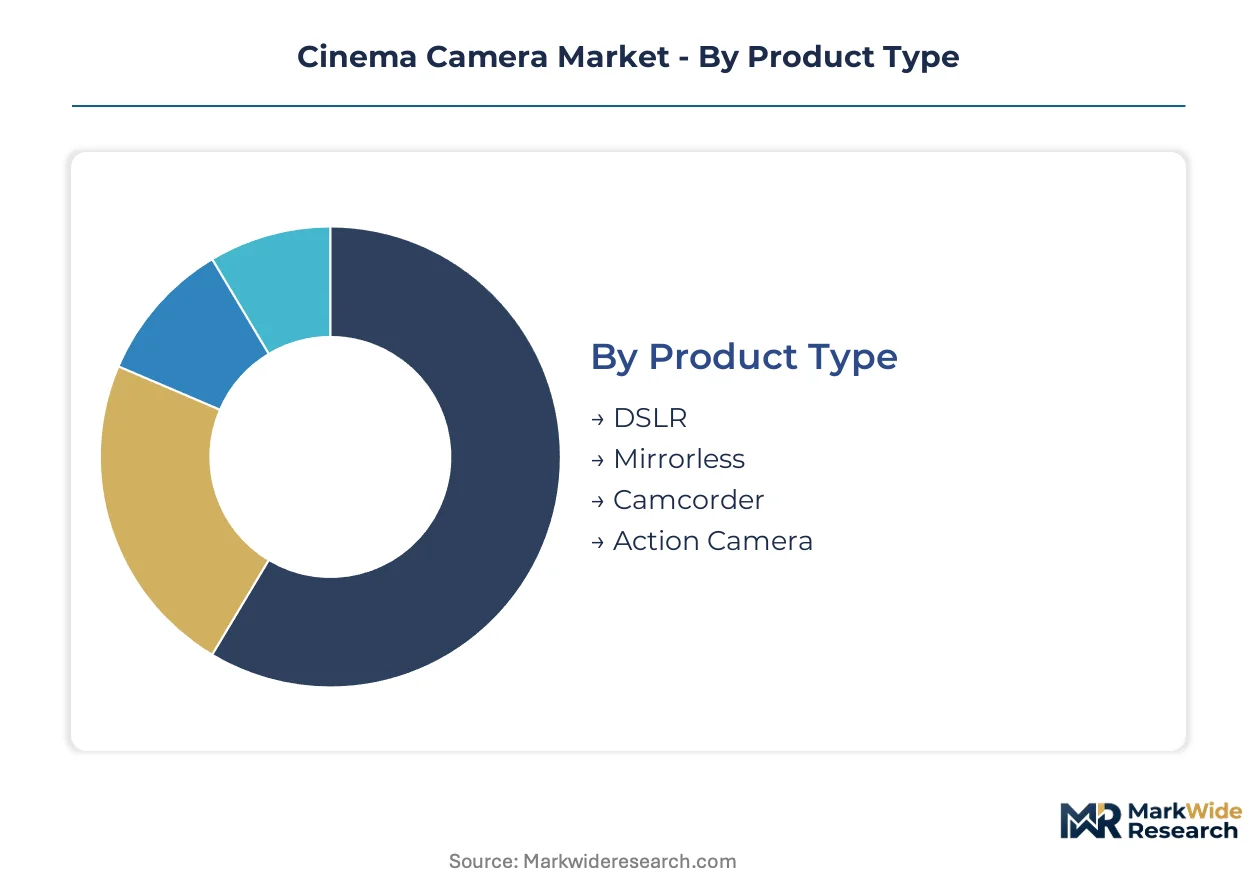
Cinema camera procurement decisions hinge on format compatibility, post-production latitude, and crew mobility requirements. Production houses segment their fleet investments across resolution tiers and connectivity specifications to match project scale and delivery platform mandates.
Product Type:
Form factor determines rental house fleet composition and owner-operator purchase patterns.
- DSLR:Full-frame sensors in compact bodies serve documentary units requiring shallow depth-of-field on tight location schedules. Demand concentrates among independent filmmakers in Mumbai and Lagos where owner-operators prioritize multi-use stills-video capability.
- Mirrorless:Compact bodies with full-frame or Super 35 sensors and native lens ecosystems dominate independent production and commercial work. Content creators across Los Angeles, London, and Seoul drive procurement as hybrid shooting expands.
- Camcorder:Integrated zoom lenses and broadcast-ready codecs serve ENG workflows and reality television production.
- Action Camera:Ruggedized, ultra-compact units capture POV and stunt sequences for action units and sports cinematography.
Mirrorless leads on scale; Mirrorless also leads on momentum.
Technology:
Resolution and dynamic range specifications drive equipment refresh cycles across production tiers.
- 4K:The baseline acquisition standard for streaming original content and commercial production. Studios in Burbank and Pinewood mandate 4K minimum for all original series, compressing HD fleet retirement timelines.
- 8K:Full-frame and large-format sensors capture at 8192×4320 for theatrical exhibition and future-proofed masters. Premium productions in Tokyo and Sydney deploy 8K for VFX-heavy features where reframing flexibility justifies storage overhead.
- HDR:Wide dynamic range capture preserves highlight and shadow detail for HDR10+ and Dolby Vision delivery pipelines.
- Low-Light:Dual-native ISO architectures extend shooting into practical-lit environments without supplemental grip.
4K leads on scale; 8K leads on momentum.
End User:
Production entity type determines capital deployment models and feature prioritization.
- Independent Filmmakers:Owner-operators purchasing single-camera systems prioritize price-performance balance and lens ecosystem breadth. Crowdfunding-backed productions across Berlin and São Paulo favor mirrorless bodies for festival-qualifying features.
- Studios:Major theatrical producers in Culver City and Borehamwood mandate ARRI and RED large-format systems for simultaneous cinema and streaming release. Fleet procurement runs through long-term rental partnerships with Panavision and ARRI Rental.
- Broadcasters:Network-affiliated production units require ENG-form factor cameras with integrated transmission and metadata compliance.
- Content Creators:YouTube and TikTok-native producers drive compact cinema camera volume for branded content and documentary series.
Studios lead on scale; Content Creators lead on momentum.
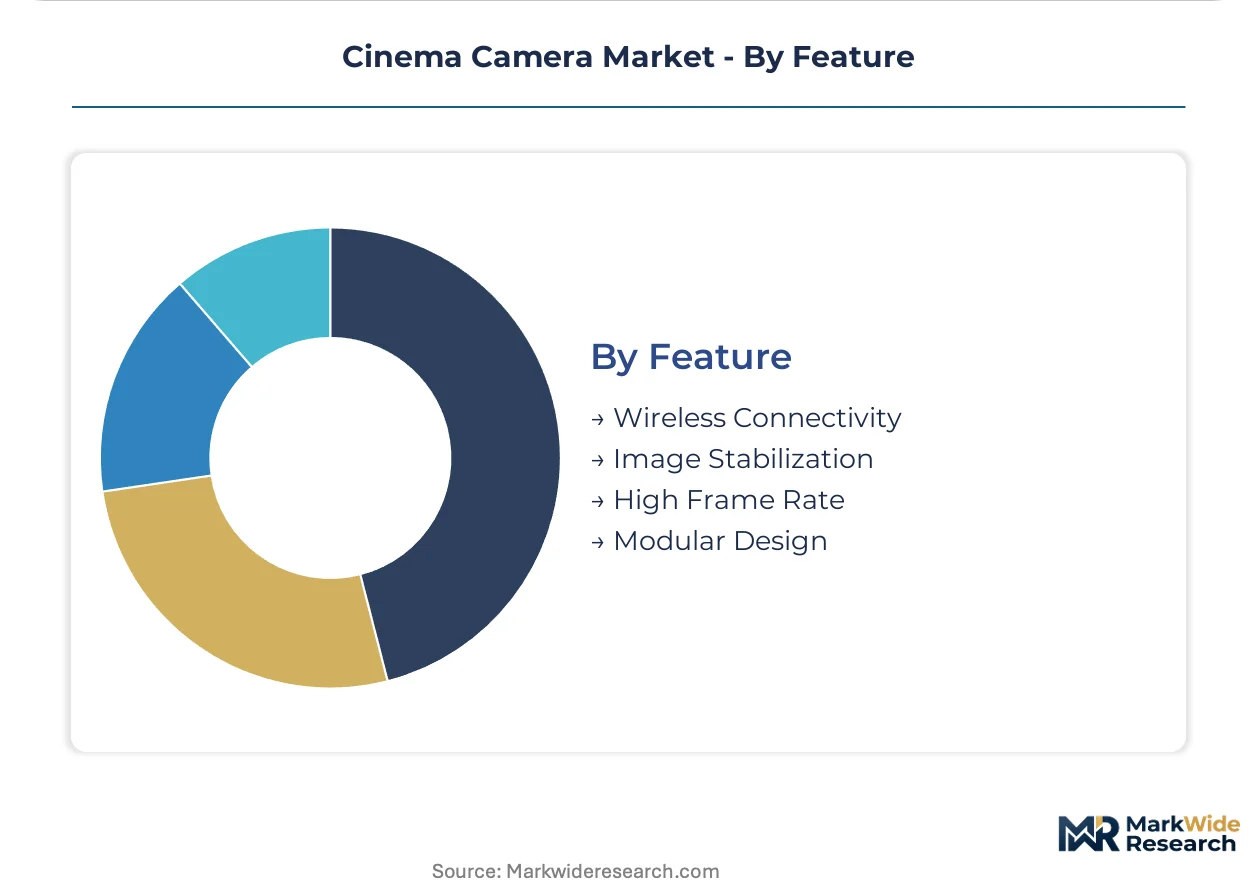
Feature:
On-set workflow integration shapes feature prioritization across production categories.
- Wireless Connectivity:Integrated Wi-Fi and dedicated video transmission enable remote monitoring and camera control. Multi-unit productions in Atlanta and Vancouver require wireless video assist for director and client viewing.
- Image Stabilization:Sensor-shift and lens-based stabilization reduce gimbal dependency for handheld documentary work.
- High Frame Rate:120fps and 240fps capture supports slow-motion commercial and music video production.
- Modular Design:Swappable sensor blocks and accessory mounts extend platform longevity across format transitions.
Wireless Connectivity leads on scale; Modular Design leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns reflect regulatory-arbitrage dynamics as studios relocate shoots to jurisdictions offering favorable tax incentives and streamlined equipment import protocols. Cost-of-compliance gaps between markets are reshaping fleet deployment strategies among rental houses and production service companies.
United States
Streaming platform headquarters in Los Angeles and Atlanta drive concentrated procurement of large-format systems for simultaneous theatrical and platform release. The FCC governs wireless transmission frequencies for on-camera video assist systems, mandating Part 15 compliance for multi-unit productions. Georgia's film tax credit program has expanded stage infrastructure in the Atlanta metropolitan area, attracting Marvel and Netflix original series that deploy ARRI and RED camera packages.
Germany
Bavaria's studio complexes and Cologne's commercial production sector sustain demand for broadcast-cinema crossover equipment. The EU Green Deal's circular electronics mandates accelerate rental-house fleet modernization as older HD equipment faces accelerated depreciation. Munich anchors ARRI's engineering operations, sustaining regional dominance in large-format digital cinematography for premium theatrical releases across European co-productions.
Japan
Domestic broadcasters and anime-live-action hybrid productions drive specialized sensor requirements. METI oversees industrial standards for imaging equipment while export control frameworks shape sensor fabrication capacity allocation. Tokyo and Osaka production corridors concentrate CMOS image sensor foundry operations, with Sony Group Corporation anchoring supply to multiple camera brands while competing through its own cinema line.
India
Bollywood's expansion into streaming originals and international co-productions is expanding rental demand in Mumbai and Hyderabad. The government's audiovisual co-production treaties and 30% cash rebate schemes for foreign shoots are attracting Amazon and Netflix productions. Maharashtra and Telangana production corridors are consolidating grip and camera rental infrastructure to serve incoming international productions requiring 4K and 8K acquisition packages.
United Kingdom
Pinewood and Shepperton studios anchor theatrical production volumes for major franchise features. The British Film Institute's certification requirements for high-end television tax relief mandate minimum production spend thresholds that favor professional camera system procurement. London's post-production ecosystem is integrating with on-set virtual production volumes, creating demand for genlock-synchronized camera arrays and specialized lens metadata protocols.
Cinema Camera Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue computational imaging and subscription-based fleet services. The vendor base stratifies across three tiers: heritage Munich and Tokyo engineering houses controlling premium theatrical; Japanese and Korean electronics conglomerates dominating sensor supply and mid-range volume; and Chinese and Australian challengers capturing independent and commercial segments. Three strategic archetypes define positioning: sensor-forward platform specialists, broadcast-cinema crossover generalists, and virtual production workflow integrators. Competitive intensity centers on M&A for lens metadata technology and strategic partnerships with LED volume stage operators.
Within the heritage engineering tier, ARRI and RED Digital Cinema exemplify premium positioning through large-format platform specialization. Sony Group Corporation and Canon Inc. occupy the broadcast-cinema crossover space, leveraging CMOS fabrication scale and dual-pixel autofocus differentiation respectively. Blackmagic Design represents the independent production vector with compact form-factor prioritization.
| Leading Market Players |
|---|
| ARRI |
| Sony Group Corporation |
| Canon Inc. |
| RED Digital Cinema |
| Blackmagic Design |
| Panasonic Corporation |
| Nikon Corporation |
| JVC |
| Kinefinity |
| Others |
Supply Flow & Price Mechanics
8K acquisition pipelines and computational imaging workflows are simultaneously inflating R&D amortization burdens and concentrating procurement leverage among sensor-forward OEMs with captive foundry relationships. This technology transition compresses margin recovery timelines for rental houses while rewarding vertically integrated manufacturers with cost visibility across CMOS fabrication and lens assembly.
Pricing Analysis
Distributor margins on cinema camera bodies compress as direct-to-production-house subscription fleets bypass traditional rental intermediaries. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor size and RAW codec latitude, with ARRI and RED commanding brand premiums for large-format theatrical certification. Price erosion runs through the independent filmmaker tier where Blackmagic and Kinefinity undercut on per-unit acquisition cost. Content creators exhibit highest price sensitivity, while studio production units prioritize total cost of ownership including lens ecosystem lock-in.
Supply Chain Analysis
Specialized cleanroom technician availability in Japan and South Korea constrains CMOS sensor foundry expansion despite capital equipment installation. Sensor fabrication draws from silicon wafer supply anchored in Taiwan and Japan, with rare earth elements for optical coatings sourced from China and Australia. Single-source vulnerability concentrates in large-format sensor lithography equipment held by Dutch and Japanese vendors. Distribution runs through authorized rental houses in Los Angeles, London, and Mumbai, with direct OEM sales penetrating studio and broadcast accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Production migration toward India and Southeast Asia creates geographic-arbitrage opportunities as 30% cash rebates in Maharashtra undercut European co-production incentives by double-digit percentage points on comparable spend thresholds.
For Market Incumbents: Cement sensor-foundry partnerships in Japan and South Korea to secure allocation priority during semiconductor demand spikes. Lock in multi-year lens metadata licensing agreements with LED volume stage operators to defend against Chinese challengers integrating virtual production workflows. Prioritize modular platform architectures that extend fleet longevity across 4K-to-8K transitions. For New Entrants and Emerging Players: The gap between RED Komodo-tier pricing and Blackmagic Pocket tier pricing offers white-space entry for full-frame RAW-capable bodies under $4,000. Target Mumbai and São Paulo owner-operator segments where crowdfunding-backed features prioritize festival-qualifying image quality over rental infrastructure. Pursue direct-to-creator subscription bundling with cloud dailies platforms to bypass established rental house channel control. For Investors and Strategic Acquirers: Valuations sit cheapest among broadcast-cinema crossover specialists with stagnant theatrical attach rates but growing streaming original volume. Five-to-ten-year viability hinges on computational imaging IP portfolios and virtual production integration depth. Monitor LED volume stage deployment velocity as inflection indicator for genlock-synchronized camera array demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Foundry Capacity Expansion | Captive supply of large-format CMOS from Sony and Canon foundries secures allocation priority during demand spikes. |
| Virtual Production Workflow Integration | Genlock synchronization and lens metadata protocols position vendors for LED volume stage procurement in Atlanta and London. |
| Subscription Fleet Management Launch | Operational expenditure classification attracts mid-tier commercial producers with irregular project pipelines in Los Angeles. |
| Computational Imaging R&D Partnership | Machine learning noise reduction extends usable ISO ranges for location shooting under constrained lighting conditions. |
| Regional Certification Fast-Track | Simultaneous FCC Part 15 and CE marking compliance compresses product launch timelines by 8-14 months for multi-market release. |
Methodological Framework
Multiple input streams — rental house fleet managers, cinematographers and DITs, post-production facility engineers, and OEM product strategy leads — were reconciled against trade customs data, FCC equipment authorization filings, and SEC 10-K segment disclosures. Primary fieldwork captured procurement decision criteria across production tiers in Los Angeles, London, Mumbai, and Tokyo. Secondary validation drew from IHS Markit production volume databases, BFI tax relief certification records, and EU CSRD supply chain disclosure filings. Bottom-up unit economics and top-down market sizing were triangulated to anchor volume projections.
Historical shipment trajectories were cross-referenced against panel input from camera rental consortiums and streaming platform production executives. Segmentation modeling spanned product type, resolution tier, end-user category, and regional production incentive framework across the analysis window. CAGRs were derived from equipment refresh cycle compression rates and streaming original content budget growth curves. Forecast inputs included sensor foundry capacity expansion schedules and virtual production stage deployment pipelines.
Caveats apply where semiconductor allocation shocks, regulatory divergence in content quota frameworks, or smartphone computational video displacement could materially shift the outlook. Forecasts embed assumptions on streaming platform original production commitment durability and theatrical exhibition recovery velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
Camera Jib Market
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
North America Animation, VFX and Post Production Market