
 Global Advanced Cinema Projector Market | 2026-2036
Global Advanced Cinema Projector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Cinema Projector Market Intelligence
The EU's Ecodesign Directive, combined with RoHS restrictions on hazardous substances, is realigning the competitive landscape by increasing R&D costs for energy-efficient and compliant designs. Barco leverages its deep focus on high-brightness laser solutions to serve the premium multiplex segment. Christie differentiates through its integrated media block and projection systems for large-format screens. Meanwhile, Sony competes by offering 4K LCoS technology for both cinema and high-end private theater applications.
An advanced cinema projector is a high-lumen digital projection system designed for large-screen theatrical exhibition, typically exceeding 20,000 lumens and offering 4K resolution. Its primary purpose is to deliver high-fidelity, color-accurate motion pictures compliant with Digital Cinema Initiatives (DCI) standards. Laser projection technology now dominates new installations over legacy lamp-based systems due to its longer lifespan and superior brightness. While multiplexes constitute the largest application area, the private theater segment offers a high-growth opportunity for specialized vendors.
Compliance with Digital Cinema Initiatives (DCI) specifications is a mandatory requirement for theatrical distribution, setting a high bar for performance and security. Furthermore, energy efficiency standards like the EU's Ecodesign and safety certifications such as CE marking in Europe and FCC in the United States govern market access. The critical decision for cinema chains now revolves around balancing the high initial capital outlay for laser projectors against their long-term total cost of ownership benefits.
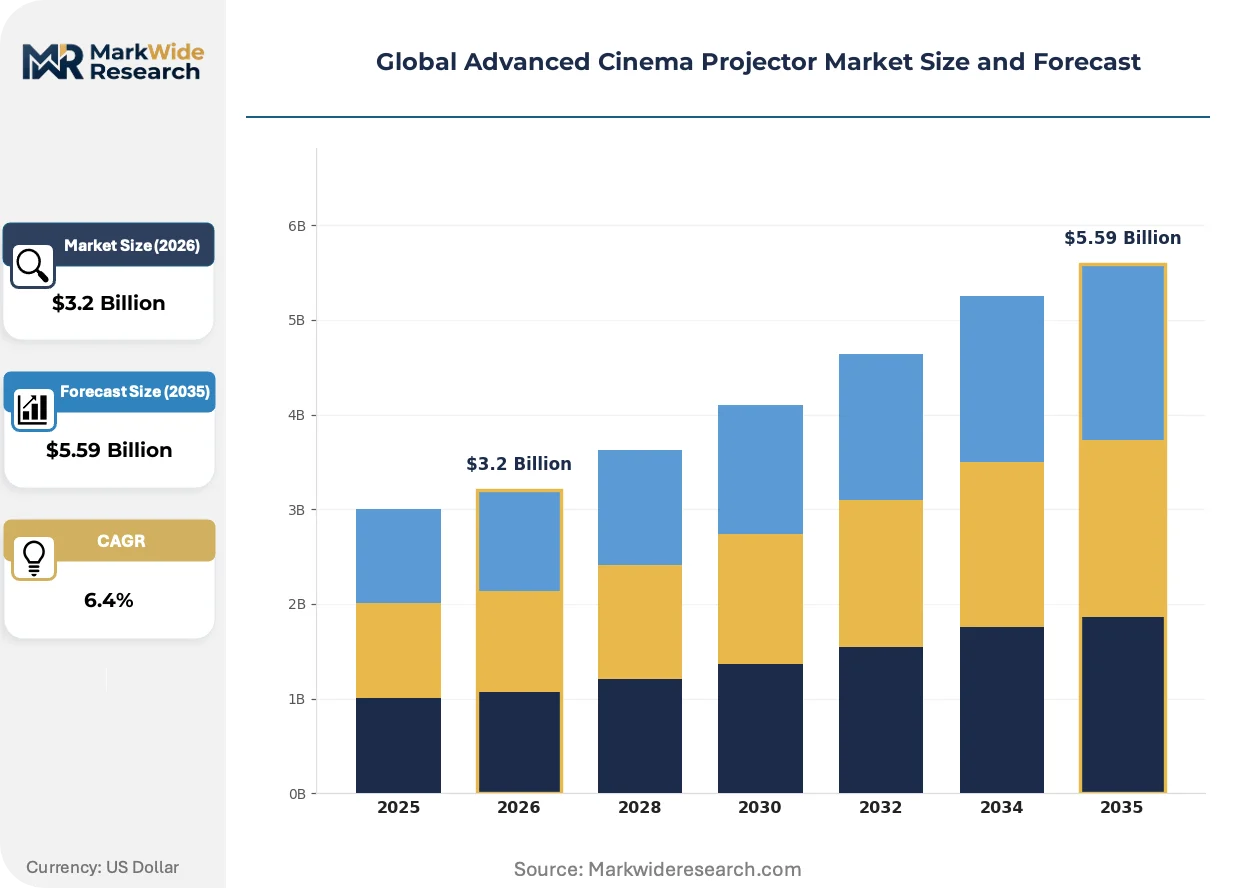
Market Dynamics
The central tension defining the advanced cinema projector market is the financial trade-off between the high initial capital expenditure for laser-based systems and their compelling long-term total cost of ownership. This calculation is forcing cinema operators to re-evaluate fleet modernization schedules and vendor financing models.
Growth Catalysts
- Laser Technology Adoption:The transition from lamp to laser light sources provides superior brightness, longer operational life, and reduced maintenance, creating a strong value proposition for multiplex operators focused on lowering operational expenditures and enhancing visual quality.
- Entertainment Venue Diversification:Demand from non-theatrical applications, such as theme parks, museums, and live event venues, is creating new revenue streams for projectors capable of delivering immersive, large-format visual experiences beyond traditional cinema.
- New Screen Construction:Rapid and large-scale construction of new cinema screens, particularly concentrated in China, provides a consistent demand pipeline for DCI-compliant projection systems to equip new multiplexes.
Market Restraints
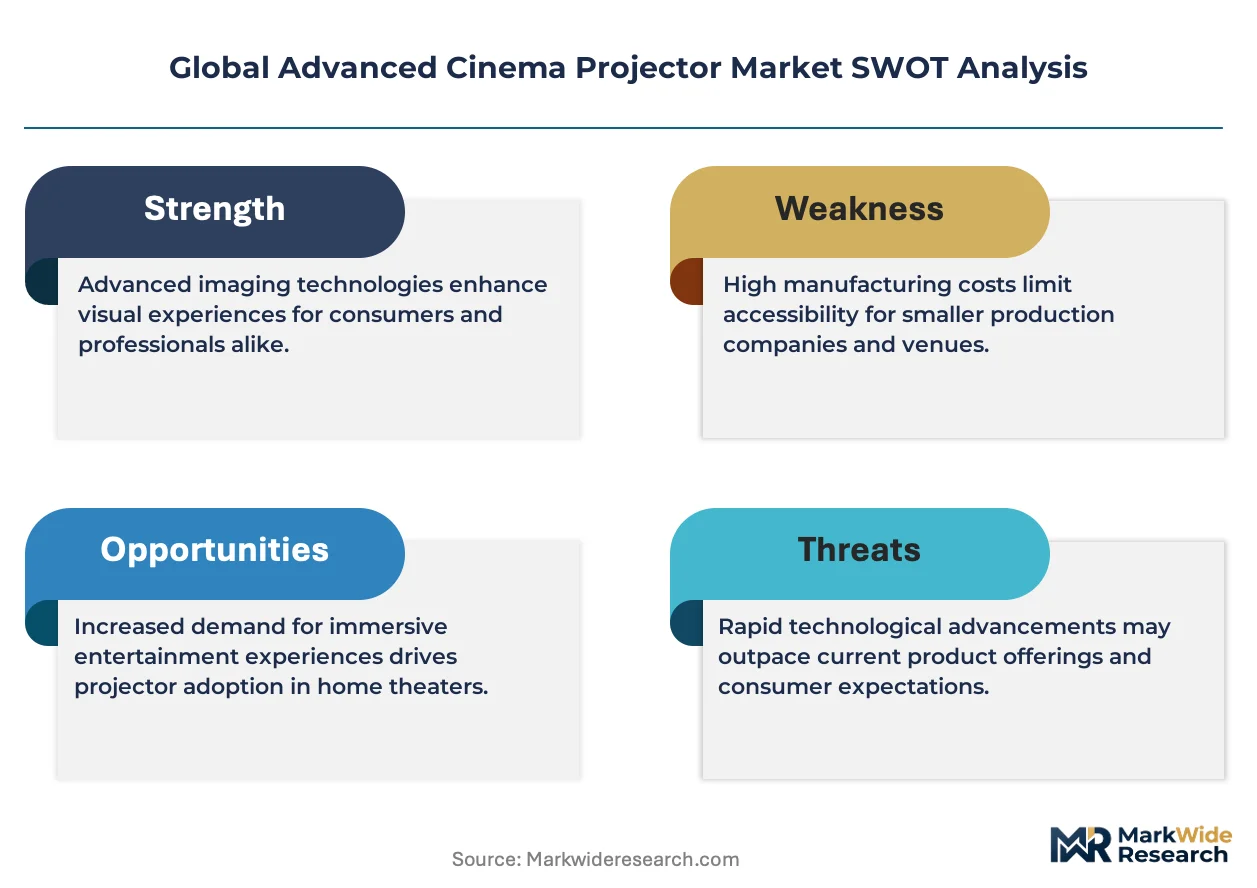
- High Initial Investment:The significant upfront cost of 4K laser projectors remains a substantial barrier to adoption, especially for smaller, independent cinema owners who lack the scale and capital access of large chains.
- Home Entertainment Substitution:The proliferation of high-resolution, large-format consumer televisions and the availability of first-run content on streaming platforms present a persistent substitution threat that can dampen theatrical attendance and subsequent exhibitor investment.
- Regulatory Compliance Costs:Mandates such as the EU's Ecodesign Directive increase research and development expenses for manufacturers, as they must engineer more energy-efficient systems while phasing out restricted components.
Strategic Opportunities
- Private Theater Segment:The high-end residential or private cinema market offers a lucrative niche for specialized vendors to adapt DCI-grade technology for affluent consumers seeking premium, theatrical-quality experiences at home.
- Emerging Market Expansion:Underpenetrated markets across Southeast Asia and Latin America represent a key growth frontier as disposable incomes rise and the modern multiplex footprint expands beyond metropolitan hubs.
- Integrated Solution Bundling:Opportunities exist for manufacturers to bundle projection hardware with integrated media servers, theater management software, and long-term service contracts, creating a more complete and sticky ecosystem for cinema operators.
Industry Challenges
- Legacy System Integration:Ensuring seamless interoperability between new laser projection systems and existing in-theater infrastructure, including audio processors and automation systems, presents a significant technical and logistical challenge for exhibitors.
- DCI Certification Hurdles:The rigorous and time-consuming process of achieving Digital Cinema Initiatives (DCI) compliance for new projector models sets a high performance and security bar, potentially delaying product launches and market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Cinema Projector Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Projection Technology: DLP, LCD, LCoS, Laser, LED Application Area: Multiplexes, Art Houses, Drive-ins, Event Venues, Private Theaters Installation Type: Ceiling Mount, Rear Projection, Front Projection, Portable Setup End User Segment: Film Producers, Distributors, Cinema Chains, Independent Exhibitors, Entertainment Parks |
| Companies Covered | BenQ, JVC, Sony, Digital Projection, Canon, Christie, Epson, Panasonic, Barco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Cinema Projector Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards integrated systems that simplify operations and enhance security. This drive for efficiency is occurring alongside a technological pivot to solid-state illumination, fundamentally changing projector design and performance benchmarks.
Integrated Media Block (IMB) technology combines the image processor and server into a single, secure hardware unit. Multiplex operators are adopting these systems to streamline projection booth workflows and harden security against content piracy. This technology is unifying previously disparate hardware components, reducing equipment footprint and simplifying maintenance for theater technicians.
The EU's Ecodesign Directive, coupled with RoHS restrictions, is accelerating the phase-out of legacy lamp-based projectors containing hazardous materials. This regulatory pressure directly benefits solid-state light sources like laser and RGB pure laser, which offer greater energy efficiency. European cinema exhibitors are most affected, facing a clear mandate to invest in compliant laser technology for new builds and retrofits.
A shift in purchasing behavior sees cinema chains moving away from simple hardware acquisition towards evaluating the total cost of ownership over the projector's lifecycle. This disrupts the traditional transactional sales model, placing greater emphasis on long-term service agreements and light source warranties. This trend is most visible in the competitive North American market, where operational efficiency is a primary driver of profitability.
Global Advanced Cinema Projector Market Segmentation
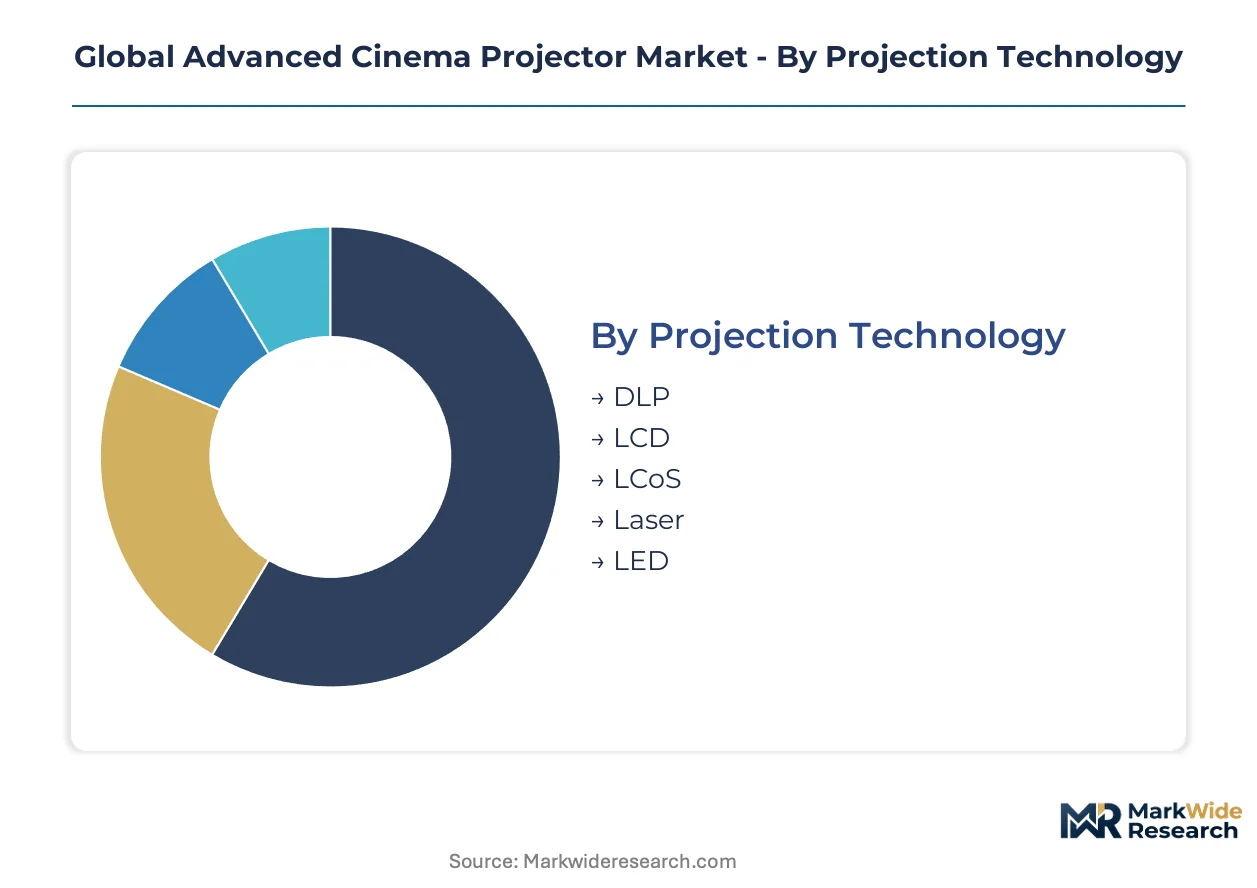
Segmentation of the advanced cinema projector market reveals distinct demand patterns and technological preferences across various user groups. Understanding these segments allows manufacturers to tailor product development and service offerings. This granular view highlights where innovation is most impactful and capital investment is most concentrated.
Projection Technology:
Supply concentration within projection technology largely reflects the established manufacturing capabilities for different illumination and imaging systems.
- Laser:Laser projection systems utilize solid-state light sources, either pure RGB or phosphor-based, to generate light for image display. Demand concentrates in new multiplex installations in China, driven by superior brightness, longer operational life, and reduced maintenance costs compared to traditional lamps.
- DLP:Digital Light Processing (DLP) technology employs millions of microscopic mirrors to project images, offering high contrast and resolution. This technology remains prevalent in existing cinema infrastructure globally, valued for its proven reliability and widespread adoption in theatrical exhibition.
- LCoS:Liquid Crystal on Silicon (LCoS) technology combines LCD and DLP characteristics, offering high resolution and deep black levels for premium applications.
- LCD:Liquid Crystal Display (LCD) projectors use three separate LCD panels to produce vibrant colors, often found in smaller venue or entry-level systems.
- LED:Light Emitting Diode (LED) projectors offer long lifespan and instant on/off capabilities, gaining traction in smaller, specialized projection environments.
DLP technology absorbs the bulk of installed capacity; Laser technology is expanding most quickly.
Application Area:
The distinct functional requirements of various venues shape the demand for advanced cinema projectors across different application areas.
- Multiplexes:These large-scale commercial cinemas feature multiple screens, requiring robust, high-lumen, DCI-compliant projection systems for continuous operation. Demand from new screen construction in China and modernization efforts in North America drives this segment, focusing on operational efficiency and immersive audience experiences.
- Private Theaters:High-end residential or dedicated personal screening rooms require DCI-grade projection adapted for smaller, controlled environments, often emphasizing image fidelity and customization. Affluent consumers seeking premium, theatrical-quality experiences at home drive this niche, creating a high-growth opportunity for specialized vendors.
- Event Venues:These spaces, including theme parks and concert halls, utilize advanced projectors for immersive, large-format visual experiences beyond traditional cinema.
- Art Houses:Independent and specialized cinemas often prioritize image quality and color accuracy for niche film presentations, frequently adopting LCoS or high-end DLP systems.
- Drive-ins:Outdoor cinema venues require exceptionally bright projectors with robust weather protection to deliver clear images under challenging ambient light conditions.
Multiplexes represent the largest volume segment; the private theater segment is gaining share fastest.
Installation Type:
The physical constraints and operational needs of a cinema space dictate the preferred installation type for advanced projectors.
- Ceiling Mount:Projectors are securely suspended from the ceiling, typically above the audience, allowing for optimal throw distance and minimal obstruction in conventional theaters. This standard configuration dominates multiplex installations globally, valued for space efficiency and consistent image alignment in dedicated projection booths.
- Portable Setup:These systems are designed for easy transport and rapid deployment, often featuring integrated media players and simplified alignment for temporary venues. Event venues and pop-up cinemas drive demand for portability, requiring flexible solutions for diverse locations and temporary immersive experiences.
- Front Projection:Projectors are positioned in front of the screen, commonly at floor level or on a stand, offering flexibility for smaller spaces or non-traditional setups.
- Rear Projection:The projector is placed behind the screen, creating a flush, integrated display that saves floor space and eliminates audience shadows.
Ceiling Mount installations account for the majority of new deployments; Portable Setup is experiencing the steepest expansion trajectory.
End User Segment:
The financial capabilities and strategic priorities of different end-user segments influence their investment cycles and technology choices.
- Cinema Chains:Large, multi-location operators require standardized, DCI-compliant, high-lumen projectors with robust network management capabilities for centralized control. Fleet modernization and new screen expansion in emerging markets like China drive significant procurement, prioritizing total cost of ownership and long-term service agreements.
- Entertainment Parks:These venues demand specialized, ultra-bright, often custom-integrated projection systems capable of operating reliably in diverse environmental conditions for immersive attractions. Diversification into non-theatrical applications and the creation of unique visitor experiences propel demand from global theme parks and experiential centers.
- Independent Exhibitors:Smaller, often single-location cinemas face high initial investment barriers, frequently opting for financing models or refurbished equipment to upgrade their systems.
- Film Producers:Producers utilize advanced projectors for post-production, color grading, and private screenings, requiring extreme color accuracy and high resolution for critical viewing.
- Distributors:Content distributors may invest in projectors for quality control, exhibition previews, or to facilitate content delivery logistics to various cinema formats.
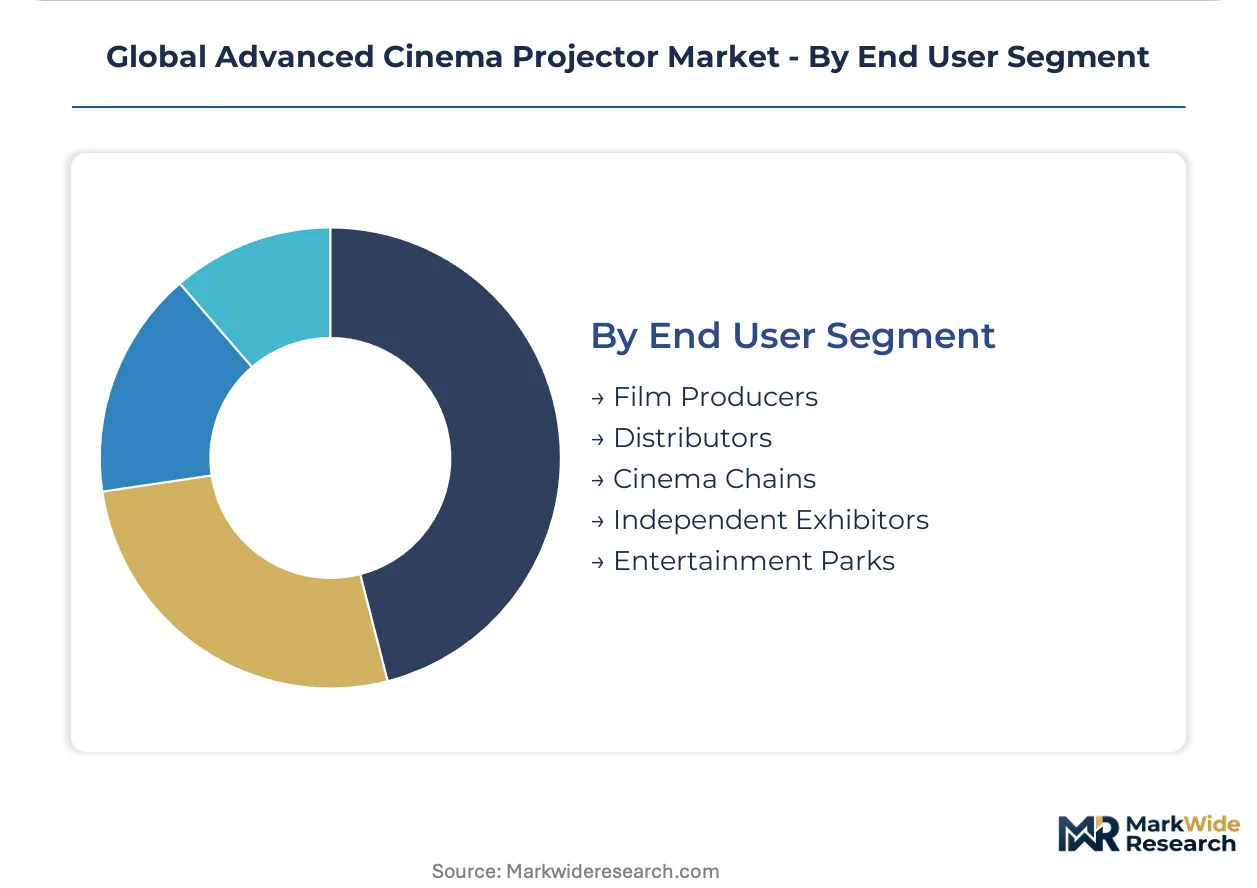
Cinema Chains drive the largest volume of advanced projector sales; Entertainment Parks are climbing the fastest in terms of new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for advanced cinema projectors notably centers on countries investing heavily in new entertainment infrastructure. These markets prioritize immersive audience experiences and operational efficiencies, driving the adoption of advanced projection technologies. Regulatory frameworks and economic incentives further shape regional market dynamics for cinema equipment.
China
New screen construction and multiplex expansion across China drive significant demand for DCI-compliant projection systems. The country's dual carbon goals and GB standards encourage the adoption of energy-efficient laser projectors. Major cities like Beijing and Shanghai continue to anchor substantial investment in modern cinema complexes and entertainment venues.
United States
The United States market sees cinema chains modernizing existing fleets with laser-based systems to enhance visual quality and reduce operational costs. FCC certifications govern market access for electronic equipment, including advanced projectors. Hollywood and Los Angeles remain central to post-production and content creation, influencing technology standards for theatrical exhibition.
Germany
German cinema operators focus on upgrading to energy-efficient laser technology, driven by the EU's Ecodesign Directive and CE marking requirements. This shift supports long-term sustainability goals and operational savings for exhibitors. Major urban centers such as Berlin and Munich exhibit strong demand for premium cinema experiences and art house venues.
India
India's expanding middle class and rapid urbanization fuel the construction of new multiplexes, particularly in Tier 2 and Tier 3 cities. BIS certifications ensure product quality and safety for advanced cinema projectors within the country. Metropolitan areas like Mumbai and Delhi are experiencing significant growth in screen count, requiring DCI-compliant systems.
Japan
Japanese exhibitors prioritize image fidelity and technological innovation, leading to demand for high-resolution LCoS and RGB pure laser systems. METI regulations guide energy efficiency standards for electronic products, impacting projector design and adoption. Tokyo and Osaka serve as key hubs for cinema technology adoption and advanced theatrical exhibition.
Global Advanced Cinema Projector Market Key Industry Players
European producers anchor one tier, emphasizing high-brightness laser solutions and integrated systems, while East Asian specialists hold another, focusing on advanced display technologies and cost-efficiency. The market structure exhibits moderate consolidation among top-tier manufacturers. Strategic archetypes include technology innovators, value-focused providers, and integrated solution specialists. Portfolio diversification and strategic partnerships represent dominant competitive moves.
Within the technology innovator tier, Sony and Barco exemplify companies pushing the boundaries of projection performance. Sony offers 4K LCoS technology for both cinema and high-end private theater applications. Barco leverages its deep focus on high-brightness laser solutions to serve the premium multiplex segment. Christie occupies a position as an integrated solution specialist, differentiating through its integrated media block and projection systems for large-format screens.
| Leading Market Players |
|---|
| BenQ |
| JVC |
| Sony |
| Digital Projection |
| Canon |
| Christie |
| Epson |
| Panasonic |
| Barco |
| Others |
Cost & Logistics Intelligence
Solid-state illumination technology, notably laser projection, simultaneously reshapes cost economics by reducing long-term operational expenses and influences supply concentration towards manufacturers capable of advanced component integration.
Pricing Analysis
Volume sales to large cinema chains operate on negotiated contracts, while specialized vendors offer premium-mid-economy pricing differentiation for private theaters. Price differentiation stems from image resolution capabilities, lumen output, and the inclusion of long-term service agreements. Pricing softness stems from the high initial capital outlay for 4K laser projectors, which large chains balance against total cost of ownership benefits. Smaller, independent cinema owners exhibit the highest price sensitivity, often seeking refurbished equipment or flexible financing models.
Supply Chain Analysis
Reverse-logistics flows for advanced projectors increasingly focus on component recovery and refurbishment, driven by the high value of laser light engines and imaging systems. Geographic supply concentration for critical components centers on East Asia for advanced display technologies like LCoS and DLP chips, alongside European manufacturers for high-brightness laser diodes. The supply chain relies on specialized optical components and precision electronics. Regulatory restrictions, such as the EU's RoHS directive, pose a structural risk for component sourcing. Distribution primarily runs through direct sales channels to major cinema chains and specialized integrators for event venues and private theaters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a significant technology-transition phase, with laser projection technology rapidly displacing legacy lamp-based systems across new installations and modernization efforts.
For Market Incumbents:To counter home entertainment substitution, incumbents must deepen long-term service agreements and integrate comprehensive theater management software. Investing in R&D for modular, energy-efficient laser engines extends product lifecycles and reduces operational costs for exhibitors. Expanding financing options for smaller cinema operators helps overcome the high initial investment barrier. Barco and Christie should leverage their established multiplex relationships to bundle integrated solutions.
For New Entrants and Emerging Players:The EU's Ecodesign Directive in Europe opens a window for new entrants offering highly energy-efficient, compliant laser projection systems. Target the private theater segment with DCI-grade technology adapted for residential environments, emphasizing bespoke installation and calibration services. Pursue emerging markets across Southeast Asia and Latin America by offering flexible financing models and localized support. Focus on integrated media block solutions to simplify installation and maintenance for smaller venues.
For Investors and Strategic Acquirers:Exit pathways concentrate in integrated solution specialists and technology innovators possessing strong intellectual property in laser optics or advanced image processing. The long-term viability of the market depends on the continued global modernization cycle of cinema screens and diversification into immersive entertainment venues. Acquisition targets should include firms with proprietary IMB technology or established distribution networks in high-growth emerging markets. Practitioners should monitor DCI standard revisions and new screen construction rates in Asia for early signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Long-Term Service Contracts | Secures recurring revenue streams and enhances customer loyalty for high-value laser projector systems. |
| Invest in RGB Pure Laser R&D | Delivers superior color fidelity and brightness, differentiating offerings in the premium multiplex segment. |
| Expand Integrated Solution Bundling | Simplifies procurement and operations for cinema chains, creating a more sticky ecosystem. |
| Target Emerging Market Expansion | Captures new screen construction demand in regions like India and Southeast Asia. |
| Develop Eco-Compliant Projectors | Ensures market access in regulated regions and aligns with exhibitor sustainability goals. |
Research Approach
Digital Cinema Initiatives (DCI) standards documents, EU Ecodesign directives, and FCC certifications formed the secondary backbone, complemented by trade publications and company reports. Primary research involved interviews with cinema chain executives, projection system engineers, event venue managers, and private theater integrators. This approach ensured a robust triangulation between reported data and qualitative market insights, covering both top-down market sizing and bottom-up validation.
Historical trendline analysis informed the forecast framework, applying regression modeling and growth curve extrapolation across the analysis window. Segmentation dimensions modeled included projection technology, application area, installation type, end user segment, and regional regulatory compliance. Compound annual growth rates were derived from historical growth rates and projected market drivers, with new screen construction rates and laser technology adoption curves serving as key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for laser projection technology would alter the outlook for legacy systems. Forecasts reflect assumptions regarding macroeconomic stability and regulatory continuity. Practitioners should monitor DCI standard revisions and economic growth in emerging markets for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Camera Jib Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Cinema Camera Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Drive-In Movie Theater Market