
 Tripod Dolly Market | 2026-2036
Tripod Dolly Market Size, Share, and Industry Trends Forecast 2026-2036
Tripod Dolly Market Analytics
Subscription-based maintenance and calibration services for motorized tripod dollies is hardening into a recurring revenue layer that reshapes vendor-customer relationships. Manfrotto leverages its European service infrastructure to anchor long-term contracts with rental houses. Proaim competes aggressively on direct-to-consumer pricing while sustaining thin margins through accessory bundling. Neewer dominates entry-level channels with volume manufacturing that controls cost curves across Southeast Asian supply chains.
A tripod dolly is a wheeled platform that mounts beneath a tripod to enable smooth horizontal camera movement across flat or track-laid surfaces, typically constructed from aluminum or steel with pneumatic or solid casters rated for loads between 15 and 150 kilograms. The device serves film, television, and live event producers who require repeatable, vibration-free tracking shots without the footprint of full rail systems. Heavy-duty aluminum models still occupy the largest revenue pool due to rental fleet standardization, though carbon fiber variants are gaining share among traveling documentary crews who prioritize payload-to-weight ratios. Motorized product types represent the fastest-expanding segment as remote operation protocols integrate with wireless focus and pan-tilt systems, while studio rental end users concentrate procurement around versatile load-capacity configurations that span lightweight mirrorless rigs through broadcast cinema cameras.
The Federal Communications Commission governs wireless spectrum allocation for motorized dolly control interfaces, while OSHA workplace standards influence load-rating disclosures and caster-lock safety mechanisms in commercial production environments. The EPA's evolving framework for aluminum smelting emissions indirectly shapes raw material cost structures for domestic manufacturers. Buyers and rental operators must track how wireless protocol certifications and material sourcing disclosures reshape supplier qualification criteria.
Market Dynamics
Carbon fiber material substitution is compressing weight-to-payload ratios across rental fleets while motorized control interfaces demand FCC wireless certification, forcing manufacturers to rebuild product architectures around dual compliance burdens rather than incremental feature additions.
Growth Catalysts
- Streaming Content Pipelines:Film production studios in the United States are expanding grip equipment inventories to fulfill long-form series commitments from subscription video platforms.
- REACH Material Disclosures:European Union chemical transparency mandates are accelerating aluminum supply chain documentation, favoring manufacturers with established European service infrastructure.
- Wireless Integration Protocols:Remote operation standards for motorized dollies are converging with pan-tilt-head control systems, enabling synchronized camera movement without dedicated track crews.
Market Restraints
- Aluminum Smelting Emissions:EPA evolving frameworks for domestic smelting operations are indirectly elevating raw material cost structures for U.S.-based manufacturers.
- Southeast Asian Supply Concentration:Volume manufacturing dependencies in Vietnam and Thailand create vulnerability to port congestion and regional logistics disruptions.
- Manual Dolly Substitution:Entry-level pneumatic caster platforms from Chinese suppliers undercut motorized variants on price, capturing budget-conscious independent filmmaker segments.
Strategic Opportunities
- Subscription Maintenance Contracts:Recurring calibration and firmware update services for motorized units create annuity revenue streams that reduce customer churn.
- Documentary Crew Mobility:Carbon fiber payload-to-weight advantages align with traveling production needs in remote locations across Kenya and Patagonia.
- India PLI Manufacturing Incentives:Production-linked incentive schemes for precision engineering components attract assembly relocation for export-oriented rental house supply.
Industry Challenges
- Wireless Spectrum Certification Timelines:FCC equipment authorization delays for new control interfaces extend product launch windows by six to nine months.
- Legacy Fleet Compatibility:Rental houses face integration friction when retrofitting motorized heads onto existing aluminum dolly platforms with non-standard mounting patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tripod Dolly Market |
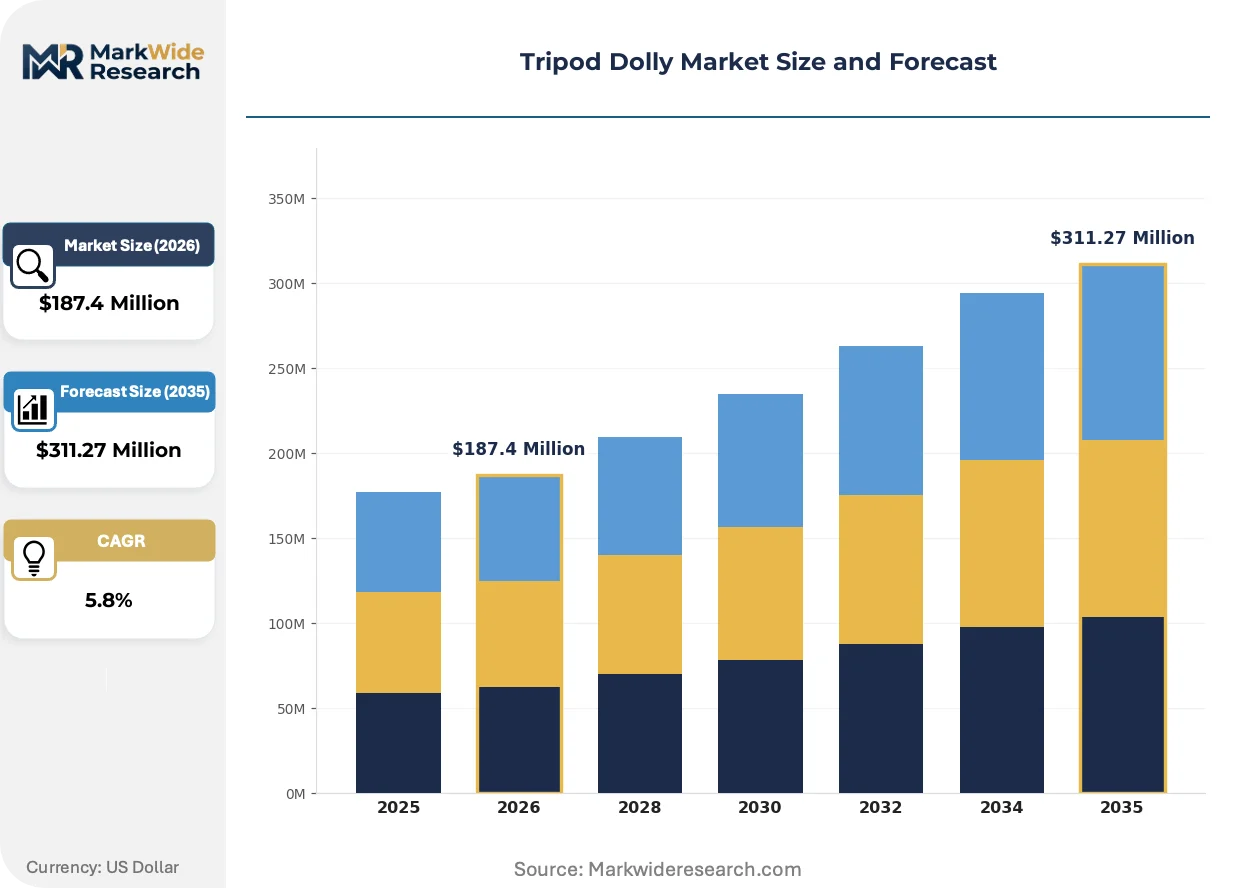
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty, Compact, Versatile, Motorized End User: Film Production, Photography, Event Management, Studio Rental Material: Aluminum, Steel, Carbon Fiber, Plastic Load Capacity: Lightweight, Medium, Heavy, Extra Heavy |
| Companies Covered | Neewer, Magnus, Proaim, Manfrotto, Glide Gear, eCostConnection, Kingjoy, Slidekamera, Hague, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tripod Dolly Market Evolving Landscape
Motorized control architectures and carbon fiber structural materials are converging to redefine product category boundaries, while regulatory fragmentation across wireless certification regimes forces parallel development tracks.
Carbon fiber layup techniques are consolidating structural performance thresholds previously requiring steel reinforcement. Documentary production crews operating in remote terrain are adopting these platforms to reduce transport weight without sacrificing broadcast camera stability. The technology is consolidating mid-tier product segments where aluminum previously dominated rental fleet procurement.
OSHA workplace standards for load-rating disclosures and caster-lock safety mechanisms are tightening documentation requirements for commercial production environments. Studios in California and New York now demand third-party validation of pneumatic brake systems before fleet insurance coverage activates. Grip equipment rental operators are responding by consolidating supplier relationships with vendors holding pre-certified component libraries.
Rental house procurement is fragmenting between long-term fleet standardization and project-specific equipment sourcing. Large studios in Los Angeles negotiate master service agreements with preventive maintenance clauses, while independent producers in Austin and Atlanta favor transactional marketplace rentals with per-day pricing. This bifurcation is most visible in the United States, where regional production hub density supports both channel models simultaneously.
Tripod Dolly Market Segmentation
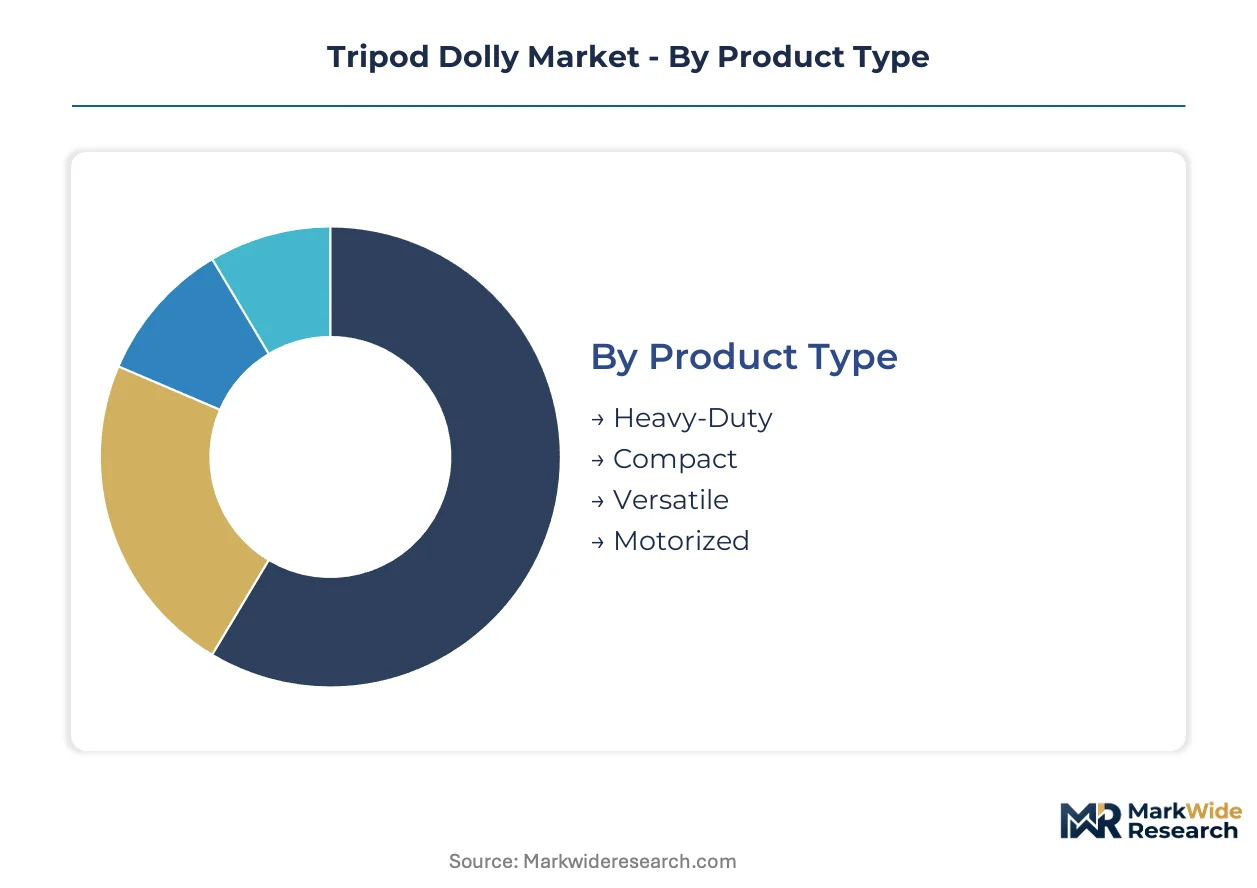
Segmentation in the tripod dolly market reveals how certification burdens, material costs, and end-use requirements fragment procurement patterns across rental houses and production studios. Each dimension carries distinct regulatory and operational implications that reshape vendor positioning.
Product Type:
FCC wireless certification applies selectively across this category, with motorized variants facing six-to-nine-month authorization timelines while manual platforms bypass spectrum governance entirely.
- Heavy-Duty:Reinforced aluminum or steel construction rated for 80-150 kilogram payloads, serving broadcast cinema configurations. Studio rental operators in Los Angeles and New York standardize fleets around these platforms to secure insurance coverage under tightening OSHA load-rating disclosure rules.
- Motorized:Remote-controlled wheel assemblies integrating with wireless pan-tilt-head protocols. Demand concentrates among streaming content producers in the United States who require synchronized camera movement without dedicated track crews, though FCC equipment authorization delays constrain launch velocity.
- Compact:Collapsible frames targeting independent filmmakers and documentary crews. Portability requirements drive adoption across Southeast Asian production hubs where space-constrained location shooting dominates.
- Versatile:Modular designs accommodating multiple mounting patterns and caster configurations. Rental houses favor these units to reduce fleet duplication across project types.
Heavy-Duty sits at the top of the volume ranking, with Motorized climbing the fastest.
End User:
Procurement sophistication varies sharply across this dimension, from transactional marketplace rentals to master service agreements with preventive maintenance clauses.
- Film Production:Long-form series commitments from subscription video platforms drive grip equipment inventory expansion. Studios in California negotiate multi-year supplier contracts with embedded calibration services for motorized units.
- Studio Rental:Fleet standardization around versatile load-capacity configurations spans lightweight mirrorless rigs through broadcast cinema cameras. Third-party validation of pneumatic brake systems is becoming mandatory before insurance activation.
- Photography:Still-image producers prioritize compact aluminum variants for location portrait and commercial work. Budget constraints favor entry-level pneumatic caster platforms over motorized alternatives.
- Event Management:Live production crews require rapid deployment capabilities and redundant caster-lock mechanisms for safety compliance in high-traffic environments.
Studio Rental commands the largest procurement volumes, while Film Production expands most aggressively on streaming infrastructure investment.
Material:
REACH disclosure requirements in Europe and EPA smelting frameworks in the United States impose divergent compliance costs that reshape supplier qualification criteria.
- Aluminum:Dominates rental fleet procurement due to cost efficiency and established repair networks. EPA evolving frameworks for domestic smelting operations indirectly elevate raw material cost structures for U.S.-based manufacturers.
- Carbon Fiber:Layup techniques consolidate structural performance thresholds previously requiring steel reinforcement. Documentary crews operating in remote terrain across Kenya and Patagonia adopt these platforms to reduce transport weight without sacrificing broadcast camera stability.
- Steel:Remains specified for permanent studio installations where weight penalties are irrelevant and maximum durability is prioritized.
- Plastic:Injection-molded components appear primarily in entry-level consumer segments with limited professional adoption.
Aluminum retains volume leadership, with Carbon Fiber gaining share fastest on payload-to-weight optimization.
Load Capacity:
Rental house procurement fragments between lightweight configurations for mirrorless rigs and heavy-duty platforms for cinema cameras, with medium-capacity units capturing the broadest project flexibility.
- Heavy:60-100 kilogram ratings accommodate broadcast cinema cameras with full lens and accessory loads. OSHA workplace standards for load-rating disclosures tighten documentation requirements for commercial production environments deploying these units.
- Medium:30-60 kilogram range captures the widest cross-section of production types, from documentary rigs to commercial cinematography. This segment benefits from fleet standardization trends among regional rental operators.
- Lightweight:Under 30 kilogram ratings align with mirrorless and DSLR configurations. Independent filmmakers in Austin and Atlanta favor transactional marketplace rentals with per-day pricing for these units.
- Extra Heavy:Exceeding 100 kilograms, these platforms serve specialized applications including IMAX and large-format cinematography with limited addressable demand.
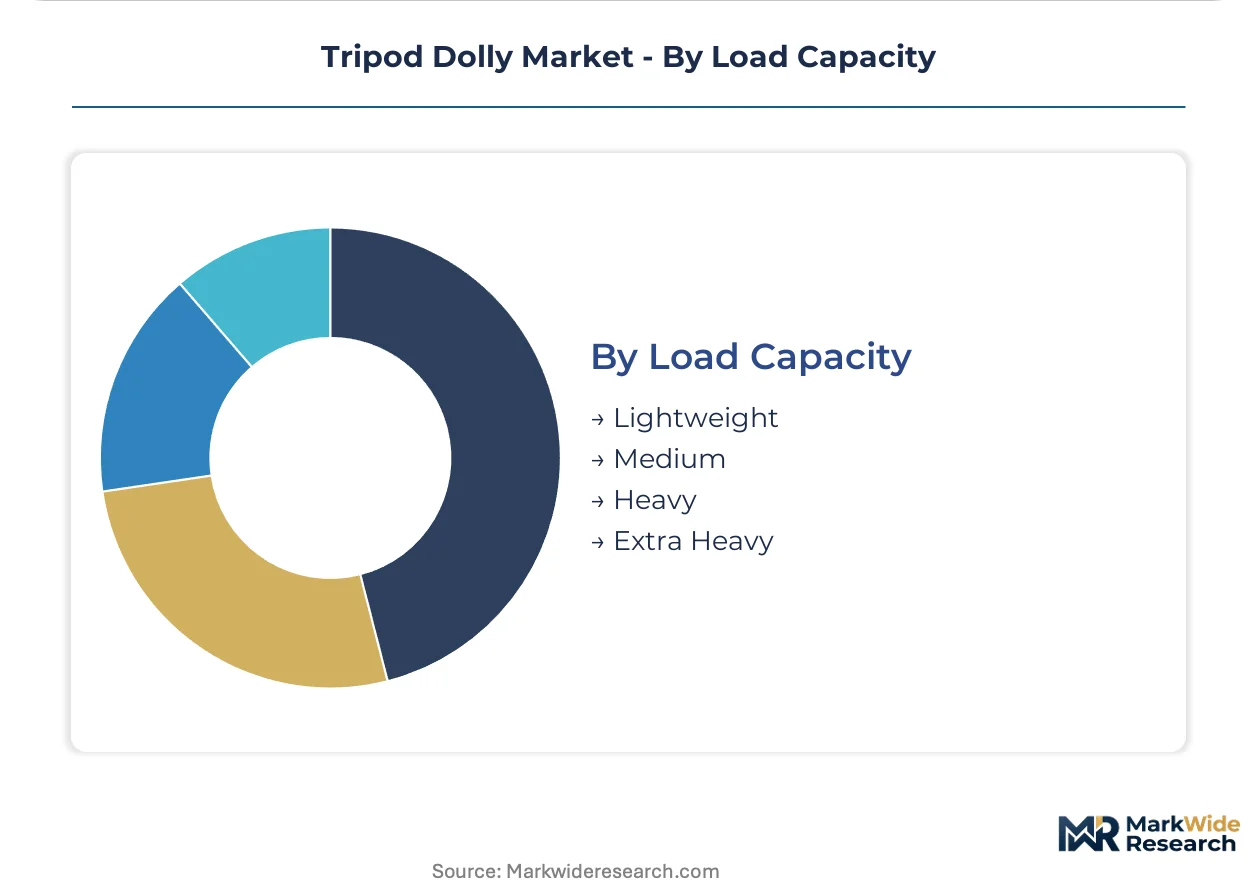
Medium load capacity holds the top volume position, with Heavy capacity expanding most quickly on broadcast infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering heritage contrasts with India's emerging manufacturing incentives in shaping regional tripod dolly supply capabilities. Both markets now attract assembly relocation as vendors seek regulatory arbitrage and cost optimization across divergent compliance environments.
United States
Streaming content pipelines from Los Angeles and New York studios drive grip equipment inventory expansion. FCC wireless certification timelines for motorized dolly control interfaces extend product launches by six to nine months. Production clusters in California and Georgia negotiate master service agreements with embedded preventive maintenance clauses.
Germany
REACH material disclosure mandates accelerate aluminum supply chain documentation requirements. ECHA chemical transparency frameworks favor manufacturers with established European service infrastructure. Industrial concentration in Bavaria and North Rhine-Westphalia supports precision engineering component fabrication for export-oriented rental house supply.
India
Production-linked incentive schemes for precision engineering components attract assembly relocation from Southeast Asian supply chains. BIS standards for load-rating disclosures tighten domestic market entry requirements. Manufacturing investment concentrates in Maharashtra and Gujarat where engineering talent pools support carbon fiber layup technique adoption.
China
Volume manufacturing dependencies in Guangdong and Zhejiang provinces control cost curves across entry-level pneumatic caster platforms. MIIT wireless protocol standards diverge from FCC frameworks, forcing parallel product development tracks. Domestic demand from documentary production crews in Sichuan and Yunnan provinces prioritizes compact collapsible frames.
United Kingdom
Independent filmmaker communities in London and Manchester drive replacement cycles for versatile load-capacity configurations. CE marking requirements for motorized units align with EU regulatory frameworks post-Brexit transition. Studio rental operators in Scotland consolidate supplier relationships around pre-certified component libraries.
Tripod Dolly Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier vendors anchoring long-term rental house contracts while volume producers capture direct-to-consumer channels. The vendor base organizes around three strategic archetypes: European service infrastructure operators, Southeast Asian cost-curve controllers, and direct-to-consumer pricing aggressors. Competitive moves concentrate on subscription maintenance contract expansion and carbon fiber material substitution for payload-to-weight optimization.
Within the European service infrastructure tier, Manfrotto leverages its established continental presence to anchor long-term contracts with rental houses. Proaim occupies a position among pricing-aggressive specialists competing on direct-to-consumer channels. Neewer exemplifies the volume-manufacturing archetype that dominates entry-level segments through Southeast Asian supply chain control.
| Leading Market Players |
|---|
| Neewer |
| Magnus |
| Proaim |
| Manfrotto |
| Glide Gear |
| eCostConnection |
| Kingjoy |
| Slidekamera |
| Hague |
| Others |
Value Network & Pricing Analysis
Carbon fiber layup specialists concentrated in Bavaria and North Rhine-Westphalia command wage premiums that compress pricing spreads between motorized and manual dolly tiers. Labor-cost differentials between European precision engineering hubs and Southeast Asian assembly floors define the three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for entry-level pneumatic caster platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by FCC wireless certification status and carbon fiber content. Cost compression in the economy tier intensifies because Chinese suppliers undercut motorized variants on direct-to-consumer channels. Independent filmmakers in Austin and Atlanta exhibit highest price sensitivity, while Los Angeles studio rental operators prioritize versatile load-capacity configurations over per-unit cost.
Supply Chain Analysis
Regional distribution centers in Los Angeles and New York anchor hub-and-spoke patterns serving production clusters across California and Georgia. Manufacturing concentrates in China, Vietnam, and Thailand for aluminum extrusion and caster assembly. Raw material dependencies center on aluminum billet, carbon fiber prepreg, and pneumatic tire compounds. Single-source vulnerability runs through Southeast Asian port congestion exposure. Distribution runs through rental house fleet procurement and direct-to-consumer marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tripod dolly market reads as a late-cycle quality story. Streaming content pipelines from subscription video platforms are concentrating demand toward motorized units with embedded calibration services and carbon fiber payload-to-weight optimization.
For Market Incumbents: Anchor long-term rental house contracts through preventive maintenance clauses and FCC pre-certified component libraries. Defend against entry-level pneumatic substitution by deepening backward integration into carbon fiber layup production in Germany. Certification investment in REACH material documentation and OSHA load-rating validation secures insurance-dependent studio procurement. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer the lowest-friction route to independent filmmaker segments in Austin, Atlanta, and London. Documentary crew mobility across Kenya and Patagonia presents the most penetrable white-space for carbon fiber compact variants. A per-day transactional rental marketplace model bypasses entrenched fleet standardization relationships. For Investors and Strategic Acquirers: Grip equipment rental houses are the most active acquirer in this space, consolidating regional operators to capture master service agreement volumes. Long-term viability hinges on recurring revenue attachment rates for motorized unit maintenance. The signal to monitor is FCC equipment authorization backlog duration as inflection indicator for new product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Maintenance Contract Expansion | Recurring calibration services for motorized units reduce churn among Los Angeles studio rental operators. |
| Carbon Fiber Material Substitution | Layup technique adoption in Bavaria consolidates structural performance for documentary crews in remote terrain. |
| FCC Pre-Certification Investment | Pre-certified component libraries accelerate insurance activation for OSHA-compliant rental fleets. |
| Regional Distribution Hub Consolidation | Hub-and-spoke networks in California and Georgia capture streaming infrastructure procurement. |
| Direct-to-Consumer Channel Development | Digital marketplace routes bypass rental house intermediaries for independent filmmaker price sensitivity. |
Research Methodology
Bottom-up production studio and rental house modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with grip equipment rental operators, studio procurement managers, carbon fiber component fabricators, and FCC compliance consultants combined with secondary validation from SEC filings, customs trade records, and ECHA REACH disclosure databases. Triangulation across supply-side facility audits and demand-side fleet inventory surveys ensures coverage alignment.
Historical trendline analysis of motorized unit adoption rates and aluminum-carbon fiber material mix shifts informs projection parameters across the modeling period. Segmentation dimensions include product type, end user, material composition, and load capacity tier, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from weighted average of bottom-up unit economics and top-down market size reconciliation, incorporating streaming content pipeline commitments and wireless certification timeline assumptions.
FCC equipment authorization delays, Southeast Asian logistics disruptions, and EPA smelting emission framework evolution are the dominant revision risks. Forecasts reflect documented assumptions around regulatory timeline stability and material cost trajectory continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
Cinema Camera Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
Movie Tickets Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Drive-In Movie Theater Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Camera Jib Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Japan Animation, VFX and Post Production Market