
 Movies and Entertainment Market | 2026-2036
Movies and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Movies and Entertainment Market Intelligence
The shift from fully integrated studio production to a hybrid model utilizing co-production agreements and independent content acquisition is rebalancing the industry's creative sourcing. This allows for greater risk diversification and access to a wider pool of talent. Major studios like The Walt Disney Company leverage vast intellectual property libraries for franchise development. In contrast, Netflix specializes in data-driven content commissioning on a global scale, while A24 differentiates through critically acclaimed, director-led feature films.
Movies and entertainment encompass the industrial production, financing, and commercial distribution of audiovisual content. This content adheres to technical specifications like the Digital Cinema Package (DCP) for theatrical exhibition or specific bitrate encoding for streaming platforms. Within content types, television series now compete directly with feature films for budget and audience attention. The distribution channel mix shows a definitive shift toward streaming services, altering revenue models previously reliant on cinemas.
Content distribution and creation are governed by a complex web of national and international regulations. These rules dictate everything from intellectual property rights to local content quotas. For instance, U.S. copyright laws, the EU's GDPR influencing viewer data usage, and China's NMPA overseeing content approval all shape market access. Success for creators and distributors depends on navigating these varied legal landscapes while adapting to new monetization strategies.
Market Dynamics
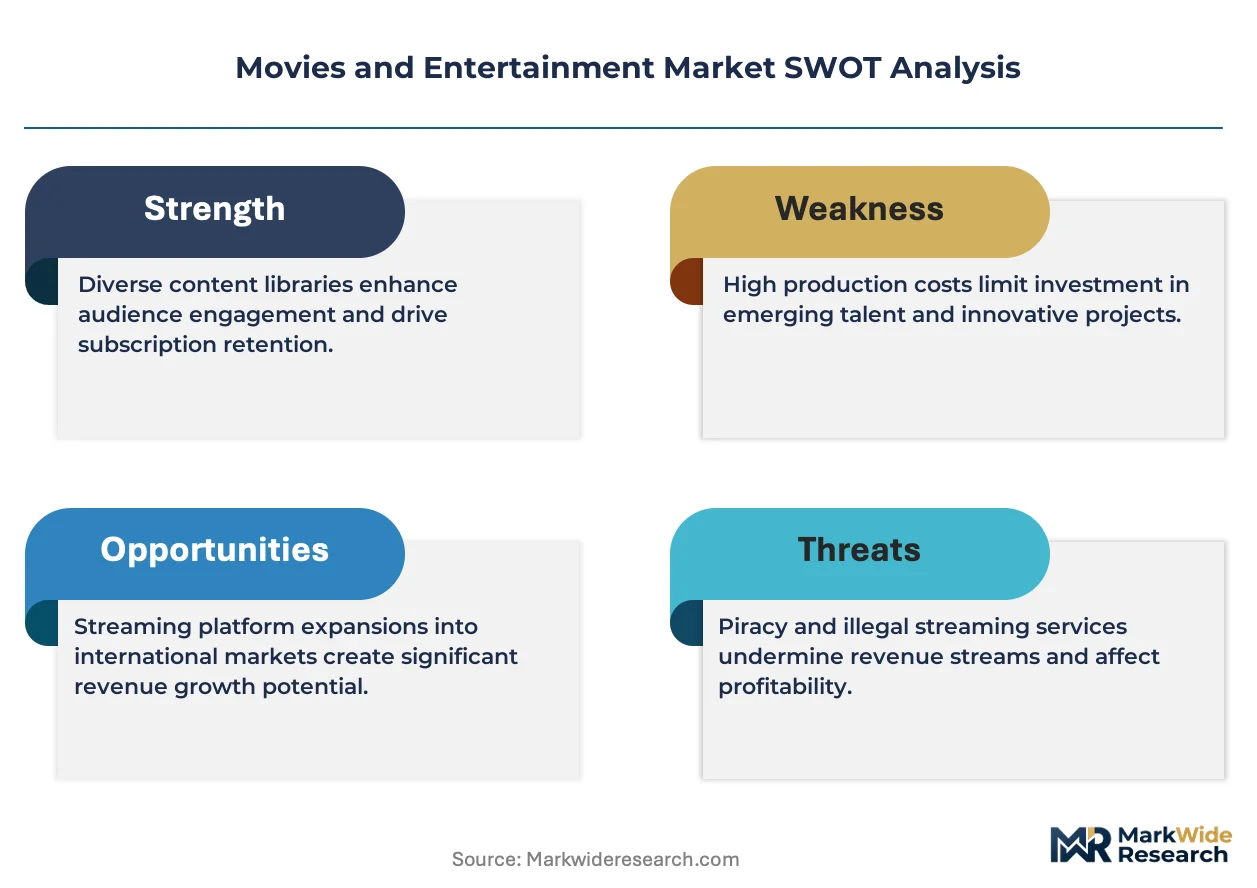
The shift toward data-driven content commissioning is the central force rebalancing creative sourcing. This model prioritizes algorithmic analysis of viewer behavior to inform production and acquisition decisions on a global scale, moving away from traditional studio intuition.
Growth Catalysts
- Expanding Digital Infrastructure:Rapidly improving internet access and mobile data affordability in countries like India unlocks vast new audiences for streaming and digital content consumption.
- Original Content Investment:Aggressive capital allocation by major streaming platforms into producing exclusive, original series and films acts as a primary subscriber acquisition and retention tool.
- Globalized Content Demand:A growing consumer appetite for non-English language productions from regions like South Korea and Spain creates new export markets for international creators.
Market Restraints
- Content Regulation and Censorship:Stringent content approval processes, such as those enforced by China's NMPA, create significant market access barriers and require costly content modifications.
- Production Cost Escalation:The rising costs of talent, visual effects, and global marketing campaigns for blockbuster films put significant pressure on studio profitability and risk profiles.
- Audience Fragmentation:The proliferation of entertainment options, including short-form video platforms and interactive gaming, creates intense competition for viewer attention and leisure time.
Strategic Opportunities
- Interactive Narrative Formats:The convergence of gaming engine technology with cinematic storytelling opens opportunities for new, immersive entertainment experiences that offer viewer agency.
- Niche Streaming Services:Launching specialized, direct-to-consumer platforms focused on underserved genres or demographics presents a path for independent players to build loyal audiences.
- Emerging Market Co-Productions:Partnering with local production houses in fast-growing regions like Southeast Asia allows studios to access new talent pools and create culturally relevant content.
Industry Challenges
- Intellectual Property Management:Navigating the complex web of global copyright laws and royalty distribution for content licensed across dozens of territories is a major operational hurdle.
- Talent Pipeline Shortages:Intense competition exists for skilled professionals in high-demand fields like visual effects, data science, and AI-driven production tools.
- Format Standardization:A lack of universally adopted technical standards for emerging formats like virtual reality cinema slows investment and hinders the creation of a broad content ecosystem.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Movies and Entertainment Market |
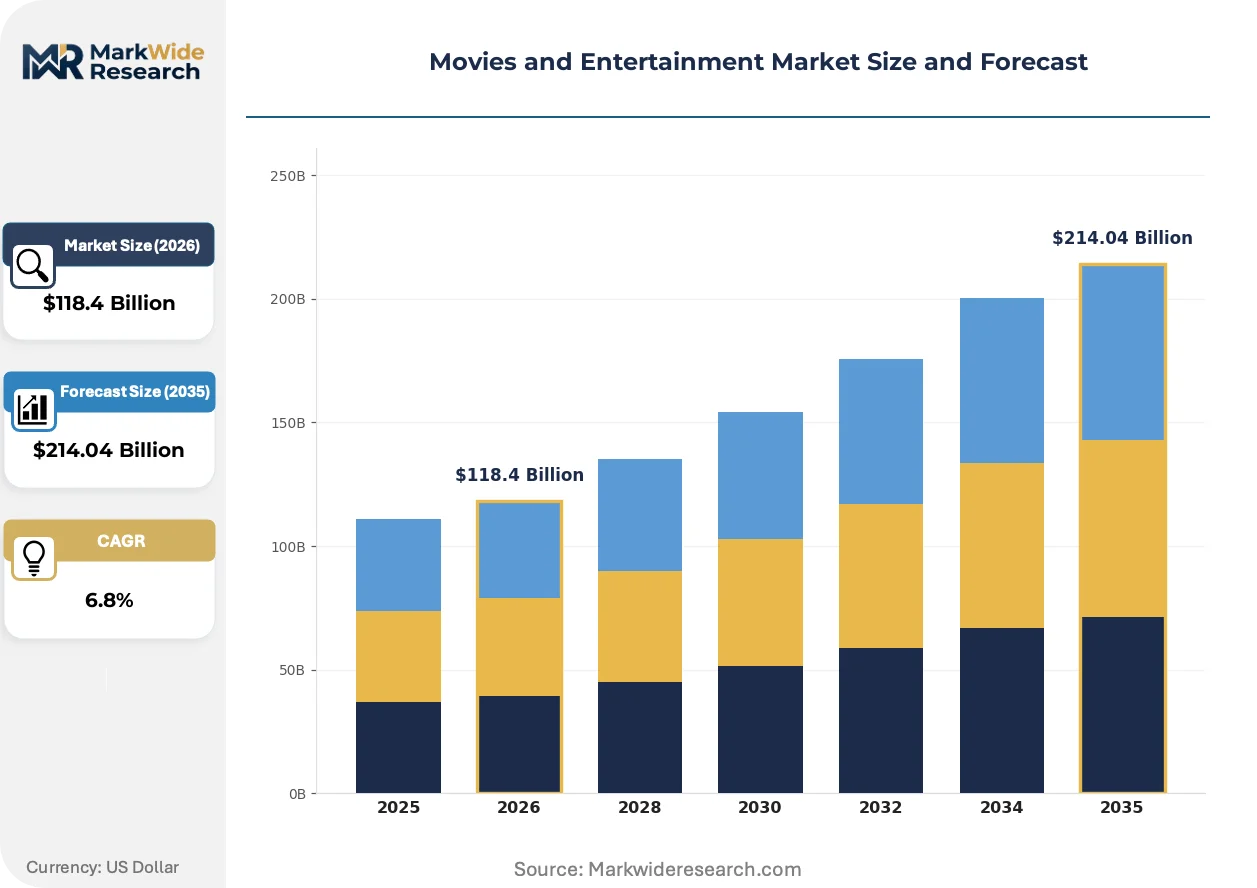
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $214.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Feature Films, Documentaries, Short Films, Television Series Distribution Channel: Cinemas, Streaming Services, Broadcast TV, DVD/Blu-ray Viewer Demographics: Teens, Adults, Families, Seniors Genre: Action, Comedy, Drama, Horror |
| Companies Covered | Warner Bros Discovery, Paramount Global, Walt Disney, Lionsgate Studios, Amazon MGM Studios, Comcast, Netflix, A24, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Movies and Entertainment Market Strategic Shifts & Innovations
A conflict between creative autonomy and data-driven optimization defines current content strategies. This dynamic influences decisions from project greenlighting to user experience personalization, forcing a re-evaluation of traditional production models.
Generative AI tools are accelerating post-production for visual effects and editing. Studios and independent creators adopt this technology to reduce manual labor and shorten project timelines. This capability is converging with digital asset management systems, enabling more complex creative development within compressed production schedules.
Regulatory frameworks like the EU's General Data Protection Regulation (GDPR) govern viewer data use. This forces streaming platforms to be transparent about how they use personal information for recommendations. The streaming services segment is most affected, adapting its algorithms to comply with strict user consent requirements.
Viewing habits show a shift from appointment-based schedules to on-demand, serialized consumption. This change disrupts legacy broadcast models that rely on linear advertising revenue. The trend is most visible in markets with high broadband penetration, such as North America, where subscription services dominate.
Movies and Entertainment Market Segmentation
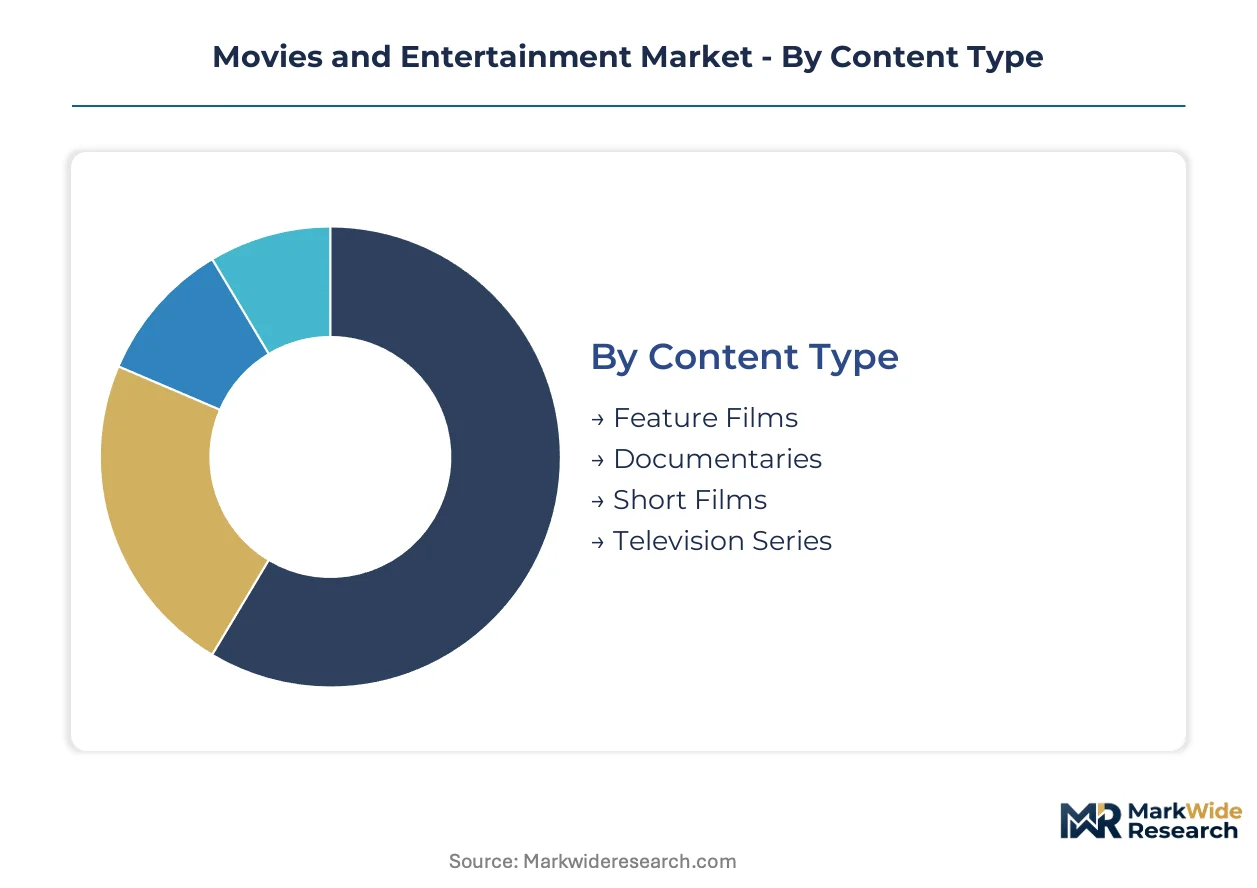
The Movies and Entertainment Market exhibits diverse characteristics across its various segments, reflecting distinct production methodologies, distribution pathways, and audience preferences. Understanding these segmentations provides clarity on market dynamics and strategic focus areas for content creators and distributors. Each category highlights unique operational considerations and growth trajectories.
Content Type:
Content types adhere to specific technical specifications for production and exhibition, influencing their creative scope and distribution formats.
- Feature Films:These productions typically exceed 40 minutes in length and are designed for theatrical release, often requiring Digital Cinema Package (DCP) standards for projection. Demand concentrates in global markets like India, where cinematic experiences remain a cultural cornerstone.
- Television Series:Episodic content structured for serialized viewing, these productions often involve longer narrative arcs and specific bitrate encoding for streaming platforms. Audience attention is increasingly shifting towards these series, driven by original content investments from major streaming platforms.
- Documentaries:Non-fictional films presenting factual information, often distributed through film festivals and educational streaming channels.
- Short Films:Brief cinematic works, typically under 40 minutes, frequently showcasing emerging talent and experimental narratives.
Mature deployment sits with Feature Films. Newer deployment is concentrated in Television Series.
Distribution Channel:
The choice of distribution channel dictates content accessibility and revenue models, reaching audiences through varied platforms.
- Streaming Services:Digital platforms offering on-demand access to a vast library of content, requiring robust internet infrastructure and efficient content delivery networks. Demand is expanding most quickly in regions with high broadband penetration, like North America, driven by subscriber acquisition strategies.
- Cinemas:Traditional venues for public exhibition of films, relying on scheduled screenings and providing an immersive communal viewing experience. Global box office receipts continue to concentrate in major markets such as the United States, supported by large-scale blockbuster releases.
- Broadcast TV:Linear television programming delivered via terrestrial, satellite, or cable networks, often relying on advertising revenue models.
- DVD/Blu-ray:Physical media formats for home entertainment, providing high-quality playback and collector's editions for dedicated fans.
The distribution landscape is undergoing rapid transformation, with Streaming Services gaining share fastest.
Viewer Demographics:
Content commissioning increasingly targets specific viewer demographics to optimize engagement and personalization strategies.
- Adults:This demographic segment, typically aged 25-54, forms a significant portion of the audience for diverse genres, including drama and thrillers. Content tailored for adults often explores complex themes, with demand concentrating in markets like the United States where subscription services cater to varied tastes.
- Families:This segment includes content suitable for all ages, emphasizing themes of adventure, animation, and educational narratives, driving demand for co-viewing experiences. Global demand for family-friendly content remains high, fueled by platforms like Disney+ leveraging extensive intellectual property.
- Teens:Younger audiences, typically 13-18, show strong preferences for fantasy, sci-fi, and social media-driven content, influencing platform engagement.
- Seniors:Audiences aged 65 and above often prefer historical dramas, documentaries, and classic films, finding content through traditional broadcast and niche streaming.
Content catering to Adults represents a stable demand base, while offerings for Teens are experiencing steepest expansion trajectory.
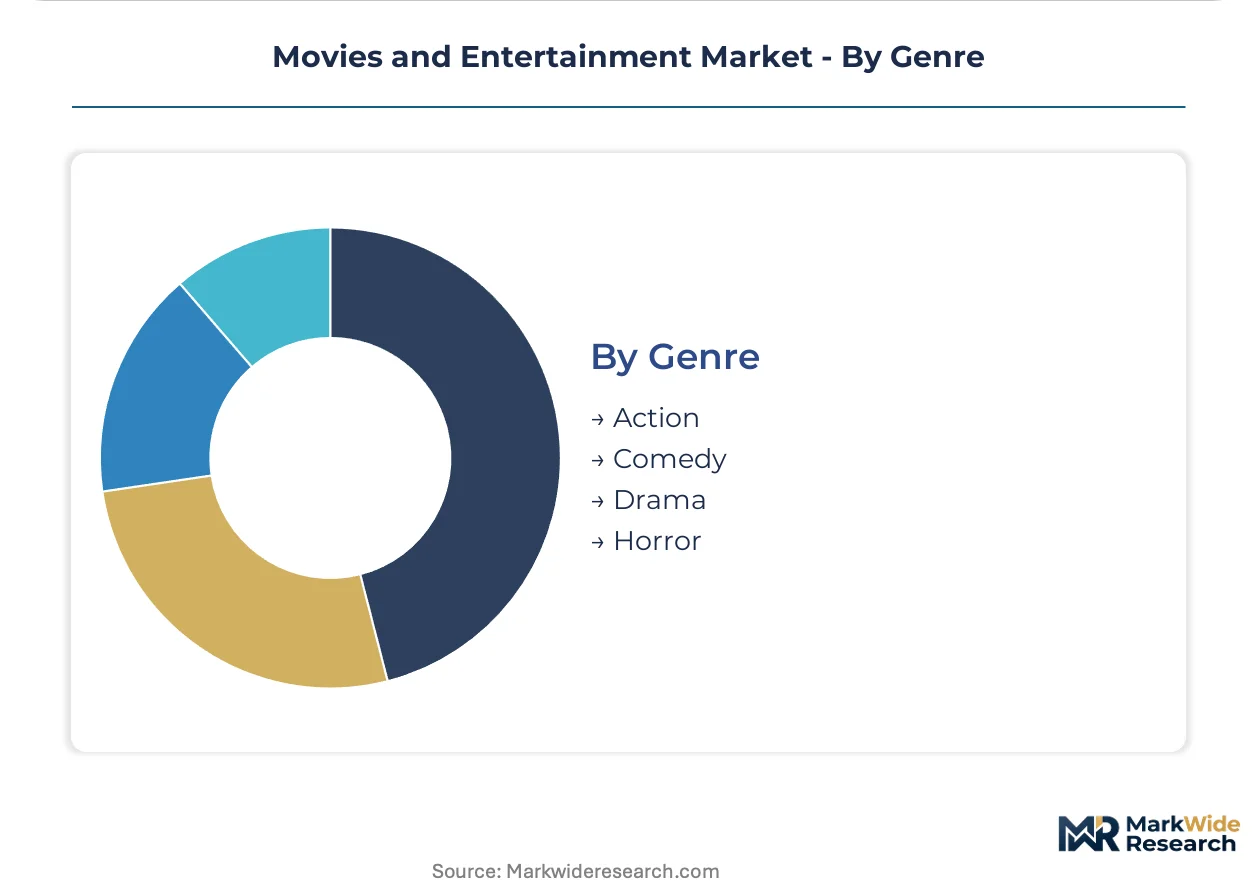
Genre:
Audience preferences for specific genres significantly influence creative development and production investment decisions.
- Drama:This genre focuses on character development and emotional narratives, often exploring complex human conditions and social issues. Demand for compelling drama is consistently high across all demographics, particularly in European markets known for critically acclaimed productions.
- Action:Characterized by high-energy sequences, stunts, and often special effects, this genre frequently involves large production budgets and global marketing campaigns. Blockbuster action films drive significant theatrical revenue in markets such as China.
- Comedy:Films and series designed to evoke laughter, often relying on witty dialogue or situational humor to entertain audiences.
- Horror:A genre focused on suspense, fear, and psychological thrills, attracting a dedicated niche audience globally.
Drama consistently attracts broad viewership, while Action films command significant box office returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global movies and entertainment market sees significant activity anchored by the United States, a primary hub for content creation and distribution. Expanding digital infrastructure in countries like India also drives demand. This market navigates varied regulatory landscapes and evolving consumption patterns worldwide.
United States
United States consumers drive demand for streaming services, particularly for adult-oriented dramas and original series. U.S. copyright laws heavily influence content licensing and global distribution agreements. Hollywood in Los Angeles remains the primary global center for feature film production and talent acquisition.
India
India's market expands rapidly due to improving internet access and affordable mobile data, increasing digital content consumption. The Indian Telecom Regulatory Authority (TRAI) oversees digital infrastructure development, supporting wider content accessibility. Mumbai, the heart of Bollywood, concentrates significant demand for cinematic experiences.
China
China's film market sees strong demand for action films, generating substantial box office revenue. The NMPA enforces strict content approval processes, creating market access barriers for international distributors. Beijing acts as a major production and distribution center, shaping domestic entertainment trends.
United Kingdom
United Kingdom audiences consistently seek compelling drama and diverse content across streaming platforms. The EU's GDPR dictates how viewer data is collected and used by streaming services for recommendations. London's creative sector is a significant hub for television series production and digital media innovation.
South Korea
South Korea benefits from global demand for its non-English language productions, particularly television series. The Korean Communications Commission (KCC) regulates digital content platforms and broadcasting standards. Seoul acts as a dynamic hub for K-drama and K-pop, driving international content exports.
Movies and Entertainment Market Key Industry Players
Global majors compete with regional champions across creative sourcing and distribution reach in the movies and entertainment market. The market features fully integrated studios, data-driven streaming platforms, and niche content specialists. Major players invest heavily in original content to attract subscribers and leverage vast intellectual property libraries for franchise development. Companies also engage in strategic partnerships to expand global footprint and diversify content portfolios. This structure supports both large-scale blockbusters and specialized independent productions.
Data-driven content commissioning is exemplified by Netflix, a global streaming giant focusing on algorithmic analysis for production decisions. Walt Disney, a long-established studio, anchors the market's integrated production model, leveraging extensive intellectual property for franchise development and family content. A24 occupies a position as a niche content specialist, known for critically acclaimed, director-led feature films that differentiate its offerings. These entities collectively shape the industry's strategic direction and content innovation.
| Leading Market Players |
|---|
| Warner Bros Discovery |
| Paramount Global |
| Walt Disney |
| Lionsgate Studios |
| Amazon MGM Studios |
| Comcast |
| Netflix |
| A24 |
| Sony |
| Others |
Cost & Logistics Intelligence
Streaming platforms' aggressive content commissioning strategies directly influence project-based pricing for independent production houses. This model emphasizes value-based licensing agreements for intellectual property.
Pricing Analysis
Content licensing agreements often bundle extensive post-production support and marketing rights, shaping the overall value proposition. Project-based pricing dominates for original productions, reflecting the creative talent involved and production scale. Price differentiation stems from the intellectual property's established value and the exclusivity period for distribution rights. Production cost escalation, particularly for visual effects and talent, creates upward pricing pressure. Niche streaming services exhibit higher price sensitivity compared to global platforms seeking tentpole content.
Supply Chain Analysis
Digital content delivery networks form the primary distribution layer, utilizing global server infrastructures to ensure low-latency streaming to diverse regions. The production supply chain concentrates heavily in the United States, India, and South Korea, drawing from a specialized pool of creative talent and advanced visual effects software. Intellectual property management across dozens of territories presents a significant operational risk. Content distribution increasingly relies on streaming platforms, displacing traditional theatrical exhibition models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The movies and entertainment market faces supply constraints driven by intense competition for elite creative talent and advanced visual effects capabilities. This bottleneck props up production costs, impacting profitability across the industry.
For Market Incumbents: Deploy extensive intellectual property monetization strategies to counter audience fragmentation. Leverage existing franchises through spin-offs and multi-platform content to maintain viewer engagement. Form strategic co-production agreements with regional partners to diversify creative sourcing and mitigate rising content acquisition costs. This approach insulates against the threat of new streaming platforms.
For New Entrants and Emerging Players: Capture underserved niche audiences with specialized direct-to-consumer streaming services. Focus on emerging market co-productions, particularly in regions like Southeast Asia, to access new talent and culturally relevant content. Launch interactive narrative formats that leverage gaming engine technology to offer viewer agency. This strategy targets the highly penetrable segment of engaged, genre-specific communities.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking long-term value in content libraries and enabling technologies. Prioritize investments in niche content specialists like A24 or AI-powered post-production studios to gain a competitive edge. Acquisitions of regional production houses in fast-growing markets present opportunities for global expansion. A sustained increase in subscriber retention rates for specialized streaming services signals market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Original Content Investment | Drives subscriber acquisition for streaming services and retains audience attention. |
| AI Integration in Post-Production | Accelerates visual effects workflows, reducing timelines for major studios. |
| Global Co-Production Partnerships | Accesses diverse talent pools and local cultural insights in emerging markets. |
| Niche Platform Development | Cultivates loyal audiences in underserved genres, differentiating from global platforms. |
| IP Franchise Expansion | Leverages established intellectual property for cross-platform content development by Walt Disney. |
Research Approach
Trade association data, regulatory filings from bodies like the NMPA, and industry reports anchored secondary inputs for this analysis. Primary research involved in-depth interviews with studio executives, independent producers, streaming platform strategists, and content rights lawyers. This approach triangulated insights from both supply-side and demand-side perspectives. Bottom-up data collection complemented top-down market sizing for comprehensive validation.
Data stream reconciliation involved synthesizing quantitative market values with qualitative industry trends across the analysis window. The analytical framework modeled market dynamics across content type, distribution channel, viewer demographics, genre, and regional market nuances. Compound annual growth rates were derived from historical performance and projected technological shifts. Key inputs included global broadband penetration rates and original content investment levels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving regulatory frameworks and rapid shifts in consumer viewing habits. These forecasts reflect documented assumptions regarding market growth and technological adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
China Animation, VFX and Post Production Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Movie Tickets Market
Film and Cinema
Middle East and Africa Animation, VFX and Post Production Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
Camera Jib Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
Anime Movies and TV Shows Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Japan Animation, VFX and Post Production Market