
 Digital Ad Spending Market | 2026-2036
Digital Ad Spending Market Size, Share, and Industry Trends Forecast 2026-2036
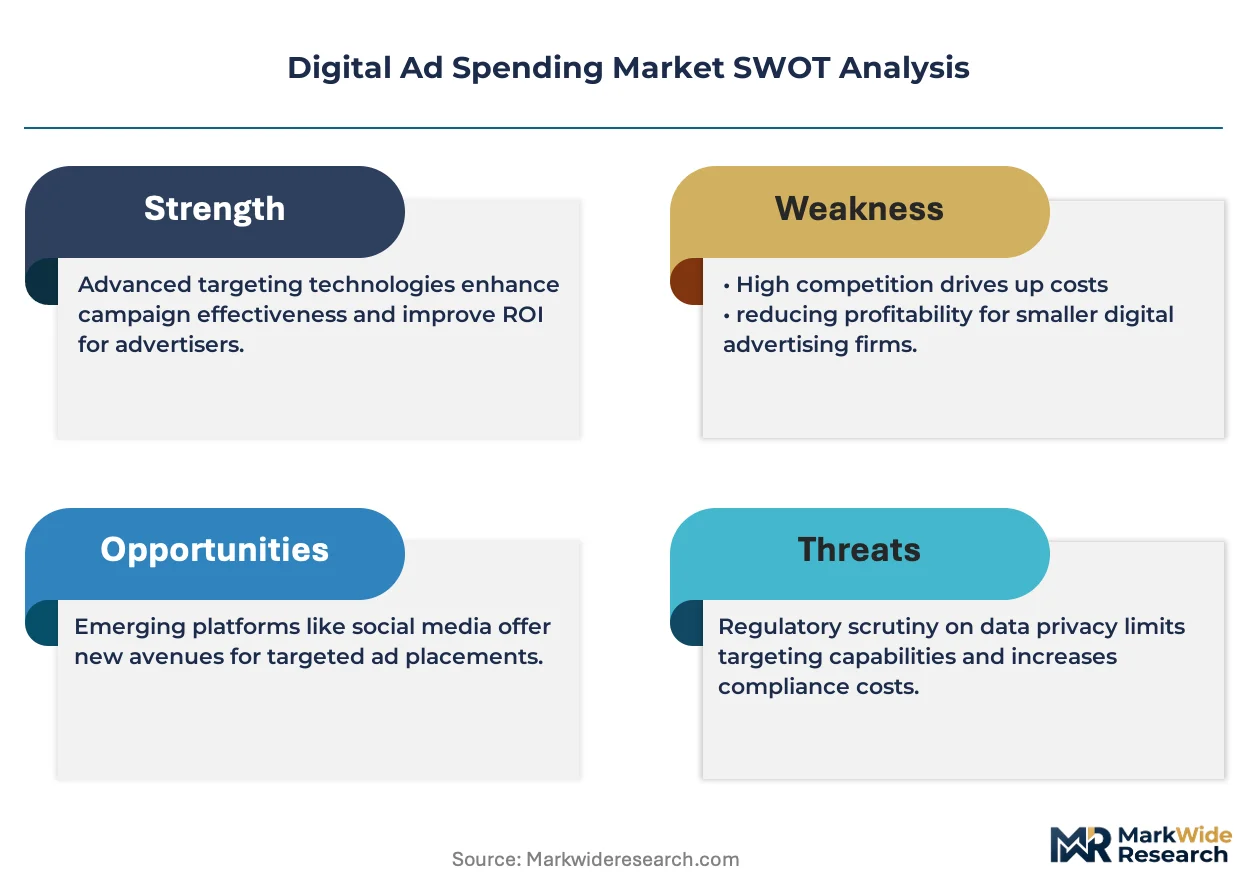
Digital Ad Spending Market Analysis
India is rewriting how Asia-Pacific advertisers allocate programmatic budgets as infrastructure investments in data centers and 5G expand addressable audiences. Google dominates search advertising through its control of query intent and auction mechanics. Meta competes in social advertising by leveraging its first-party data graph across Instagram and Facebook. Amazon anchors retail media through its captive commerce data and closed-loop attribution.
Digital ad spending encompasses the transfer of marketing budgets to internet-delivered promotional inventory measured through impressions, clicks, conversions, and return on ad spend. The ecosystem operates on real-time bidding protocols, demand-side platforms, and supply-side platforms that match advertiser creative assets to publisher inventory within milliseconds. Video ads within streaming services represent the fastest-expanding format as connected television supplants linear broadcast. Search ads retain the largest margin pool due to high-intent user queries and auction-based pricing. Mobile platforms lead volume delivery as smartphone penetration extends session duration and location-based targeting precision.
The Federal Trade Commission scrutinizes data collection practices that underpin behavioral targeting, while the European Union's Digital Markets Act imposes interoperability obligations on designated gatekeeper platforms. The California Consumer Privacy Act grants deletion rights that reshape audience segmentation methodologies and measurement fidelity. Stakeholders must monitor regulatory fragmentation across jurisdictions as compliance costs diverge and first-party data strategies determine competitive viability.
Market Dynamics
Google's deprecation of third-party cookies is collapsing the infrastructure that powered behavioral targeting for two decades, forcing advertisers to rebuild measurement stacks around first-party data and contextual signals.
Growth Catalysts
- Connected Television Inventory Scaling:Streaming platforms in the United States are converting linear broadcast budgets to programmatic video, expanding addressable audiences beyond traditional demographic panels.
- Retail Media Network Proliferation:E-commerce platforms with closed-loop attribution are capturing search and display budgets that previously flowed to open-web publishers.
- 5G Infrastructure Deployment:India's data center investments and mobile bandwidth expansion are enabling real-time bidding at scale for Asia-Pacific programmatic buyers.
Market Restraints
- Signal Loss From Identifier Deprecation:Apple's App Tracking Transparency and Google's Privacy Sandbox are degrading cross-device attribution fidelity and return-on-ad-spend measurement.
- Supply Concentration in Walled Gardens:Meta, Google, and Amazon control over seventy percent of digital ad inventory, extracting platform taxes that compress independent publisher margins.
- Regulatory Fragmentation Costs:The European Union's Digital Markets Act interoperability mandates and the California Consumer Privacy Act deletion rights are forcing parallel compliance architectures.
Strategic Opportunities
- Commerce Media Expansion:Non-retail verticals including travel and financial services are deploying first-party transaction data to build closed-loop advertising products.
- Privacy-Enhancing Technologies:Differential privacy and secure multi-party computation are enabling cohort-based targeting without individual-level tracking.
- Programmatic Audio Integration:Podcast and streaming music inventory is adopting real-time bidding protocols, opening undermonetized attention pools.
Industry Challenges
- Measurement Engineer Scarcity:The shift from third-party cookies to server-side tracking and clean rooms requires data engineering capabilities that outpace talent pipeline supply.
- Legacy System Integration Friction:Enterprise advertisers with on-premise customer data platforms face multi-year migrations to cloud-native identity resolution architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Ad Spending Market |
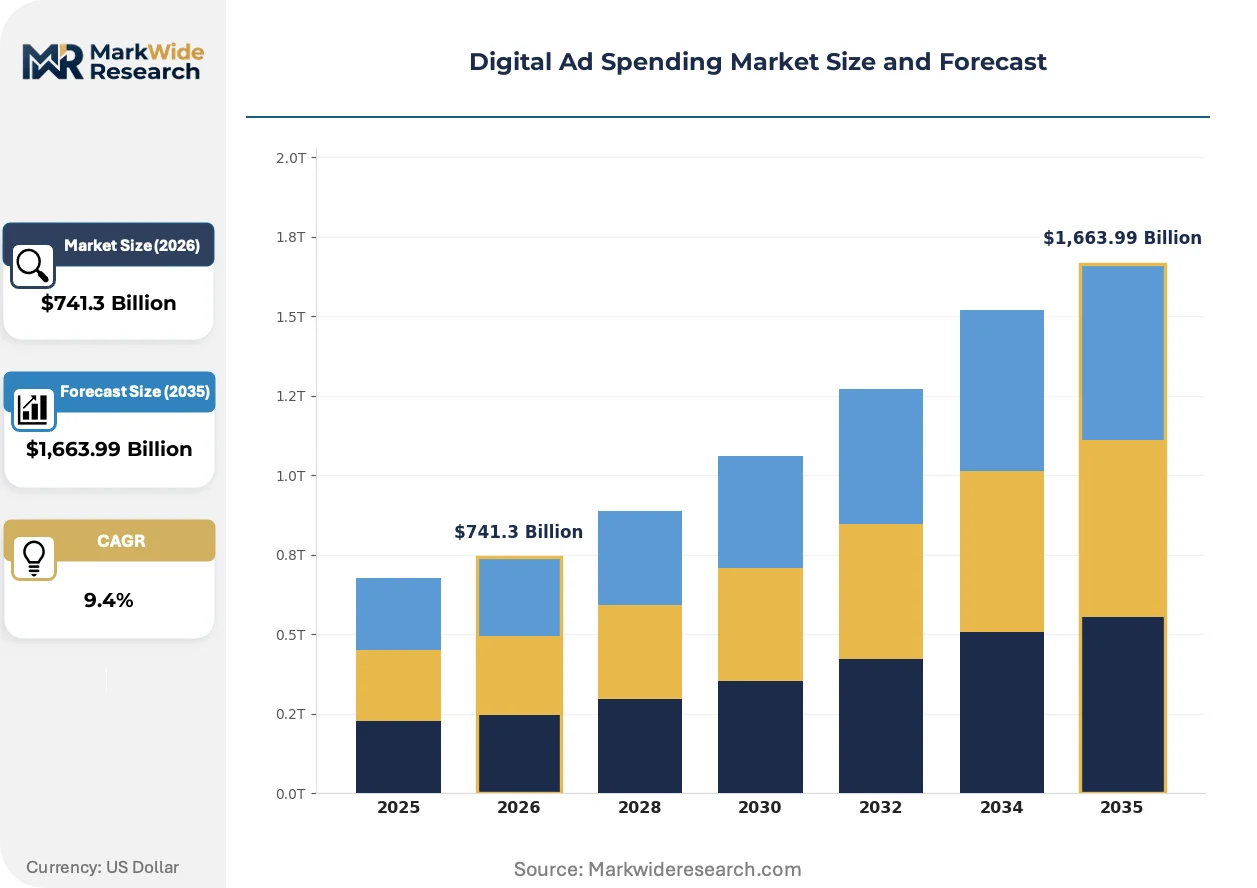
| Market Size in 2026 | $741.3 Billion |
| Market Size in 2035 | $1,663.99 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Display Ads, Video Ads, Social Media Ads, Search Ads Industry Vertical: E-commerce, Automotive, Travel, Healthcare Platform: Mobile, Desktop, Digital TV, Streaming Services Target Audience: Gen Z, Millennials, Professionals, Families |
| Companies Covered | TikTok, Apple, Google, YouTube, Netflix, Meta, Microsoft, ByteDance, Amazon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Ad Spending Market Emerging Trajectories
Artificial intelligence is compressing the creative-to-media pipeline, collapsing production timelines and enabling dynamic asset generation that responds to real-time auction signals.
Clean room infrastructure is collapsing the boundaries between advertiser first-party data and publisher inventory, enabling privacy-compliant audience matching without data leakage. Retail media networks and CTV platforms are adopting these environments fastest, converting data collaboration into competitive differentiation. The technology is collapsing traditional agency intermediary roles as direct platform integrations proliferate.
The European Union's Digital Markets Act interoperability obligations are forcing designated gatekeeper platforms to open advertising interfaces to third-party measurement providers. This regulatory shift is fragmenting previously closed attribution ecosystems and enabling independent verification of impression delivery. Small and mid-sized publishers in Germany and France are leveraging these openings to diversify demand sources.
Buyer concentration among enterprise advertisers is compressing payment terms and demanding outcome-based compensation models that shift risk to media sellers. Direct-to-consumer brands with in-house programmatic capabilities are displacing traditional agency-managed service relationships. This pattern is most visible in the United States, where retail and technology verticals have built captive trading desk operations.
Digital Ad Spending Market Segmentation
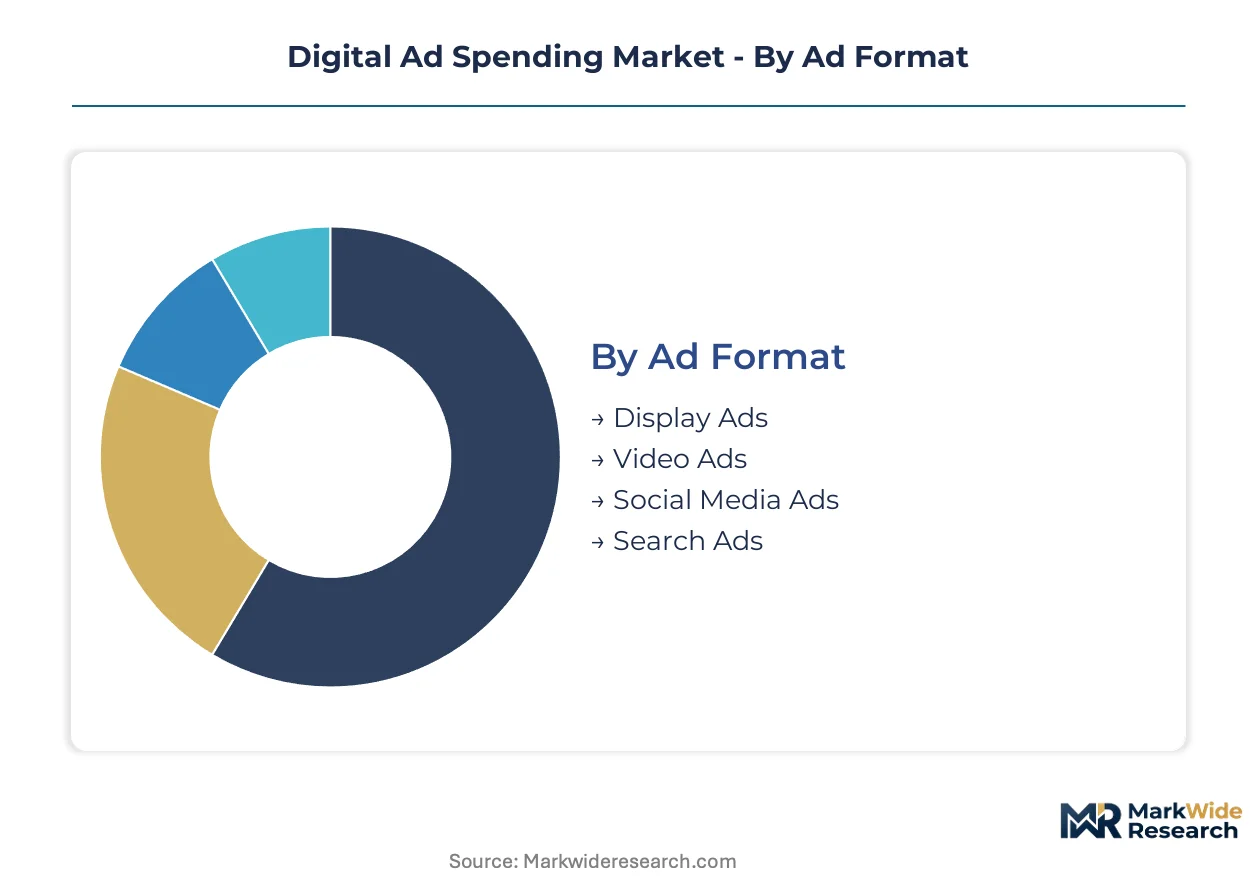
Segmentation in digital advertising determines budget allocation precision and creative format selection. Advertisers match inventory types to audience behaviors and platform contexts to optimize return on ad spend.
Ad Format:
Mature formats dominate revenue pools while emerging formats capture attention shifts across streaming and commerce environments.
- Search Ads:Text-based placements triggered by query intent deliver the highest conversion rates through auction-based keyword targeting. Advertisers in the United States concentrate spend here for bottom-funnel performance, though privacy regulations are degrading attribution fidelity.
- Video Ads:Sight-sound-motion creative assets within streaming and social feeds command premium CPMs through completion-rate optimization. Connected television inventory in the United States is accelerating migration from linear broadcast budgets as measurement standards mature.
- Display Ads:Banner and native placements across publisher networks rely on contextual and first-party data signals for targeting.
- Social Media Ads:Feed-based and story-format inventory leverages platform-specific engagement patterns and creator content integration.
Search Ads retain volume leadership; Video Ads hold the steepest expansion curve.
Industry Vertical:
Customer journey complexity shapes platform mix and attribution window requirements across sectors.
- E-commerce:Closed-loop transaction data enables precise return-on-ad-spend measurement and dynamic product feed automation. Retail media networks within this vertical are capturing budgets that previously flowed to open-web publishers through first-party data advantages.
- Automotive:High-consideration purchase cycles require multi-touch attribution across search, video, and display touchpoints. Dealership networks in the United States coordinate national brand spend with local inventory advertising through coordinated platform strategies.
- Travel:Seasonal demand fluctuations and real-time inventory availability drive programmatic bidding intensity and cancellation-adjusted attribution models.
- Healthcare:HIPAA compliance constraints limit audience targeting precision, forcing reliance on contextual placement and publisher-direct partnerships.
E-commerce commands the largest share of platform investment; Travel is climbing fastest as post-pandemic booking behavior normalizes.
Platform:
Device and delivery environment determine creative specifications, attention duration, and measurement methodology.
- Mobile:Smartphone-delivered inventory leads global impression volume through app-based and mobile-web placements. India's 5G infrastructure deployment is expanding real-time bidding capacity for Asia-Pacific programmatic buyers as data center investments scale.
- Streaming Services:Subscription and ad-supported video platforms deliver non-skippable creative within premium content environments. Connected television inventory scaling in the United States is converting linear broadcast budgets to programmatic video with addressable audience targeting.
- Desktop:Laptop and workstation placements retain B2B advertising concentration and complex purchase journey touchpoints.
- Digital TV:Smart television native applications and broadcast replacement interfaces bridge traditional and programmatic buying workflows.
Mobile retains volume leadership; Streaming Services holds the steepest expansion curve.
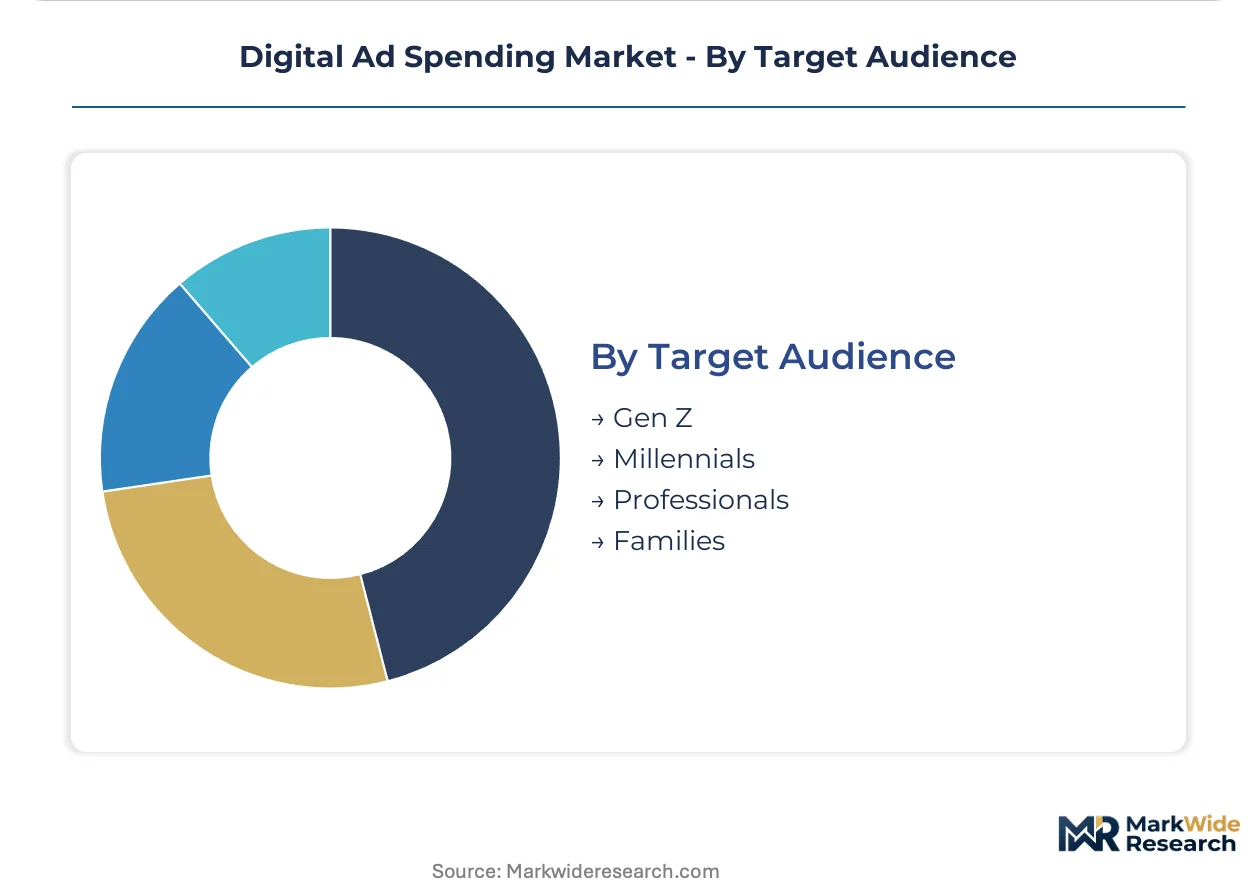
Target Audience:
Generational media consumption patterns dictate platform preference and creative format responsiveness.
- Gen Z:Short-form video-native consumers with high ad avoidance behaviors and creator-driven trust mechanisms. TikTok and Instagram Reels inventory in the United States captures disproportionate attention share from this cohort.
- Millennials:Streaming-first viewers with cross-platform purchase journeys and subscription fatigue driving ad-supported service adoption.
- Professionals:LinkedIn and desktop-focused B2B decision-makers with longer sales cycles and content-gated engagement patterns.
- Families:Co-viewing and household-level targeting subjects with shared device usage complicating individual attribution.
Millennials retain volume leadership; Gen Z holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital ad inventory concentrates in markets with scaled connected television infrastructure and mature programmatic ecosystems. Advertiser budgets flow toward jurisdictions where first-party data infrastructure and measurement standards have advanced furthest.
United States
Connected television inventory scaling and retail media network proliferation drive advertiser migration from linear broadcast. The FTC scrutinizes data collection practices under Section 5 of the FTC Act while state-level privacy laws multiply. New York and Los Angeles anchor the largest media buying operations, with trading desks concentrated in Manhattan and creative production clusters in Southern California.
China
Short-form video platforms and e-commerce integration command dominant attention shares among mobile-first consumers. The SAMR enforces anti-monopoly provisions against designated gatekeeper platforms under 2021 guidelines. Beijing and Shenzhen host the headquarters of dominant platform operators, with algorithmic advertising engineering talent clustering in Haidian District and Nanshan District respectively.
United Kingdom
Programmatic video and retail media adoption accelerates as post-cookie measurement alternatives mature. The Information Commissioner's Office enforces GDPR-derived standards on consent mechanisms and data processing transparency. London's Soho and Shoreditch districts concentrate independent media agencies and ad-tech vendors serving European campaigns.
Germany
Privacy-conscious consumer behavior and stringent consent requirements shape platform strategies and inventory pricing. The Digital Markets Act interoperability mandates force designated gatekeepers to open advertising interfaces to third-party measurement. Hamburg and Berlin host the European headquarters of major platform operators, with media buying concentrated around the Axel Springer Passage and Torstraße corridors.
India
5G infrastructure deployment and data center investments expand real-time bidding capacity for Asia-Pacific programmatic buyers. TRAI regulates digital communication platforms and over-the-top services under evolving frameworks. Mumbai and Bangalore concentrate media agency networks and ad-tech engineering operations, with Gurgaon emerging as a hub for in-house brand trading desks.
Digital Ad Spending Market Vendor Landscape
Search-dominant platforms and social-graph operators split the market through divergent data architectures and auction mechanics. Supply concentration exceeds seventy percent among three ecosystem owners, compressing independent publisher margins and extracting platform taxes. Strategic archetypes include query-intent monetizers, identity-graph aggregators, and commerce-data holders. Competitive moves center on clean-room infrastructure deployment and first-party data partnership networks.
Within the search-intent tier, Google occupies a foundational position through query auction control. Among social-graph operators, Meta exemplifies identity-based targeting across feed environments. At the commerce-data vector, Amazon anchors closed-loop attribution through transaction-level signals. These three represent the dominant strategic archetypes competing for enterprise advertiser budgets.
| Leading Market Players |
|---|
| TikTok |
| Apple |
| YouTube |
| Netflix |
| Meta |
| Microsoft |
| ByteDance |
| Amazon |
| Others |
Supply Flow & Price Mechanics
Manhattan's trading desk concentration anchors global media buying operations, with platform control over auction mechanics translating directly into pricing power across programmatic inventory tiers. Google's Privacy Sandbox deprecation timeline compresses first-party data infrastructure investment windows, forcing advertisers to absorb compliance premiums or cede measurement fidelity.
Pricing Analysis
The Digital Markets Act dictates the pricing tier structure for gatekeeper platform access across European campaigns, with interoperability mandates fragmenting previously closed attribution ecosystems. Three-tier pricing structure across premium, standard, and economy levels reflects data clean room sophistication, measurement granularity, and creative production automation depth. Cost compression in mid-market agency tiers is intensifying because direct-to-consumer brands with in-house programmatic capabilities displace traditional managed service relationships. Small and mid-sized publishers exhibit highest price sensitivity due to margin compression from supply concentration, while enterprise advertisers with captive trading desks demonstrate lowest sensitivity given outcome-based compensation models.
Supply Chain Analysis
Export control regimes limiting semiconductor and cloud infrastructure flows constrain data center capacity expansion for real-time bidding platforms across Asia-Pacific markets. Supply concentrates in the United States, Ireland, and Singapore for hyperscaler advertising infrastructure, with component dependencies spanning specialized AI accelerators, high-bandwidth memory modules, and subsea fiber interconnects. Single-source vulnerability in Taiwan-based foundry capacity for advanced logic chips threatens clean room deployment timelines. Distribution runs through direct platform APIs and certified reseller networks, collapsing traditional agency intermediary roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital ad spending operates as a high-growth disruption propelled by connected television inventory scaling and retail media network proliferation, with Google's third-party cookie deprecation serving as the regulatory inflection forcing infrastructure rebuilds.
For Market Incumbents: Pre-empt signal loss through accelerated clean room infrastructure deployment and first-party data partnership networks before Privacy Sandbox deprecation degrades cross-device attribution fidelity. Secure measurement engineer talent pipelines through university partnerships and cloud-native identity resolution certification programs. Defensive consolidation around contextual targeting capabilities and server-side tracking architectures counters emerging privacy-enhancing technology specialists. For New Entrants and Emerging Players: Build out programmatic audio integration capabilities across podcast and streaming music inventory, capturing undermonetized attention pools as real-time bidding protocols expand beyond video and display. India's 5G infrastructure deployment presents the most penetrable geography for Asia-Pacific programmatic buyers given data center investment scaling and addressable audience expansion. Go-to-market through direct brand trading desk partnerships bypasses entrenched agency relationships. For Investors and Strategic Acquirers: Long-term, this sits as a data infrastructure consolidation play because first-party data strategies determine competitive viability as third-party identifiers deprecate. Acquisition target archetype: privacy-enhancing technology specialists with differential privacy or secure multi-party computation capabilities. The signal to watch is clean room adoption velocity among retail media networks and connected television platforms as indicator of infrastructure shift completion.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Room Infrastructure Deployment | Enables privacy-compliant audience matching between advertiser first-party data and publisher inventory without leakage. |
| First-Party Data Partnership Networks | Converts data collaboration into competitive differentiation as Google's Privacy Sandbox degrades behavioral targeting. |
| Programmatic Audio Integration | Opens undermonetized podcast and streaming music attention pools through real-time bidding protocol adoption. |
| Measurement Engineer Talent Acquisition | Addresses scarcity in server-side tracking and cloud-native identity resolution capabilities outpacing pipeline supply. |
| Direct Platform API Integration | Collapses traditional agency intermediary roles as enterprise advertisers build captive trading desk operations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, App Annie mobile intelligence data, and IAB programmatic spending surveys. Primary interviews engaged chief marketing officers, programmatic trading desk heads, ad-tech platform engineers, and media agency buying directors across New York, London, and Mumbai. Bottom-up triangulation against supply-side platform inventory data and top-down validation through advertiser budget allocation surveys ensured cross-verification.
Forecast inputs span ad format evolution, platform penetration curves, and generational media consumption shifts across the projection horizon. Segmentation dimensions modeled include format type, industry vertical, delivery platform, and target audience cohort. CAGRs derived from historical spending trajectories adjusted for identifier deprecation impact, retail media network capture rates, and connected television inventory scaling curves. Regulatory compliance cost projections and first-party data infrastructure investment cycles informed scenario weighting.
Stress conditions across Privacy Sandbox implementation delays, TRAI regulatory framework evolution, and 5G deployment pace in India were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on signal loss mitigation technology adoption and clean room standardization timelines. Material shifts in Digital Markets Act enforcement intensity or FTC Section 5 scrutiny scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
Programmatic Display Advertising Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
North America Advertising Market
Advertising and Marketing Media
Brazil OOH and DOOH Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Europe Programmatic Advertising Market