
 Social Media Advertisement Market | 2026-2036
Social Media Advertisement Market Size, Share, and Industry Trends Forecast 2026-2036
Social Media Advertisement Market Analysis
Self-serve ad bundling is realigning how small and mid-sized buyers access inventory. Meta Platforms leverages its consolidated campaign tools to simplify cross-platform placement. Google sustains dominance through search-to-social retargeting integration. ByteDance competes aggressively via short-form video inventory that captures mobile-native attention spans.
Social media advertisement denotes paid promotional content distributed through interactive digital platforms, typically priced on auction-based cost-per-impression or cost-per-click mechanisms and optimized through algorithmic audience matching. Its primary commercial purpose is to convert granular user behavioral data into measurable brand awareness or direct-response outcomes. Video ads and stories ads command premium placement rates as brands chase immersive formats, while carousel ads retain utility for product catalogs and sequential storytelling. User-generated content represents the fastest-growing content type as authenticity metrics outperform polished creative in engagement algorithms.
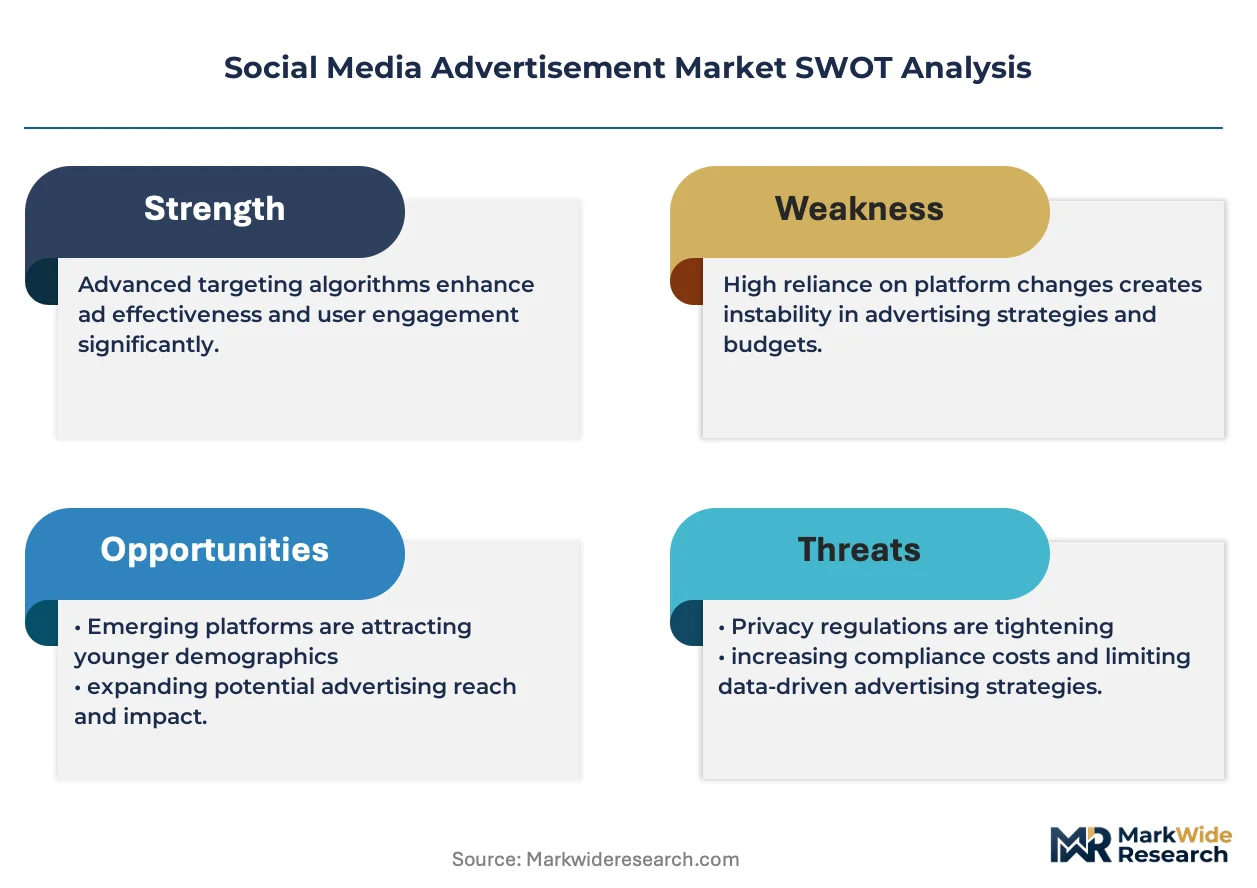
The EU Digital Services Act and GDPR impose transparency obligations on ad targeting and data processing, compelling platforms to redesign consent flows and limit granular profiling. The US FTC scrutinizes influencer disclosure practices and deceptive ad labeling across social channels. Stakeholders must monitor evolving platform-specific enforcement patterns and preemptively restructure attribution models before compliance deadlines harden into operational constraints.
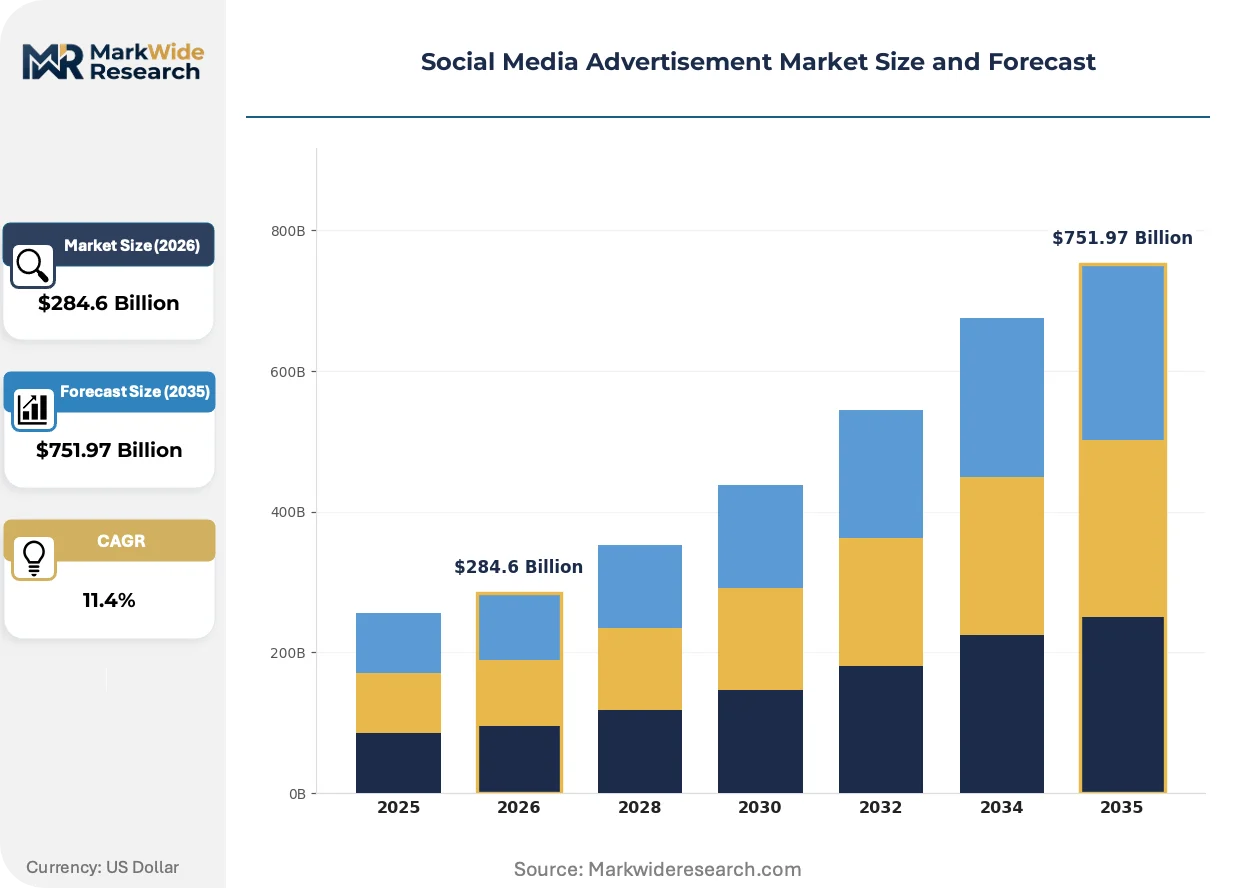
Market Dynamics
Algorithmic auction pricing and first-party data deprecation are compressing margins while forcing advertisers to rebuild attribution models around probabilistic rather than deterministic measurement frameworks.
Growth Catalysts
- India Mobile-First Expansion:Smartphone penetration in tier-2 and tier-3 cities creates addressable audiences previously unreachable through traditional media channels.
- EU Digital Services Act:Transparency mandates on ad targeting are accelerating investment in contextual and cohort-based alternatives to cookie-dependent strategies.
- Short-Form Video Inventory:ByteDance and Meta's Reels units command premium CPMs as brands reallocate television budgets toward mobile-native attention capture.
Market Restraints
- First-Party Data Scarcity:Apple's App Tracking Transparency and Google's Privacy Sandbox eliminate granular user-level tracking that powered performance optimization.
- Creative Production Costs:Platform-native formats require continuous asset iteration, inflating operational overhead for mid-sized advertisers without in-house studio capabilities.
- Platform Concentration Risk:Meta and Google capture over seventy percent of digital ad spend in most Western markets, creating single-source dependency.
Strategic Opportunities
- Brazil Connected TV Integration:Smart TV penetration enables social platforms to extend retargeting into living-room screens, bridging mobile and television measurement.
- Indonesia Creator Economy Infrastructure:Micro-influencer networks and shoppable livestreams unlock direct-response commerce at scale in Southeast Asia's largest economy.
- AI-Generated Creative Tools:Generative text-to-image and video synthesis reduce production timelines from weeks to hours for personalized ad variants.
Industry Challenges
- Attribution Engineering Talent:Probabilistic measurement requires data scientists capable of building media mix models, a skill set scarce outside top-tier agencies.
- Cross-Platform Identity Resolution:Advertisers struggle to unify fragmented user journeys across walled gardens without violating emerging privacy regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Media Advertisement Market |
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $751.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Image Ads, Video Ads, Carousel Ads, Stories Ads Target Audience: Millennials, Gen Z, Professionals, Small Business Owners Platform Type: Facebook, Instagram, Twitter, LinkedIn Content Type: Promotional Content, Educational Content, User-Generated Content, Brand Storytelling |
| Companies Covered | Meta Platforms, Google, Amazon, ByteDance, Microsoft, Snap, X Corp, LinkedIn, Publicis Groupe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Media Advertisement Market Emerging Trajectories
Retail media networks and social commerce infrastructure are dissolving the boundary between content consumption and transaction completion, reshaping how inventory is valued and sold.
Server-side ad insertion is unifying programmatic delivery across in-feed, stories, and connected television environments. Publishers and platforms are adopting this architecture to bypass client-side blocking and improve load latency. The technology is compressing the distinction between social and streaming video ad units, enabling buyers to execute cross-format campaigns through single insertion orders.
GDPR enforcement actions by CNIL and other European data protection authorities are tightening consent requirements for real-time bidding. Platforms must now document lawful basis for every impression transaction, increasing compliance overhead. Advertisers targeting EU audiences are restructuring data processing agreements and reducing reliance on behavioral signals in favor of contextual and declared-interest targeting.
Self-serve buying interfaces are displacing managed service relationships among mid-market advertisers. Direct platform access enables real-time budget reallocation and creative testing without agency intermediation. This pattern is most visible in North America and Western Europe, where marketing operations teams have built internal capabilities previously outsourced to media buying specialists.
Social Media Advertisement Market Segmentation
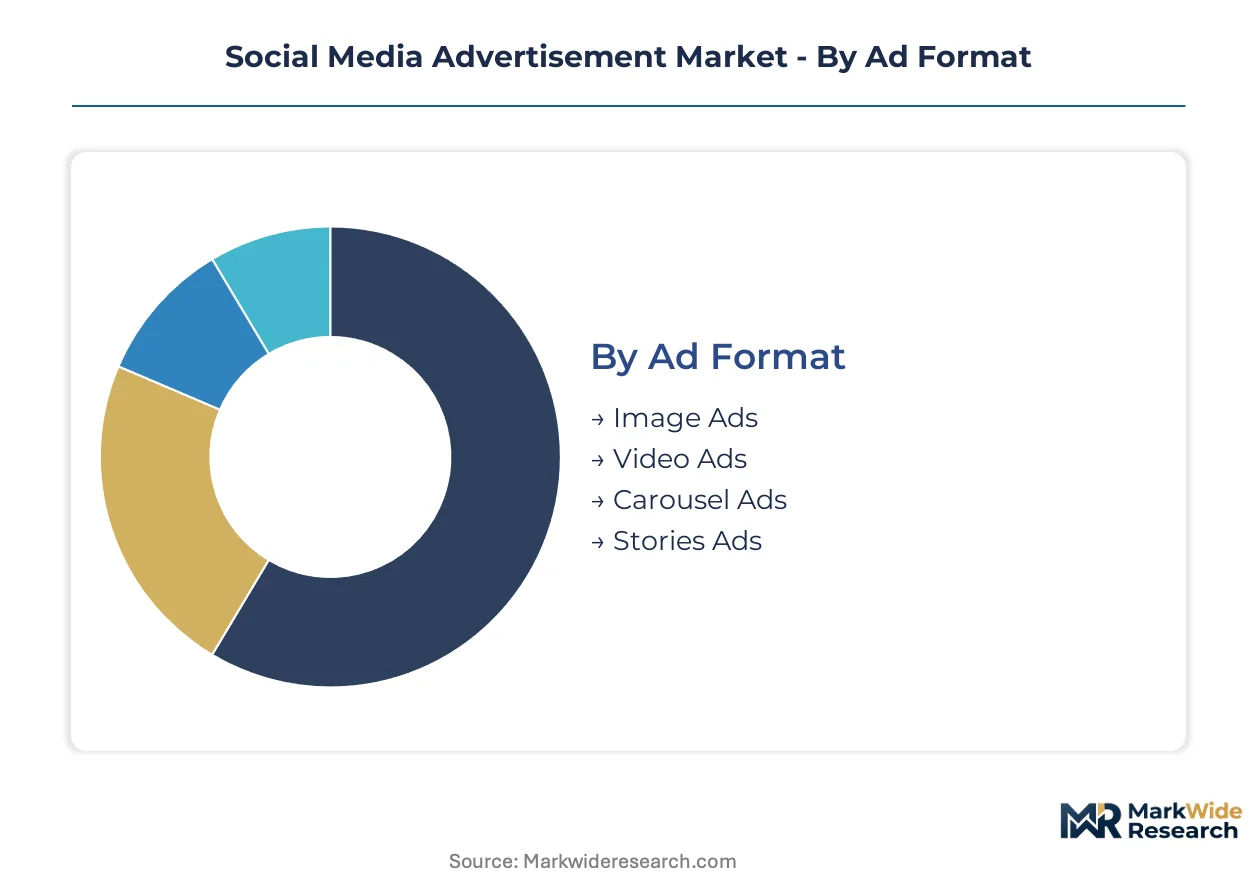
Social media advertisement inventory fragments across format, audience, platform, and content dimensions. Buyers optimize campaign performance by matching creative specifications to platform-native consumption patterns and demographic concentration.
Ad Format:
Cost tier separates buyers in this category, with premium formats commanding dedicated production budgets and higher CPM floors.
- Video Ads:Full-motion creative with sound-on autoplay defaults, typically 15-60 seconds in duration. Demand concentrates in India and Brazil as mobile-first users consume vertical video during commute windows; ByteDance and Meta Reels inventory drives premium placement rates.
- Stories Ads:Ephemeral full-screen vertical units with 24-hour expiration and interactive sticker overlays. Advertisers in Indonesia and tier-2 Indian cities chase Stories inventory for uncluttered attention capture; swipe-up mechanics enable direct-response attribution without landing page friction.
- Image Ads:Static single-frame placements optimized for feed scrolling behavior. Budget-conscious SMB buyers in Brazil default to image units for prospecting campaigns.
- Carousel Ads:Multi-card sequential formats supporting product catalogs and narrative progression. E-commerce brands in India deploy carousels for sequential storytelling across price tiers.
Volume sits with Image Ads; growth tilts toward Video Ads.
Target Audience:
Application context distinguishes buyers, with B2B and B2C advertisers pursuing entirely different platform and creative strategies.
- Gen Z:Digital natives aged 18-26 with platform-native content literacy and skepticism toward polished creative. Demand clusters in Indonesia and Brazil where TikTok and Instagram Reels dominate daily screen time; authenticity algorithms favor user-generated content over studio production.
- Professionals:White-collar workers reachable through career-oriented platforms during business hours. LinkedIn campaigns in India target IT services and fintech sectors; lead generation forms reduce friction for high-consideration B2B offers.
- Millennials:Users aged 27-42 with established purchase power and family formation lifecycle triggers. Parenting and financial services brands in Brazil prioritize millennial segmentation for mortgage and insurance products.
- Small Business Owners:Self-employed operators seeking local customer acquisition and foot traffic. Meta's self-serve tools in India enable direct campaign management without agency intermediation.
Millennials generate the highest impression volume; Gen Z shows the steepest expansion trajectory.
Platform Type:
Customer type determines platform selection, with enterprise advertisers and SMBs accessing entirely different buying interfaces and measurement capabilities.
- Instagram:Visual-first platform with Reels, Stories, and Shopping integration. Fashion and beauty brands in Brazil and Indonesia concentrate spend here; shoppable posts collapse discovery-to-purchase friction.
- Facebook:Mature platform with superior targeting depth and lookalike audience tools. Political and cause-based advertisers in India leverage Facebook's granular interest layering for voter mobilization.
- LinkedIn:Professional network with job-title and company-size targeting. SaaS vendors and executive education providers in India allocate premium CPMs for decision-maker reach.
- Twitter:Real-time conversation platform with keyword and event-based targeting. News publishers and sports brands in Brazil activate around live cultural moments.
Facebook retains impression dominance; Instagram gains share fastest among new campaign launches.
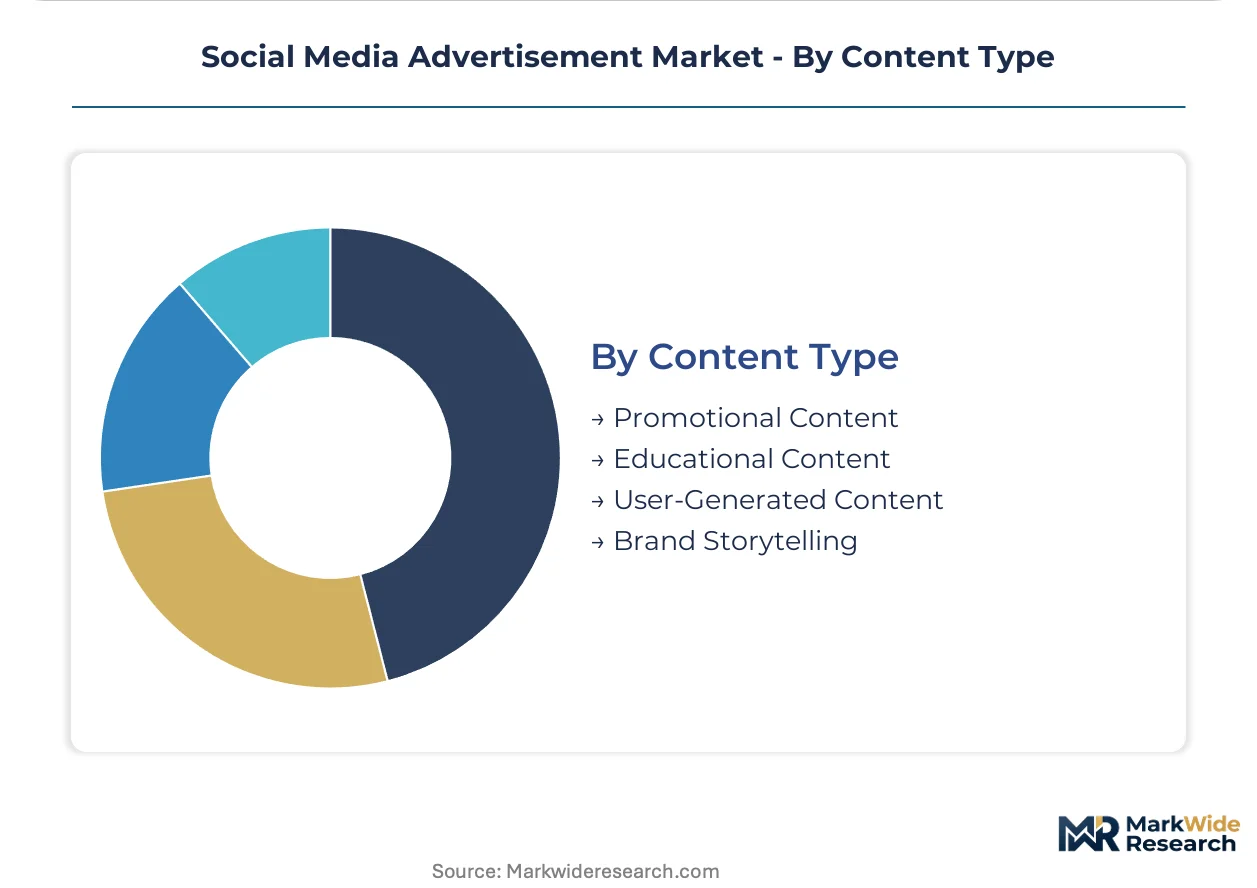
Content Type:
Supply concentration shapes this category, with platform algorithms distributing reach unequally across content production models.
- User-Generated Content:Organic-style creative produced by creators or customers rather than brand studios. Performance marketers in Indonesia and Brazil prioritize UGC for engagement rate optimization; authenticity signals outperform polished creative in algorithmic ranking.
- Brand Storytelling:Narrative-driven long-form content emphasizing values and origin narratives. Luxury and DTC brands in India deploy storytelling for consideration-phase cultivation.
- Promotional Content:Direct offer messaging with price, discount, and urgency triggers. E-commerce flash sale campaigns in Brazil rely on promotional density for conversion velocity.
- Educational Content:How-to and explainer formats building category authority. Fintech and health tech brands in India use educational sequencing to overcome trust barriers.
Promotional Content commands current spend volume; User-Generated Content climbs the fastest as platform algorithms reweight authenticity signals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertiser spend concentrates in markets with mobile-first populations and maturing digital payment infrastructure, while regulatory complexity fragments campaign execution across jurisdictions. The United States generates the highest absolute ad revenue, though growth rates now lag emerging economies. Europe enforces the strictest transparency mandates, reshaping how platforms process behavioral data.
United States
Enterprise advertisers and direct-to-consumer brands drive platform revenue through self-serve buying interfaces. The FTC scrutinizes influencer disclosure practices and deceptive ad labeling, compelling platforms to redesign native content markers. New York and Los Angeles anchor creative production clusters where agencies build in-house studios for platform-native asset iteration.
India
Smartphone penetration in tier-2 and tier-3 cities creates addressable audiences previously unreachable through traditional media. The Digital Personal Data Protection Act imposes consent requirements on behavioral targeting, forcing advertisers toward contextual alternatives. Mumbai and Bengaluru concentrate demand from e-commerce and fintech sectors deploying vernacular-language video campaigns.
Brazil
Connected TV integration enables social platforms to extend retargeting into living-room screens, bridging mobile and television measurement. ANVISA and consumer protection agencies monitor health and financial product advertising for misleading claims. São Paulo anchors the creative economy where micro-influencer networks unlock direct-response commerce at scale.
Indonesia
Shoppable livestreams and creator economy infrastructure transform content consumption into transaction completion. The Ministry of Communication and Informatics enforces content moderation rules that affect ad placement eligibility. Jakarta and Surabaya concentrate demand from consumer brands chasing Gen Z engagement through user-generated content formats.
Germany
B2B advertisers allocate premium budgets for professional network targeting in Europe's largest economy. The GDPR and Digital Services Act impose documentation requirements for every impression transaction, increasing compliance overhead. Berlin and Munich host data engineering clusters where advertisers rebuild attribution models around probabilistic measurement frameworks.
Social Media Advertisement Market Vendor Landscape
The competitive structure tilts toward platform conglomerates with consolidated campaign tools and proprietary audience data. Two strategic archetypes dominate: algorithmic auction platforms that monetize attention through automated bidding, and creative infrastructure providers that reduce production friction for advertisers. Competitive moves center on cross-platform identity resolution capabilities and generative creative tool integration.
Among the algorithmic auction platforms, Meta Platforms, Google, and ByteDance exemplify divergent approaches to attention capture. Meta leverages consolidated campaign tools across its family of apps to simplify cross-platform placement for mid-market buyers. Google sustains dominance through search-to-social retargeting integration that unifies intent signals across environments. ByteDance competes aggressively via short-form video inventory optimized for mobile-native consumption patterns in emerging economies.
| Leading Market Players |
|---|
| Meta Platforms |
| Amazon |
| ByteDance |
| Microsoft |
| Snap |
| X Corp |
| Publicis Groupe |
| Others |
Supply Flow & Price Mechanics
EU Digital Services Act transparency mandates gate qualified inventory access and premium-tier CPM placement for advertisers demonstrating compliant consent architecture. Advertisers lacking documented lawful basis for impression transactions face exclusion from high-value auction pools, compressing effective supply and sustaining rate floors for verified participants.
Pricing Analysis
Margin tightening in mid-market buyer tiers reflects algorithmic auction density and first-party data depreciation costs. Three-tier pricing structure across premium video, standard feed placement, and economy remnant inventory separates buyers by production capability and measurement sophistication. Price differentiation traces to creative format complexity and cross-platform attribution depth. SMB advertisers in Brazil and India exhibit highest price sensitivity, while enterprise DTC brands absorb premium rates for Reels and Stories inventory.
Supply Chain Analysis
Dual-sourcing requirements for impression verification now mandate redundant measurement provider qualification across Meta, Google, and ByteDance inventory pools. Supply concentrates in United States, Ireland, and Singapore data center clusters hosting auction infrastructure. Raw material dependencies span GPU compute capacity, subsea cable bandwidth, and renewable energy procurement for carbon-neutral ad serving. Single-source vulnerability concentrates in Meta-Google duopoly for Western auction liquidity. Distribution runs through self-serve APIs and managed service desks with divergent fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Attribution engineering talent scarcity props pricing power for platforms offering probabilistic measurement tools. Qualified data scientist availability constrains advertiser migration to privacy-compliant campaign architectures.
For Market Incumbents: Extend first-party data infrastructure through server-side conversion APIs and clean room partnerships. Consolidate cross-platform identity graphs before regulatory fragmentation hardens. Threat substitution from TikTok Shop commerce integration demands defensive shoppable format deployment. Lever investment in Brazil and Indonesia creator economy tooling to lock micro-influencer supply. For New Entrants and Emerging Players: Launch via vertical-specific self-serve interfaces targeting SMB advertisers abandoned by agency intermediation. White-space concentrates in tier-2 Indian city vernacular video production and Indonesia shoppable livestream infrastructure. Go-to-market angle: AI-generated creative variant tools reducing production timelines from weeks to hours for resource-constrained buyers. For Investors and Strategic Acquirers: CNIL enforcement actions escalating to platform fines are the leading indicator that probabilistic attribution startups command premium multiples. Long-term viability frames around privacy-preserving measurement stack ownership. Acquisition target archetype: mid-cap MMM vendors with CPG client concentration. Signal to watch: platform disclosure of consent-rate degradation in EU auction pools.| Strategic Initiative | Industry Significance |
|---|---|
| Server-Side Conversion API Deployment | Meta's CAPI and Google's Enhanced Conversions bypass iOS ATT signal loss for deterministic attribution. |
| Clean Room Data Partnership | Advertiser-first-party data activation through Amazon Marketing Cloud and Google Ads Data Hub rebuilds audience graphs. |
| AI Creative Generation Platform | Text-to-video synthesis from Runway and Pika Labs collapses production cost curves for personalized variant testing. |
| Creator Economy Infrastructure Buildout | Indonesia and Brazil micro-influencer networks unlock direct-response commerce at CAC levels below feed advertising. |
| Connected TV Retargeting Integration | Brazil smart TV penetration enables social platforms to bridge mobile and living-room measurement for unified frequency capping. |
Methodological Framework
Platform transparency reports, SEC 10-K advertising revenue disclosures, and EU Digital Services Act compliance filings formed the secondary backbone of this analysis. Primary interviews with programmatic trading desk directors, ad operations leads at DTC brands, privacy counsel at major platforms, and measurement vendor product managers validated auction dynamics and consent architecture deployment. Bottom-up impression volume estimates triangulated against top-down platform revenue disclosures.
Historical trendline analysis of CPM trajectories and auction fill rates informed the projection framework across the analysis window. Segmentation dimensions modeled include ad format type, target audience demographic, platform environment, and content production model. CAGRs derived from regression of smartphone penetration curves against social commerce GMV growth. Forecast inputs incorporated Digital Personal Data Protection Act implementation timelines and Privacy Sandbox deprecation schedules.
The model assumes a particular technology adoption path; alternative pathways for on-device attribution and differential privacy would alter the outlook for probabilistic measurement vendor demand. Deviation in regulatory enforcement intensity across CNIL, FTC, and emerging market data protection authorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Europe Public Relation Services Market
Advertising and Marketing Media
Digital Ad Spending Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Italy OOH and DOOH Market