
 Programmatic Display Advertising Market | 2026-2036
Programmatic Display Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Programmatic Display Advertising Market Analysis
Buyer concentration among retail advertisers is recalibrating how demand-side platforms allocate engineering resources and sales coverage. The Trade Desk leverages its unified ID framework to sustain independent identity resolution outside walled gardens. Google Display & Video 360 anchors the largest share of authenticated inventory through its integration with Google Marketing Platform. Amazon DSP competes by controlling closed-loop attribution from ad impression to purchase conversion.
Programmatic display advertising denotes the automated buying and selling of digital ad inventory through algorithmic auction mechanisms, typically executed within milliseconds via real-time bidding protocols that evaluate user signals against advertiser targeting criteria. Its primary commercial purpose is to match brand messages with specific audience segments at scale while optimizing cost-per-acquisition through continuous machine learning feedback. Video ads within the advertising format dimension command expanding budget allocation as connected television inventory migrates from linear to addressable streams. Real-time bidding retains volume leadership among buying types, though private marketplace arrangements capture disproportionate margin pools by offering preferred access to premium publisher inventory.
The Federal Trade Commission scrutinizes data brokerage practices and ad-tech intermediation under evolving consumer protection mandates, while the European Union's GDPR and Digital Markets Act constrain cross-border data flows and platform self-preferencing. These frameworks elevate compliance costs for smaller intermediaries while advantaging scaled platforms with dedicated privacy engineering teams. Stakeholders must monitor regulatory fragmentation between federal privacy legislation in the United States and sectoral state laws such as the California Consumer Privacy Act.
Market Dynamics
Google's deprecation of third-party cookies is forcing demand-side platforms to rebuild identity infrastructure around first-party data graphs and authenticated user signals, compressing the addressable audience pool while elevating data clean room investments.
Growth Catalysts
- Connected Television Migration:Streaming inventory is shifting from linear upfronts to programmatic pipes, opening addressable video budgets previously locked in broadcast commitments.
- Retail Media Networks:Closed-loop attribution from impression to purchase is pulling CPG advertisers off open-web exchanges into retailer-controlled programmatic environments.
- GDPR Enforcement:Consent-based data collection frameworks are advantaging publishers with direct reader relationships and registered user bases.
Market Restraints
- Identifier Deprecation:Apple's ATT framework and Google's Privacy Sandbox are collapsing deterministic targeting precision, forcing reliance on probabilistic modeling with degraded performance.
- Supply Path Optimization:Header bidding complexity and intermediary layering are compressing publisher yields while elevating take-rate scrutiny from buy-side auditors.
- Ad Fraud Infrastructure:Sophisticated invalid traffic schemes exploiting CTV measurement gaps are eroding advertiser confidence in emerging inventory pools.
Strategic Opportunities
- Commerce Media Expansion:Non-retail verticals including travel and financial services are building closed-loop programmatic stacks mirroring Amazon's attribution model.
- Privacy-Enhancing Technologies:Differential privacy and on-device learning are converging to enable cohort-based targeting without individual-level data export.
- India Digital Infrastructure:Unified Payments Interface integration is enabling real-time purchase signals for programmatic optimization in emerging digital commerce markets.
Industry Challenges
- Identity Resolution Talent:Shortage of engineers skilled in probabilistic graph construction and differential privacy implementation is constraining platform R&D velocity.
- Cross-Border Data Architecture:Fragmentation between GDPR adequacy decisions and emerging national data localization laws is complicating global campaign orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmatic Display Advertising Market |
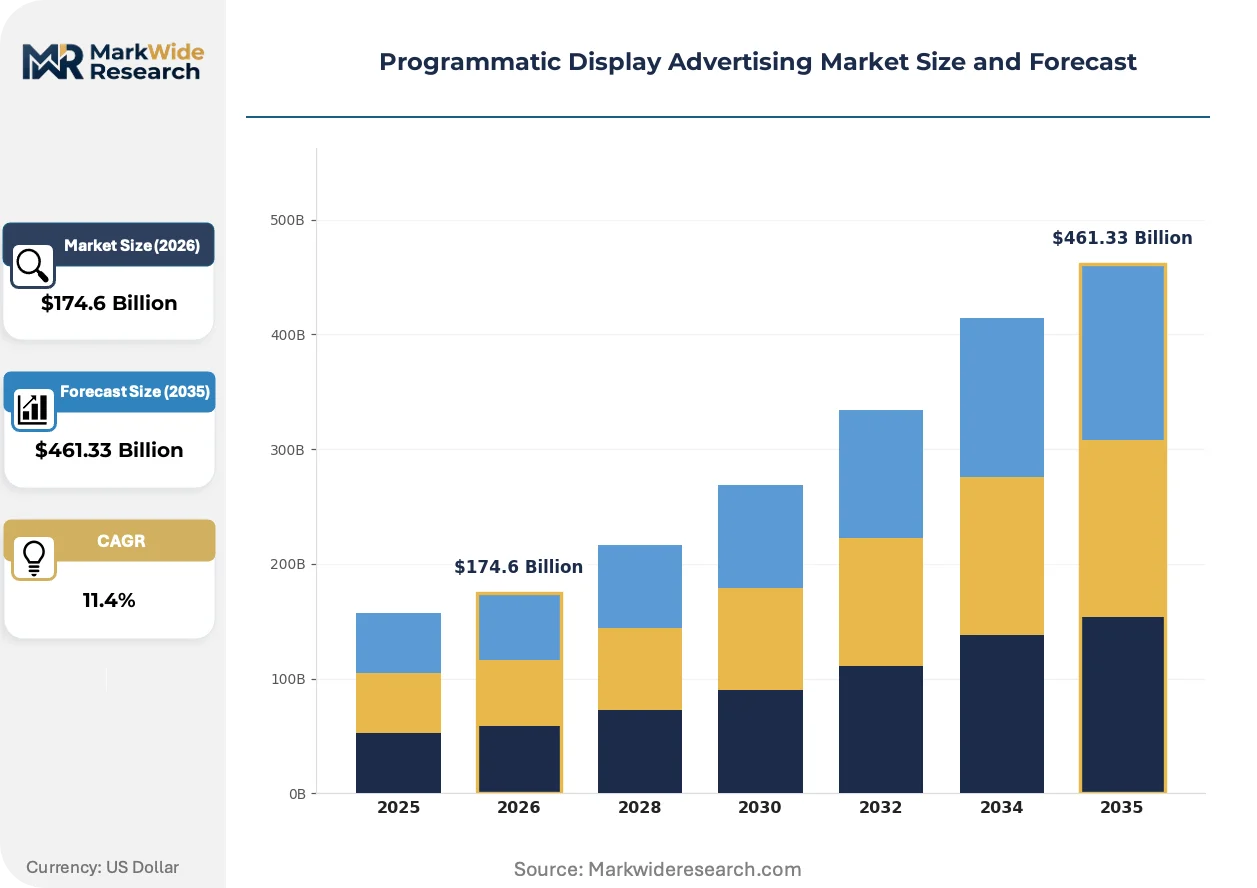
| Market Size in 2026 | $174.6 Billion |
| Market Size in 2035 | $461.33 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Advertising Format: Banner Ads, Video Ads, Native Ads, Rich Media Target Audience: Retail Customers, B2B Clients, Mobile Users, Millennials Buying Type: Real-Time Bidding, Programmatic Direct, Private Marketplace, Guaranteed Industry Vertical: E-commerce, Travel, Automotive, Entertainment |
| Companies Covered | The Trade Desk, Google Display & Video 360, Amazon DSP, MediaMath, Adobe Advertising Cloud, Adform, Amobee, Magnite, PubMatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmatic Display Advertising Market Emerging Trajectories
Algorithmic auction mechanics are migrating from second-price to first-price clearing, compressing bid shading strategies while elevating transparency demands from agency trading desks.
Server-side ad insertion is rewriting how connected television inventory is monetized, eliminating client-side latency that previously degraded viewer experience. Broadcasters including NBCUniversal and Paramount are adopting SSAI infrastructure to compete with native streaming platforms for programmatic video budgets. The technology is rewriting competitive positioning by collapsing the technical distinction between linear and digital video buying workflows.
The Digital Markets Act is constraining self-preferencing in ad-tech stacks, forcing platform operators to separate data access between owned inventory and third-party demand. European publishers are gaining portability rights for audience data previously locked in walled garden environments. Smaller demand-side platforms are responding by building interoperable identity frameworks that comply with DMA interoperability mandates.
Outcome-based buying models are displacing impression-based guarantees in CTV negotiations, with advertisers paying only on verified incremental lift rather than completed views. Agency holding companies are restructuring trading desk compensation around these performance metrics. This shift is most visible in the United States, where retail advertisers with closed-loop measurement are extracting favorable terms from broadcasters desperate for streaming revenue.
Programmatic Display Advertising Market Segmentation
Segmentation in programmatic display advertising determines how inventory is priced, targeted, and transacted. Advertisers align budget allocation with format performance and audience addressability, while publishers optimize yield across buying mechanisms.
Advertising Format:
Technology specifications differentiate creative capabilities and measurement fidelity across inventory types.
- Video Ads:Server-side ad insertion eliminates latency in connected television streams. Demand concentrates among retail advertisers in the United States seeking closed-loop attribution from impression to purchase.
- Native Ads:Format-matching algorithms render sponsored content within editorial feeds without disrupting user experience. Publishers with registered user bases leverage this inventory for consent-based targeting under GDPR enforcement.
- Banner Ads:Standard display units remain the volume foundation of open-web exchanges.
- Rich Media:Interactive creative formats enable expandable units and engagement metrics beyond viewability.
Video ads lead on scale; native ads lead on momentum.
Target Audience:
Cost tier segmentation separates premium authenticated segments from probabilistically modeled pools.
- Retail Customers:First-party data graphs from loyalty programs enable deterministic targeting. E-commerce platforms monetize this segment through retail media networks with closed-loop purchase attribution.
- Mobile Users:On-device signal processing supports cohort-based targeting without individual-level data export. India's Unified Payments Interface integration is enabling real-time purchase signals for programmatic optimization.
- B2B Clients:Account-based targeting relies on firmographic data matched against IP addresses and device graphs.
- Millennials:Streaming-native consumption patterns concentrate video ad demand on connected television inventory.
Retail customers command premium rates; mobile users are climbing the fastest as identifier deprecation elevates on-device targeting.
Buying Type:
Volume and margin distribution vary sharply across transaction mechanisms.
- Real-Time Bidding:Open auction protocols process billions of impressions daily through algorithmic evaluation. Header bidding complexity has elevated supply path optimization scrutiny from buy-side auditors.
- Private Marketplace:Curated inventory access commands disproportionate margin pools through preferred publisher relationships. Broadcasters including NBCUniversal and Paramount leverage PMP arrangements for streaming video budgets.
- Programmatic Direct:Automated guaranteed deals combine workflow efficiency with fixed price certainty.
- Guaranteed:Upfront commitments preserve traditional media planning structures within automated execution.
Real-time bidding dominates transaction volume; private marketplace gains share fastest as premium inventory scarcity intensifies.
Industry Vertical:
Application-specific use cases drive divergent data infrastructure investments.
- E-commerce:Product catalog feeds enable dynamic creative optimization tied to real-time inventory availability. Amazon DSP anchors closed-loop attribution from ad impression to purchase conversion.
- Automotive:Dealer-level targeting requires integration with customer relationship management systems and financing pre-qualification data.
- Travel:Non-retail verticals are building closed-loop programmatic stacks mirroring Amazon's attribution model for booking conversion measurement.
- Entertainment:Content release windows create concentrated demand spikes requiring rapid audience scaling.
E-commerce leads on data infrastructure spend; travel is expanding most quickly as vertical-specific attribution platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium programmatic rates through connected television inventory, while Germany enforces stricter consent frameworks that reshape data infrastructure investments across the European market.
United States
Retail media networks and CTV inventory concentration drive disproportionate demand from CPG advertisers seeking closed-loop attribution. The FTC scrutinizes data brokerage practices under evolving consumer protection mandates. New York and Los Angeles anchor the largest agency trading desk clusters, where broadcasters including NBCUniversal compete for streaming video budgets.
Germany
GDPR enforcement elevates compliance costs while advantaging publishers with registered user bases and direct reader relationships. The Digital Markets Act constrains platform self-preferencing, forcing interoperability in ad-tech stacks. Berlin and Hamburg host emerging demand-side platforms building authenticated identity frameworks compliant with DMA mandates.
United Kingdom
Agency holding companies restructure trading desk compensation around outcome-based CTV buying models. The Information Commissioner's Office enforces consent-based data collection through the UK GDPR framework. London concentrates independent programmatic consultancies advising brands on supply path optimization strategies.
India
Unified Payments Interface integration enables real-time purchase signals for programmatic optimization in digital commerce markets. The Telecom Regulatory Authority of India governs data localization requirements for cross-border ad-tech operations. Mumbai and Bangalore anchor retail media network expansion as non-retail verticals build closed-loop attribution stacks.
Japan
Streaming-native consumption patterns concentrate video ad demand on addressable television inventory migrating from linear commitments. The Ministry of Economy, Trade and Industry promotes privacy-enhancing technology standards for cohort-based targeting. Tokyo hosts trading desk operations for multinational brands seeking deterministic measurement in cookie-constrained environments.
Programmatic Display Advertising Market Vendor Landscape
United States platforms anchor the demand-side tier; European specialists hold differentiated positions in consent-first infrastructure. The vendor base stratifies across walled garden operators, independent identity resolution providers, and supply-side intermediaries. Three archetypes dominate: authenticated inventory aggregators, first-party data infrastructure builders, and closed-loop attribution specialists. M&A activity concentrates on identity graph assets and clean room technologies, while geographic expansion targets India and Southeast Asia for digital commerce signal integration.
Within the independent demand-side tier, The Trade Desk exemplifies unified identity framework positioning outside walled garden environments. Google Display & Video 360 occupies a scale-driven position anchored to Google Marketing Platform integration. Amazon DSP represents the closed-loop attribution archetype controlling purchase conversion measurement from impression to transaction.
| Leading Market Players |
|---|
| The Trade Desk |
| Google Display & Video 360 |
| Amazon DSP |
| MediaMath |
| Adobe Advertising Cloud |
| Adform |
| Amobee |
| Magnite |
| PubMatic |
| Others |
Supply Flow & Price Mechanics
Authenticated inventory scarcity against open-exchange commoditization splits the market into divergent margin structures, with premium private marketplace placements commanding five to fifteen times the effective CPM of remnant banner inventory while supply chain concentration in cloud infrastructure and SSP consolidation shapes who captures that spread.
Pricing Analysis
Capacity additions in server-side ad insertion infrastructure are reshaping price floors for connected television inventory as broadcasters compete with native streaming platforms. Pricing stratifies across premium guaranteed, private marketplace, and open auction tiers, with differentiation driven by viewability certification and closed-loop attribution depth. Cost compression in open-exchange display stems from header bidding complexity and intermediary layering. Retail advertisers with first-party data assets show least price sensitivity; mid-market performance marketers face acute pressure.
Supply Chain Analysis
Dual-sourcing requirements from agency holding companies now mandate qualification of at least two demand-side platforms and two supply-side platforms per major campaign. Supply concentrates in the United States for cloud infrastructure, Ireland and the Netherlands for EU data residency compliance, and India for engineering talent pools. Raw material dependencies span data center compute, bandwidth transit agreements, and identity graph licensing. Tariff exposure sits with cross-border data flows under evolving localization mandates. Distribution runs through agency trading desks, direct advertiser relationships, and self-serve platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in programmatic display advertising rests on first-party data infrastructure depreciation and premium CTV inventory scarcity elevating effective CPMs for authenticated audiences.
For Market Incumbents: To counter identifier deprecation and collapsing deterministic targeting precision, fortify clean room partnerships with major retailers and accelerate probabilistic graph R&D. Prioritize supply path optimization tooling to capture intermediary compression value. For New Entrants and Emerging Players: Begin with commerce media verticals outside retail—travel, financial services, and telecom—where closed-loop attribution infrastructure remains underdeveloped. Target India and Southeast Asia for UPI-enabled real-time signal integration. Lead with privacy-enhancing technology differentiation under GDPR and DMA compliance. For Investors and Strategic Acquirers: Consolidation pressure builds where identity resolution talent scarcity constrains platform R&D velocity and data clean room assets command strategic premiums. Long-term viability favors authenticated inventory aggregators with direct publisher relationships. Watch for DMA interoperability mandate enforcement as inflection signal for European market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Investment | Google's Privacy Sandbox and Apple's ATT framework collapse third-party cookie utility, forcing deterministic signal rebuilding. |
| Retail Media Network Partnership | Amazon DSP's closed-loop attribution model pulls CPG budgets into retailer-controlled programmatic environments. |
| Server-Side Ad Insertion Deployment | NBCUniversal and Paramount adopt SSAI to eliminate latency and capture streaming video budgets from linear upfronts. |
| Privacy-Enhancing Technology Integration | Differential privacy and on-device learning enable cohort targeting without individual-level data export under GDPR. |
| Supply Path Optimization Platform | Header bidding complexity elevates buy-side auditor scrutiny, compressing publisher yields and intermediary take rates. |
Methodological Framework
Direct dialogue with demand-side platform product executives, supply-side platform yield managers, agency trading desk directors, and advertiser marketing science leads grounded qualitative findings, cross-referenced against SEC filings from publicly traded ad-tech firms, IAB measurement standards documentation, regulatory dockets from the FTC and European Commission, and cloud infrastructure capex disclosures. Bottom-up transaction volume estimates triangulated against top-down media spend allocations.
Segment-level outputs across advertising format, buying type, target audience, and industry vertical dimensions were generated through structured modeling across the projection horizon. CAGRs derived from historical growth rate analysis adjusted for identifier deprecation impact, retail media network expansion curves, and connected television inventory migration patterns. Forecast inputs incorporated GDPR enforcement intensity indices and DMA interoperability timeline assumptions.
Several conditions sit outside the modeled scope, including sudden regulatory bans on real-time bidding protocols, major platform acquisition blockage under antitrust review, and catastrophic ad fraud revelations eroding CTV measurement confidence. Deviation in Privacy Sandbox adoption velocity or ATT opt-in rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
Vietnam OOH and DOOH Market
Advertising and Marketing Media
Australia OOH and DOOH Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Programmatic Advertising Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Global Contextual Advertising Market
Advertising and Marketing Media
Native Video Advertising Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Russia OOH and DOOH Market