
 South East Asia Digital Out-Of-Home (Dooh) Market | 2026-2036
South East Asia Digital Out-Of-Home (Dooh) Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Digital Out-Of-Home (Dooh) Market Analytics
Programmatic inventory pipelines across ASEAN urban centers are reshaping how media buyers access roadside and transit screen networks. JCDecaux leverages its airport and street furniture concessions across Singapore and Bangkok to sustain premium rate card positioning. Plan B Media Public Company Limited anchors Thailand's out-of-home infrastructure through exclusive mall and BTS station contracts. oOh!media Limited competes in the premium transit vertical with digital rail platform dominance in Australian-ASEAN corridor strategies.
Digital Out-Of-Home (Dooh) encompasses networked electronic display systems deployed in public environments, typically operating at 500–5,000 nits brightness with IP65-rated weatherproofing for tropical climates, delivering advertiser content via cellular or fiber-connected content management platforms to audiences in transit, retail, and leisure contexts. LED Displays command the highest hardware investment intensity due to fine-pitch cabinet costs and installation complexity in humid equatorial conditions. Programmatic advertising models are expanding fastest as demand-side platforms integrate with supply-side ad servers, though Direct Sales still captures the largest share of contracted annual revenue from multinational FMCG buyers.
TRAI content guidelines influence broadcaster-adjacent screen regulation in markets like Indonesia and Malaysia, while Singapore's PDPC enforces personal data handling standards that constrain facial analytics and mobile retargeting integrations. Thailand's NBTC maintains broadcast spectrum coordination rules that affect transit network connectivity reliability. Stakeholders must weigh hardware refresh cycles against evolving local content certification requirements and platform interoperability standards.
Market Dynamics
Programmatic trading infrastructure is compressing media buying cycles across South East Asia's fragmented screen networks, forcing inventory aggregation and real-time pricing transparency that legacy direct-sales models cannot match.
Growth Catalysts
- Urban Transit Buildouts:Vietnam's metro expansion and Jakarta's MRT extensions are creating captive audience environments with high dwell times, attracting premium advertiser commitment to rail platform networks.
- PDPC Data Frameworks:Singapore's personal data protection standards, while constraining facial analytics, are legitimizing anonymized mobile signal integration for audience measurement, accelerating programmatic adoption.
- LED Fine-Pitch Maturation:SMD packaging advances are reducing cabinet costs for outdoor-rated displays, enabling roadside digitization in secondary Thai and Indonesian cities previously priced out of hardware conversion.
Market Restraints
- Power Infrastructure Variability:Unreliable grid supply in Philippine and Indonesian secondary markets necessitates costly UPS and generator redundancy, elevating total cost of ownership for 24/7 operations.
- TRAI-Inspired Content Certification:Indonesian and Malaysian broadcast-adjacent regulators are imposing pre-approval workflows for dynamic creative, adding 48-72 hour latency to campaign activation.
- Hardware Import Dependence:Fine-pitch LED modules and driver ICs concentrate in Chinese manufacturing clusters, exposing ASEAN deployers to tariff volatility and shipping bottlenecks through Singapore transshipment ports.
Strategic Opportunities
- Retail Media Convergence:Mall operators in Bangkok and Manila are opening in-house retail media networks, creating first-party data partnerships that bypass traditional media agency intermediation.
- NBTC Spectrum Coordination:Thailand's broadcast regulator is harmonizing 5G small-cell and transit network frequencies, enabling reliable cellular backhaul for roadside screens without fiber trenching costs.
- Programmatic Guaranteed Contracts:FMCG buyers are migrating from annual fixed commitments to audience-guaranteed programmatic pipes, rewarding inventory aggregators with data management platform integration.
Industry Challenges
- Creative Technical Talent Scarcity:Dynamic content optimization for 500-5,000 nit brightness variation across daypart requires specialized motion design skills that Bangkok and Jakarta labor markets undersupply.
- Legacy CMS Integration Friction:Early-generation content management platforms in Malaysia's installed base lack OpenRTB protocol support, forcing parallel operation during multi-year refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Digital Out-Of-Home (Dooh) Market |
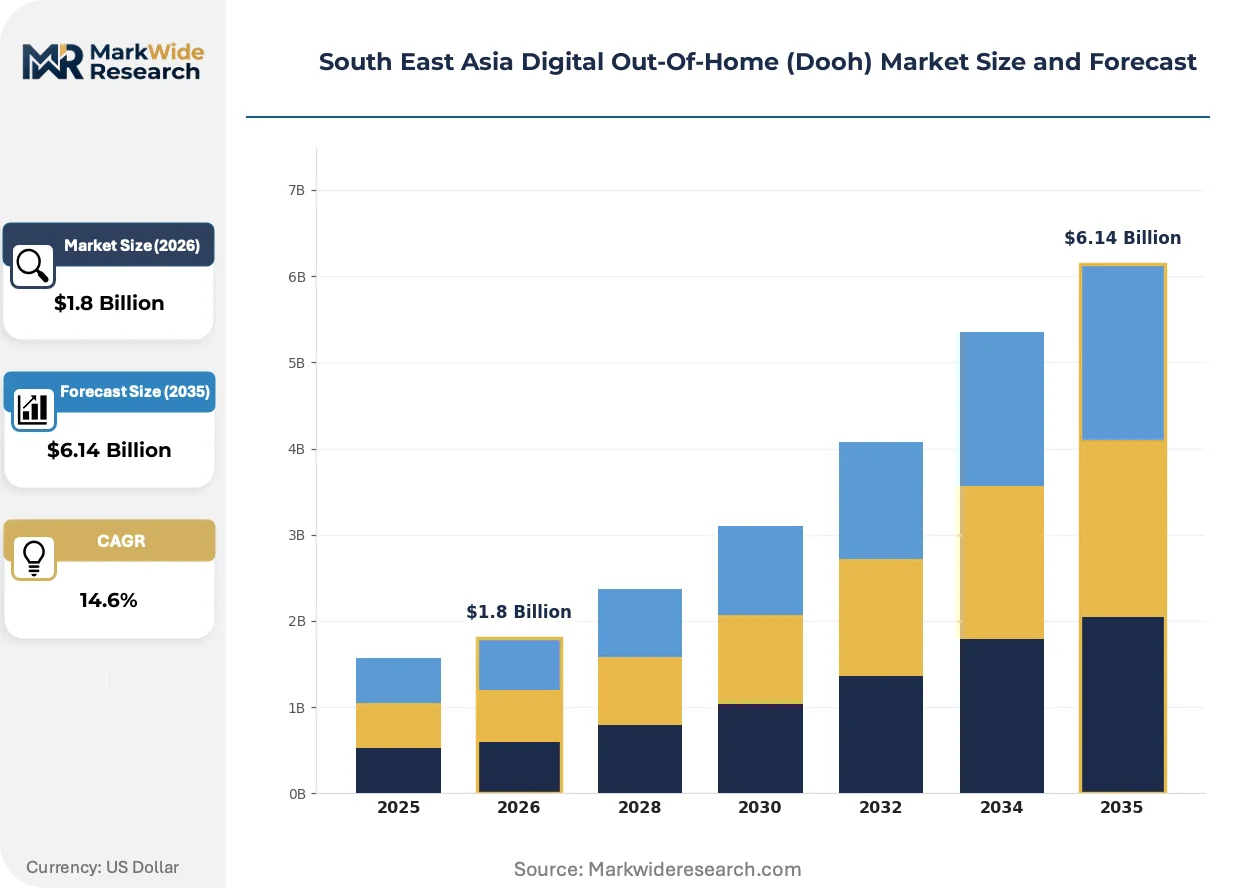
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Digital Billboards, LCD Screens, LED Displays, Interactive Kiosks Content Format: Video Ads, Static Ads, Audio Ads, Augmented Reality Placement Type: Street Furniture, Transit Stations, Malls, Arenas Advertising Model: Programmatic, Direct Sales, Auction-Based, Hybrid |
| Companies Covered | JCDecaux, Clear Channel Outdoor Holdings, Inc., Dentsu Group Inc., Hakuhodo DY Holdings Inc., oOh!media Limited, Hivestack Inc., Plan B Media Public Company Limited, Big Tree Outdoor Sdn. Bhd., Moove Media Pte Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Digital Out-Of-Home (Dooh) Market Evolving Landscape
Cloud-native ad serving is dissolving the boundary between digital out-of-home and mobile programmatic stacks, enabling unified audience planning across previously siloed channels.
Edge-computing content nodes are virtualizing the traditional centralized playout architecture. These distributed processing units cache and render creatives locally at screen sites, reducing backhaul bandwidth requirements by 60-70% for high-frequency dynamic campaigns. Transit operators in Singapore and Bangkok are deploying these nodes to support real-time trigger-based creative swaps tied to train arrival data, compressing latency to sub-second intervals that satellite-dependent systems cannot achieve.
TRAI-inspired content standards in Indonesia and Malaysia are mandating pre-certification workflows for all dynamic advertising copy. These regulations impose documentation burdens on creative agencies unfamiliar with broadcast-adjacent compliance, but they simultaneously erect barriers against low-quality inventory that protects premium rate card positioning for established network operators. Mall-based screens in Jakarta face the strictest enforcement timelines, with 72-hour approval windows becoming standard contractual terms.
Media buyers are consolidating vendor relationships around full-funnel attribution capabilities, displacing the historical focus on gross rating point equivalents. FMCG procurement teams in Manila and Ho Chi Minh City now require proof of store visit lift or sales impact as table stakes for annual commitment, forcing inventory owners to integrate with mobile location data providers and retail analytics platforms. This behavioral shift favors network operators with direct mall operator data partnerships over pure-play roadside inventory aggregators.
South East Asia Digital Out-Of-Home (Dooh) Market Segmentation
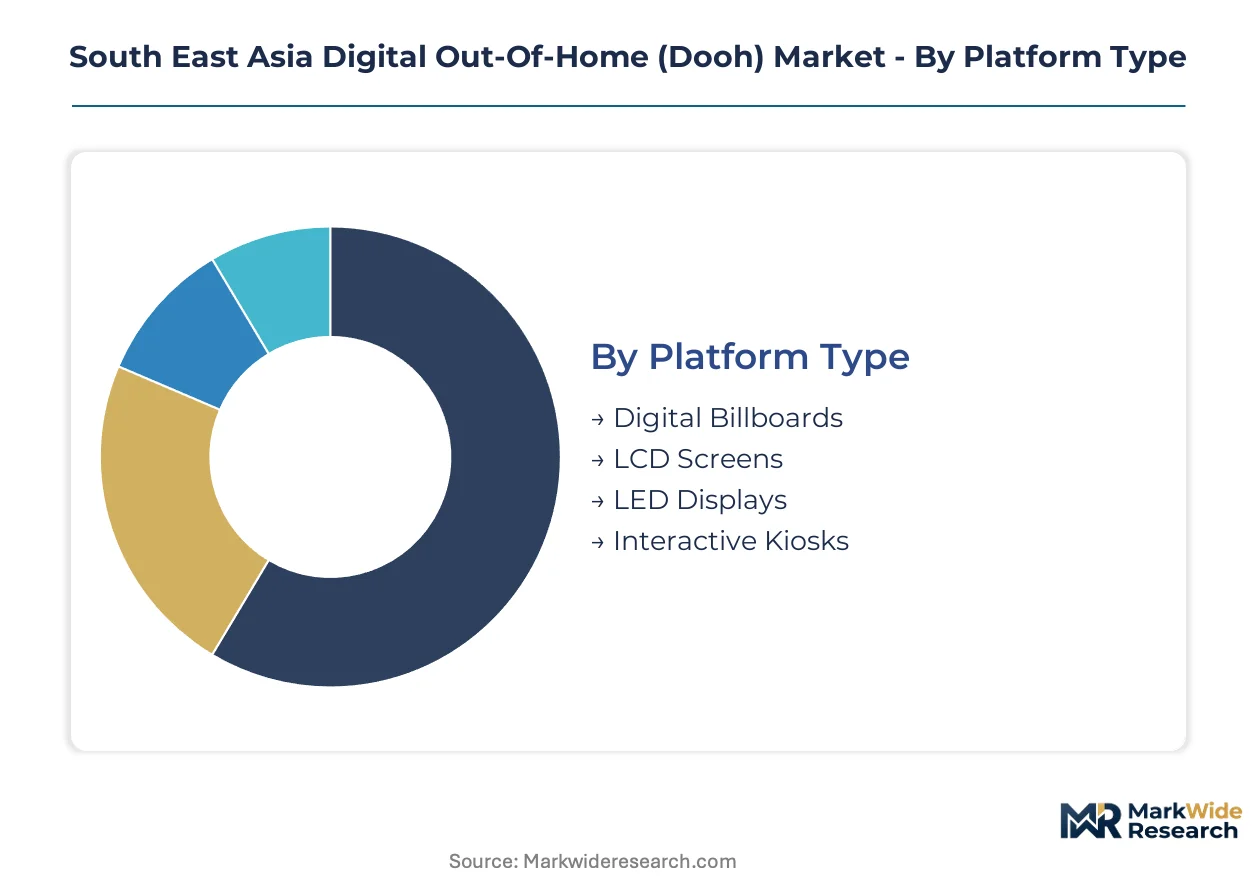
Platform heterogeneity across South East Asia's tropical climate zones and regulatory environments creates distinct deployment economics for network operators. Content format choices hinge on brightness requirements and dwell-time patterns in transit versus retail contexts. Placement and advertising model selections determine capital intensity and data partnership architectures.
Platform Type:
Use-case spectrum spans roadside visibility at 500-5,000 nits through climate-controlled indoor engagement.
- Digital Billboards:Large-format roadside installations utilizing SMD LED modules with IP65 weatherproofing for tropical humidity. Demand concentrates along Jakarta's toll corridors and Bangkok's Sukhumvit arterial, where 24/7 visibility commands premium rate cards despite grid reliability challenges requiring UPS redundancy.
- LED Displays:Fine-pitch cabinets with sub-4mm pixel density enabling close-proximity creative execution in retail environments. Vietnamese metro operators and Indonesian mall developers are prioritizing these for platform and atrium deployments where passenger dwell times exceed 90 seconds.
- LCD Screens:High-brightness panels with ambient light sensors for indoor transit and retail networks. Singapore's MRT stations and Manila's LRT-2 extensions specify these for energy-constrained underground environments.
- Interactive Kiosks:Touch-enabled units with integrated payment and wayfinding modules. Bangkok's BTS stations and Jakarta's MRT terminals are piloting these for retail media convergence, though PDPC-style data handling requirements constrain facial analytics integration.
Established volume favors Digital Billboards; emerging adoption favors LED Displays.
Content Format:
Cost tier differentiation separates high-production motion assets from rapid-deployment static frames.
- Video Ads:Motion creative optimized for 500-5,000 nit brightness variation across daypart, requiring specialized rendering pipelines. FMCG procurement teams in Ho Chi Minh City and Manila now mandate video-first commitments for annual network contracts, displacing legacy static-heavy schedules.
- Static Ads:JPEG/PNG frames with sub-100KB file sizes for low-bandwidth cellular backhaul environments. Philippine provincial networks and Indonesian secondary cities rely on these where fiber trenching costs prohibit real-time video streaming.
- Audio Ads:Synchronized sound zones in transit environments with directional speaker arrays. Singapore's Changi Airport and Bangkok's Suvarnabhumi concessions deploy these in gate hold rooms where captive audience metrics support premium pricing.
- Augmented Reality:Marker-triggered or location-based overlays requiring smartphone integration and edge-computing nodes. Mall operators in Jakarta's Grand Indonesia and Bangkok's Siam Paragon are testing these for first-party data capture, though TRAI-inspired certification workflows add 72-hour deployment latency.
Video Ads dominate contracted revenue; Augmented Reality is climbing the fastest.
Placement Type:
Geography-driven margin profiles separate high-dwell transit environments from high-frequency street furniture.
- Transit Stations:Rail platform and concourse networks with 3-15 minute average dwell times. Vietnam's metro expansion and Jakarta's MRT Phase 2 are creating new inventory clusters where audience measurement integrates with mobile signal data for programmatic guaranteed contracts.
- Malls:Atrium, corridor, and food-court installations with direct retailer data partnerships. Bangkok's CentralWorld and Manila's SM Megamall operate in-house retail media networks that bypass traditional agency intermediation, capturing first-party purchase behavior.
- Street Furniture:Bus shelters, benches, and kiosks with 15-45 second exposure windows. JCDecaux's Bangkok and Singapore concessions maintain premium positioning through exclusive municipal contracts with 10-15 year tenures.
- Arenas:Stadium and concert venue networks with event-triggered dynamic pricing. Singapore's National Stadium and Jakarta's Gelora Bung Karno deploy these for sponsor activation during ASEAN football fixtures and K-pop touring schedules.
Transit Stations anchor rate card premiums; Malls are gaining share fastest through retail media convergence.
Advertising Model:
Maturity gradient separates legacy direct relationships from automated trading infrastructure.
- Direct Sales:Annual fixed commitments with multinational FMCG buyers and automotive brands. These contracts still capture the largest share of contracted revenue across Thai and Indonesian networks, though buyers are migrating toward audience guarantees.
- Programmatic:Real-time bidding through demand-side platform integration with supply-side ad servers. Singapore's PDPC-compliant anonymized mobile signal frameworks are legitimizing this model, compressing media buying cycles from weeks to hours.
- Auction-Based:Open exchange inventory for remnant screen time and off-peak dayparts. Secondary city networks in the Philippines and Vietnam utilize these for yield optimization where direct sales teams lack geographic coverage.
- Hybrid:Programmatic guaranteed pipes with direct-sold premium tiers. This model is expanding most quickly as inventory aggregators integrate data management platforms to satisfy FMCG procurement requirements for store visit lift attribution.
Direct Sales retains volume leadership; Hybrid models are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore commands premium rate cards that exceed Jakarta and Manila benchmarks by triple-digit margins, while Vietnamese metro buildouts are compressing pricing power differentials across the Mekong corridor.
Singapore
Changi Airport concessions and MRT station networks drive demand for high-brightness LCD installations with sub-second latency requirements. PDPC data handling standards legitimize anonymized mobile signal integration for audience measurement, accelerating programmatic adoption. Marina Bay and Orchard Road clusters concentrate premium inventory where JCDecaux maintains exclusive municipal contracts.
Thailand
BTS Skytrain extensions and Bangkok mall expansions are creating captive audience environments with 90-second average dwell times. NBTC spectrum coordination rules harmonize 5G small-cell frequencies for reliable cellular backhaul. Sukhumvit and Silom transit corridors anchor Thailand's highest-yielding screen networks through Plan B Media's station concessions.
Indonesia
Jakarta MRT Phase 2 and mall infrastructure buildouts in Surabaya are expanding addressable inventory for FMCG procurement teams. TRAI-inspired content certification mandates 72-hour pre-approval workflows for dynamic creative. Grand Indonesia and Plaza Indonesia anchor retail media convergence pilots with first-party data partnerships.
Vietnam
Ho Chi Minh City Metro Line 1 and Hanoi urban rail extensions are generating greenfield platform inventory with guaranteed audience metrics. Local data privacy frameworks constrain facial analytics while permitting anonymized mobile retargeting. District 1 and Ba Dinh transit corridors concentrate Vietnam's fastest-growing programmatic pipeline development.
Philippines
Manila LRT-2 extensions and SM Megamall retail media networks are displacing traditional agency intermediation. Unreliable grid supply in provincial markets necessitates costly UPS redundancy for 24/7 operations. Makati and Ortigas CBD clusters anchor premium digital billboard deployments despite infrastructure variability challenges.
South East Asia Digital Out-Of-Home (Dooh) Market Competitive Landscape
Airport concession holders and transit network operators split the market between premium rate card positioning and volume-driven inventory aggregation. The competitive structure concentrates around exclusive municipal contracts with 10-15 year tenures and programmatic technology licensing partnerships. Three archetypes dominate: legacy outdoor media conglomerates with street furniture portfolios, transit-specialist operators with rail platform dominance, and ad-tech platforms enabling real-time trading infrastructure. Consolidation pressure is intensifying through exclusive concession renewals and supply-side platform integration mandates.
Among ASEAN-based infrastructure specialists, Plan B Media Public Company Limited exemplifies the transit-dominant archetype through exclusive BTS station and mall contracts. JCDecaux anchors the premium concession tier across Singapore and Bangkok airport and street furniture networks. oOh!media Limited occupies a position bridging Australian-ASEAN corridor strategies with digital rail platform specialization. These three represent divergent geographic and vertical positioning within a market where concession tenure length increasingly determines competitive durability.
| Leading Market Players |
|---|
| JCDecaux |
| Clear Channel Outdoor Holdings, Inc. |
| Dentsu Group Inc. |
| Hakuhodo DY Holdings Inc. |
| oOh!media Limited |
| Hivestack Inc. |
| Plan B Media Public Company Limited |
| Big Tree Outdoor Sdn. Bhd. |
| Moove Media Pte Ltd |
| Others |
Value Network & Pricing Analysis
Chinese fine-pitch LED module manufacturing clusters concentrate 70-80% of global SMD cabinet supply, anchoring margin capture upstream while ASEAN deployers absorb tariff volatility and shipping bottlenecks through Singapore transshipment ports. This upstream concentration forces downstream pricing power toward concession-holding network operators with exclusive municipal contracts, compressing pure-play inventory aggregators into yield-optimization strategies.
Pricing Analysis
Configured-to-order pricing for custom brightness-calibrated LED cabinets commands 40-60% premiums over standard-catalog SMD modules. Three-tier pricing structure across premium, standard, and economy levels separates airport concession holders from transit specialists and provincial roadside aggregators. Cost compression in the economy tier is intensifying because Philippine and Indonesian secondary markets lack fiber infrastructure for real-time video delivery. FMCG procurement teams in Bangkok and Singapore exhibit lowest price sensitivity due to first-party data partnership requirements, while provincial Philippine operators face acute margin pressure from generator-dependent 24/7 operations.
Supply Chain Analysis
Export-control scrutiny on advanced driver ICs and fine-pitch LED packaging equipment constrains technology flows from Taiwan and South Korea into mainland Chinese assembly plants. Component sourcing draws from Shenzhen SMD module fabricators, Taiwanese driver IC designers, and Korean phosphor suppliers. Single-source vulnerability concentrates in Chinese cabinet assembly where NBTC spectrum coordination delays can strand transit network deployments. Distribution runs through Singapore logistics hubs for Thai and Indonesian network operators, with direct Shenzhen-Manila lanes serving Philippine provincial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmatic ad-serving interoperability is dissolving channel boundaries between digital out-of-home and mobile programmatic stacks, creating platform-economics inflection where inventory aggregators must integrate with demand-side platforms or face disintermediation.
For Market Incumbents: Pre-empt concession renewal compression by embedding edge-computing nodes into existing transit contracts before NBTC spectrum harmonization completes. Secure exclusive data partnerships with mall operators in Bangkok and Jakarta to defend against retail media network bypass. Vertical integration into local creative certification workflows offsets TRAI-inspired approval latency that threatens campaign activation speed.
For New Entrants and Emerging Players: Vietnamese metro greenfield deployments offer lowest competitive density among ASEAN transit corridors. White-space targets include Ho Chi Minh City platform networks where guaranteed audience metrics lack established programmatic infrastructure, and Indonesian secondary city roadside digitization where SMD cost maturation enables hardware conversion previously priced out. Go-to-market through supply-side platform licensing partnerships accelerates inventory aggregation without exclusive concession requirements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed transit specialists holding 10-15 year BTS and MRT concessions approaching renewal windows. Long-term viability hinges on data management platform integration capabilities that satisfy FMCG procurement requirements for store visit lift attribution. Watch for NBTC spectrum coordination completion as inflection indicator enabling reliable cellular backhaul and programmatic guaranteed contract scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Node Deployment | Reduces backhaul bandwidth costs by 60-70% for Singapore and Bangkok transit operators. |
| First-Party Data Partnership | Enables mall operators in Jakarta and Manila to bypass traditional media agency intermediation. |
| Supply-Side Platform Integration | Compresses media buying cycles from weeks to hours for PDPC-compliant Singapore networks. |
| Creative Certification Workflow Investment | Absorbs TRAI-inspired 72-hour approval latency for dynamic campaigns in Indonesian malls. |
| 5G Small-Cell Backhaul Harmonization | Leverages NBTC spectrum coordination to eliminate fiber trenching costs in Thai roadside networks. |
Research Methodology
Cross-validation between supply-side platform transaction logs and concession-holder revenue disclosures anchors the qualitative findings on programmatic adoption velocity. Primary interviews with network operations directors, media agency programmatic traders, mall operator retail media heads, and NBTC spectrum coordination officers combined with secondary validation from customs import records, municipal concession registries, and telecommunications regulator filings. Bottom-up triangulation of screen-level deployment economics with top-down market sizing from media spend allocation surveys ensures segmentation integrity across platform types.
Calibration against historical concession renewal patterns and LED hardware cost curves informs the projection framework across the analysis window. Segmentation dimensions modeled include platform type, content format, placement geography, and advertising model maturity. CAGRs derive from fitted adoption curves for programmatic trading infrastructure and transit network expansion timelines. Industry-specific inputs incorporate SMD packaging cost trajectories and PDPC compliance adoption rates for anonymized mobile signal integration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed ad-tech platforms or state-funded transit operators would shift outcomes. Material shifts in Chinese export-control enforcement on driver ICs or NBTC spectrum allocation delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
Europe Digital OOH Advertising Market
Advertising and Marketing Media
Social Network Advertising Market
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
Europe Programmatic Advertising Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Middle East and Africa Programmatic Advertising Market
Advertising and Marketing Media
Global Contextual Advertising Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Spain OOH and DOOH Market