
 Finland OOH and DOOH Market | 2026-2036
Finland OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Finland OOH and DOOH Market Insights
Retail advertisers are redrawing Finland's OOH and DOOH market by shifting budgets from traditional static formats toward programmatic digital inventory. JCDecaux Finland leverages its dominance in airport and transit concessions across Helsinki-Vantaa and central rail terminals. Clear Channel Outdoor Finland anchors the national street furniture network with coverage in Tampere and Oulu. MediaTeko differentiates through hyperlocal digital kiosk deployments tied to municipal smart city frameworks.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display media deployed in public spaces for commercial messaging, with DOOH substituting static vinyl and paper substrates with networked LED, LCD, and projection systems capable of real-time content rotation and audience measurement. The primary commercial purpose is to intercept consumer attention during transit, dwell, and purchase-intent moments outside residential environments. Digital kiosks represent the fastest-expanding medium type as Finnish municipalities approve sidewalk and plaza installations for both advertising and civic information services. Behavioral audience targeting is displacing demographic-only planning as retailers demand footfall-to-conversion attribution. Static ads retain residual share in rural highway billboards where electrification costs exceed revenue potential.
Finnish Communications Regulatory Authority (FICORA) spectrum allocations govern DOOH network connectivity, while the Finnish Transport and Communications Agency (Traficom) regulates roadside display safety and driver distraction thresholds. EU GDPR compliance constrains geolocation targeting precision and requires explicit consent frameworks for mobile device proximity tracking. Stakeholders must monitor municipal zoning liberalization in secondary cities and the pace of EU AI Act implementation affecting automated audience measurement algorithms.
Market Dynamics
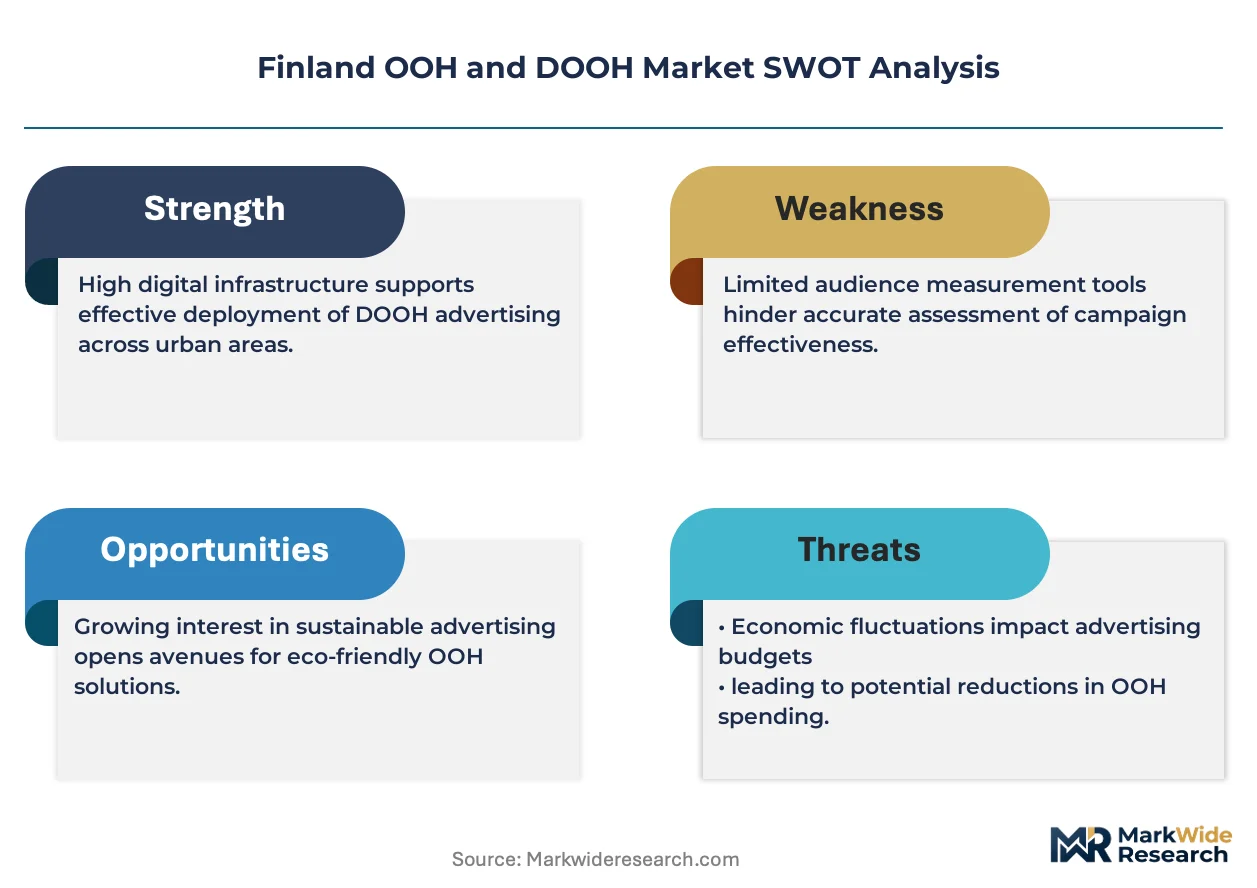
The EU Green Deal is compressing Finland's OOH and DOOH market timeline, forcing operators to retire static vinyl substrates before end-of-life and absorb premature LED retrofit capex. Municipal smart city frameworks in Helsinki, Tampere, and Turku are simultaneously opening sidewalk digital kiosk concessions, creating dual pressure on legacy inventory and new deployment capital.
Growth Catalysts
- EU Green Deal retrofit mandates:The national carbon neutrality target accelerates LED replacement of legacy static billboards, pulling forward digital infrastructure investment cycles.
- Retail location placements:Greater Helsinki metropolitan corridor concentration drives premium inventory scarcity and rate inflation for transit-adjacent digital screens.
- Programmatic trading platforms:Real-time audience measurement integration enables impression-level buying, attracting performance advertisers from mobile and social channels.
Market Restraints
- Rural highway electrification costs:Grid extension expenses exceed revenue potential in Lapland and Eastern Finland, trapping inventory in static formats.
- FICORA spectrum allocation scarcity:Limited sub-6GHz licenses constrain DOOH network density and real-time content synchronization capabilities.
- GDPR geolocation precision limits:Finnish Communications Regulatory Authority enforcement of proximity tracking consent degrades mobile-device audience matching accuracy.
Strategic Opportunities
- Tampere and Oulu secondary city liberalization:Municipal zoning reforms permit sidewalk digital kiosk installations previously restricted to Helsinki.
- EU AI Act implementation:Automated audience measurement algorithm compliance creates first-mover advantage for certified computer vision providers.
- Transit authority concession renewals:Helsinki, Tampere, and Turku rail-terminal screen network rebidding opens 10-15 year exclusive operating rights.
Industry Challenges
- Computer vision engineering talent scarcity:Automated audience measurement deployment requires scarce machine learning operations specialists unavailable in Finnish labor markets.
- Legacy static-to-digital integration complexity:Existing vinyl billboard structural foundations require complete reconstruction for LED weight and wind-load specifications.
- Traficom driver distraction compliance:Roadside display luminance and motion thresholds demand iterative testing cycles extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland OOH and DOOH Market |
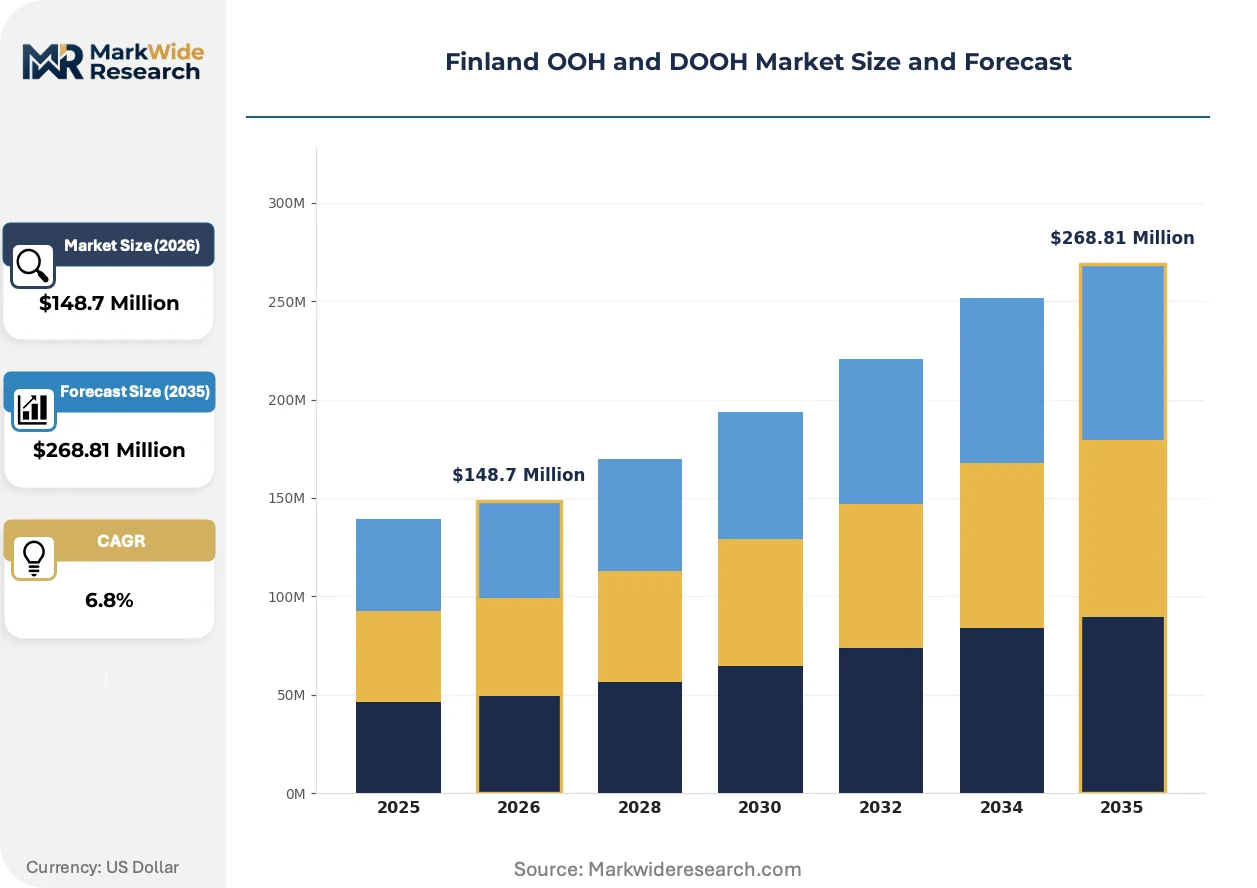
| Market Size in 2026 | $148.7 Million |
| Market Size in 2035 | $268.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medium Type: Billboards, Transit Advertising, Street Furniture, Digital Kiosks Audience Targeting: Demographics, Psychographics, Behavioral, Geolocation Ad Format: Static Ads, Animated Content, Interactive Displays, Video Walls Placement Strategy: High Traffic Areas, Event Venues, Retail Locations, Public Transport |
| Companies Covered | JCDecaux Finland, Clear Channel Outdoor Finland, Ocean Outdoor Finland, MediaTeko, 10näyttö, Bluebell Digital, Displayforce Global Ltd, McCann Worldgroup, Hasan & Partners, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland OOH and DOOH Market Trends and Innovations
Finland's OOH and DOOH market is experiencing convergent pressure from decarbonization policy, municipal digital infrastructure mandates, and advertiser demand for attribution-capable inventory. Three distinct vectors are reshaping competitive positioning and capital allocation priorities.
Edge-computing-enabled audience measurement is fragmenting the planning and buying workflow for Finnish DOOH inventory. Cameras with on-device inference processors eliminate cloud latency for demographic detection and attention-duration scoring. Retail advertisers in Greater Helsinki are adopting these systems for footfall-to-store-visit attribution. The technology is fragmenting rate-card standardization as impression-level validation enables dynamic pricing previously impossible with panel-based estimates.
EU AI Act algorithmic transparency requirements are restructuring vendor selection criteria for Finnish DOOH operators. Automated audience measurement systems must document training data provenance and bias testing protocols. Transit authorities in Helsinki-Vantaa and central rail terminals are prioritizing certified computer vision providers. The regulation is compressing procurement timelines as municipal buyers await compliance documentation before concession awards.
Behavioral targeting is displacing demographic-only planning among Finnish retail advertisers. Footfall pattern analysis and purchase-intent signal integration enable moment-based creative rotation. Programmatic platforms are capturing budget migration from static highway billboards. The shift concentrates in Greater Helsinki grocery and fashion verticals where dwell-time proximity drives conversion elasticity.
Finland OOH and DOOH Market Segmentation
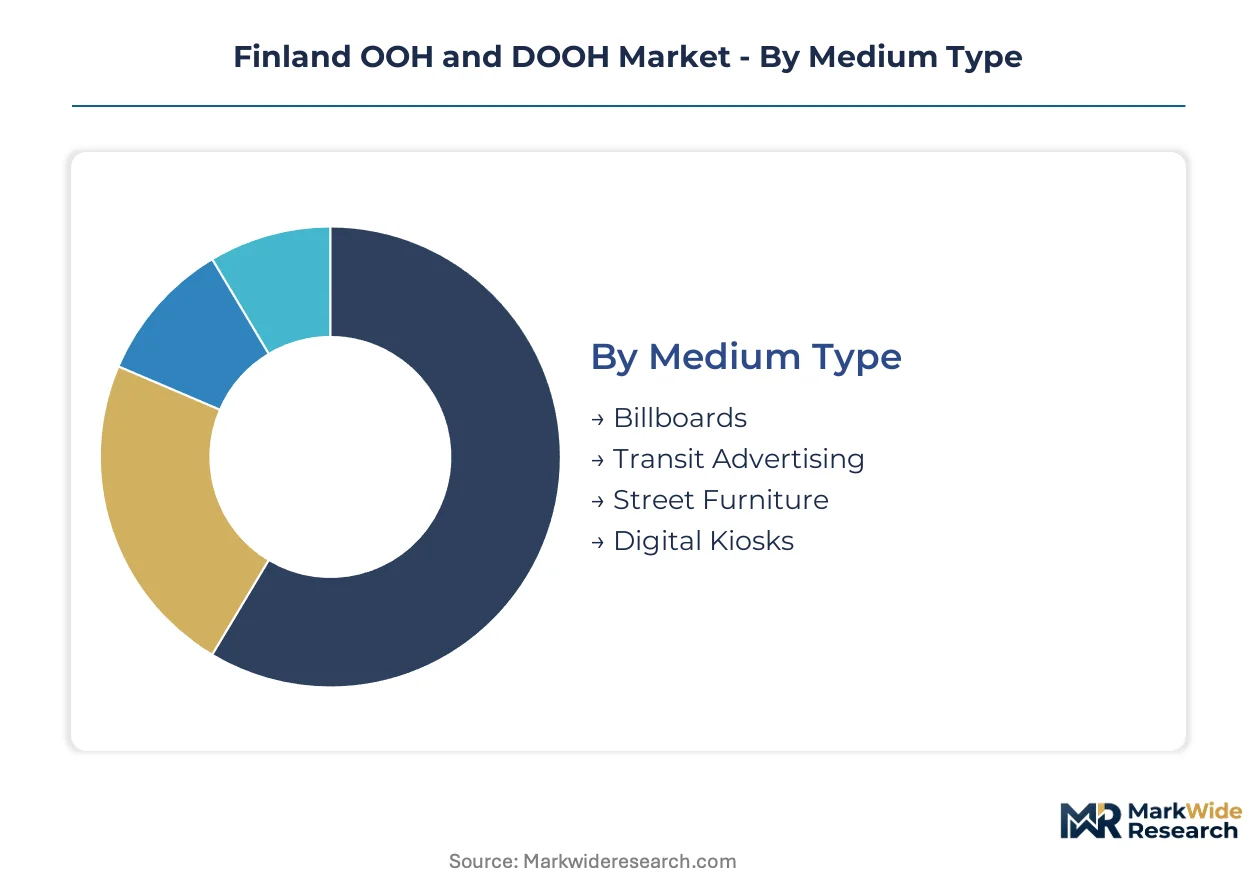
Finland's OOH and DOOH market segmentation reflects regulatory fragmentation across municipal, national, and EU jurisdictional layers. Traficom roadside safety rules, FICORA spectrum licensing, and GDPR consent frameworks each reshape viable segment combinations for operators and advertisers.
Medium Type:
Traficom driver distraction thresholds and municipal zoning codes differentiate deployable infrastructure across Finnish urban hierarchies.
- Billboards:Large-format roadside displays face Traficom luminance caps and motion restrictions along highways. Static vinyl substrates dominate Lapland and Eastern Finland where grid extension costs exceed LED retrofit economics.
- Transit Advertising:Helsinki-Vantaa airport and central rail terminals anchor premium inventory under JCDecaux concession control. Real-time content synchronization demands FICORA sub-6GHz spectrum allocations that constrain network density.
- Street Furniture:Clear Channel Outdoor Finland operates bus shelters and benches across Tampere and Oulu municipal networks. EU Green Deal retrofit mandates accelerate LED replacement timelines.
- Digital Kiosks:Sidewalk and plaza installations expand fastest as Helsinki, Tampere, and Turku smart city frameworks approve dual-use advertising and civic information concessions.
Established volume favors billboards; emerging adoption favors digital kiosks.
Audience Targeting:
GDPR enforcement by the Finnish Communications Regulatory Authority degrades precision for proximity-based methods while elevating compliant alternatives.
- Demographics:Age and gender classification through computer vision requires EU AI Act algorithmic transparency documentation. Transit authorities prioritize certified providers for rail-terminal concessions.
- Psychographics:Lifestyle and values-based segmentation relies on panel-based survey integration rather than real-time behavioral signals. MediaTeko deploys this approach for hyperlocal digital kiosk campaigns.
- Behavioral:Footfall pattern analysis and purchase-intent signal integration enable moment-based creative rotation. Retail advertisers in Greater Helsinki grocery and fashion verticals concentrate here.
- Geolocation:Mobile device proximity tracking demands explicit consent frameworks under GDPR. Finnish Communications Regulatory Authority enforcement limits precision for audience matching.
Behavioral targeting climbs the fastest as retailers demand footfall-to-conversion attribution.
Ad Format:
EU AI Act implementation timelines compress procurement cycles for automated measurement systems while favoring static alternatives in compliance-delayed deployments.
- Static Ads:Vinyl and paper substrates retain residual share in rural highway inventory. Traficom safety rules and electrification gaps trap these formats outside metropolitan corridors.
- Animated Content:Looping digital sequences with controlled motion parameters satisfy Traficom driver distraction thresholds. Edge-computing inference processors enable on-device demographic detection.
- Interactive Displays:Touch-enabled and gesture-responsive screens deploy in Helsinki retail plazas with dwell-time optimization. GDPR consent requirements constrain data collection scope.
- Video Walls:Large-scale LED arrays dominate event venues and premium transit terminals. Helsinki-Vantaa airport installations command rate premiums for international audience capture.
Static ads retain volume leadership; video walls gain share fastest in premium inventory.
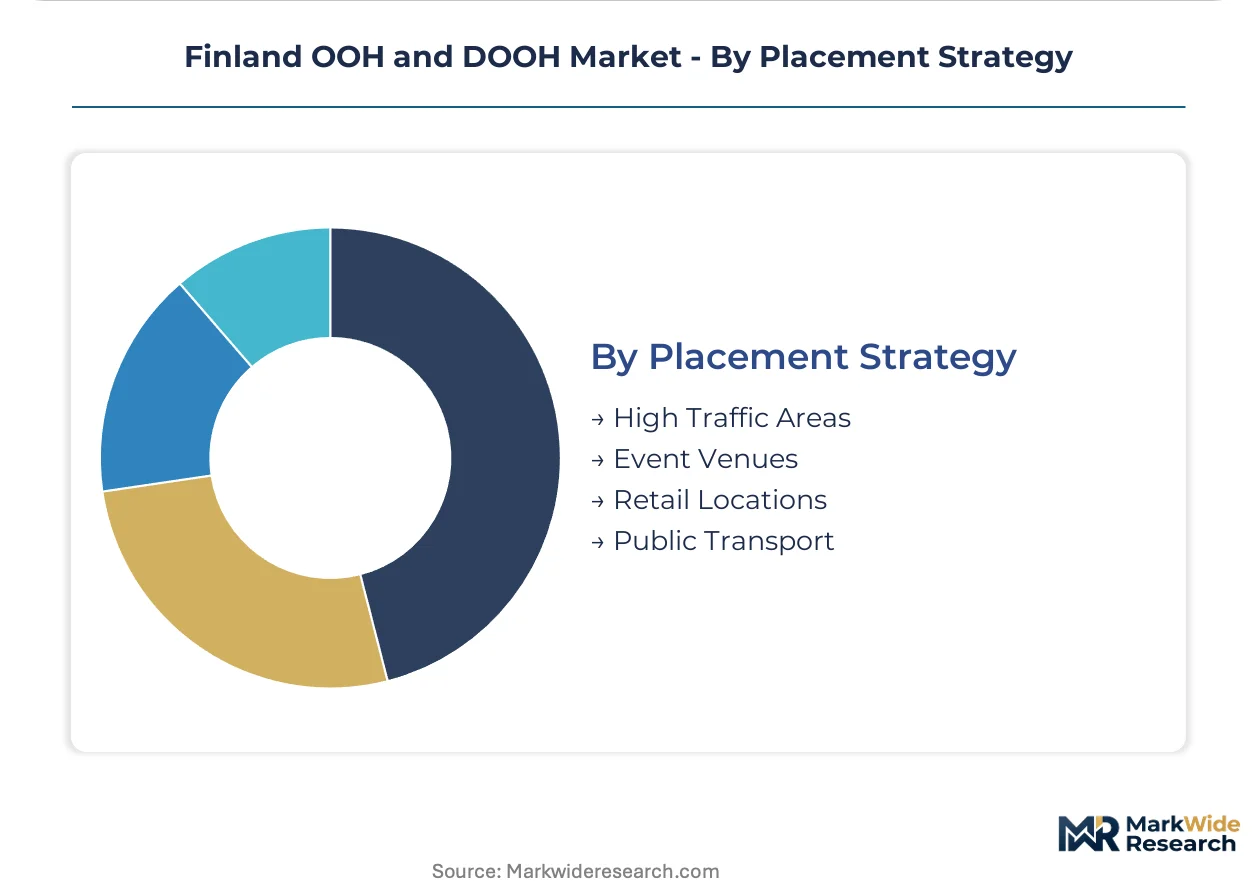
Placement Strategy:
Greater Helsinki metropolitan concentration creates scarcity-driven rate inflation while secondary city liberalization expands addressable inventory.
- High Traffic Areas:Central business district and arterial road placements face Traficom luminance compliance testing. Iterative certification cycles extend deployment timelines.
- Event Venues:Temporary and seasonal installations around sports and cultural facilities enable premium pricing. Video wall formats dominate this segment.
- Retail Locations:Grocery and fashion verticals in Greater Helsinki drive programmatic platform adoption. Footfall-to-store-visit attribution capabilities concentrate advertiser demand here.
- Public Transport:Helsinki, Tampere, and Turku rail-terminal screen networks face 10-15 year exclusive concession rebidding. Transit authority smart city integration requirements reshape vendor selection criteria.
Public transport anchors established revenue; retail locations attract the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish OOH operators export digital screen expertise and smart city integration capabilities to Nordic neighbors, while importing LED hardware and programmatic trading platforms from Germany and the Netherlands. This bilateral flow concentrates investment decisions in Helsinki, Tampere, and Turku municipal procurement offices.
Greater Helsinki
Helsinki-Vantaa airport and central rail terminals anchor premium DOOH inventory under exclusive concession frameworks. EU Green Deal retrofit mandates accelerate LED replacement of legacy static formats across the metropolitan corridor. Retail location placements in grocery and fashion verticals drive programmatic platform adoption for footfall attribution.
Tampere
Secondary city zoning liberalization permits sidewalk digital kiosk installations previously restricted to the capital. Clear Channel Outdoor Finland operates bus shelter networks under municipal smart city partnerships. The Traficom roadside safety compliance testing extends deployment timelines for high-traffic arterial placements.
Turku
Rail-terminal screen network rebidding opens exclusive operating rights for 10-15 year concession periods. Transit authority procurement prioritizes EU AI Act-certified computer vision providers for automated audience measurement. The Åbo Akademi university corridor generates demand for hyperlocal campus-adjacent inventory.
Oulu
Arctic technology cluster concentration attracts event venue and temporary installation premium pricing. FICORA spectrum allocation scarcity constrains real-time content synchronization for network density expansion. Rural highway electrification gaps trap peripheral inventory in static vinyl formats.
Finland OOH and DOOH Market Competitive Landscape
Listed outdoor advertising multinationals compete with private specialists across concession tenure and municipal relationship depth. The Finnish OOH and DOOH market structures around three archetypes: airport-transit concession incumbents, street furniture network operators, and hyperlocal digital kiosk deployers. Consolidation pressure intensifies as EU Green Deal capex requirements favor balance-sheet capacity. Competitive moves concentrate on concession renewal lobbying and smart city framework certification.
Within the airport-transit tier, JCDecaux Finland and Clear Channel Outdoor Finland occupy positions shaped by Helsinki-Vantaa and rail-terminal exclusive rights. MediaTeko exemplifies the hyperlocal specialization archetype through municipal smart city integration. These three anchors represent divergent capital deployment strategies: concession consolidation versus kiosk proliferation versus programmatic platform development.
| Leading Market Players |
|---|
| JCDecaux Finland |
| Clear Channel Outdoor Finland |
| Ocean Outdoor Finland |
| MediaTeko |
| 10näyttö |
| Bluebell Digital |
| Displayforce Global Ltd |
| McCann Worldgroup |
| Hasan & Partners |
| Others |
Pricing and Supply Chain Analysis
LED module substitution for legacy vinyl substrates simultaneously relocates procurement geography toward East Asian manufacturing hubs and compresses margin structures for Finnish operators absorbing premature retrofit capex. This input transition elevates capital intensity while fragmenting supplier bargaining power across the value chain.
Pricing Analysis
Static-to-digital generation gaps define Finland's OOH pricing architecture, with legacy vinyl billboards commanding residual premiums in rural electrification gaps while LED-equipped inventory captures rate inflation in Greater Helsinki transit corridors. Three-tier pricing structure across premium airport-terminal, standard street-furniture, and economy rural-static levels reflects certification grade and footfall attribution capabilities. Cost compression in standard-tier municipal concessions is intensifying because EU Green Deal retrofit mandates accelerate depreciation schedules. Retail advertisers in grocery and fashion verticals exhibit lowest price sensitivity due to footfall-to-conversion attribution demands, while highway static buyers face highest sensitivity given electrification cost pass-through limitations.
Supply Chain Analysis
Inventory lead times for LED display modules have extended from East Asian manufacturing centers as Finnish operators front-load procurement ahead of EU AI Act compliance deadlines. China, South Korea, and Taiwan concentrate LED panel and driver IC production, while aluminum extrusion and structural steel feed from Nordic and German mills. Finnish operators face single-source vulnerability in edge-computing inference processors for audience measurement systems. Distribution runs through Helsinki-based systems integrators with municipal smart city certification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finland's OOH market operates as a regulatory entrenchment moat where concession tenure and municipal certification create switching costs that protect incumbent cash flows from new capital deployment.
For Market Incumbents: Secure exclusive operating rights through early engagement with Helsinki, Tampere, and Turku transit authority rebidding cycles before EU AI Act compliance documentation requirements harden vendor selection criteria. Extend backward integration into LED module assembly to offset East Asian procurement concentration and margin pressure from accelerated Green Deal retrofit timelines. For New Entrants and Emerging Players: EU AI Act certification fast-track for computer vision providers creates entry pathway into automated audience measurement procurement prioritized by municipal transit authorities. Target Tampere and Oulu sidewalk digital kiosk concessions where zoning liberalization has reduced incumbent lock-in, deploying hyperlocal civic-information integration as differentiated go-to-market positioning against established street furniture networks. For Investors and Strategic Acquirers: The market sits at a capital-deployment phase that favors balance-sheet-heavy concession consolidators over technology specialists. Long-term viability rests on 10-15 year exclusive operating right renewals with embedded smart city integration requirements. Watch municipal procurement timeline acceleration as inflection indicator for concession value repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Renewal Pre-Positioning | Early engagement with Helsinki-Vantaa and rail-terminal authorities secures 10-15 year exclusive operating rights before EU AI Act compliance hardens vendor selection. |
| LED Retrofit Acceleration | Front-loaded capital deployment ahead of Green Deal mandates captures premium rate positioning in Greater Helsinki metropolitan corridor inventory. |
| EU AI Act Certification Investment | Documented algorithmic transparency for computer vision systems unlocks transit authority procurement prioritization and municipal smart city integration. |
| Secondary City Zoning Expansion | Tampere and Oulu sidewalk digital kiosk approvals extend addressable inventory beyond capital-market saturation. |
| Programmatic Platform Development | Real-time audience measurement integration attracts performance advertiser budget migration from mobile and social channels. |
Research Methodology
The analysis maps digital kiosk, transit advertising, street furniture, and billboard sub-sectors, each validated through transit authority procurement officers, municipal smart city directors, outdoor advertising operators, and retail media buyers. Primary interviews combined with secondary validation from FICORA spectrum allocation filings, Traficom roadside safety compliance records, EU Green Deal implementation directives, and municipal zoning ordinance databases. Bottom-up inventory counts and top-down media spend estimates triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include medium type, placement strategy, audience targeting methodology, and ad format complexity. CAGRs derived from infrastructure deployment timelines, concession renewal cycles, and advertiser budget reallocation patterns. Forecast inputs incorporate EU AI Act implementation pace and FICORA sub-6GHz license availability.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement and stable municipal zoning liberalization trajectories; material deviation in regulatory timelines or electrification cost curves would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
North America Programmatic Advertisement Market
Advertising and Marketing Media
North America Public Relation Services Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
United States Marketing Agencies Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
Malaysia OOH and DOOH Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
Chile OOH and DOOH Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
Global Programmatic Advertisement Market