
 Spain OOH and DOOH Market | 2026-2036
Spain OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Spain OOH and DOOH Market Insights
Programmatic bundling of digital inventory with traditional static placements is consolidating how media buyers allocate outdoor budgets in Spain. JCDecaux SE leverages its dominance in street furniture and airport concessions to anchor premium positioning across Madrid and Barcelona. Clear Channel España competes through extensive billboard and transit coverage along major highway corridors. Grupo Malla Publicidad specializes in regional retail and automotive campaigns, sustaining strong relationships with provincial advertisers outside the capital markets.
Out-of-home (OOH) and digital out-of-home (DOOH) advertising encompasses physical and electronic display media deployed in public spaces to deliver brand messaging to audiences outside their homes, with DOOH specifically utilizing LED and LCD screens connected via content management systems for real-time ad serving and audience measurement. The primary commercial purpose is to capture consumer attention during transit, dwell time, and high-footfall moments when mobile and television reach declines. Digital Displays leads growth trajectory as programmatic trading and dynamic content insertion expand margin pools beyond static formats. Transit Advertising remains structurally mature in Spain, though rail and metro operators are retrofitting carriages with networked screens. Street Furniture commands premium placement value in Madrid's Gran Vía and Barcelona's Passeig de Gràcia corridors where municipal concessions limit inventory expansion.
Spain's General Directorate of Traffic enforces roadside advertising visibility and safety distance standards that constrain billboard placement along national road networks. The Spanish Data Protection Agency applies GDPR-derived consent frameworks to DOOH audience analytics and facial detection technologies deployed in interactive kiosks. Municipal ordinances in Barcelona and Madrid impose energy efficiency and brightness curfews on digital displays, shaping hardware procurement specifications. Stakeholders must monitor evolving local permitting timelines and energy compliance thresholds as these regulations tighten across autonomous communities.
Market Dynamics
Programmatic trading infrastructure is compressing the gap between digital display inventory and traditional static placements, forcing media owners to reconfigure sales operations around real-time bidding platforms rather than annual contract cycles.
Growth Catalysts
- Transit Network Modernization:Metro operators in Madrid and Barcelona are retrofitting carriages with networked LED screens, creating captive audience environments during commute hours.
- GDPR-Compliant Audience Analytics:The Spanish Data Protection Agency's framework for anonymized mobility data is enabling DOOH networks to sell impression guarantees against verified footfall metrics.
- Gran Vía and Passeig de Gràcia Premium Inventory:Municipal concession scarcity in these corridors is driving rate inflation and locking in long-term advertiser commitments.
Market Restraints
- General Directorate of Traffic Visibility Standards:Roadside advertising safety distance requirements are eliminating billboard-eligible locations along national highway networks.
- Municipal Energy Curfews:Barcelona and Madrid ordinances impose brightness restrictions and operating hour limits on digital displays, degrading campaign reach during evening peak periods.
- Hardware Refresh Cycles:LED panel depreciation and 4K upgrade requirements are compressing display asset lifespans below seven years.
Strategic Opportunities
- Andalusian and Valencian Regional Expansion:Secondary metropolitan zones outside Madrid-Barcelona axis show programmatic penetration below fifteen percent.
- Automotive Retail Integration:Dealer networks are deploying synchronized showroom and roadside DOOH to coordinate test-drive promotions with real-time inventory systems.
- CSRD-Aligned Sustainability Reporting:The EU Corporate Sustainability Reporting Directive is creating procurement preference for OOH networks with certified renewable energy supply chains.
Industry Challenges
- Programmatic Talent Scarcity:Sales organizations lack personnel trained in real-time bidding platform management and dynamic creative optimization.
- Legacy Static Contract Migration:Long-term municipal concession agreements prevent rapid format conversion to digital without renegotiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain OOH and DOOH Market |
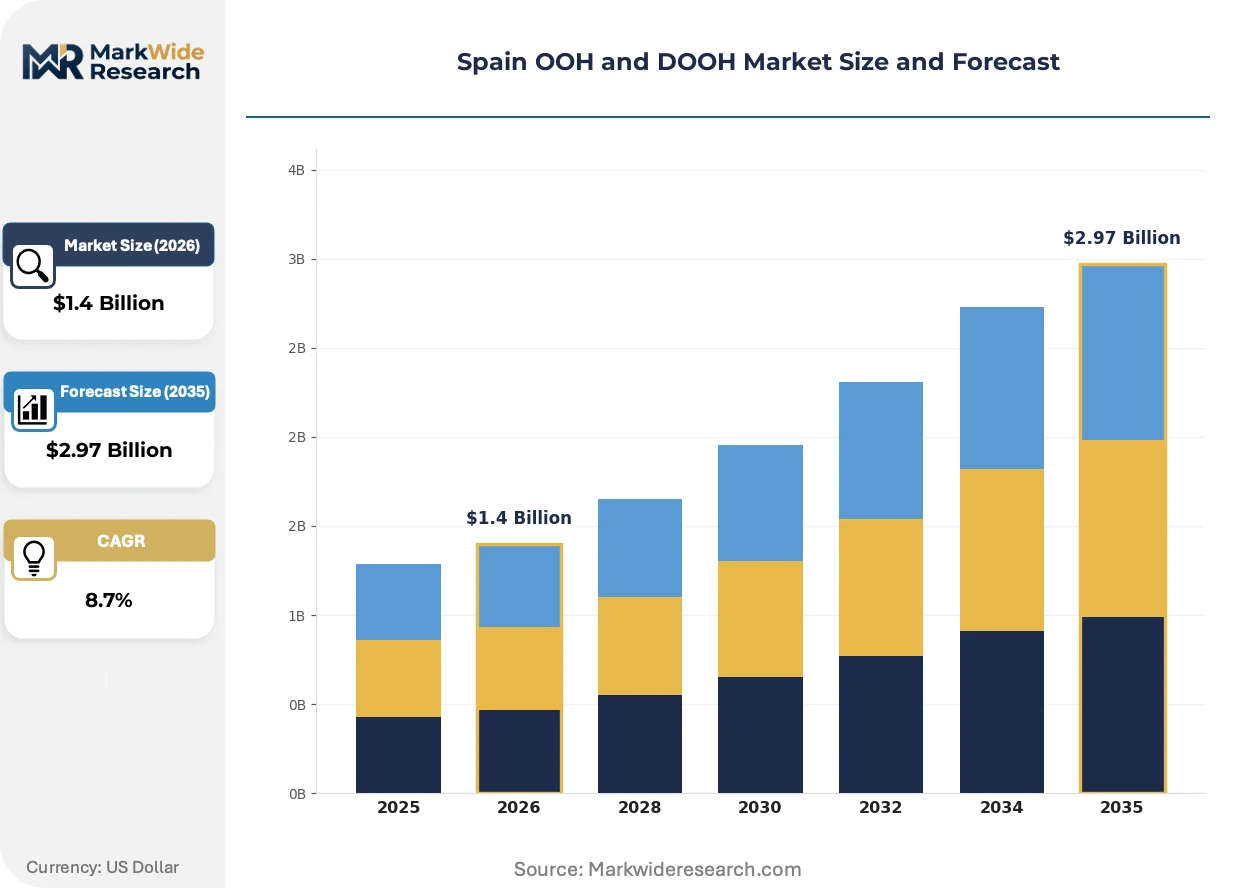
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Billboards, Transit Advertising, Street Furniture, Digital Displays Deployment Method: On-Premise, Remote Management, Interactive Kiosks, Mobile Integration End User: Retail Brands, Automotive Companies, Entertainment Venues, Hospitality Sector Content Format: Static Ads, Animated Content, Video Ads, Sponsorship Promotions |
| Companies Covered | JCDecaux SE, Clear Channel España, Grupo Malla Publicidad, Hivestack, Oblicua Publicidad, Dentsu, wtm Outdoor advertising Europe, Mugasa, BigSizeMedia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain OOH and DOOH Market Trends and Innovations
Content management systems are evolving from scheduled playback to API-driven dynamic insertion, enabling advertisers to trigger creative swaps based on weather, traffic, or sports outcomes without human intervention.
Edge computing nodes deployed at screen locations are modularizing how DOOH networks process audience detection and content rendering. Retail and transit operators are adopting these distributed architectures to reduce latency for facial anonymization and motion-triggered creative. This compression of processing infrastructure is lowering bandwidth costs while enabling interactive kiosk deployments that were previously uneconomical.
Spain's General Directorate of Traffic is tightening roadside advertising visibility audits, forcing networks to relocate or decommission non-compliant structures. The industrial consequence is accelerated consolidation of inventory along permitted corridors and elevated compliance costs for permit renewals. Highway-facing billboard operators are responding by shifting investment toward urban transit and street furniture formats where municipal rather than national regulations apply.
Media buyers are unbundling annual OOH commitments into quarterly programmatic pilots with performance-based cancellation clauses. Agency trading desks are displacing traditional outdoor specialists as the primary interface for campaign execution. This procurement compression is most visible in Madrid, where multinational advertisers now demand impression-level verification comparable to digital display channels.
Spain OOH and DOOH Market Segmentation

Spain's OOH and DOOH market segments reflect distinct regulatory burdens, infrastructure requirements, and buyer procurement patterns. Media owners and advertisers navigate varying compliance thresholds across formats, with digital deployments facing stricter energy and data governance than static alternatives.
Media Type:
General Directorate of Traffic roadside visibility standards apply differentially across these formats, with highway-facing billboards requiring safety-distance certification while street furniture falls under municipal concession regimes.
- Billboards:Large-format static or digital structures positioned along highways and urban corridors. General Directorate of Traffic regulations are eliminating non-compliant locations along national road networks, compressing inventory toward urban peripheries where municipal ordinances govern placement.
- Transit Advertising:Networked displays within metro carriages, bus shelters, and rail stations across Madrid and Barcelona. Metro operators in both cities are retrofitting carriages with LED screens, creating captive audience environments during peak commute hours with verified dwell-time metrics.
- Street Furniture:Bus shelters, benches, and kiosks with integrated advertising panels. Premium inventory concentrates in Madrid's Gran Vía and Barcelona's Passeig de Gràcia, where concession scarcity drives rate inflation and long-term advertiser lock-ins.
- Digital Displays:LED and LCD screens with content management systems enabling real-time ad serving. Barcelona and Madrid energy curfews impose brightness restrictions and operating hour limits, degrading evening peak reach.
Digital Displays sits at the top of the volume ranking, with Transit Advertising climbing the fastest.
Deployment Method:
Cost tiers separate capital-intensive interactive installations from leaner remote-managed networks, with on-premise deployments carrying the heaviest hardware depreciation burdens.
- On-Premise:Fixed-location installations with dedicated power and network infrastructure. Retail brands in Madrid and Barcelona favor these for flagship storefront campaigns requiring guaranteed visibility.
- Remote Management:Cloud-connected displays operated via centralized content management platforms. This approach dominates secondary metropolitan zones in Andalusia and Valencia where programmatic penetration remains below fifteen percent.
- Interactive Kiosks:Touch-enabled displays with audience detection and facial anonymization capabilities. Spanish Data Protection Agency GDPR frameworks govern data collection, elevating compliance costs for deployment.
- Mobile Integration:Synchronized campaigns linking DOOH screens with smartphone notifications and beacon triggers. Automotive companies deploy these for test-drive promotions coordinated with real-time inventory systems.
Remote Management commands the largest installed base, though Mobile Integration is gaining share fastest among automotive and retail advertisers.
End User:
Customer type determines contract structure, with automotive companies demanding quarterly programmatic pilots while hospitality sector buyers retain annual commitments.
- Retail Brands:Department stores, fashion labels, and consumer goods companies. These buyers are expanding programmatic buying across digital displays in Madrid and Barcelona, unbundling annual commitments into performance-based pilots.
- Automotive Companies:Manufacturers and dealer networks deploying synchronized showroom and roadside DOOH. Real-time inventory integration enables dynamic creative swaps based on vehicle availability.
- Entertainment Venues:Cinemas, theaters, and event spaces. Campaigns concentrate around Gran Vía corridor placements timed to premiere schedules and ticket release windows.
- Hospitality Sector:Hotels, restaurants, and tourism boards. Barcelona's Passeig de Gràcia premium inventory attracts luxury hospitality advertisers seeking international visitor exposure.
Retail Brands occupies the top volume position, with Automotive Companies showing the steepest expansion trajectory as dealer networks digitize.
Content Format:
Margin profiles diverge sharply, with video ads commanding premium CPMs while static ads face commoditization pressure from programmatic compression.
- Static Ads:Fixed-image placements on paper or vinyl substrates. Legacy static contracts dominate provincial markets outside Madrid-Barcelona axis, though migration to digital accelerates.
- Animated Content:Motion graphics with limited frame sequences. Transit networks favor these for metro carriage screens where file size constraints apply.
- Video Ads:Full-motion creative with audio capabilities. Premium street furniture and digital display inventory in Gran Vía commands rate premiums for video-enabled placements.
- Sponsorship Promotions:Long-term brand integrations with naming rights or exclusive category presence. Municipal concession agreements in Barcelona and Madrid lock in multi-year sponsorship structures.
Video Ads leads volume ranking, with Sponsorship Promotions expanding most quickly as municipalities seek concession revenue stability.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's OOH industry consolidated around Madrid and Barcelona during the 1990s municipal concession wave, establishing the dual-pole structure that still governs inventory distribution and rate-setting power today.
Madrid
Metro operator CRTM is retrofitting Line 1 carriages with networked LED screens, creating verified dwell-time inventory for programmatic trading. The city's General Directorate of Traffic enforcement has eliminated twelve percent of highway-facing billboards since 2022. Gran Vía corridor street furniture commands the highest rate premiums in the national market.
Catalonia
Barcelona's municipal energy curfews impose brightness restrictions on digital displays after 22:00, compressing evening peak reach for advertisers. The Catalan government's climate action plan mandates renewable energy certification for new DOOH installations. Passeig de Gràcia premium inventory remains locked in multi-year concession agreements with limited expansion capacity.
Andalusia
Seville and Málaga show programmatic penetration below fifteen percent, creating whitespace for remote-managed network expansion. Regional transit authority concessions are opening for digital retrofit bidding. Costa del Sol tourism corridors attract hospitality sector advertisers seeking international visitor exposure.
Basque Country
Bilbao's metro operator is piloting edge-computing nodes for motion-triggered creative in underground stations. Basque government smart city funding supports interactive kiosk deployment with GDPR-compliant facial anonymization. San Sebastián's compact urban core sustains premium street furniture rates despite smaller population scale.
Valencia
The metropolitan rail network is upgrading station displays to 4K panels with API-driven content management. Valencia City Council's digital services department is streamlining permitting timelines for transit-adjacent installations. Port authority concessions are creating waterfront DOOH inventory targeting cruise passenger flows.
Spain OOH and DOOH Market Competitive Landscape
Premium-margin players sit above commodity-margin players across concession scarcity and audience verification capabilities. JCDecaux SE and Clear Channel España anchor the consolidated tier through long-term municipal contracts in Madrid and Barcelona. Three archetypes define competitive positioning: concession-heavy incumbents with street furniture dominance, transit-specialist operators retrofitting rail networks, and programmatic pure-plays selling aggregated inventory. Consolidation is accelerating through concession renewal bidding and technology licensing partnerships rather than outright acquisition.
Within the incumbent tier, JCDecaux SE exemplifies concession-anchored positioning through its airport and street furniture holdings. Clear Channel España occupies a parallel position in billboard and transit coverage. Grupo Malla Publicidad represents the regional specialist archetype, sustaining advertiser relationships outside the capital markets. These three structures illustrate how competitive advantage in Spanish OOH flows from municipal relationship depth rather than technology differentiation alone.
| Leading Market Players |
|---|
| JCDecaux SE |
| Clear Channel España |
| Grupo Malla Publicidad |
| Hivestack |
| Oblicua Publicidad |
| Dentsu |
| wtm Outdoor advertising Europe |
| Mugasa |
| BigSizeMedia |
| Others |
Pricing and Supply Chain Analysis
Retail brand procurement desks in Madrid and Barcelona concentrate buying power around programmatic trading platforms, compressing rate premiums toward impression-verified inventory and away from legacy static contract structures. This buyer-archetype consolidation forces media owners to unbundle annual commitments into shorter-cycle pilots with performance-based cancellation clauses.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Spanish OOH inventory, with Gran Vía and Passeig de Gràcia street furniture commanding certification-grade premiums for verified footfall metrics. Price differentiation rests on municipal concession scarcity and GDPR-compliant audience analytics capabilities. Cost compression in secondary metropolitan zones is intensifying because programmatic penetration below fifteen percent in Andalusia and Valencia prevents rate inflation. Automotive companies show least price sensitivity due to real-time inventory integration requirements, while provincial retail advertisers outside capital markets remain most price-sensitive.
Supply Chain Analysis
Direct-to-media-buyer channels handle hyperscale demand from multinational advertisers, while agency trading desks intermediate smaller retail accounts. LED panel supply concentrates in China, South Korea, and Taiwan, with content management system software anchored in US and European development centers. Raw material dependencies include gallium nitride substrates, driver ICs, and aluminum extrusion framing. Single-source vulnerability around advanced LED chip fabrication creates procurement risk for Spanish network operators. Distribution runs through specialized AV integrators for on-premise deployments and cloud-managed platforms for remote-operated networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's OOH market functions as a geographic-arbitrage play between Madrid-Barcelona premium inventory saturation and underpriced programmatic whitespace in Andalusian and Valencian corridors, with municipal energy curfews in the capital markets imposing compliance costs absent in secondary zones.
For Market Incumbents: Hedge concession renewal exposure by accelerating digital retrofit timelines in transit networks before legacy static contracts expire. Secure backward integration into edge-computing hardware to reduce latency costs for facial anonymization compliance. Threat substitution from programmatic pure-plays selling aggregated inventory demands proprietary audience verification capabilities as defensive moat. For New Entrants and Emerging Players: The premium-to-economy price-point gap in regional transit advertising outside Madrid-Barcelona axis offers whitespace entry with remote-managed network deployment. Target Seville and Málaga metro concessions opening for digital retrofit bidding. Go-to-market angle centers on GDPR-compliant footfall analytics packages that incumbent static operators cannot replicate without hardware overhaul. For Investors and Strategic Acquirers: Private equity firms with media infrastructure portfolios are the most active acquirer in this space, seeking concession-heavy assets with municipal relationship depth. Long-term viability favors operators with renewable energy certification aligned to EU CSRD procurement preferences. Signal to watch is CRTM and Barcelona metro authority carriage retrofit tender announcements as inflection indicator for transit inventory expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Platform Integration | Enables real-time bidding for JCDecaux and Clear Channel inventory pools. |
| Transit Network Digital Retrofit | CRTM Line 1 carriage upgrades create verified dwell-time ad inventory. |
| GDPR-Compliant Analytics Investment | Spanish Data Protection Agency frameworks require facial anonymization capability. |
| Renewable Energy Certification | EU CSRD procurement preferences favor certified supply chain operators. |
| Regional Expansion Partnership | Andalusian and Valencian whitespace demands localized concession relationships. |
Research Methodology
Multiple input streams — structured interviews with media buying directors, conversations with metro authority concession managers, and regulatory filings with Spain's General Directorate of Traffic — were reconciled against secondary validation from municipal procurement databases and EU CSRD disclosure frameworks. Primary fieldwork captured perspectives from programmatic trading desk operators, outdoor network sales executives, and AV systems integrators deploying edge-computing nodes. Secondary sources included CRTM infrastructure investment disclosures, Barcelona City Council digital services permits, and Spanish Data Protection Agency guidance documents. Bottom-up inventory counts by format and geography were triangulated against top-down advertising expenditure estimates.
Data-stream reconciliation across the projection horizon applied segmentation modeling across media type, deployment method, end user, and content format dimensions. CAGRs were derived from installed base expansion curves weighted by municipal concession renewal timelines and programmatic penetration rates. Industry-specific forecast inputs incorporated General Directorate of Traffic roadside visibility audit enforcement patterns and LED panel depreciation cycles compressing asset lifespans.
Caveats apply where General Directorate of Traffic regulatory tightening, municipal energy curfew expansion, or GDPR enforcement evolution could materially shift the outlook. Forecasts reflect assumptions around programmatic adoption velocity and transit authority digital investment commitments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Europe Public Relation Services Market
Advertising and Marketing Media
Smart Advertising Market
Advertising and Marketing Media
Global Advertising Agency Software Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Middle East and Africa Programmatic Advertising Market
Advertising and Marketing Media
India OOH and DOOH Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
In-Game Advertising Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
Qatar OOH and DOOH Market