
 North America Advertising Market | 2026-2036
North America Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
North America Advertising Market Intelligence
Market Context
Data-science talent scarcity across the US and Canada is unwinding traditional agency staffing models and forcing faster automation adoption. WPP leverages its global analytics academies to sustain creative-technical hybrid teams in Toronto and Chicago. Omnicom Group anchors its competitive stance through proprietary media-planning platforms that dominate upfront television negotiations.
Technical Definition and Segment Structure
Advertising in North America encompasses paid, non-personal communication transmitted through owned, earned, and purchased channels to influence audience behavior, with digital formats now measured through real-time attribution windows and cross-device identity graphs. The medium dimension shows digital commanding the largest share of planning budgets while print contracts to niche B2B applications. Service type reveals media buying as the mature margin pool and analytics as the fastest-expanding capability layer where agencies differentiate through proprietary data partnerships.
Regulatory Framework
The US Federal Trade Commission enforces truth-in-advertising standards that mandate clear disclosure of sponsored content and prohibit deceptive native advertising formats. Canada's Competition Bureau and Advertising Standards Canada jointly govern comparative claims and influencer marketing transparency, shaping how agencies structure client contracts. Health Canada and the US Food and Drug Administration impose additional promotional restrictions on pharmaceutical advertisers, creating specialized compliance verticals within major holding companies. Stakeholders must monitor emerging state-level privacy legislation that fragments the uniform data-targeting environment agencies have operated within for two decades.
Market Dynamics
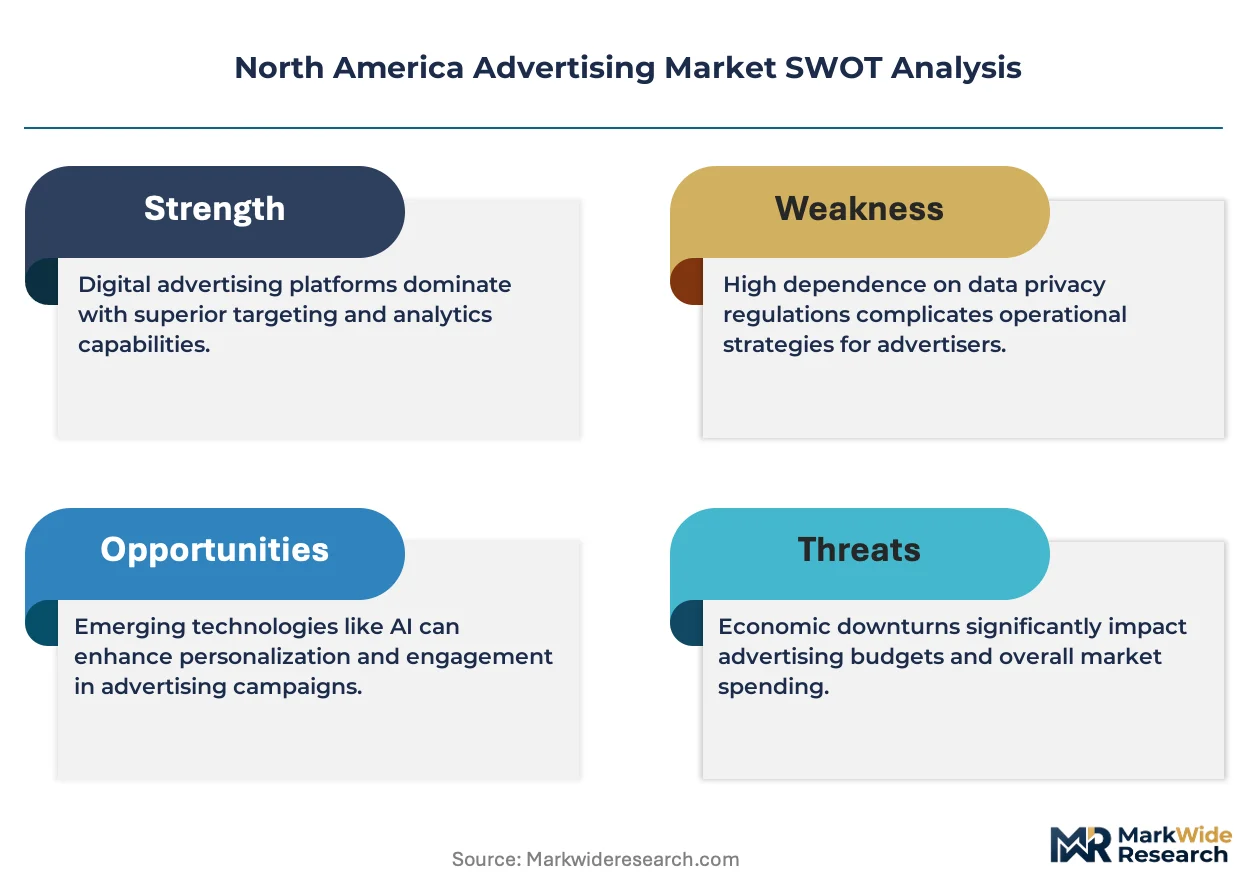
Programmatic media buying is compressing traditional agency fee structures across the United States and Canada, forcing holding companies to automate planning workflows and retrain creative talent for data-centric campaign optimization.
Growth Catalysts
- FTC Disclosure Mandates:The US Federal Trade Commission's updated native advertising guidelines are accelerating demand for compliance-integrated creative services. Agencies that embed legal review into production pipelines capture larger retainer contracts from risk-averse pharmaceutical and financial advertisers.
- Connected Television (CTV) Inventory Expansion:Streaming platforms are releasing addressable ad slots that merge broadcast reach with digital targeting precision. Media buyers in Los Angeles and New York are reallocating upfront television budgets toward programmatic CTV marketplaces.
- First-Party Data Infrastructure:Retail media networks operated by major grocery and big-box chains are building closed-loop attribution systems. Advertisers gain direct access to purchase-level outcomes without third-party cookie dependencies.
Market Restraints
- State Privacy Fragmentation:California's Consumer Privacy Act and emerging legislation in Colorado, Connecticut, and Virginia are creating incompatible data governance requirements. National campaigns require jurisdiction-specific creative variants and consent management platforms.
- Platform Concentration Risk:Meta and Alphabet properties capture dominant shares of digital ad spend. Advertisers face pricing power asymmetry and limited negotiating leverage during rate renegotiations.
- Linear Television Decline:Cord-cutting acceleration in Canadian and US households is eroding reach for brand advertisers dependent on demographic-based broadcast buys. Replacement CTV inventory remains fragmented across incompatible tech stacks.
Strategic Opportunities
- Retail Media Networks:Walmart, Target, and Loblaw are opening on-site and off-site ad inventory to external brands. First-party shopper data enables closed-loop measurement that traditional publishers cannot replicate.
- Artificial Intelligence Creative Generation:Generative tools for copy adaptation and dynamic creative optimization are converging with predictive audience modeling. Early adopters in the direct-to-consumer segment are compressing campaign production cycles from weeks to days.
- Regulatory Tailwind from Health Canada:Updated guidance on direct-to-consumer pharmaceutical advertising is expanding permissible channels for prescription drug promotion. Specialized agencies with regulatory expertise are capturing compliance-heavy assignments.
Industry Challenges
- Data Science Talent Scarcity:The shortage of machine learning engineers with marketing domain knowledge is delaying automation roadmaps at mid-sized agencies. Compensation inflation in Toronto and San Francisco is squeezing margin structures.
- Cross-Platform Measurement Fragmentation:Incompatible identity graphs across walled gardens and open web environments are complicating unified attribution. Advertisers demand consolidated reporting that technical infrastructure cannot yet deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Advertising Market |
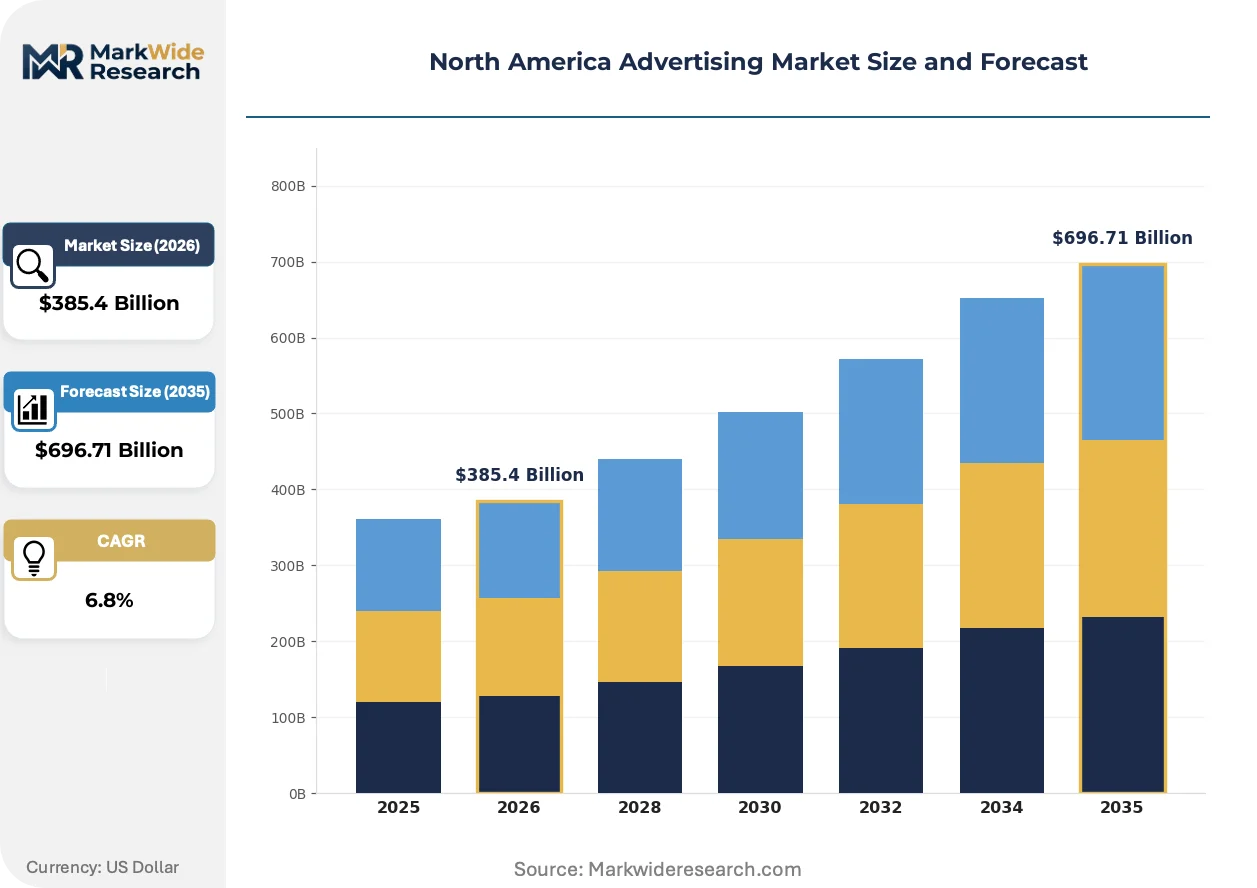
| Market Size in 2026 | $385.4 Billion |
| Market Size in 2035 | $696.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medium: Digital, Print, Television, Radio Client Type: Retailers, Corporations, Non-Profits, Startups Service Type: Creative Services, Media Buying, Analytics, SEO Industry Vertical: Technology, Healthcare, Travel, Finance |
| Companies Covered | Interpublic Group, Havas Group, WPP, BBDO, Ogilvy, Omnicom Group, Dentsu Group, TBWA\Chiat\Day, Publicis Groupe, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Advertising Market Strategic Shifts & Innovations
Artificial intelligence is rewriting production economics across creative and media functions, compressing timelines while raising new questions about intellectual property ownership and disclosure transparency.
Generative AI tools for image, video, and copy production are displacing traditional studio-based creative workflows. Mid-market advertisers in the consumer packaged goods vertical are adopting these platforms for rapid variant testing. The technology is displacing junior creative roles and flattening agency staffing pyramids.
The US Federal Trade Commission's endorsement disclosure requirements are tightening enforcement against undisclosed influencer relationships. Brands must now maintain auditable records of material connections across nano-influencer networks. The policy shift most affects beauty and wellness advertisers operating through dispersed creator ecosystems in California and Texas.
Advertiser procurement teams are consolidating agency rosters and demanding outcome-based compensation structures. Retainer-plus-performance fee models are replacing pure commission arrangements in the technology and telecommunications verticals. This transition is most advanced among Fortune 500 advertisers headquartered in New York and Seattle.
North America Advertising Market Segmentation
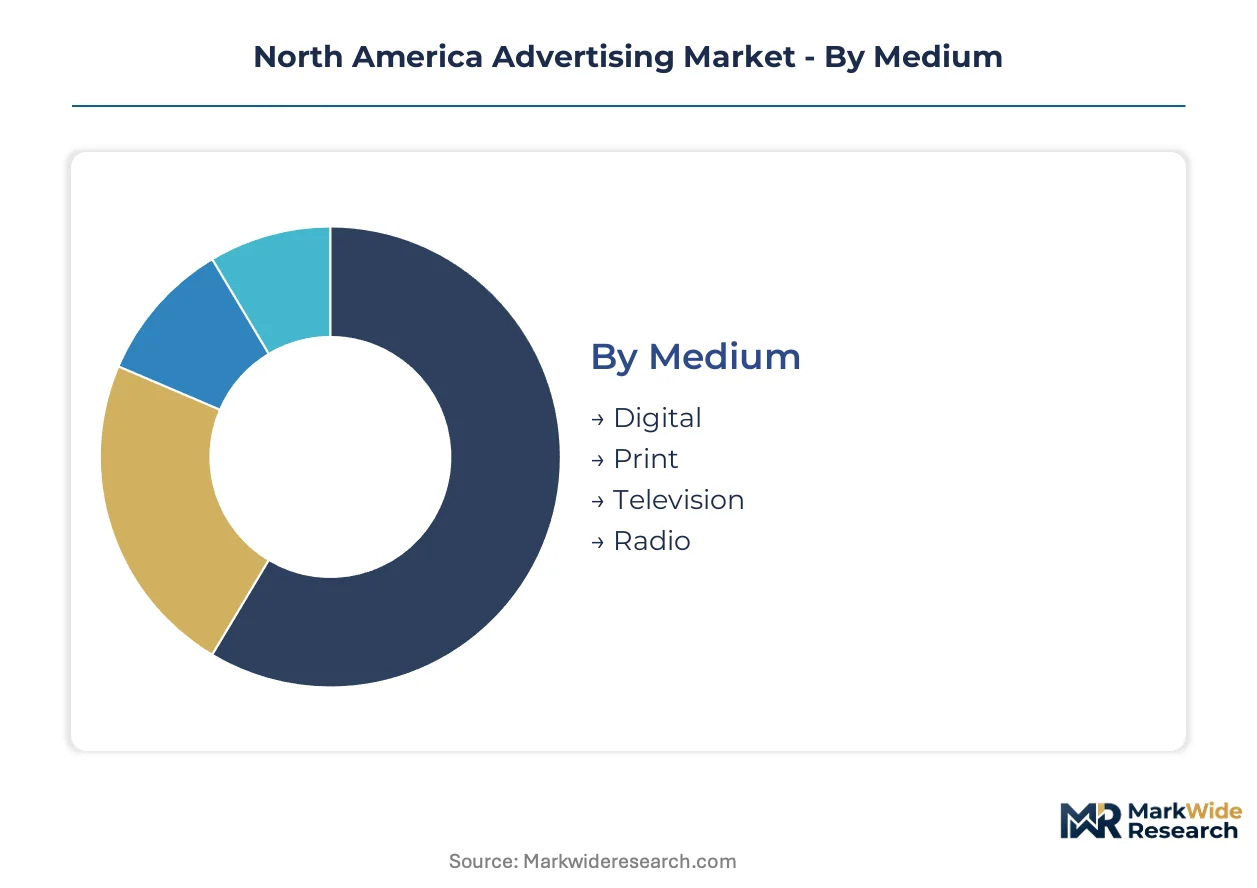
Segmentation in the North America Advertising Market reveals how budget allocation and service procurement patterns diverge across legacy and emerging channels. Advertisers in California's tech corridor and New York's media hub are driving structural shifts that reshape competitive positioning within each category.
Medium:
Digital formats face the strongest substitution pressure as connected television and retail media networks erode traditional broadcast and print allocations.
- Digital:Programmatic display, search, and social formats now operate through real-time attribution windows and cross-device identity graphs. Demand concentrates among direct-to-consumer brands in Los Angeles and San Francisco that prioritize closed-loop measurement over reach-based planning.
- Television:Linear broadcast maintains residual value for demographic-based brand building, though cord-cutting acceleration in US and Canadian households is compressing addressable inventory. Replacement CTV slots remain fragmented across incompatible technology stacks.
- Radio:Terrestrial and satellite audio formats retain local advertising utility for automotive and retail clients targeting commute-based audiences.
- Print:Magazine and newspaper placements have contracted to niche B2B applications and luxury brand supplements with aging subscriber bases.
Television anchors the volume base while Digital gains share at the steepest rate.
Client Type:
Procurement sophistication varies sharply across client scale, with enterprise advertisers demanding outcome-based compensation structures that mid-market players cannot replicate.
- Corporations:Fortune 500 advertisers headquartered in New York and Seattle are consolidating agency rosters and mandating retainer-plus-performance fee models. Procurement teams enforce unified reporting standards across global brand portfolios.
- Retailers:Grocery and big-box chains are expanding programmatic ad budgets while building proprietary retail media networks. Walmart, Target, and Loblaw operate closed-loop attribution systems that external brands access for purchase-level outcome measurement.
- Startups:Venture-backed direct-to-consumer brands compress campaign production cycles through generative AI tools for rapid variant testing.
- Non-Profits:Cause-driven organizations rely on donated media inventory and pro-bono creative services with limited measurement infrastructure.
Corporations dominate absolute spend while Retailers are expanding most quickly into in-house agency capabilities.
Service Type:
Margin compression in mature capabilities is forcing holding companies to automate planning workflows and retrain creative talent for data-centric optimization.
- Media Buying:Traditional commission-based purchasing has matured into a low-margin pool as programmatic platforms displace manual negotiation. Upfront television negotiations in New York remain a defended stronghold for agencies with proprietary planning platforms.
- Analytics:Predictive audience modeling and cross-platform attribution represent the fastest-expanding capability layer where differentiation depends on proprietary data partnerships. Machine learning engineers with marketing domain knowledge command compensation premiums in Toronto and San Francisco.
- Creative Services:Copy, visual production, and campaign concept development face displacement from generative AI tools that flatten agency staffing pyramids.
- SEO:Organic search optimization operates as a technical specialty with limited integration into full-funnel media planning.
Media Buying anchors the volume base while Analytics climbs the fastest as advertisers demand consolidated reporting.
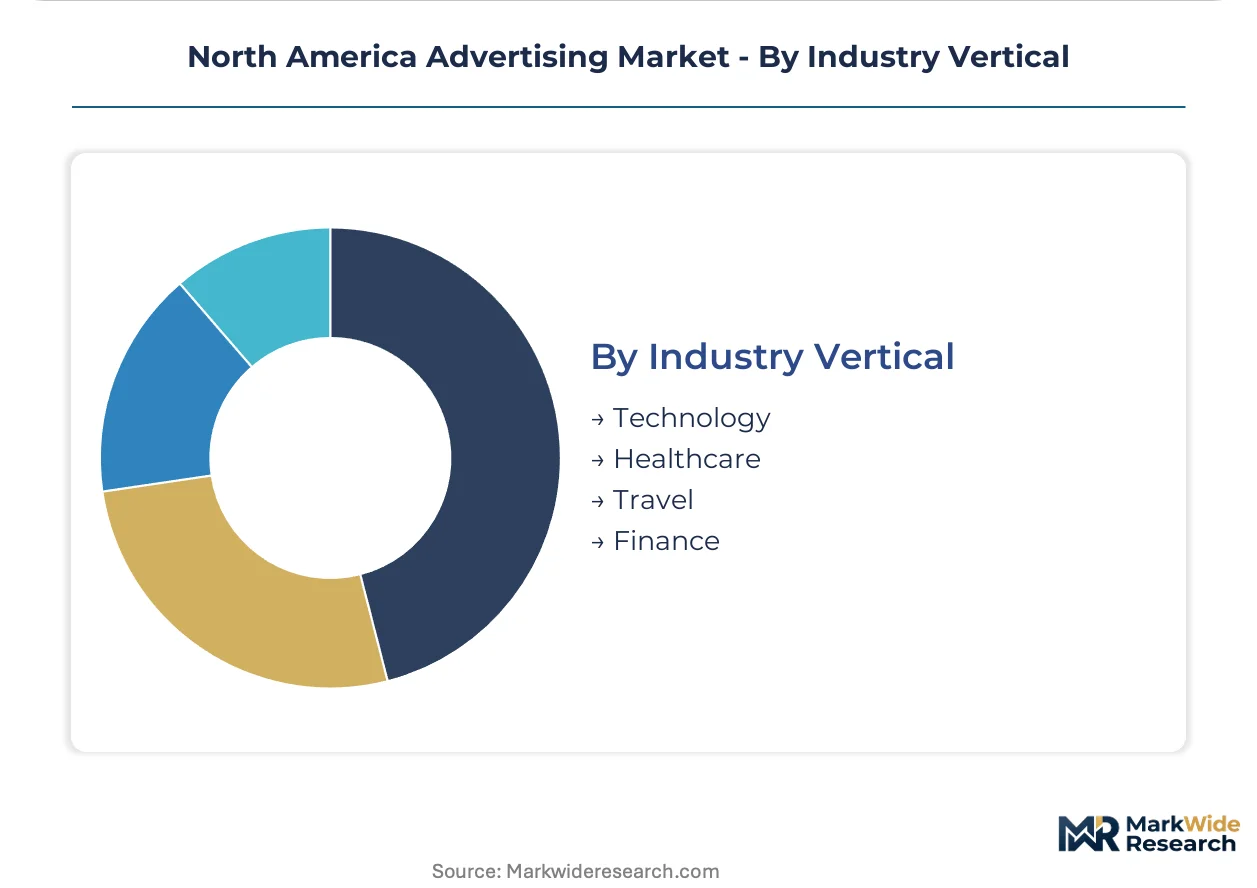
Industry Vertical:
Regulatory stringency creates specialized compliance verticals that reshape how agencies structure client contracts and staff account teams.
- Healthcare:Pharmaceutical advertisers face promotional restrictions from the FDA and Health Canada that mandate specialized legal review pipelines. Updated guidance on direct-to-consumer advertising is expanding permissible channels for prescription drug promotion.
- Finance:Banks, insurers, and investment firms require embedded compliance review for risk-averse messaging under FTC truth-in-advertising standards.
- Technology:Software and telecommunications advertisers lead adoption of outcome-based compensation structures and AI-driven creative generation.
- Travel:Airlines, hotels, and booking platforms concentrate seasonal demand spikes that stress-test media planning agility.
Healthcare anchors the volume base while Technology is expanding most quickly into automated production workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's advertisers allocate disproportionately to linear television compared with US peers, while Mexican brands concentrate spending on mobile-first digital formats. This consumption-mix differential reflects infrastructure maturity and platform penetration gaps across the three North American economies.
United States
Fortune 500 procurement teams in New York and Seattle demand outcome-based compensation structures and consolidated agency rosters. The FTC enforces updated native advertising disclosure guidelines that mandate auditable influencer relationship records. Los Angeles and San Francisco host direct-to-consumer brands prioritizing closed-loop measurement over reach-based planning.
Canada
Health Canada guidance on direct-to-consumer pharmaceutical advertising is expanding permissible prescription drug promotion channels. The Competition Bureau and Advertising Standards Canada jointly govern comparative claims and influencer transparency requirements. Toronto anchors creative-technical hybrid teams where data-science talent scarcity drives compensation inflation.
Mexico
Mobile-first advertisers concentrate spending on social platforms as smartphone penetration outpaces desktop infrastructure. The Federal Consumer Protection Agency enforces truth-in-advertising standards adapted from US FTC frameworks. Mexico City Metro hosts regional headquarters for multinational brands coordinating Latin American campaign localization.
North America Advertising Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with holding companies commanding upfront television negotiations while boutique shops capture compliance-heavy verticals. The structure stratifies across global networks with proprietary planning platforms, mid-sized independents with sector specialization, and AI-native challengers compressing production cycles. Dominant competitive moves include M&A consolidation to secure data partnerships and automation investments to offset talent scarcity.
Within the integrated holding company tier, WPP and Omnicom Group occupy positions defined by global scale and proprietary technology infrastructure. Publicis Groupe anchors the European-origin competitive vector with substantial North American operational presence. Interpublic Group exemplifies the mid-tier network archetype balancing creative heritage with programmatic capability investments.
| Leading Market Players |
|---|
| Interpublic Group |
| Havas Group |
| WPP |
| BBDO |
| Ogilvy |
| Omnicom Group |
| Dentsu Group |
| TBWA\Chiat\Day |
| Publicis Groupe |
| Others |
Cost & Logistics Intelligence
Platform-scale data infrastructure in Los Angeles and New York compresses production costs for campaigns while concentrating bargaining power among Meta and Alphabet properties that command premium inventory rates. This scale dynamic elevates price floors for mid-sized agencies lacking proprietary audience graphs and forces consolidation among independent media buyers competing for remnant digital slots.
Pricing Analysis
Long-term retainer contracts with Fortune 500 advertisers in New York and Seattle anchor pricing stability for holding companies, while spot-market programmatic buying exposes smaller agencies to volatile CPM swings. Price differentiation rests on proprietary data partnerships and compliance-integrated creative services that pharmaceutical and financial advertisers pay premiums for. Cost compression in traditional media buying is intensifying because automated planning platforms displace manual negotiation. Mid-market direct-to-consumer brands show highest price sensitivity, whereas risk-averse healthcare advertisers demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Creative talent pipelines through Toronto and Chicago anchor service delivery for North American campaigns, while technical infrastructure concentrates in California's cloud computing corridor and Virginia's data center clusters. Raw material inputs draw from machine learning engineering labor markets, third-party identity graph licensing, and streaming platform inventory access. Single-source vulnerability runs through Meta and Alphabet's dominance of digital ad inventory. Distribution runs through holding company networks, independent programmatic exchanges, and direct publisher relationships with retail media networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected television interoperability standards and retail media network expansion are creating platform-economics inflection points where closed-loop attribution capabilities determine competitive survival.
For Market Incumbents: Shield proprietary data partnerships from platform concentration risk by deepening first-party infrastructure investments and embedding legal review pipelines into production workflows. Vertical integration into retail media network operations captures closed-loop measurement capabilities that traditional publishers cannot replicate. The threat of generative AI displacement of junior creative roles demands accelerated retraining of hybrid creative-technical teams. For New Entrants and Emerging Players: Differentiate on compliance-heavy vertical specialization where regulatory expertise creates defendable moats against automated platforms. Healthcare and pharmaceutical advertising in Canada and the United States presents the most penetrable segment given Health Canada and FDA guidance expansion. A go-to-market angle anchored in auditable influencer relationship management captures FTC enforcement tailwinds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among agencies with embedded regulatory compliance services and proprietary planning platforms that lock in Fortune 500 retainers. Long-term viability favors targets with demonstrated capability in cross-platform attribution and AI-augmented creative production. The signal to watch is consolidation velocity among mid-sized independents unable to fund automation roadmaps against talent scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Retail Media Network Partnership | First-party shopper data from Walmart and Target enables closed-loop attribution that commands premium pricing from CPG advertisers. |
| AI Creative Generation Platform | Generative tools compress production cycles from weeks to days for direct-to-consumer brands in Los Angeles and San Francisco. |
| Regulatory Compliance Vertical | FDA and Health Canada expertise captures pharmaceutical assignments requiring specialized legal review pipelines. |
| CTV Inventory Integration | Addressable streaming slots merge broadcast reach with digital targeting precision for upfront television negotiations. |
| Cross-Platform Attribution System | Unified reporting across walled gardens satisfies Fortune 500 procurement demands in New York and Seattle. |
Research Approach
A spread of perspectives from media planning directors, programmatic trading desk heads, brand procurement officers, and regulatory compliance leads converged on the working assumptions that shape this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of publicly traded holding companies, FTC enforcement action databases, and streaming platform ad revenue disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the North American advertising ecosystem.
Segmentation dimensions modeled include medium format, client type, service capability, and industry vertical across the projection horizon. CAGRs were derived from trend extrapolation of budget allocation shifts and platform penetration curves. Forecast inputs incorporated cord-cutting velocity in US and Canadian households, state privacy legislation fragmentation, and retail media network inventory expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained CTV inventory growth and stable regulatory enforcement patterns would require recalibration. Practitioners should keep alternative scenarios live as platform concentration dynamics and state-level privacy legislation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
United States Public Relation Services Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
Malaysia OOH and DOOH Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
Programmatic Advertising Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Marketing Resource Management Market